
 Asia-Pacific Juices Market | 2026-2036
Asia-Pacific Juices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Juices Market Insights
Convenience store distribution is fragmenting across Southeast Asia as local chains and petrol-station formats multiply. Nongfu Spring Co. leverages its mineral water logistics backbone to secure shelf dominance in China's tier-two cities. Kagome Co Ltd anchors premium vegetable juice positioning through controlled greenhouse sourcing in Japan. Thai Beverages PCL competes on price-aggressive tropical fruit blends distributed through its domestic beer and spirits retail network.
Asia-Pacific juices encompass non-alcoholic beverages extracted from fruits, vegetables, or blended formulations, typically processed through cold-press, centrifugal, or thermal pasteurization methods with residual solids content determining nectar versus juice classification. These products serve refreshment, nutritional supplementation, and meal-replacement functions across retail and foodservice channels. Fruit Juice leads volume but faces margin compression from commodity orange and apple concentrate pricing; Blended Juice commands premium positioning where vegetable and superfruit combinations justify higher unit economics. Tetra Packs dominate rural penetration due to ambient stability and lower logistics cost, while bottles concentrate in urban supermarkets where visual branding drives impulse purchase.
Japan's FOSHU framework and China's SAMR nutrition labeling standards shape permissible health claims and sugar disclosure thresholds, directly influencing reformulation investment and packaging redesign cycles. India's FSSAI enforcement of fruit content minimums for nectar products restricts dilution practices and elevates input costs for value-tier producers. Stakeholders must monitor evolving ASEAN harmonization talks on cross-border juice standards, as divergent national rules fragment procurement and labeling compliance across the region.
Market Dynamics
China's SAMR sugar disclosure mandates are forcing reformulation investments across the Asia-Pacific, compressing margins for concentrate-dependent producers while elevating cold-pressed alternatives.
Growth Catalysts
- FOSHU Framework:Japan's functional food standards enable clinically validated health claims on vegetable juices, rewarding R&D investment with premium shelf positioning.
- Urban Foodservice Expansion:Southeast Asian restaurants and cafés are diversifying beverage menus, creating dedicated juice bar formats that absorb higher wholesale prices.
- Cold-Press Technology:High-pressure processing equipment is extending ambient shelf life without thermal degradation, unlocking convenience store distribution for perishable blends.
Market Restraints
- Orange Concentrate Volatility:Brazilian frost cycles and Florida citrus greening disease transmit price shocks through commodity input contracts.
- Single-Origin Supply Risk:Philippine pineapple and Thai mango processing concentrates expose buyers to typhoon-related crop failures and port closures.
- FSSAI Fruit Content Floors:India's nectar minimums eliminate dilution strategies for value-tier entrants, raising working capital requirements for pulp procurement.
Strategic Opportunities
- ASEAN Harmonization:Pending cross-border standard convergence would reduce multi-country label redesign costs and enable centralized production.
- Petrol-Station Retail:Thailand and Indonesia's fuel retail networks are adding refrigerated juice SKUs to capture commuter traffic outside traditional grocery hours.
- Dual Carbon Alignment:China's MEE emissions targets favor domestic producers with renewable-powered processing facilities and shorter distribution radii.
Industry Challenges
- Refrigerated Last-Mile Infrastructure:Cold-chain gaps in India's tier-three cities limit cold-pressed product reach and inflate spoilage rates.
- Health Claim Substantiation:Clinical trial costs for FOSHU or SAMR functional approvals strain mid-tier R&D budgets and extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Juices Market |
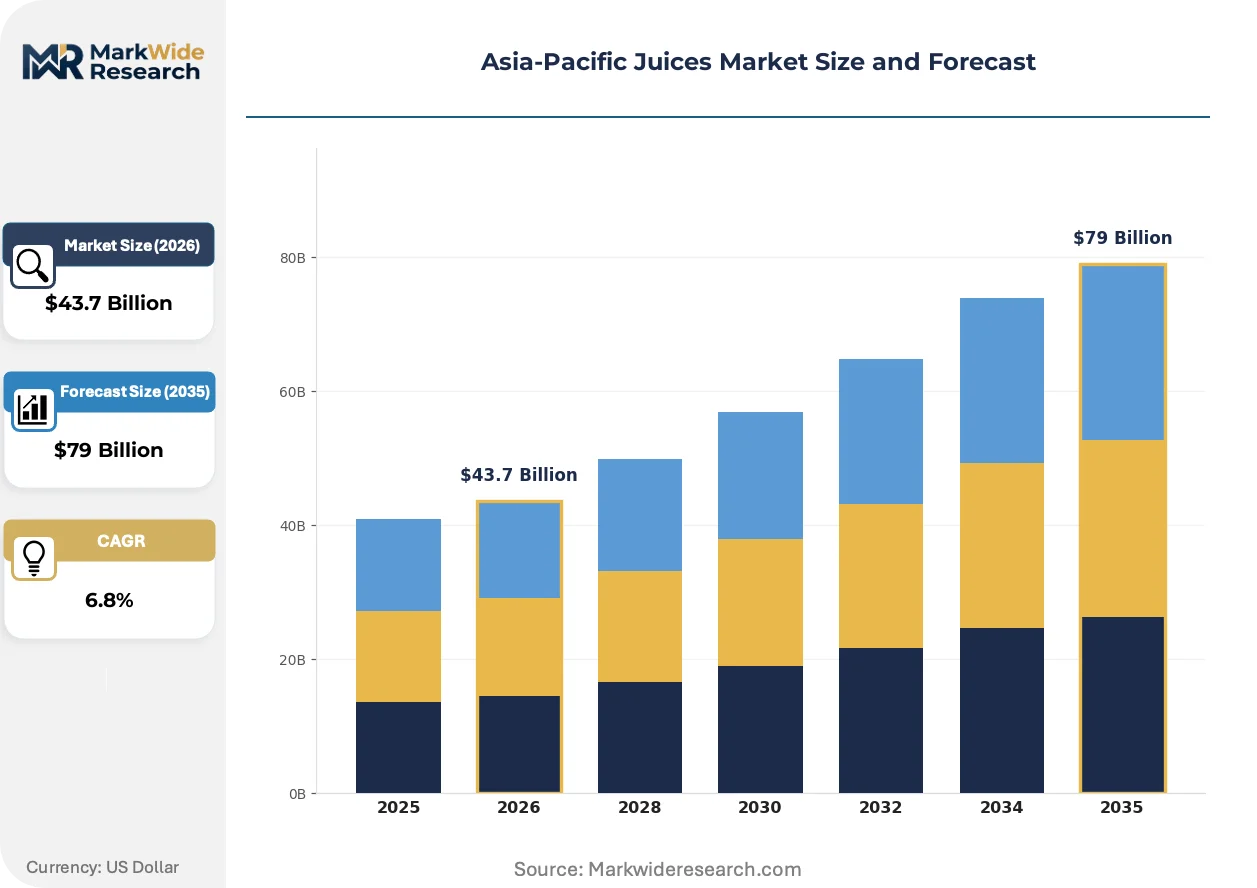
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Juice, Vegetable Juice, Blended Juice, Carbonated Juice Packaging Type: Bottles, Cartons, Tetra Packs, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Food Service End User: Households, Restaurants, Cafés, Catering Services |
| Companies Covered | Beijing Huiyuan Food and Beverage Co., Kagome Co Ltd, Nongfu Spring Co., Uni-President Enterprises Corp., PepsiCo, Inc., Suntory Holdings Limited, Tingyi (Cayman Islands) Holding Corporation, Thai Beverages PCL, The Coca-Cola Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Juices Market Trends and Innovations
Digital traceability systems and processing automation are compressing quality assurance cycles while enabling personalized nutrition positioning across Asia-Pacific retail channels.
High-pressure processing is virtualizing thermal pasteurization in premium juice manufacturing. Japanese and Australian cold-pressed producers are adopting HPP units at scale to preserve enzyme activity and vitamin retention. This shift is virtualizing the traditional tradeoff between shelf stability and nutritional integrity, allowing ambient distribution of products previously confined to refrigerated cases.
China's SAMR tightened additive disclosure rules now mandate front-of-pack sugar content warnings on all juice products exceeding specified thresholds. Manufacturers are responding with stevia and monk fruit reformulations, though taste-profile matching extends development timelines. Premium vegetable-forward blends face lower compliance burdens and are capturing shelf space from legacy fruit nectar SKUs.
Direct-to-subscription models are displacing supermarket bulk purchasing among health-conscious urban households in Seoul, Singapore, and Mumbai. Cold-pressed brands are bundling personalized wellness programs with recurring deliveries, extracting higher lifetime value per account. This channel migration is most pronounced among dual-income professionals seeking meal-replacement convenience without retail friction.
Asia-Pacific Juices Market Segmentation
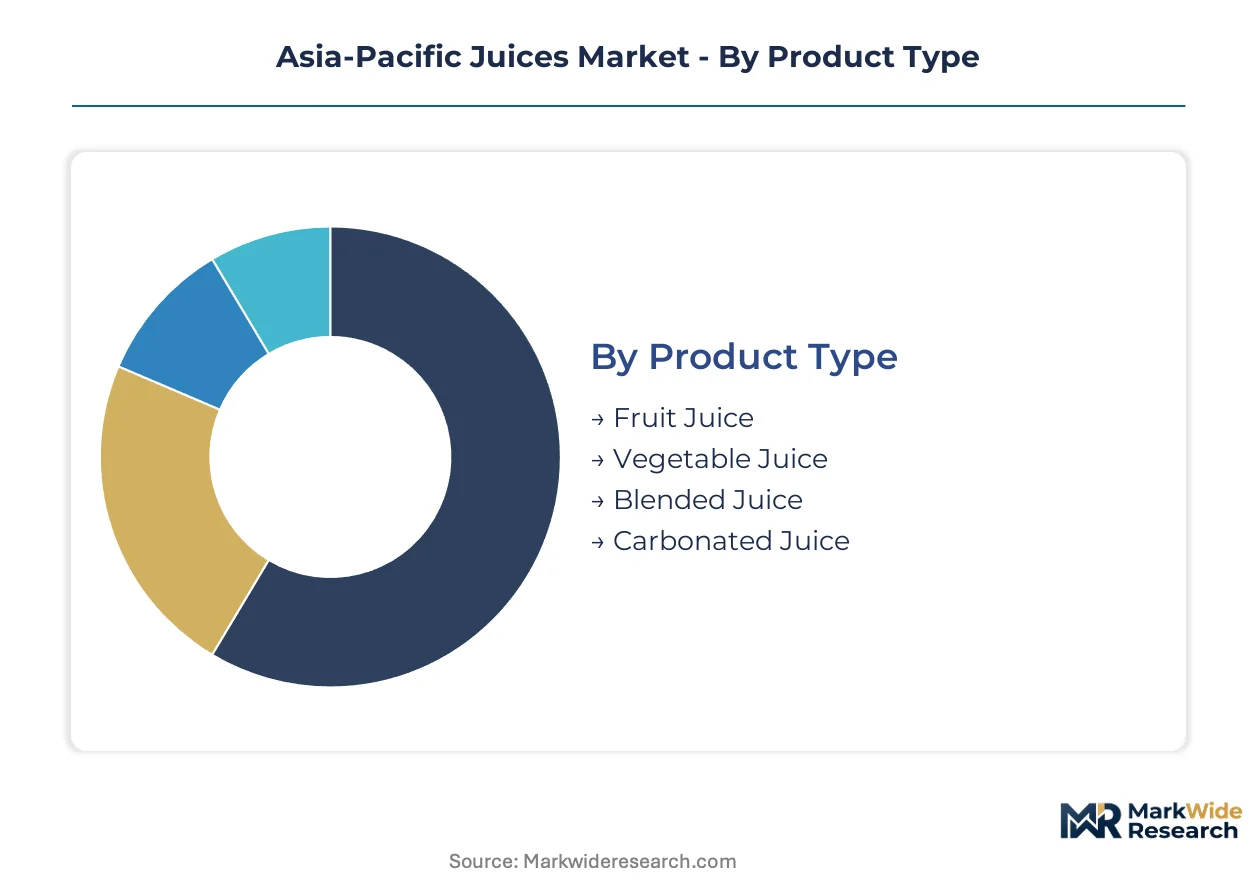
Asia-Pacific juice producers navigate four intersecting segmentation dimensions that determine margin capture and channel access. Product formulation drives regulatory compliance burden and health claim eligibility. Packaging and distribution choices reflect cold-chain maturity and urban retail density variations across the region.
Product Type:
Mature categories dominate volume, while emerging formats command premium positioning through functional differentiation.
- Fruit Juice:Orange, apple, and tropical variants constitute the volume foundation, processed through centrifugal or thermal pasteurization methods. Demand concentrates in China's tier-two cities and India's metropolitan centers where price-sensitive households prioritize refreshment over nutritional density. SAMR sugar disclosure mandates are compressing margins for concentrate-dependent producers.
- Blended Juice:Vegetable-superfruit combinations deliver higher per-unit economics through FOSHU-eligible health claims in Japan and premium positioning elsewhere. Seoul, Singapore, and Mumbai households absorb subscription-priced cold-pressed variants. High-pressure processing equipment extends ambient shelf life without thermal degradation.
- Vegetable Juice:Tomato and carrot bases anchor functional positioning, with Kagome's controlled greenhouse sourcing setting quality benchmarks.
- Carbonated Juice:Sparkling formulations target younger demographics in Thailand and Indonesia through convenience store impulse placement.
Fruit Juice retains volume leadership; Blended Juice holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium visual branding from logistics-optimized ambient distribution.
- Tetra Packs:Aseptic carton technology enables rural penetration across India and Southeast Asia without refrigerated transport. Lower unit logistics costs and ambient stability favor value-tier fruit nectar distribution. Tetra Pak dominates procurement for producers targeting tier-three Indian cities where cold-chain gaps persist.
- Bottles:PET and glass formats concentrate in urban supermarkets where shelf visibility drives impulse purchase. China's tier-one cities and Japan's convenience stores absorb premium vegetable juice SKUs in transparent packaging. Visual branding justifies 30-50% price premiums over carton equivalents.
- Cartons:Gable-top refrigerated formats serve fresh-squeezed positioning in Australian and South Korean retail.
- Cans:Aluminum formats capture petrol-station and vending machine channels in Thailand and Indonesia.
Tetra Packs dominate rural volume; Bottles capture urban value concentration.
Distribution Channel:
Customer type determines channel priority, with household procurement fragmenting across format-specific retail networks.
- Supermarkets:Large-format retail concentrates assortment breadth in urban centers, absorbing premium and standard-tier juice SKUs. Visual merchandising and chilled display cases drive impulse conversion for bottled vegetable blends. China's Hema Fresh and Japan's AEON anchor category management investments.
- Convenience Stores:7-Eleven, FamilyMart, and local chains multiply across Southeast Asia, extending juice access beyond traditional grocery hours. Refrigerated SKU expansion in Thailand and Indonesia captures commuter traffic. Petrol-station retail networks add dedicated chilled juice sections.
- Online Retailers:Direct-to-subscription models displace bulk purchasing among health-conscious dual-income professionals.
- Food Service:Restaurants and cafés diversify beverage menus with dedicated juice bar formats.
Supermarkets retain assortment leadership; Convenience Stores are gaining share fastest.
End User:
Application context separates refreshment occasions from meal-replacement and hospitality service requirements.
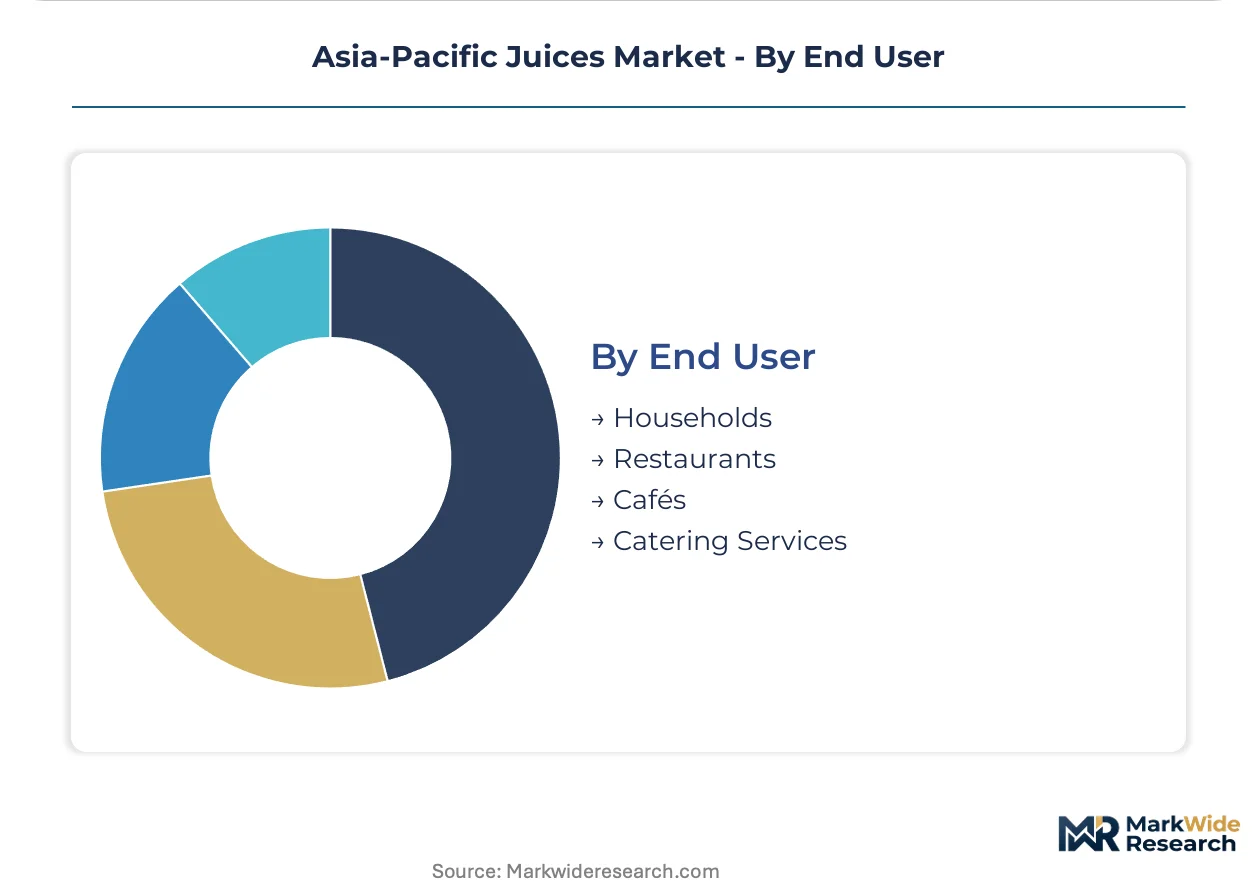
- Households:Urban families drive volume through retail procurement, with cold-pressed subscription penetration highest in Seoul, Singapore, and Mumbai. Health-conscious dual-income professionals prioritize personalized wellness bundling over price minimization. FSSAI fruit content floors elevate input costs for value-tier nectar purchases.
- Restaurants:Southeast Asian dining establishments expand juice menu offerings, absorbing higher wholesale prices for premium blends. Dedicated juice bar formats capture beverage occasion extension.
- Cafés:Specialty coffee chains in Japan and Australia integrate vegetable-forward juices into all-day menu positioning.
- Catering Services:Event and institutional foodservice procures ambient-stable formats for volume reliability.
Households retain consumption leadership; Restaurants hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's sugar disclosure mandates in China are cascading through procurement and labeling practices across the Asia-Pacific, forcing producers in neighboring markets to anticipate regulatory convergence.
China
Tier-two cities absorb volume-tier fruit nectar through mineral water logistics networks, while tier-one supermarkets drive premium vegetable juice conversion. SAMR's front-of-pack sugar warnings compress margins for concentrate-dependent producers and elevate cold-pressed alternatives. Yangtze River Delta processing clusters are retrofitting high-pressure processing lines to serve export-ready functional blends.
Japan
FOSHU-eligible vegetable juices command premium shelf positioning through clinically validated health claims. Tokyo and Osaka convenience stores anchor single-serve chilled distribution for enzyme-active formulations. METI-backed processing automation grants are accelerating HPP adoption in Kanto and Kansai manufacturing corridors.
India
FSSAI fruit content minimums for nectar products restrict dilution strategies and elevate working capital requirements for pulp procurement. Mumbai, Delhi-NCR, and Bengaluru households drive cold-pressed subscription penetration among dual-income professionals. Maharashtra and Karnataka processing hubs are consolidating to capture economies of scale under tighter input standards.
Thailand
Petrol-station retail networks are expanding refrigerated SKU counts to capture commuter traffic outside traditional grocery hours. Domestic beer and spirits distribution infrastructure absorbs price-aggressive tropical fruit blends. Bangkok-based beverage conglomerates are leveraging existing route-to-market density for juice category entry.
Australia
Gable-top refrigerated formats serve fresh-squeezed positioning in Sydney and Melbourne supermarkets. High-pressure processing adoption is most advanced here, with producers supplying enzyme-stable exports to Southeast Asian markets. Victoria and New South Wales manufacturing clusters are integrating digital traceability systems to compress quality assurance cycles.
Asia-Pacific Juices Market Competitive Landscape
Beverage conglomerates and specialized juice operators split the market along channel and price-tier lines. Consolidation pressures concentrate among mid-tier producers caught between commodity fruit nectar compression and premium functional positioning requirements. Three archetypes dominate: diversified beverage holdings with cross-category route-to-market density, mineral water specialists leveraging logistics backbones for juice distribution, and controlled-source vegetable processors with greenhouse quality benchmarks. Competitive moves center on cold-chain infrastructure partnerships and high-pressure processing capacity expansion.
Within the controlled-source tier, Kagome Co Ltd exemplifies greenhouse-anchored quality positioning. Nongfu Spring Co. occupies a position bridging mineral water logistics density with juice shelf dominance in China's tier-two cities. Thai Beverages PCL represents route-to-market leverage through domestic beer and spirits retail network absorption.
| Leading Market Players |
|---|
| Beijing Huiyuan Food and Beverage Co. |
| Kagome Co Ltd |
| Nongfu Spring Co. |
| Uni-President Enterprises Corp. |
| PepsiCo, Inc. |
| Suntory Holdings Limited |
| Tingyi (Cayman Islands) Holding Corporation |
| Thai Beverages PCL |
| The Coca-Cola Company |
| Others |
Pricing and Supply Chain Analysis
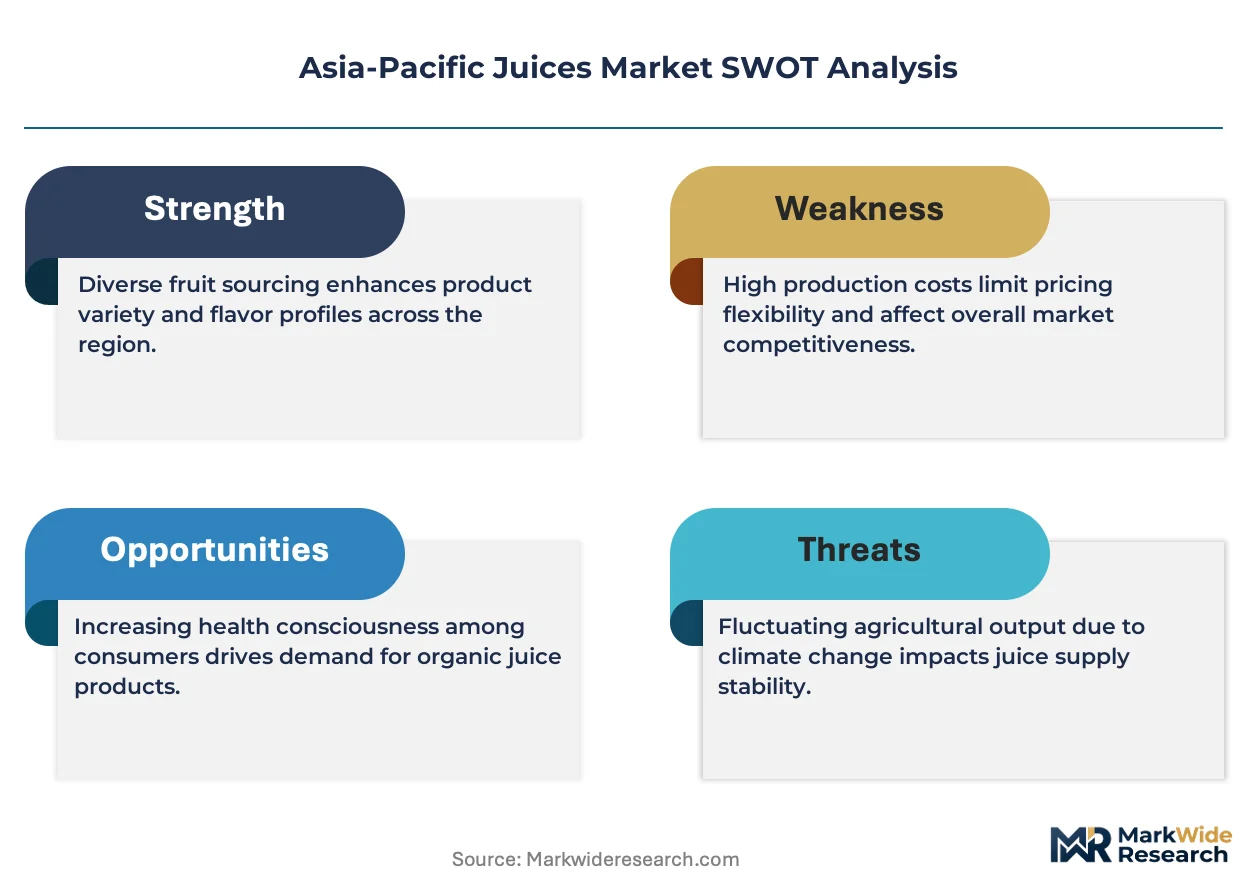
The Shanghai-Singapore maritime corridor's freight cost volatility compresses margins for concentrate-dependent producers while amplifying price differentiation between cold-pressed premium tiers and ambient-stable value SKUs across Southeast Asian distribution networks.
Pricing Analysis
The customization-premium spread between subscription-configured cold-pressed blends and standard Tetra Pack nectars reaches three-to-one multiples in Mumbai and Seoul urban markets. Three-tier pricing structure across premium, standard, and economy levels reflects FOSHU certification status, high-pressure processing investment, and vegetable content ratios. Cost compression in commodity fruit nectar tiers is intensifying because Brazilian orange concentrate contracts transmit frost-cycle volatility. Households in India's tier-three cities exhibit highest price sensitivity, while dual-income professionals in Singapore absorb subscription premiums without volume elasticity.
Supply Chain Analysis
Contract-manufacturing concentration among Yangtze River Delta beverage processors and Maharashtra pulp consolidation facilities shapes procurement leverage for brand owners. Geographic supply concentrates in China, India, and Thailand for tropical fruit pulp extraction and aseptic filling capacity. Raw material dependencies center on Brazilian orange concentrate, Philippine pineapple puree, and domestic carrot pulp from Shandong and Punjab growing regions. Single-origin exposure to typhoon-disrupted Philippine pineapple harvests creates vulnerability for tropical blend formulations. Distribution runs through mineral water logistics networks in China's tier-two cities and petrol-station retail chains across Thailand and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as health-conscious urban households abandon supermarket bulk purchasing for personalized subscription models, creating niche entry points beyond incumbent route-to-market density.
For Market Incumbents: Pre-empt cold-pressed subscription encroachment by retrofitting high-pressure processing lines in Yangtze River Delta and Kanto manufacturing corridors. Acquire controlled-source vegetable suppliers with greenhouse traceability to defend against Kagome-quality benchmarks. Lock in exclusive chilled distribution partnerships with 7-Eleven and FamilyMart Southeast Asian networks before regional harmonization enables competitor label standardization.
For New Entrants and Emerging Players: Build out direct-to-subscription capabilities targeting dual-income professionals in Mumbai, Seoul, and Singapore with personalized wellness bundling. India's tier-three cities offer the most penetrable geography given persistent cold-chain gaps that incumbents have not addressed. Lead with petrol-station retail partnerships in Thailand and Indonesia to capture commuter traffic outside traditional grocery hours.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage holdings seeking to divest non-core juice operations amid SAMR sugar disclosure compliance costs. Long-term viability favors controlled-source vegetable processors with greenhouse quality benchmarks and HPP-equipped facilities serving export-ready functional blends. Watch ASEAN harmonization progress as inflection signal for centralized production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | Enables FOSHU-eligible health claims through enzyme preservation in Kanto corridor facilities. |
| Controlled-Source Greenhouse Integration | Secures quality benchmarks against Kagome through captive tomato and carrot supply. |
| Petrol-Station Retail Network Penetration | Captures Thailand and Indonesia commuter traffic outside traditional grocery hours. |
| Direct-to-Subscription Platform Launch | Extracts lifetime value from Mumbai and Seoul dual-income professionals seeking meal replacement. |
| SAMR Compliance Reformulation | Mandates stevia and monk fruit substitution to avoid front-of-pack sugar warnings in China. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with juice brand managers, cold-chain logistics directors, F&B procurement leads at Southeast Asian restaurant chains, and regulatory affairs specialists navigating SAMR and FSSAI frameworks. Secondary validation drew from customs records, Nielsen retail audit data, ASEAN harmonization documentation, and METI processing automation grant disclosures. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Calibration anchored historical consumption patterns to projected urbanization rates and health claim eligibility expansion across the analysis window. Segmentation dimensions modeled include product formulation tier, packaging technology, distribution channel density, and end-use occasion. CAGRs were derived from trend extrapolation of cold-pressed adoption curves and FOSHU approval velocities. Forecast inputs incorporated HPP equipment deployment timelines and ASEAN regulatory convergence scenarios.
Practitioners should monitor Brazilian frost cycles, Philippine typhoon severity, and SAMR enforcement intensity for early signals of input cost shocks or compliance burden shifts. Quarterly review of FOSHU approval backlogs, petrol-station SKU expansion rates, and subscription platform customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Plant Based Beverages Market
Beverages
Water Bottle Market
Beverages
Global Electrolyte Drinks Market
Beverages
Packaged Natural Mineral Water Market
Beverages
GCC Bottled Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
US Bubble Tea Market
Beverages
Nitro-Infused Cola Market
Beverages
Rose Floral Water Market
Beverages
Solid Beverages Market
Beverages
United Kingdom Energy Drink Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Reconstituted Juice Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
North America Fruit Juice Market