
 Hospitality Real Estate Sector Market | 2026-2036
Hospitality Real Estate Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Hospitality Real Estate Sector Market Analysis
The EU Green Deal is expanding energy efficiency mandates across European hospitality portfolios, compelling owners to retrofit aging stock or face obsolescence. Marriott International leverages its global scale to embed sustainability protocols across managed and franchised properties. Hilton Worldwide Holdings anchors its development pipeline in LEED-certified construction standards. Host Hotels & Resorts, Inc. differentiates through concentrated ownership of premium urban and resort assets with above-average RevPAR profiles.
The hospitality real estate sector encompasses income-producing properties purpose-built for temporary lodging, food service, and guest amenities, typically structured as commercial mortgage-backed securities or REIT-held assets with weighted average lease terms under one year. Hotels and resorts command the largest share of institutional capital deployment due to their liquidity and established yield benchmarks, while serviced apartments represent the fastest-growing property type as extended-stay demand from corporate relocations and remote workers reshapes booking patterns. Full-service properties retain dominant position in gateway cities where ancillary revenue from food and beverage operations supports debt service coverage ratios.
EMA building performance standards, EPA Energy Star certification requirements, and BIS green building codes collectively shape capital allocation toward compliant assets and away from stranded inventory. The EU AI Act introduces emerging compliance obligations for automated guest service and pricing systems deployed across European properties. Stakeholders must monitor regulatory divergence between jurisdictions as sustainability mandates tighten and digital governance frameworks mature.
Market Dynamics
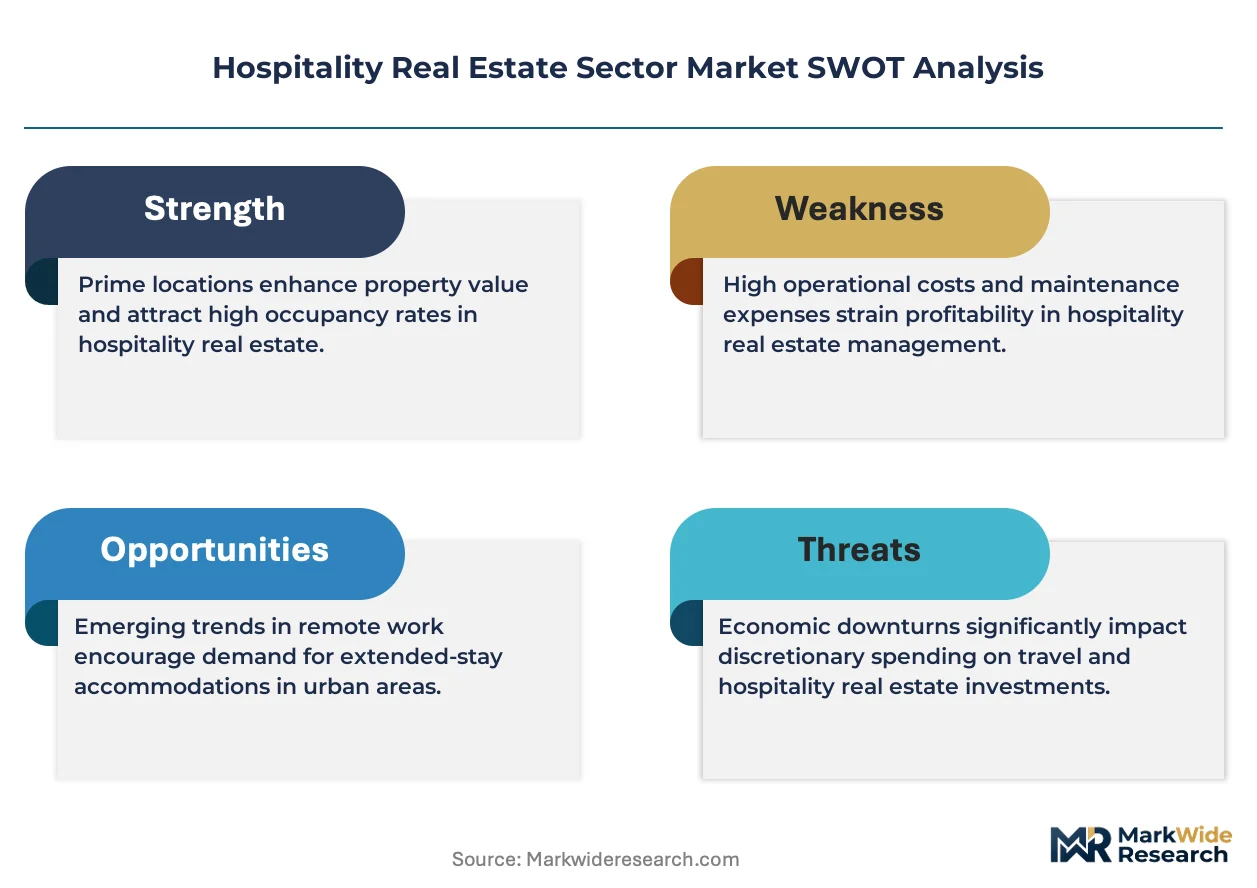
Institutional capital is rotating toward hospitality assets that satisfy ESG underwriting criteria, compressing financing spreads for LEED-certified properties while penalizing vintage stock with stranded-asset risk. The EU Green Deal's building performance standards now function as a capital-allocation filter across European portfolios.
Growth Catalysts
- Extended-stay corporate demand:Remote work permanence has restructured business travel into longer-duration stays, elevating serviced apartments above traditional hotels in yield-per-key metrics.
- EMA building retrofit mandates:The EU Green Deal's energy efficiency directives are compelling asset owners to upgrade insulation and HVAC systems, creating construction demand and future-proofing valuations.
- Spain's Mediterranean leisure cluster:Costa del Sol and Balearic Islands concentration is drawing concentrated institutional deployment as post-pandemic leisure travel normalizes.
Market Restraints
- Construction input cost volatility:Steel and concrete price swings are compressing development margins for ground-up resort projects, particularly in remote island locations with logistics constraints.
- European energy code fragmentation:Divergent national implementations of EU Green Deal standards are creating compliance complexity for cross-border portfolio operators.
- Alternative lodging platforms:Short-term rental aggregators are fragmenting demand capture and compressing pricing power in leisure-heavy submarkets.
Strategic Opportunities
- Adaptive reuse of office stock:Underutilized urban commercial buildings in Germany and France present conversion candidates for boutique hospitality formats with lower embodied carbon than new construction.
- CSRD-aligned disclosure premiums:The EU's Corporate Sustainability Reporting Directive is creating valuation spreads for assets with verified environmental performance data.
- AI-driven revenue management convergence:Machine learning pricing algorithms combined with IoT occupancy sensors are enabling dynamic rate optimization previously unavailable to mid-scale operators.
Industry Challenges
- Green building certification timelines:LEED and BREEAM documentation requirements are extending pre-opening schedules by six to twelve months, tying up capital longer.
- Legacy PMS integration friction:Property management system upgrades to cloud-native architectures are disrupting operational continuity during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospitality Real Estate Sector Market |
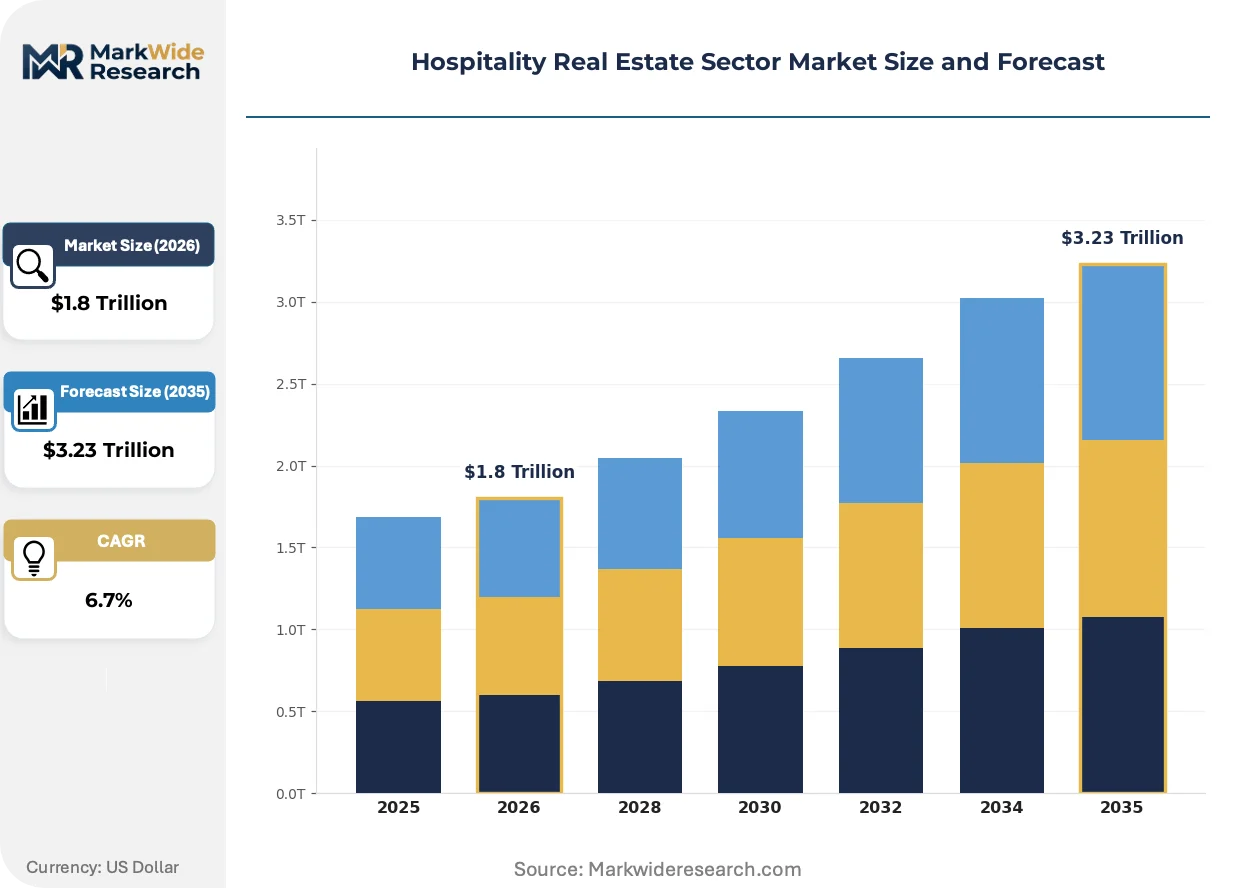
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.23 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Resorts, Motels, Serviced Apartments Investment Strategy: Acquisition, Development, Renovation, Asset Management Customer Type: Leisure Travelers, Business Travelers, Conference Attendees, Tour Groups Service Type: Full-Service, Boutique, Budget, Luxury |
| Companies Covered | Hines, Choice Hotels International, Host Hotels & Resorts, Inc., Apple Hospitality REIT, Inc., Ryman Hospitality Properties, Inc., Marriott International, InterContinental Hotels Group, Tishman Speyer, Hilton Worldwide Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospitality Real Estate Sector Market Emerging Trajectories
Digital infrastructure is rewiring how hospitality assets generate and capture value, compressing the gap between operational data and capital markets pricing. Three distinct vectors are restructuring competitive positioning.
Smart building operating systems are rewriting how mechanical, electrical, and plumbing infrastructure responds to occupancy patterns. Institutional owners with scale are deploying integrated IoT platforms across portfolios. This convergence is enabling predictive maintenance contracts that transfer equipment risk from operators to OEMs.
REACH chemical restrictions and F-Gas Regulation phase-downs are mandating refrigerant transitions in European hotel HVAC retrofits. Asset managers must now sequence equipment replacement to avoid stranded mechanical systems. Mediterranean resort properties face accelerated timelines due to cooling-load intensity.
Corporate travel procurement has consolidated around total-trip-cost metrics rather than nightly rate minimization. Extended-stay products with kitchen facilities and co-working infrastructure are displacing traditional full-service bookings in technology and consulting verticals. Germany's corporate travel market exhibits this behavioral shift most acutely.
Hospitality Real Estate Sector Market Segmentation
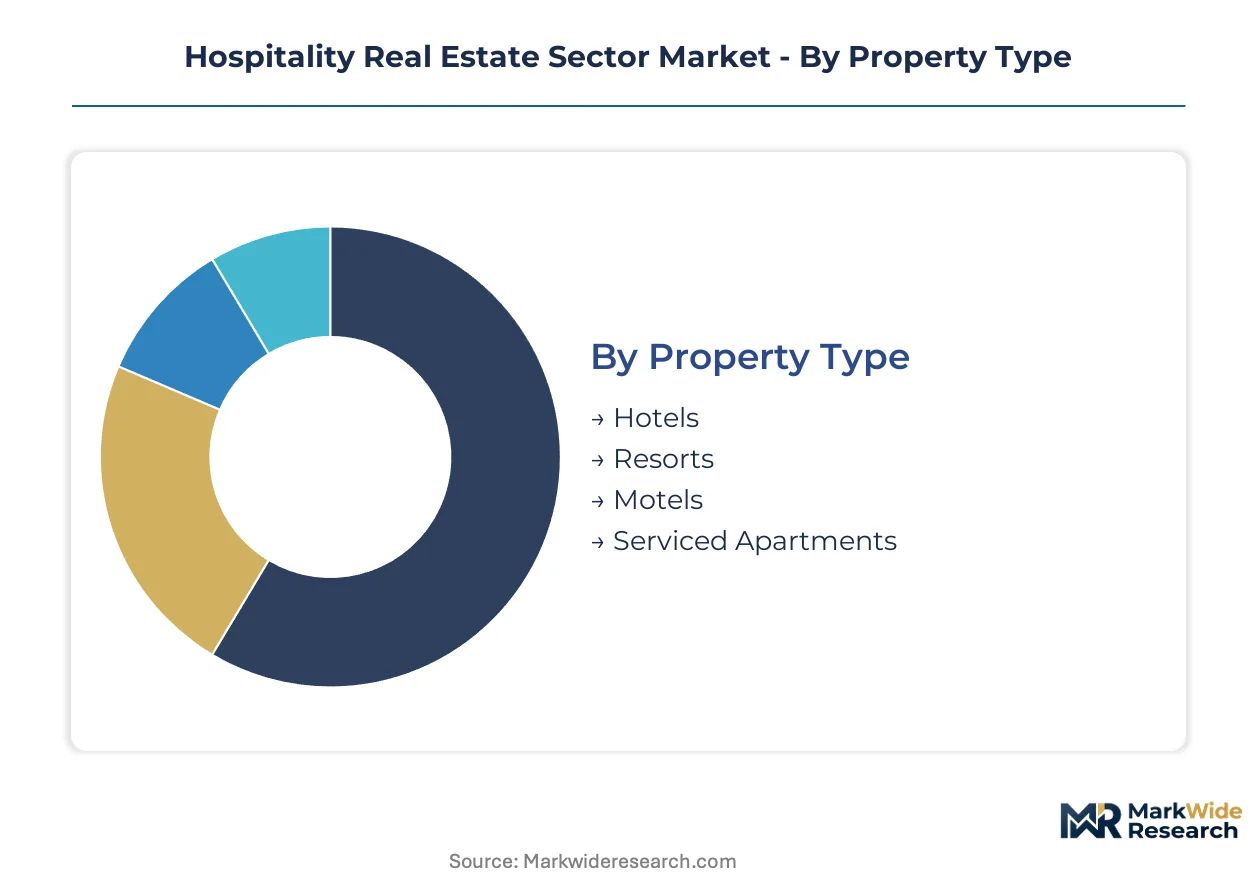
Segmentation in hospitality real estate reveals how capital allocation, operational complexity, and yield profiles vary across property configurations. Each dimension carries distinct financing structures, tenant dynamics, and regulatory exposure that shape portfolio construction decisions.
Property Type:
Standalone hospitality assets operate independently with dedicated management infrastructure, while embedded properties integrate into mixed-use developments with shared amenities and centralized services.
- Hotels:Purpose-built lodging facilities with centralized food and beverage operations, meeting spaces, and 24-hour staffing models. Institutional capital concentrates in gateway cities like London, Paris, and Dubai where RevPAR benchmarks support leveraged acquisition structures. EU Green Deal retrofit mandates are compressing financing spreads for vintage urban stock.
- Resorts:Destination properties with extensive land holdings, recreational amenities, and seasonal demand patterns. Mediterranean clusters in Spain's Costa del Sol and Balearic Islands are drawing concentrated deployment as post-pandemic leisure travel normalizes. Cooling-load intensity accelerates HVAC replacement timelines under F-Gas Regulation phase-downs.
- Motels:Drive-up lodging formats with limited service infrastructure and exterior corridor access patterns. Highway-adjacent locations in the US Sun Belt and Australian coastal corridors sustain operational relevance through lower labor intensity.
- Serviced Apartments:Extended-stay formats combining residential-scale units with hospitality services and flexible lease terms. Corporate relocation demand and remote work permanence are elevating yield-per-key metrics above traditional hotel benchmarks in Germany and Singapore.
Hotels lead volumes today; serviced apartments are gaining share fastest.
Investment Strategy:
Capital deployment mode determines risk-return profiles, with ground-up development commanding construction risk premiums and stabilized acquisitions trading on in-place yield.
- Acquisition:Purchase of income-producing assets with established operational histories and documented cash flow trajectories. Cross-border capital from Middle Eastern sovereign vehicles and Asian insurance platforms targets trophy assets in London, New York, and Tokyo.
- Development:Ground-up construction of new hospitality supply with extended capital commitment periods and entitlement risk exposure. Remote island resort projects face steel and concrete price volatility compounded by logistics constraints.
- Renovation:Capital-intensive repositioning of existing stock to capture rate premiums or comply with evolving building codes. EU Green Deal energy efficiency directives are compelling systematic HVAC and envelope upgrades across European portfolios.
- Asset Management:Operational oversight and value-add interventions without direct property ownership, typically through management contracts or franchise arrangements. Fee structures align operator incentives with owner returns through incentive management agreements.
Acquisition dominates transaction volume; renovation is expanding most quickly as retrofit mandates tighten.
Customer Type:
Demand composition shapes revenue management complexity, with homogeneous segments enabling standardized pricing and heterogeneous mixes requiring dynamic segmentation.
- Leisure Travelers:Individual and family bookings with price-sensitive demand patterns and high channel-commission exposure. Mediterranean leisure clusters exhibit concentrated recovery trajectories.
- Business Travelers:Corporate-account bookings with negotiated rate structures and loyalty program concentration. Germany's corporate travel market exhibits pronounced behavioral shift toward extended-stay products with co-working infrastructure.
- Conference Attendees:Group demand tied to meeting space utilization and ancillary food and beverage capture. Gateway city full-service properties retain dominant positioning where event infrastructure supports debt service coverage.
- Tour Groups:Block-booked demand through operator intermediaries with compressed margins and high cancellation exposure. Seasonal concentration in cultural destination markets creates occupancy volatility.
Leisure travelers anchor current occupancy; business traveler recovery is climbing the fastest.
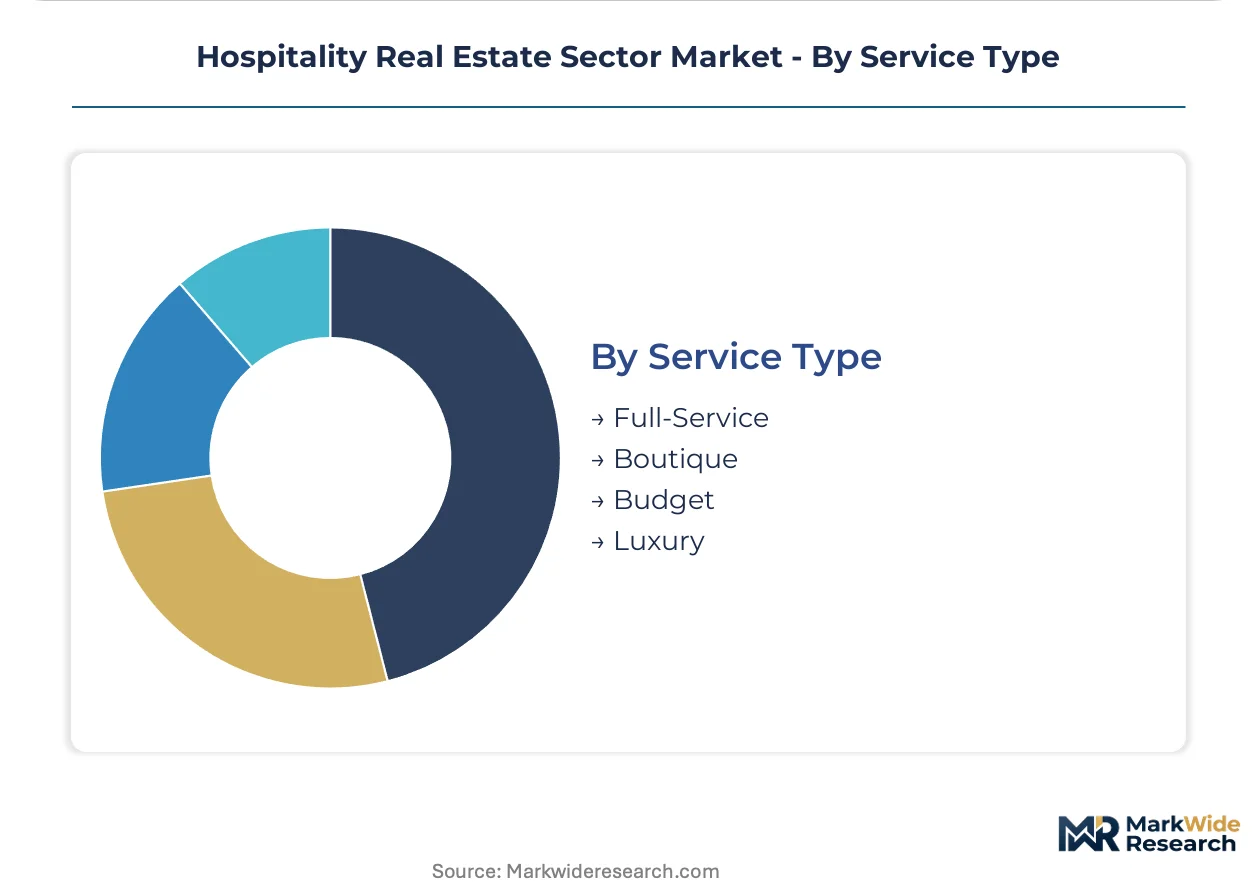
Service Type:
Service intensity tiers separate capital requirements, staffing models, and competitive positioning strategies across the hospitality spectrum.
- Full-Service:Properties with extensive food and beverage operations, meeting facilities, and concierge infrastructure. Retain dominant positioning in gateway cities where ancillary revenue supports leverage capacity.
- Boutique:Design-forward limited-service formats with localized positioning and experiential differentiation. Lifestyle properties are attracting heightened institutional capital as brand aggregators scale collection platforms.
- Budget:Limited-service formats with stripped amenity sets and standardized room products. Price competition from short-term rental aggregators is fragmenting demand capture in leisure-heavy submarkets.
- Luxury:Ultra-premium positioning with personalized service ratios, signature dining, and spa wellness infrastructure. Trophy assets in Paris, Milan, and Miami command scarcity premiums in institutional allocation models.
Full-service properties retain volume leadership; boutique formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled asset management professionals concentrate in gateway cities with established institutional investment infrastructure, creating regional competitive advantages that attract cross-border capital deployment.
United States
Corporate extended-stay demand and Sun Belt population migration drive new development in Texas and Florida. EPA Energy Star certification requirements filter capital toward compliant assets. Nashville and Austin hospitality clusters absorb record institutional deployment as technology sector relocations reshape business travel patterns.
Germany
Corporate travel procurement consolidation and adaptive reuse of underutilized office stock reshape supply fundamentals. EU Green Deal building performance standards mandate systematic HVAC and envelope upgrades. Frankfurt and Munich urban cores concentrate renovation activity as owners future-proof vintage properties against obsolescence risk.
Spain
Mediterranean leisure travel normalization and cooling-load intensity accelerate resort investment timelines. F-Gas Regulation phase-downs compel refrigerant transitions in hospitality HVAC systems. Costa del Sol and Balearic Islands institutional deployment concentrates as post-pandemic booking patterns stabilize.
United Kingdom
Boutique format expansion and lifestyle brand aggregation attract specialized capital vehicles. CSRD-aligned disclosure requirements create valuation spreads for verified environmental performance data. London trophy asset trading sustains liquidity premiums while regional cities capture adaptive reuse conversion activity.
Japan
Inbound tourism recovery and extended-stay corporate demand from technology sector relocations reshape yield profiles. METI building energy efficiency standards tighten operational compliance requirements. Tokyo and Osaka gateway properties retain institutional preference as yield benchmarks for cross-border allocation models.
Hospitality Real Estate Sector Market Vendor Landscape
Capital-heavy asset owners compete with asset-light brand licensors for value capture in hospitality real estate. The market structure concentrates around integrated platform operators with scale advantages in procurement and technology deployment. Three strategic archetypes dominate: global brand aggregators with franchise and management contract networks, concentrated REITs with premium urban and resort portfolios, and diversified real estate investors with cross-sector allocation flexibility. Competitive dynamics center on portfolio diversification into experiential formats and strategic partnerships for technology-enabled operational efficiency.
Within the brand-aggregator archetype, Marriott International and Hilton Worldwide Holdings occupy positions defined by global scale and embedded sustainability protocols. Host Hotels & Resorts, Inc. exemplifies the concentrated REIT model with ownership-focused strategies targeting above-average RevPAR profiles. These entities represent distinct capital deployment philosophies rather than direct operational competition, with each archetype capturing value through differentiated risk-return positioning across the hospitality asset spectrum.
| Leading Market Players |
|---|
| Hines |
| Choice Hotels International |
| Host Hotels & Resorts, Inc. |
| Apple Hospitality REIT, Inc. |
| Ryman Hospitality Properties, Inc. |
| Marriott International |
| InterContinental Hotels Group |
| Tishman Speyer |
| Hilton Worldwide Holdings |
| Others |
Supply Flow & Price Mechanics
LEED-BREEAM certification bifurcation separates hospitality assets into premium and commodity tiers, with certified properties commanding financing spread compression while vintage stock faces stranded-asset penalties. This divergence manifests in capital allocation filters that reward compliant supply chain configurations and punish legacy mechanical systems nearing obsolescence under EU Green Deal timelines.
Pricing Analysis
Bundled service contracts with predictive maintenance clauses now dominate institutional-grade hospitality assets, while unbundled fee-for-service arrangements persist in limited-service and budget tiers. Price differentiation hinges on ESG certification tier and geographic cooling-load intensity, with Mediterranean resort properties facing accelerated HVAC replacement costs under F-Gas Regulation phase-downs. Cost compression in vintage urban stock intensifies as EU Green Deal retrofit mandates tighten operational compliance windows. Corporate extended-stay segments exhibit lowest price sensitivity due to total-trip-cost procurement metrics, while leisure travelers through online travel agencies show highest elasticity.
Supply Chain Analysis
Regional distribution centers for hospitality FF&E and mechanical equipment concentrate in Germany, Italy, and China, with hub-and-spoke patterns serving Mediterranean resort clusters and gateway city renovation projects. Raw material dependencies center on steel, concrete, and refrigerant-grade copper tubing. Single-source vulnerability runs through Chinese-manufactured IoT sensor platforms and HVAC compressor assemblies. Distribution runs through specialized hospitality procurement consortia and brand-aggregator centralized purchasing programs that leverage global scale for equipment standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality real estate has entered a late-cycle quality phase where institutional capital rewards LEED-certified assets with premium valuations. Extended-stay corporate demand from remote work permanence tilts allocation toward serviced apartments with kitchen facilities and co-working infrastructure.
For Market Incumbents: Extend sustainability protocol embedding across franchised and managed portfolios to preempt EU Green Deal compliance gaps. Consolidate adaptive reuse expertise for office-to-hotel conversions in Germany and France. Vertical integration into IoT-enabled building operating systems transfers equipment risk from operators to OEMs and locks in recurring revenue streams. For New Entrants and Emerging Players: Enter via boutique lifestyle formats in Spain's Costa del Sol and Balearic Islands where institutional deployment concentrates but brand-aggregator collection platforms remain underpenetrated. Target corporate extended-stay segments in Frankfurt and Munich where yield-per-key metrics exceed traditional hotel benchmarks. White-label technology partnerships with revenue management platform providers accelerate operational credibility without legacy PMS migration costs. For Investors and Strategic Acquirers: Consolidation pressure builds where cross-border portfolio operators face fragmented national implementations of EU Green Deal standards. Long-term viability favors concentrated REITs with premium urban and resort exposure over diversified real estate vehicles with hospitality as a satellite allocation. Trophy assets in London, Paris, and Tokyo retain scarcity premiums as yield benchmarks for sovereign wealth deployment. Watch F-Gas Regulation enforcement intensity as an inflection signal for accelerated HVAC capital deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Reuse Conversion | Office-to-hotel repositioning in Germany and France captures lower embodied carbon than ground-up construction. |
| IoT Platform Deployment | Predictive maintenance contracts with HVAC OEMs transfer equipment risk and stabilize operating expense profiles. |
| CSRD-Aligned Disclosure | Verified environmental performance data creates valuation spreads for assets with documented compliance trajectories. |
| Extended-Stay Format Expansion | Serviced apartments with kitchen facilities and co-working infrastructure capture corporate relocation demand in Germany. |
| Refrigerant Transition Sequencing | Accelerated HVAC replacement under F-Gas Regulation phase-downs future-proofs Mediterranean resort valuations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with asset managers, brand-aggregator development executives, hospitality procurement directors, and ESG compliance officers with secondary validation. SEC REIT filings, EU building performance registries, hospitality industry association construction cost indices, and cross-border investment flow databases anchored supply-side characterization. Bottom-up property-level cash flow modeling and top-down sector allocation trend analysis triangulated market sizing.
Comparable-period anchoring linked projection assumptions to historical RevPAR trajectories, construction input cost indices, and regulatory implementation timelines across the analysis window. Segmentation dimensions modeled include property type, investment strategy, customer segment, and service intensity tier, with geographic cooling-load intensity and certification status as hospitality-specific forecast inputs. CAGRs were derived from regression-based trend extrapolation adjusted for regulatory mandate acceleration effects.
Inputs from institutional investor allocation surveys and brand-aggregator pipeline disclosures were available through the study window; gaps in proprietary management contract fee structures introduce uncertainty bands around operator-margin projections. Forecasts reflect documented assumptions about EU Green Deal implementation velocity and corporate travel behavioral persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market