
 Canada Hospitality Real Estate Market | 2026-2036
Canada Hospitality Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hospitality Real Estate Market Insights
Corporate transient demand is decoupling from traditional full-service dependency as hybrid work patterns reshape booking patterns. Brookfield Asset Management leverages its global capital platform to anchor large-scale urban hospitality portfolios. InnVest Hotels sustains dominant positioning across Canadian gateway markets through selective asset recycling. Westmont Hospitality Group specializes in extended-stay and select-service formats that compete effectively against legacy full-service properties.
Canada hospitality real estate encompasses income-producing lodging properties including hotels, motels, resorts, and hostels, typically constructed with steel-frame or reinforced concrete structures meeting seismic and energy efficiency standards, designed to generate revenue through nightly accommodation leases and ancillary services. Full-service properties command premium rate positioning but face margin compression from labor intensity, while limited-service formats capture growing investor preference for operational efficiency. Luxury and budget segments occupy opposite ends of the yield spectrum, with luxury concentrating in Toronto and Vancouver trophy assets and budget expanding along highway corridors and secondary markets.
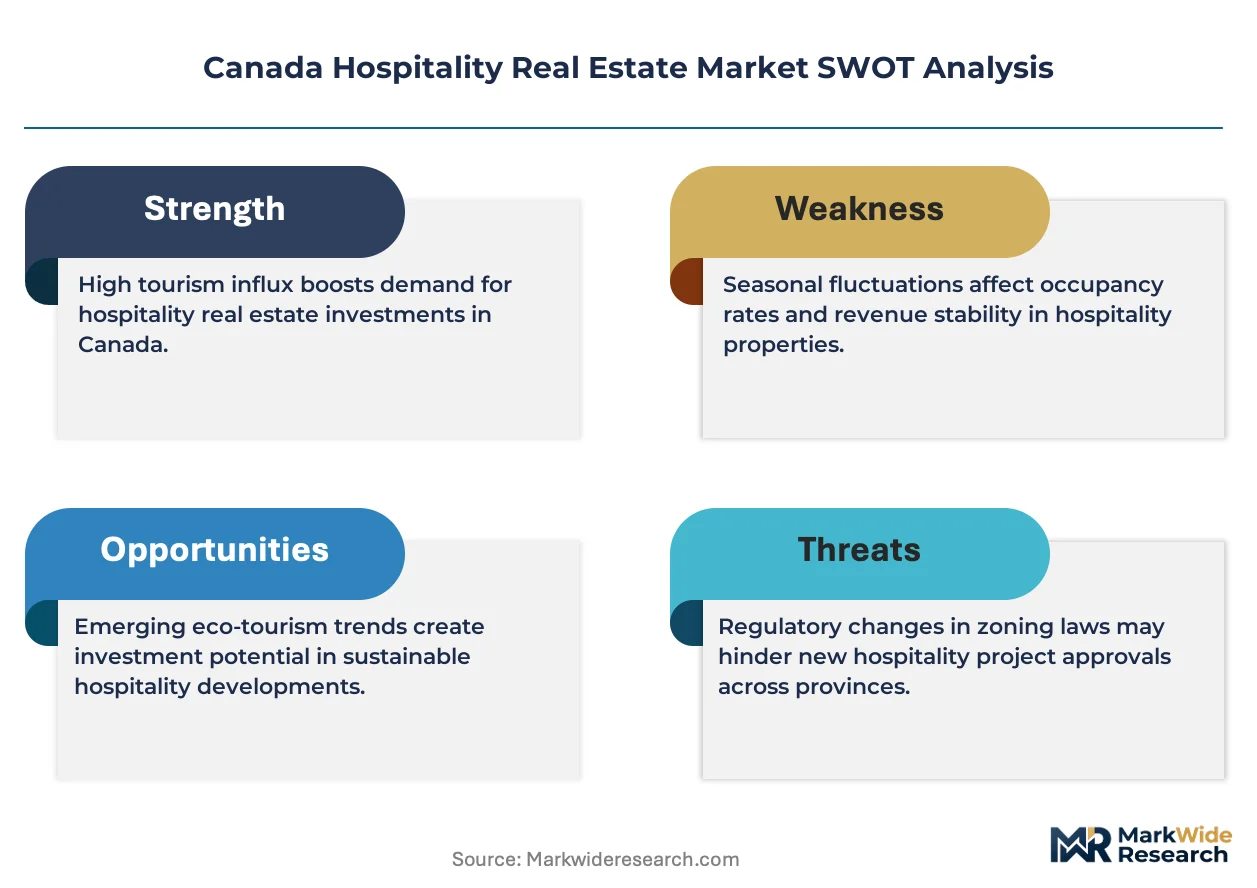
Health Canada guidelines intersect with provincial building codes to mandate accessibility, fire safety, and indoor air quality standards that shape renovation cycles and capital expenditure planning. The Canadian Mortgage and Housing Corporation financing frameworks and municipal zoning bylaws in cities like Toronto, Calgary, and Ottawa directly determine project feasibility and density allowances. Stakeholders must monitor evolving short-term rental regulations at the provincial and municipal level that threaten traditional lodging demand pools.
Market Dynamics
Hybrid work permanence is fragmenting corporate transient demand across secondary Canadian markets, forcing hospitality operators to rebalance urban trophy assets against suburban extended-stay formats. This structural decoupling compresses traditional full-service rate premiums while elevating select-service operational efficiency metrics.
Growth Catalysts
- Canada's National Building Code updates:Green certification mandates are accelerating capital deployment into energy-efficient retrofits across Ontario and British Columbia hospitality portfolios.
- Boutique hotel development:Ontario and British Columbia urban cores are seeing concentrated development of experiential lodging formats targeting leisure travelers.
- Extended-stay format preference:Corporate relocation patterns are pulling demand toward select-service properties with kitchenette configurations and weekly rate structures.
Market Restraints
- Labor cost intensity:Full-service properties face margin compression from housekeeping and F&B staffing requirements that limited-service formats avoid.
- Short-term rental substitution:Provincial and municipal regulations on platforms like Airbnb threaten traditional lodging demand pools in Toronto, Vancouver, and Montreal.
- Seismic and energy code compliance:Steel-frame and reinforced concrete construction standards elevate upfront capital requirements relative to US comparables.
Strategic Opportunities
- Secondary market underpenetration:Calgary and Ottawa hospitality assets trade at yield premiums to gateway cities with comparable demand fundamentals.
- CMHC financing leverage:Canadian Mortgage and Housing Corporation frameworks offer cost-of-capital advantages for qualifying green-certified developments.
- Ancillary revenue unbundling:Parking, co-working access, and wellness amenities present monetization white space beyond nightly accommodation leases.
Industry Challenges
- Accessibility retrofit timelines:Health Canada guidelines intersecting provincial building codes compress renovation cycle planning windows.
- Zoning density friction:Municipal bylaws in Toronto, Vancouver, and Montreal directly constrain project feasibility and unit count economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hospitality Real Estate Market |
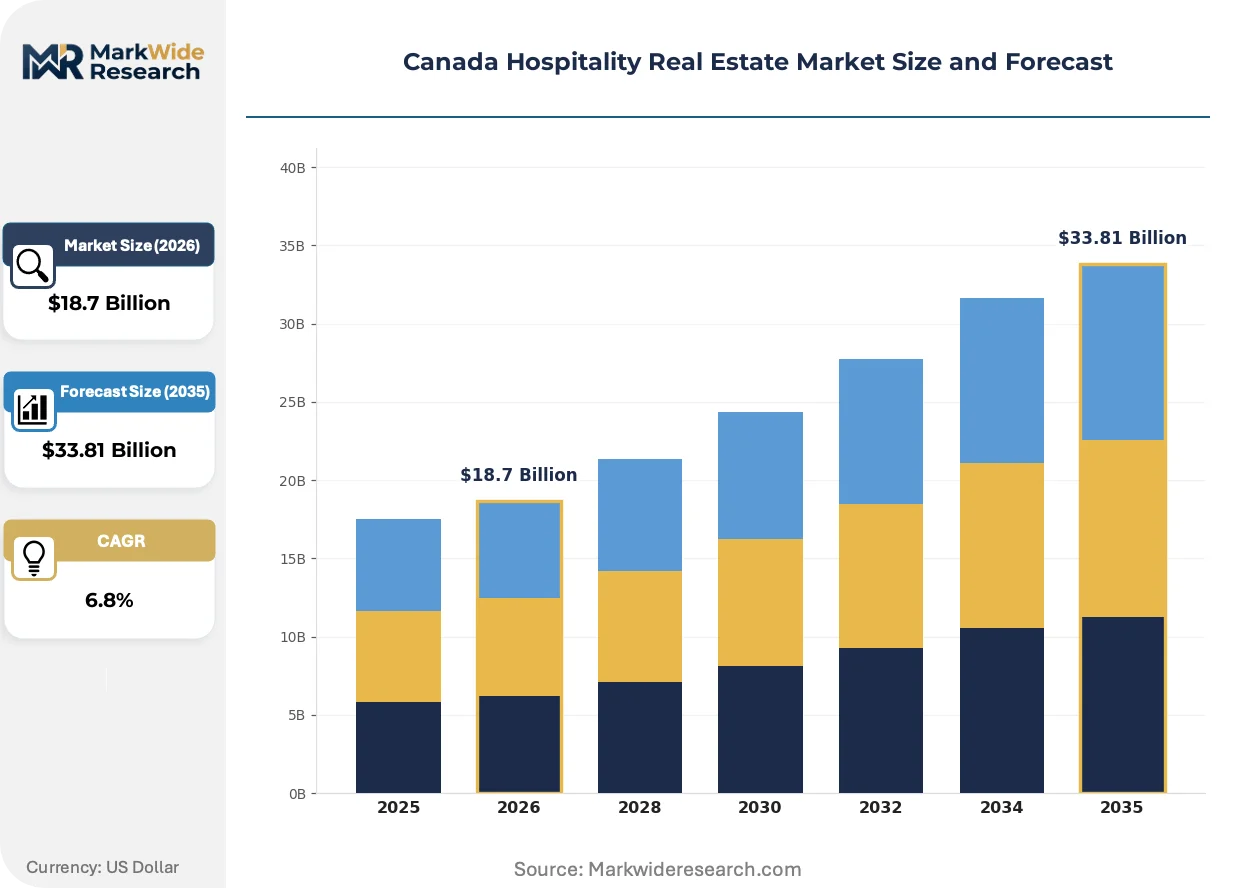
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Motels, Resorts, Hostels Service Type: Full-Service, Limited-Service, Luxury, Budget Client Type: Corporate Travelers, Leisure Guests, Group Bookings, Solo Travelers Investment Strategy: Acquisition, Development, Joint Venture, Asset Management |
| Companies Covered | Brookfield Asset Management, InnVest Hotels, Westmont Hospitality Group, Superior Lodging Corp, Coast Hotels, Fairmont Raffles Hotels International, Choice Hotels Canada Inc, IHG (InterContinental Hotel Group), Groupe Germain Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hospitality Real Estate Market Trends and Innovations
Property technology integration is redefining operational cost structures across Canadian hospitality assets. Three converging developments are compressing legacy service models while enabling new revenue architectures.
Building management system digitization is electrifying energy consumption monitoring and predictive maintenance scheduling across Canadian hotel portfolios. Mid-scale operators in Toronto and Vancouver are deploying IoT-enabled HVAC and lighting controls at accelerating pace. This infrastructure is electrifying utility cost reduction targets and compressing engineering headcount ratios without degrading guest experience quality.
Health Canada guidelines intersecting provincial fire safety and indoor air quality standards are mandating capital expenditure cycles that favor comprehensive renovation over piecemeal upgrade. The National Building Code update trajectory is forcing asset holders to front-load accessibility and environmental compliance into single-project execution. Full-service properties in Ontario and British Columbia are responding by bundling seismic retrofit with green certification pursuit to capture CMHC financing advantages.
Corporate booking behavior is fragmenting across hybrid work permanence, with group demand dispersing from single large-block commitments to multiple smaller footprints. Third-party meeting planners are displacing traditional corporate travel managers as the primary booking channel for mid-sized events. This pattern is most visible in Montreal and Calgary, where suburban select-service properties are capturing displaced urban full-service volume through flexible space configurations and technology-enabled hybrid event support.
Canada Hospitality Real Estate Market Segmentation
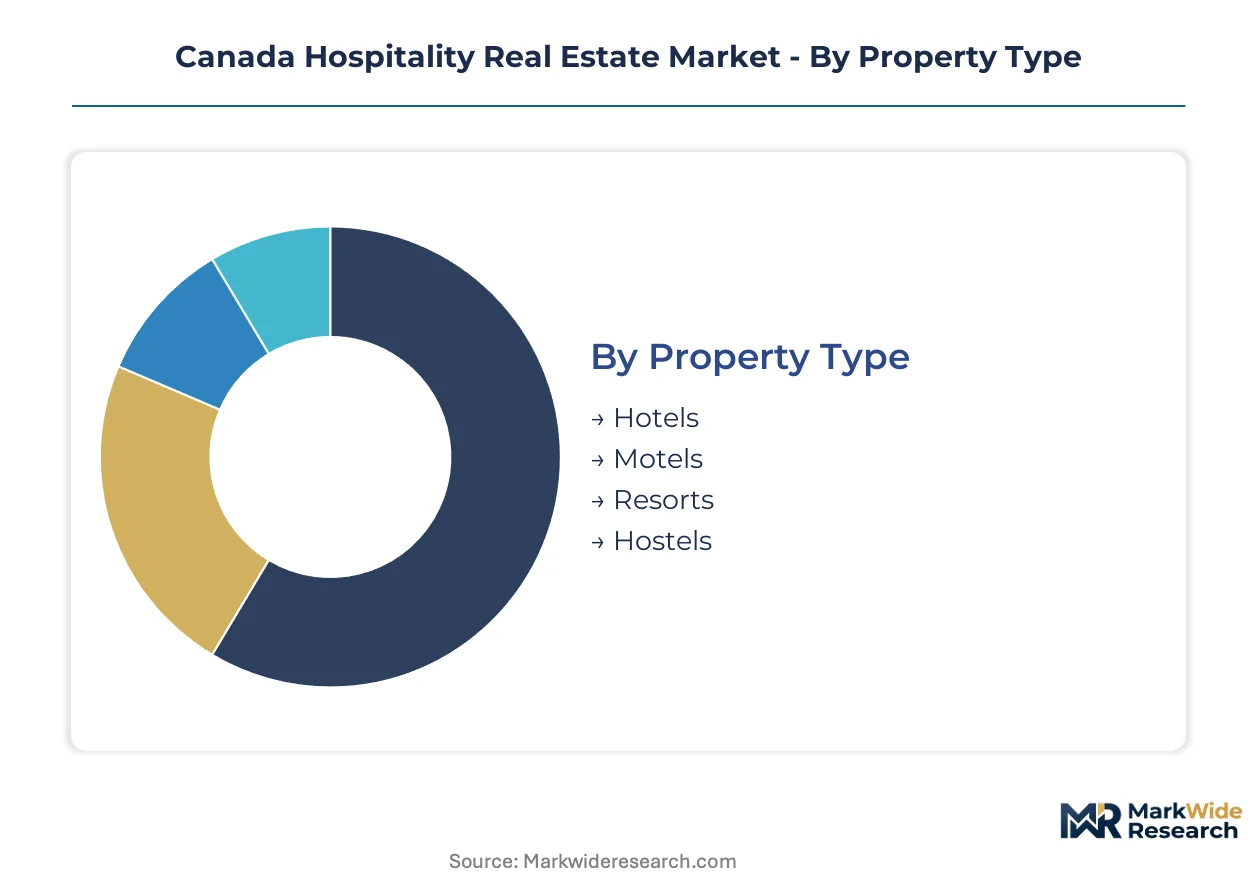
Segmentation in Canadian hospitality real estate exposes how capital allocation, operational complexity, and demand fragmentation create divergent risk-return profiles across property categories. Investors targeting Ontario and British Columbia trophy assets face fundamentally different labor cost structures and regulatory timelines than those pursuing secondary market limited-service formats.
Property Type:
Buyers differentiate by construction standard, revenue diversification, and capital intensity required for seismic and energy code compliance.
- Hotels:Steel-frame or reinforced concrete structures with integrated F&B and meeting facilities command rate premiums in Toronto and Vancouver urban cores. Health Canada guidelines mandate accessibility retrofits that compress renovation planning windows for full-service properties.
- Motels:Low-rise configurations along highway corridors minimize staffing overhead through exterior corridor access and limited amenity provision. Budget operators in secondary markets exploit this format to avoid labor cost intensity plaguing full-service competitors.
- Resorts:Destination properties in British Columbia mountain and coastal regions bundle accommodation with experiential recreation assets.
- Hostels:Shared-lodging formats concentrate in Montreal and Vancouver youth tourism corridors with minimal service infrastructure.
Hotels lead volumes today; hostels are gaining share fastest in urban leisure corridors.
Service Type:
Margin structure and staffing ratios separate buyers pursuing operational efficiency from those accepting labor intensity for rate positioning.
- Full-Service:Properties with on-site restaurants, bars, and extensive meeting space face margin compression from housekeeping and F&B staffing requirements. Corporate transient demand decoupling from traditional large-block dependency is forcing Toronto and Vancouver operators to rebalance against suburban extended-stay competition.
- Limited-Service:Select-service formats with stripped amenity provision capture growing investor preference for operational efficiency. Extended-stay configurations with kitchenette arrangements are pulling demand from corporate relocation patterns across Calgary and Ottawa.
- Luxury:Trophy assets in Vancouver and Toronto concentrate yield compression risk from green certification mandates and seismic retrofit timelines.
- Budget:Highway corridor and secondary market positioning minimizes capital expenditure exposure to National Building Code upgrade cycles.
Limited-Service properties dominate transaction velocity currently; Luxury assets show steepest expansion trajectory in green-certified retrofit pipelines.
Client Type:
Booking channel fragmentation and length-of-stay patterns determine revenue stability and ancillary monetization potential.
- Corporate Travelers:Hybrid work permanence is fragmenting demand across secondary Canadian markets, displacing traditional single large-block commitments with multiple smaller footprints. Third-party meeting planners are capturing mid-sized event booking authority from traditional corporate travel managers.
- Leisure Guests:Boutique hotel development in Ontario and British Columbia urban cores targets experiential lodging preferences with unbundled amenity pricing for parking and wellness access.
- Group Bookings:Convention and wedding demand concentrates in Montreal and Calgary suburban select-service properties through technology-enabled hybrid event support.
- Solo Travelers:Digital nomad and bleisure segments favor extended-stay formats with co-working access and weekly rate structures.
Corporate Travelers anchor revenue stability today; Solo Travelers are expanding most quickly in hybrid work corridors.
Investment Strategy:
Capital deployment timeline and control level separate institutional platforms from specialized operators.
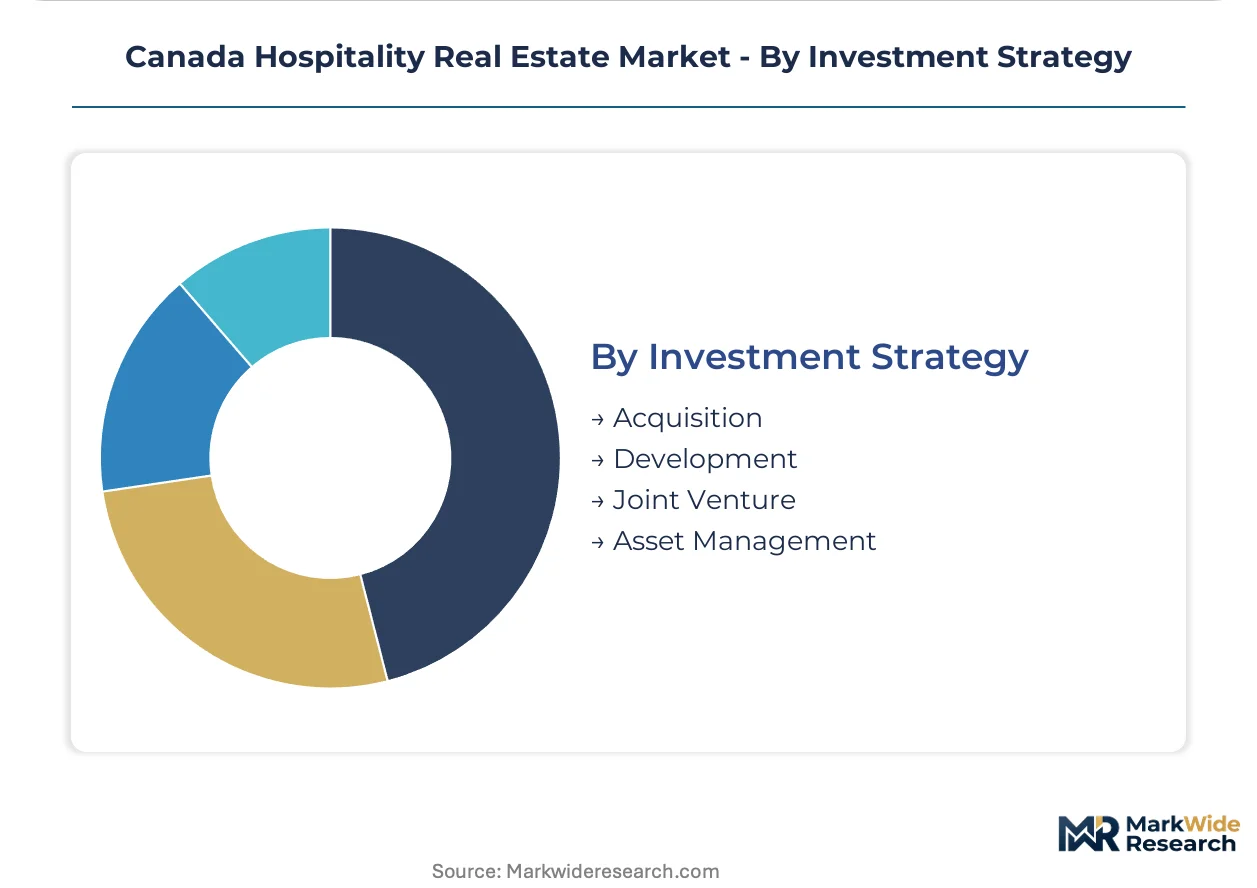
- Acquisition:Asset recycling by dominant gateway market players exploits yield premiums in Calgary and Ottawa relative to Toronto and Vancouver comparables.
- Development:Ground-up construction faces municipal zoning density friction in Toronto, Vancouver, and Montreal that constrains unit count economics.
- Joint Venture:Partnership structures distribute seismic and energy code compliance risk across institutional capital stacks.
- Asset Management:Operational oversight contracts capture ancillary revenue unbundling opportunities without direct property ownership.
Acquisition leads deployment volumes today; Development is climbing the fastest behind CMHC green financing incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling hospitality development toward provinces with more permissive municipal zoning and lower seismic retrofit compliance costs. British Columbia and Ontario absorb capital concentration despite stricter codes, while Alberta and Atlantic Canada capture yield-seeking investors priced out of gateway markets.
Ontario
Toronto's trophy asset pipeline drives institutional capital deployment into full-service urban cores. Health Canada guidelines intersecting provincial building codes compress accessibility retrofit timelines for aging properties. Boutique hotel development concentrates in Ottawa and Niagara corridors targeting leisure travelers with experiential lodging formats.
British Columbia
Vancouver's luxury segment faces margin compression from green certification mandates and seismic code compliance costs. The National Building Code update trajectory elevates upfront capital requirements for steel-frame construction relative to Prairie comparables. Victoria and Whistler resort markets capture secondary demand from corporate relocation patterns and bleisure travel.
Alberta
Calgary hospitality assets trade at yield premiums to Toronto and Vancouver with comparable demand fundamentals from energy sector transient travel. Municipal zoning bylaws in Calgary and Edmonton permit denser unit economics than coastal gateway constraints allow. Extended-stay formats with kitchenette configurations pull corporate relocation demand from downtown full-service competitors.
Quebec
Montreal's group booking market fragments across suburban select-service properties with technology-enabled hybrid event support. Provincial short-term rental regulations on platforms like Airbnb threaten traditional lodging demand pools in urban cores. Groupe Germain Hotels anchors experiential lodging development in Quebec City and Montreal leisure corridors.
Atlantic Canada
Halifax and St. John's markets remain underpenetrated by institutional capital despite comparable leisure demand fundamentals. Canadian Mortgage and Housing Corporation financing frameworks offer cost-of-capital advantages for qualifying green-certified developments in secondary markets. Seasonal resort properties in Prince Edward Island and Nova Scotia coastal regions bundle accommodation with experiential recreation assets.
Canada Hospitality Real Estate Market Competitive Landscape
Asset recycling dominates the current landscape as dominant gateway market players exploit yield premiums in secondary markets. The vendor base concentrates around three strategic archetypes: global capital platforms with urban trophy portfolios, selective asset recyclers with gateway market density, and specialized operators in extended-stay and select-service formats. Portfolio diversification and operational efficiency investments represent the dominant competitive moves as labor cost intensity compresses full-service margins.
Among Canada-based hospitality asset managers, Brookfield Asset Management, InnVest Hotels, and Westmont Hospitality Group exemplify the three archetypal competitive positions. Brookfield occupies the global capital platform tier with large-scale urban hospitality portfolios anchored by institutional capital stacks. InnVest represents the selective asset recycler model sustaining dominant positioning across Canadian gateway markets through disciplined capital deployment. Westmont sits within the specialized operator category competing through extended-stay and select-service formats that avoid labor cost intensity plaguing legacy full-service properties.
| Leading Market Players |
|---|
| Brookfield Asset Management |
| InnVest Hotels |
| Westmont Hospitality Group |
| Superior Lodging Corp |
| Coast Hotels |
| Fairmont Raffles Hotels International |
| Choice Hotels Canada Inc |
| IHG (InterContinental Hotel Group) |
| Groupe Germain Hotels |
| Others |
Pricing and Supply Chain Analysis
Institutional capital allocators in Toronto and Vancouver gateway markets anchor pricing power through trophy asset scarcity, while secondary market operators compete on yield spreads that compress operational margins. CMHC financing advantages for green-certified developments concentrate capital deployment into qualifying assets, creating bifurcated pricing dynamics between certified and legacy inventory.
Pricing Analysis
Direct-to-investor placement discounts dominate large-block transactions, bypassing traditional broker markups for institutional portfolios. Three-tier pricing structure across luxury, select-service, and economy levels reflects labor intensity differentials and amenity bundling rather than pure location premiums. Pricing pressure stems from short-term rental substitution in urban cores, forcing traditional operators toward weekly rate structures. Corporate transient buyers exhibit highest price sensitivity as hybrid work patterns fragment volume commitments, while leisure trophy asset buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Freight cost volatility in steel and reinforced concrete inputs elevates construction contingency reserves for seismic-compliant structures. Material sourcing concentrates in Ontario, Quebec, and British Columbia manufacturing corridors, with specialty glazing and HVAC systems drawing from U.S. Midwest distribution hubs. Single-source vulnerability in green certification consulting compresses project timelines when demand surges. Distribution runs through regional general contractors with CMHC pre-qualification status, linking financing eligibility to supply chain partner selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada hospitality real estate functions as a stable compounder anchored by urban land scarcity and persistent leisure demand migration toward experiential formats. Structural tailwinds from National Building Code green mandates create durable retrofit pipelines that sustain contractor and supplier ecosystems.
For Market Incumbents: Hedge full-service margin compression by accelerating select-service format conversions in Calgary and Ottawa corridors. CMHC financing leverage represents the critical lever for funding green certification retrofits ahead of regulatory deadlines. Threat substitution from municipal short-term rental enforcement demands proactive zoning compliance investment. For New Entrants and Emerging Players: The mid-market select-service gap between luxury trophy assets and highway economy motels offers the most penetrable white space. Secondary markets in Atlantic Canada and Prairie provinces present acquisition targets at yield premiums to gateway comparables. Go-to-market positioning should anchor on extended-stay kitchenette configurations targeting corporate relocation demand. For Investors and Strategic Acquirers: Pension fund platforms and insurance capital allocators represent the most active acquirer category in this space. Long-term viability rests on 10-year hold horizons that capture multiple renovation cycles and regulatory compliance premiums. Watch CMHC green financing allocation announcements as the signal for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Retrofit | Captures CMHC financing advantages while preempting Health Canada accessibility mandates. |
| Select-Service Format Conversion | Avoids labor cost intensity compressing full-service margins in Toronto and Vancouver. |
| Secondary Market Acquisition | Exploits yield premiums in Calgary and Ottawa relative to gateway city comparables. |
| Extended-Stay Configuration | Pulls corporate relocation demand from traditional full-service competitors. |
| Ancillary Revenue Unbundling | Monetizes parking, co-working, and wellness amenities beyond nightly accommodation leases. |
Research Methodology
Coverage spans Ontario, British Columbia, Alberta, Quebec, and Atlantic Canada, with primary inputs from each regional cluster. The research combines structured interviews with asset managers, hotel operators, municipal planning officials, and CMHC financing officers with secondary validation from National Building Code documentation, provincial zoning bylaws, and hospitality transaction databases. Bottom-up property-level revenue modeling triangulates against top-down provincial construction permit flows.
Rate-of-change decomposition separates cyclical occupancy recovery from structural supply growth and regulatory-driven capital expenditure acceleration. Segmentation dimensions include property type, service level, client segment, and investment strategy, with regional regulatory framework as an additional modeling layer. CAGRs derive from rolling construction pipeline analysis and historical transaction velocity patterns, incorporating CMHC financing disbursement trajectories and green certification adoption curves.
Caveats apply where municipal zoning amendments or seismic code enforcement timing could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market