
 Israel Commercial Real Estate Market | 2026-2036
Israel Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Commercial Real Estate Market Outlook
Modular office configurations with flexible lease terms is shifting tenant expectations across Israel's commercial property sector. Azrieli Group Ltd leverages its mixed-use portfolio dominance to anchor retail-office hybrid developments in central business districts. Amot Investment Ltd competes through specialized industrial logistics facilities serving e-commerce fulfillment networks. Melisron Ltd differentiates via controlled retail environments in secondary urban centers.
Israel commercial real estate comprises income-producing properties including office towers, retail centers, industrial warehouses, and mixed-use developments, typically constructed with reinforced concrete frames and curtain wall systems designed for seismic resistance per Israeli Standard 413. These assets generate returns through lease revenue streams and capital appreciation for institutional and private capital pools. Office properties command premium rents in Tel Aviv's Rothschild Boulevard corridor, while industrial segments absorb logistics demand from port-adjacent zones. Retail faces structural pressure from digital commerce, though experiential and grocery-anchored formats retain defensive positioning. Mixed-use developments attract blended capital from REITs and foreign investors seeking risk-adjusted exposure across property cycles.
The Israel Land Authority governs leasehold conversions and development rights allocation, directly constraining supply elasticity in core markets. Municipal zoning under the Ministry of Finance's urban renewal frameworks shapes density bonuses and affordable housing set-asides that alter project feasibility. The Planning and Building Law enforcement by district committees determines timeline risk for pre-construction assets. Stakeholders must monitor coalition stability around housing reform legislation and its spillover effects on commercial permitting velocity.
Market Dynamics
Israel's commercial real estate sector confronts a structural supply-demand asymmetry driven by the Israel Land Authority's centralized control over development rights, which constrains inventory expansion in the Gush Dan corridor despite sustained tenant demand from technology and life sciences clusters.
Growth Catalysts
- National Outline Plan 38:This urban renewal framework accelerates redevelopment approvals for aging residential stock, freeing adjacent commercial parcels for mixed-use densification in Tel Aviv's core districts.
- Technology sector expansion:Cybersecurity and fintech tenants are absorbing Class A office space along Rothschild Boulevard and the Atidim Park corridor, driving pre-leasing activity ahead of construction completion.
- Port-adjacent logistics demand:E-commerce fulfillment networks are concentrating distribution facilities near Haifa and Ashdod maritime terminals, absorbing industrial inventory at premium rents.
Market Restraints
- Leasehold conversion friction:The Israel Land Authority's bureaucratic allocation process extends development timelines, compressing developer IRRs and deterring speculative construction starts.
- Construction input volatility:Reinforced concrete and steel reinforcement costs fluctuate with import dependency, eroding project feasibility margins for mid-rise commercial developments.
- Seismic engineering requirements:Israeli Standard 413 mandates expensive structural redundancy, adding capex premiums that disadvantage smaller developers against institutional balance sheets.
Strategic Opportunities
- Secondary city retail repositioning:Controlled-environment retail formats in Beersheba and Haifa offer yield premiums as anchor tenants seek defensive positioning outside Tel Aviv's saturated core.
- Life sciences conversion:Obsolete office inventory near Weizmann Institute and Hebrew University research corridors presents laboratory retrofit potential serving biotech venture formation.
- Municipal density bonuses:Affordable housing set-aside negotiations with district planning committees unlock height and FAR concessions for mixed-use towers in Jerusalem's emerging business district.
Industry Challenges
- Planning committee timeline risk:District committee backlogs under the Planning and Building Law extend pre-construction phases, straining developer carrying costs and equity lockup periods.
- Specialized asset management scarcity:Operational expertise in laboratory and cold-chain logistics facilities remains concentrated among a handful of institutional platforms, limiting competitive entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Commercial Real Estate Market |
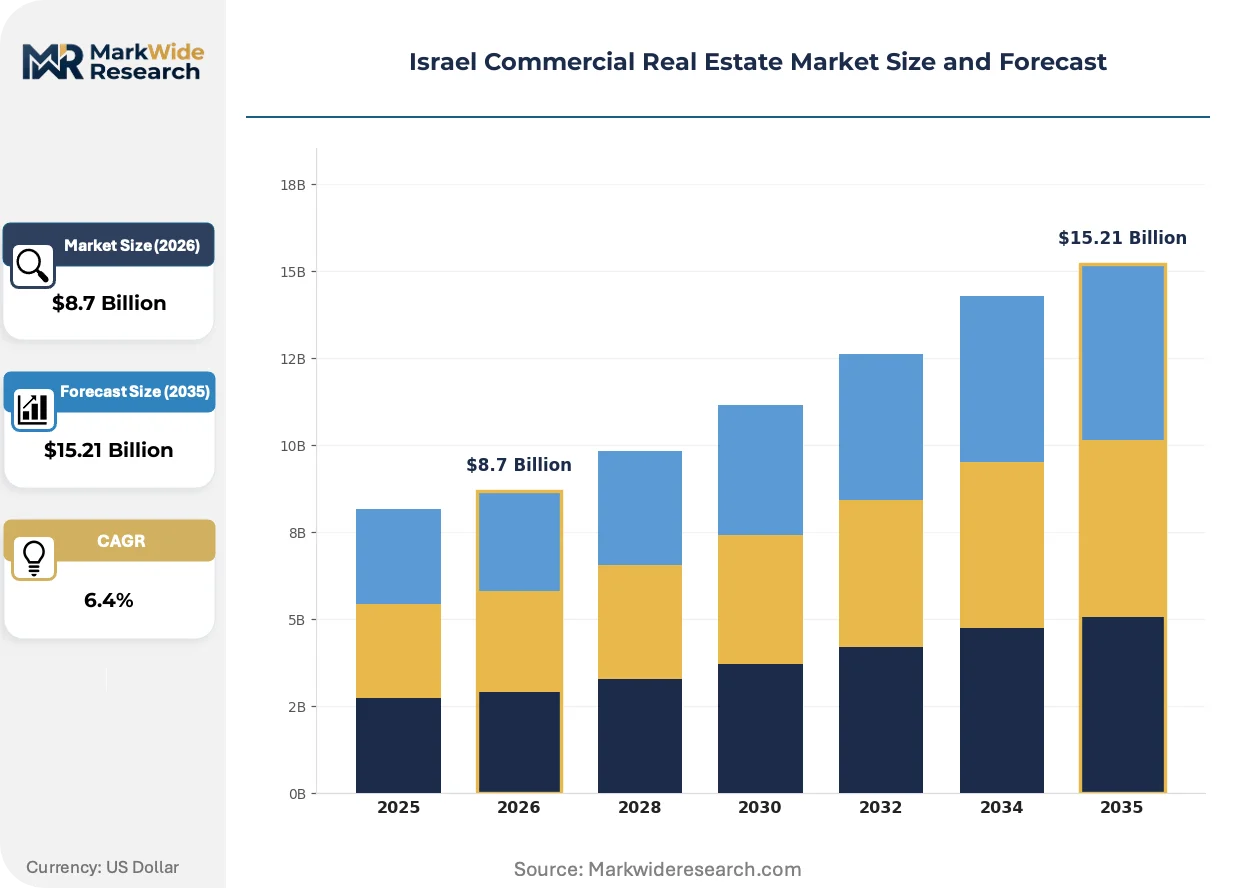
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Strategy: Core, Value-Added, Opportunistic, Development Market Segment: Institutional Investors, REITs, Private Equity, Foreign Investors Development Stage: Pre-Construction, Under Construction, Completed, Renovation |
| Companies Covered | Arko Holdings Ltd, Alony-Hetz Properties, Azrieli Group Ltd, Mivne Real Estate, Amot Investment Ltd, Melisron Ltd, Ashtrom Group Ltd, Y.H. Dimri Construction, Gazit-Globe Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Commercial Real Estate Market Strategic Shifts
Smart building infrastructure is penetrating Israel's commercial stock at accelerating velocity, compressing operating cost structures and resetting tenant expectations for environmental performance and space flexibility.
Building management systems integrating IoT sensor networks are automating HVAC optimization and predictive maintenance scheduling across Tel Aviv's Class A towers. Property managers at Azrieli Center and surrounding developments are deploying these platforms to reduce energy intensity and extend equipment lifecycle. The technology is automating manual commissioning processes that previously required specialized engineering oversight, enabling leaner operational staffing models.
Amendments to Israel's Planning and Building Law are tightening environmental performance standards for new commercial permits, mandating solar readiness and green roof provisions. The Ministry of Finance's urban renewal directives now embed energy efficiency benchmarks into density bonus calculations. Developers pursuing National Outline Plan 38 projects must demonstrate compliance with these standards to secure municipal approvals, favoring sponsors with in-house sustainability expertise.
Tenants are compressing lease commitment horizons and demanding modular fit-out allowances that accommodate headcount volatility. Technology sector occupiers in the Atidim Park and Ofer Park clusters are negotiating shorter initial terms with expansion options rather than traditional ten-year locks. This pattern concentrates in R&D-intensive submarkets where venture funding cycles drive workforce scaling unpredictability, forcing landlords to price optionality into base rents.
Israel Commercial Real Estate Market Segmentation
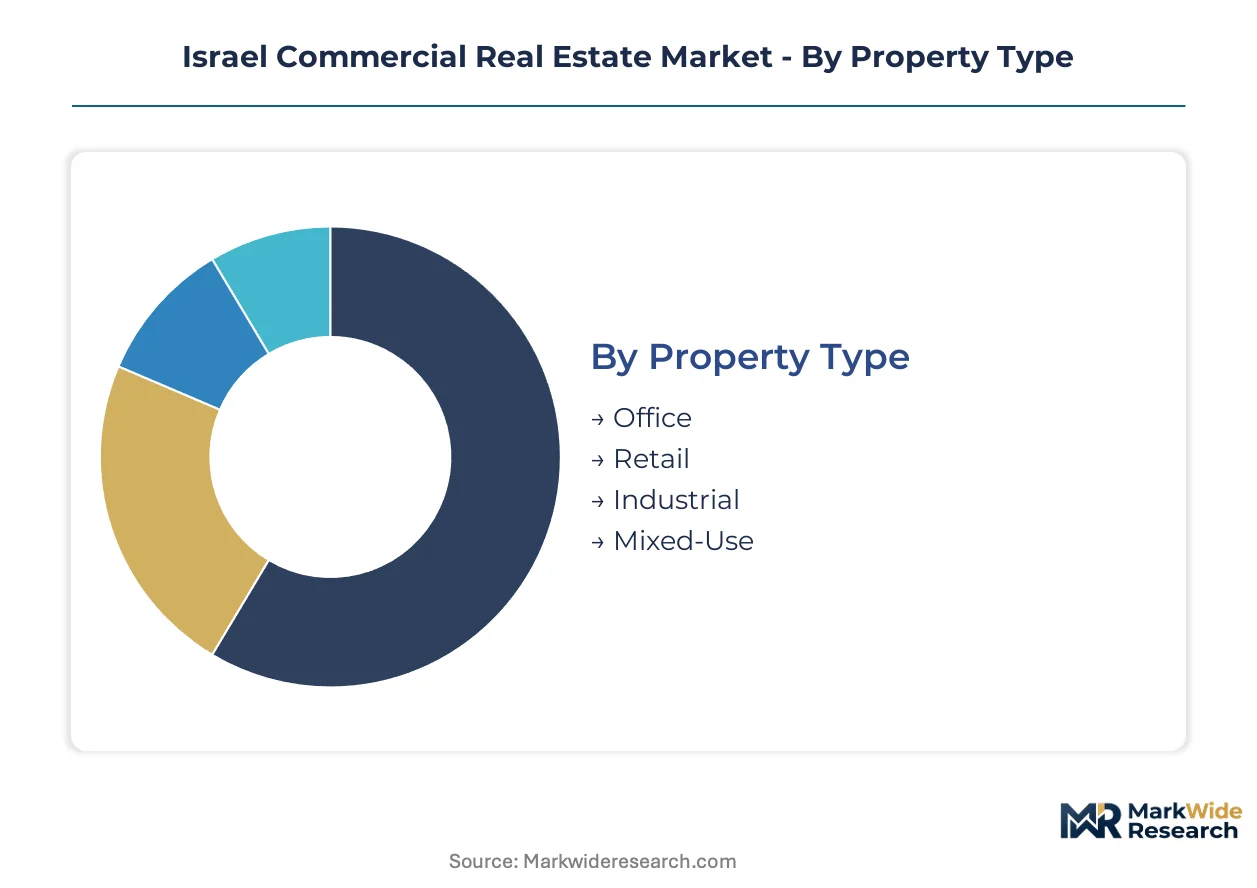
Israel's commercial real estate market segments across property function, capital strategy, investor profile, and asset lifecycle stage. Each dimension shapes risk-return profiles and dictates specialized operational expertise requirements for market participants.
Property Type:
Upgrade cycles vary dramatically across property types, with functional obsolescence driving replacement demand at different velocities for each asset class.
- Office:Class A towers with curtain wall systems and seismic-resistant reinforced concrete frames command premium rents in Tel Aviv's Rothschild Boulevard corridor. Technology sector tenants from cybersecurity and fintech clusters are pre-leasing space ahead of construction completion, absorbing inventory despite shorter lease commitment horizons.
- Industrial:Port-adjacent logistics facilities near Haifa and Ashdod maritime terminals serve e-commerce fulfillment networks with specialized cold-chain and high-bay configurations. The Israel Land Authority's leasehold conversion process constrains greenfield supply expansion, compressing vacancy rates in existing stock.
- Retail:Controlled-environment formats and grocery-anchored centers in secondary urban centers retain defensive positioning against digital commerce pressure.
- Mixed-Use:Hybrid retail-office developments in central business districts blend revenue streams across property cycles, attracting blended capital from institutional pools seeking risk-adjusted exposure.
Office sits at the top of the volume ranking, with Industrial climbing the fastest.
Investment Strategy:
Capital deployment strategies stratify by risk tolerance and return hurdle, with each tier demanding distinct asset management capabilities and holding period commitments.
- Core:Stabilized income-producing assets in Tel Aviv's Gush Dan metropolitan region generate predictable lease revenue with minimal value-add requirements. Institutional investors favor these properties for liability-matching characteristics.
- Value-Added:Underperforming assets requiring operational repositioning or lease-up in emerging corridors near Hebrew University and Weizmann Institute research clusters attract specialized sponsors with turnaround expertise.
- Opportunistic:Distressed or structurally complex assets with significant lease rollover or capital expenditure requirements command higher return thresholds from private equity pools with extended lockup structures.
- Development:Ground-up construction and National Outline Plan 38 urban renewal projects carry timeline risk from district planning committee backlogs under the Planning and Building Law.
Core strategies dominate committed capital volumes, with Development strategies expanding most quickly as urban renewal frameworks accelerate.
Market Segment:
Investor type determines access to deal flow, financing structures, and regulatory navigation capabilities across Israel's constrained land market.
- Institutional Investors:Domestic pension funds and insurance balance sheets anchor Core allocations with long-duration liabilities matching stabilized asset cash flows.
- REITs:Exchange-traded vehicles like Azrieli Group and Amot Investment provide retail investor access to diversified property portfolios with mandated distribution requirements.
- Private Equity:Discretionary capital pools target Value-Added and Opportunistic strategies with higher return hurdles and operational value creation mandates.
- Foreign Investors:Cross-border capital faces additional complexity from Israel Land Authority leasehold conversions and currency hedging requirements.
Institutional Investors maintain the largest deployed capital base, with Foreign Investors gaining share fastest as regulatory clarity improves.
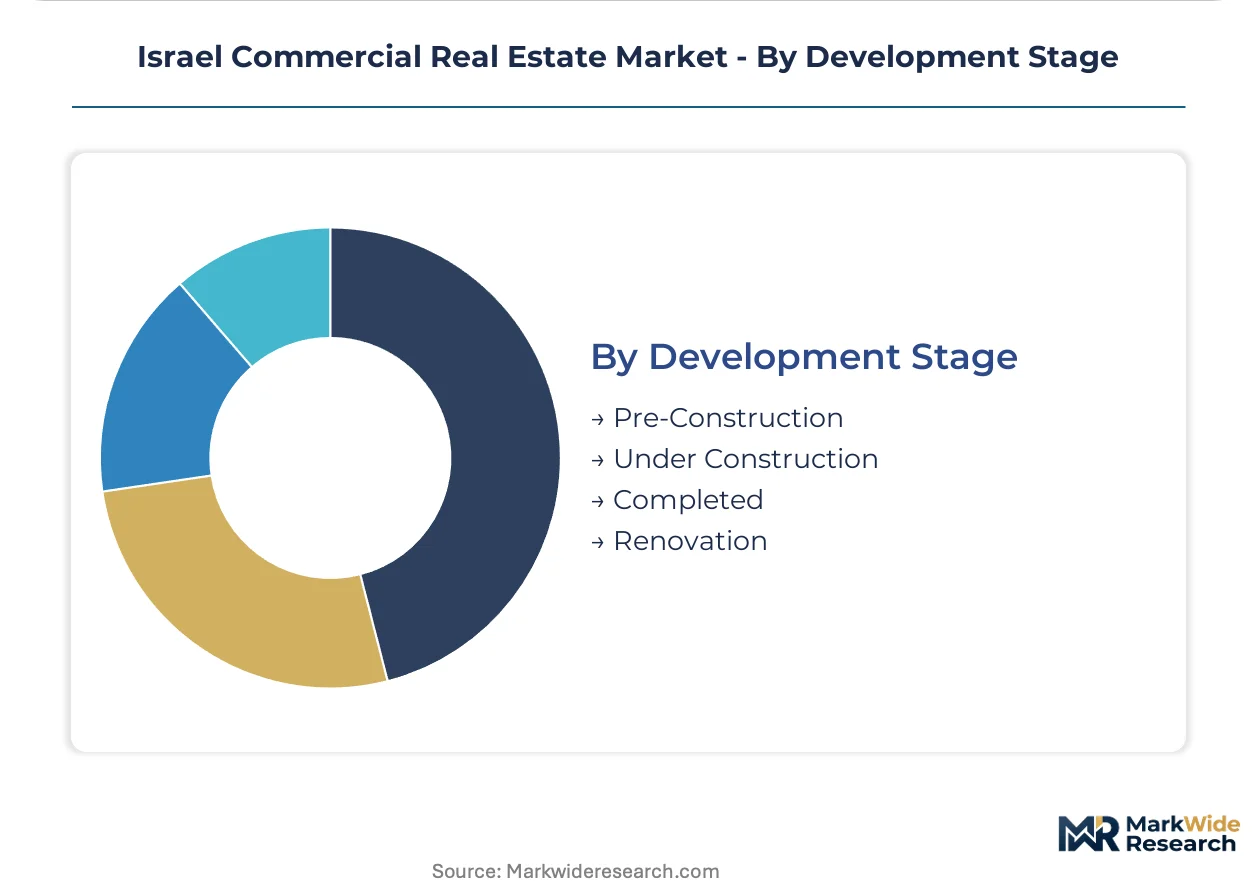
Development Stage:
Asset maturity across the construction lifecycle creates distinct risk profiles and capital structure requirements for sponsors.
- Pre-Construction:Entitlement-phase assets carry planning committee timeline risk and equity lockup uncertainty until municipal approvals finalize.
- Under Construction:Vertical development exposes sponsors to construction input volatility in reinforced concrete and steel reinforcement costs.
- Completed:Stabilized assets with in-place cash flows trade at yield compression as technology sector tenant demand intensifies bidding competition.
- Renovation:Existing stock retrofit for laboratory and life sciences use near research corridors presents conversion potential serving biotech venture formation.
Completed assets transact at the highest velocity, with Renovation projects showing the steepest expansion trajectory as functional obsolescence accelerates repurposing activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate development in Israel traces its modern lineage to post-independence state-led construction programs that concentrated economic infrastructure around Tel Aviv. The sector evolved through centralized land allocation mechanisms that persist today, shaping geographic patterns of supply constraint and demand concentration.
Tel Aviv Metropolitan Area
Technology sector tenants from cybersecurity and fintech clusters are absorbing Class A office inventory along Rothschild Boulevard and the Atidim Park corridor. The Israel Land Authority's leasehold conversion process governs development rights allocation, compressing supply elasticity. Pre-leasing activity accelerates ahead of construction completion as venture-funded firms expand footprints.
Haifa Bay Region
Port-adjacent logistics facilities serve e-commerce fulfillment networks with specialized cold-chain configurations. The Planning and Building Law enforcement by Haifa district committees determines timeline risk for industrial developments. Maritime terminal proximity drives premium rents for distribution assets near the Kishon Port industrial zone.
Jerusalem
Municipal density bonus negotiations unlock height and FAR concessions for mixed-use towers in the emerging business district. National Outline Plan 38 urban renewal frameworks accelerate redevelopment approvals for aging stock. Hebrew University research corridors attract laboratory retrofit investment serving biotech venture formation.
Beersheba
Controlled-environment retail formats offer yield premiums as anchor tenants seek defensive positioning outside Tel Aviv's saturated core. The Ministry of Finance's urban renewal directives shape affordable housing set-asides that alter project feasibility. Secondary city positioning attracts capital seeking risk-adjusted exposure beyond primary markets.
Ashdod
Industrial logistics demand concentrates near the port maritime terminal with high-bay warehouse configurations. Israeli Standard 413 seismic engineering requirements add capex premiums that favor institutional balance sheets. E-commerce networks absorb inventory at compressed vacancy rates despite construction input volatility.
Israel Commercial Real Estate Market Competitive Environment
The competitive structure tilts toward diversified holding companies with mixed-use portfolio dominance. Market concentration reflects centralized land access advantages rather than pure operational scale. Two strategic archetypes predominate: integrated developers controlling vertical construction pipelines, and specialized REITs monetizing stabilized income streams. Competitive moves cluster around municipal density bonus negotiations and National Outline Plan 38 project aggregation.
Within the integrated developer tier, Azrieli Group Ltd anchors retail-office hybrid positioning in central business districts. Amot Investment Ltd and Melisron Ltd occupy complementary positions across industrial logistics and controlled retail environments respectively. These entities exemplify how leasehold conversion expertise and planning committee relationships create defensive moats against new entrants lacking comparable regulatory navigation capabilities.
| Leading Market Players |
|---|
| Arko Holdings Ltd |
| Alony-Hetz Properties |
| Azrieli Group Ltd |
| Mivne Real Estate |
| Amot Investment Ltd |
| Melisron Ltd |
| Ashtrom Group Ltd |
| Y.H. Dimri Construction |
| Gazit-Globe Ltd |
| Others |
Value Chain & Pricing Dynamics
Class A tower premiums versus secondary market commodity rents bifurcate Israel's commercial real estate landscape, with this divergence manifesting in both lease rate structures and construction input sourcing patterns. Premium assets command institutional-grade pricing while mid-tier developments face margin compression from volatile reinforced concrete and steel reinforcement costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs lease negotiations in Israel's constrained land market. Price differentiation centers on seismic resilience certification under Israeli Standard 413 and proximity to Tel Aviv's Rothschild Boulevard corridor. Cost compression in standard-grade office stock is intensifying because technology tenants negotiate shorter commitment horizons with expansion options. Startup and venture-funded occupiers exhibit highest price sensitivity, whereas sovereign wealth and pension fund landlords demonstrate lowest elasticity.
Supply Chain Analysis
Skilled seismic engineering labor scarcity in Israel and neighboring construction markets constrains development velocity. Geographic supply concentration centers on Turkey, China, and domestic Israeli producers for reinforced concrete and curtain wall systems. Raw material dependencies include steel reinforcement bars, aluminum framing, and low-emissivity glazing. Single-source vulnerability runs through maritime shipping lanes serving Haifa and Ashdod ports. Distribution runs through vertically integrated developers with captive project management capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
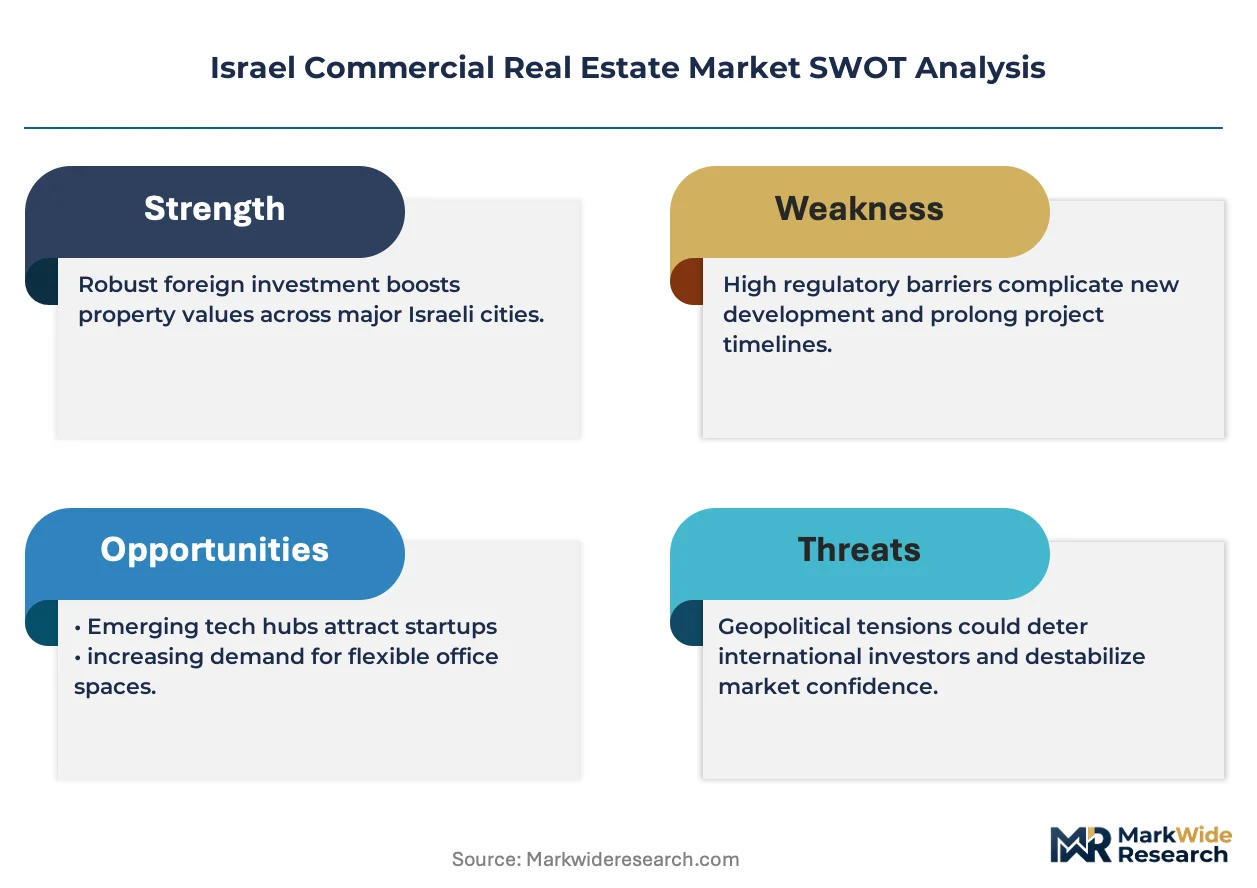
Israel's commercial real estate market functions as a geographic-arbitrage play between Tel Aviv's supply-constrained premium corridor and Beersheba's emerging secondary market, with development cost differentials exceeding 40% on a per-square-meter basis.
For Market Incumbents: To counter technology tenant demand for modular lease configurations, Azrieli Group and Amot Investment should deepen in-house sustainability expertise to secure National Outline Plan 38 density bonuses, while consolidating planning committee relationships to accelerate pre-construction timelines. For New Entrants and Emerging Players: National Outline Plan 38 in Israel opens a window for specialized laboratory conversion plays near Weizmann Institute and Hebrew University research corridors. Secondary city retail repositioning in Haifa and Beersheba offers the most penetrable entry point, with municipal density bonus negotiations as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with development-stage sponsors holding entitled land positions in Jerusalem's emerging business district. Long-term viability over a five-to-ten-year window favors platforms with demonstrated leasehold conversion expertise. Watch for coalition stability around housing reform legislation as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Urban Renewal Project Aggregation | National Outline Plan 38 expertise accelerates redevelopment approvals in Tel Aviv core districts. |
| Mixed-Use Tower Development | Blended retail-office revenue streams attract institutional capital across property cycles. |
| Smart Building Infrastructure Deployment | IoT sensor networks at Azrieli Center reduce energy intensity and extend equipment lifecycle. |
| Life Sciences Conversion | Laboratory retrofit near Weizmann Institute serves biotech venture formation demand. |
| Secondary City Retail Repositioning | Controlled-environment formats in Beersheba capture yield premiums outside saturated core markets. |
Study Parameters
Direct dialogue with property developers, municipal planning officials, institutional portfolio managers, and construction procurement leads anchored the qualitative foundation for this study. Secondary validation drew from Israel Land Authority lease allocation records, Ministry of Finance urban renewal directives, Planning and Building Law enforcement databases, and district committee approval timelines. Bottom-up asset-level cash flow modeling and top-down macroeconomic scenario analysis provided triangulation.
Bottom-up lease rate and absorption velocity data by submarket were cross-referenced against top-down GDP and technology sector employment projections across the analysis window. Segmentation dimensions modeled include property type, investment strategy, investor profile, and development stage. CAGRs were derived from historical transaction velocity and forward supply pipeline analysis. Key inputs encompassed tenant pre-leasing ratios and construction cost inflation assumptions.
Revisions become necessary when coalition instability disrupts housing reform legislation, Israel Land Authority leasehold conversion timelines extend materially, or seismic engineering standard amendments alter project feasibility. Material deviation in these triggers warrants pause and re-evaluation of development-stage exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market