
 China Commercial Real Estate Market | 2026-2036
China Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
China Commercial Real Estate Market Analysis
Asset-light operating models with third-party management contracts is reconfiguring competitive dynamics for domestic developers without balance-sheet scale. China Vanke Co. leverages its property-as-a-service platform to extend fee-based revenue streams beyond development cycles. Poly Developments and Holdings Group Co. anchors its position through state-backed land bank access in tier-two provincial capitals. Longfor Group differentiates via specialized retail mall operations that sustain higher tenant retention rates than conventional office landlords.
China commercial real estate encompasses income-producing properties including office towers, retail complexes, industrial logistics facilities, and hospitality assets, typically constructed with reinforced concrete core structures and curtain wall envelopes designed for multi-tenant occupancy over twenty-to-thirty-year economic lifespans. The sector serves institutional capital deployment, corporate operational footprint expansion, and consumer service delivery across urban economic zones. Office and industrial segments currently lead transaction velocity as technology and e-commerce tenants absorb Grade A space in Shenzhen and Chengdu. Retail property faces structural repricing as experiential formats replace traditional department store anchors, while hospitality recovery tracks inbound business travel normalization to first-tier city hubs.
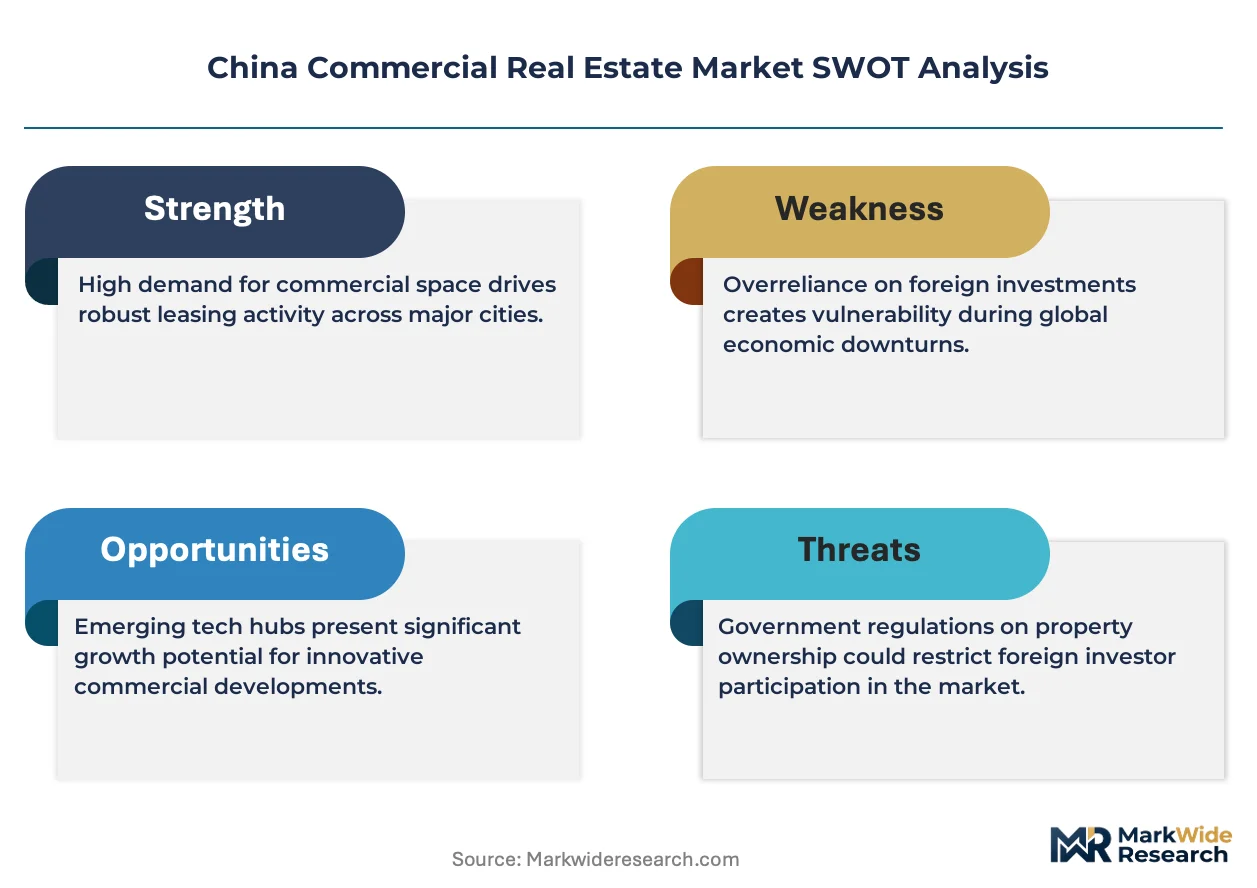
China's Ministry of Ecology and Environment enforces dual carbon compliance timelines that tighten energy efficiency standards for new commercial construction, while SAMR oversees fire safety and structural GB standards that dictate material specifications and elevator system mandates. Local urban planning bureaus in Beijing and Shanghai layer additional floor-area-ratio incentives for developers achieving three-star green building certification. Stakeholders must monitor how MEE carbon intensity benchmarks propagate from pilot zones to national code adoption, as this regulatory trajectory will determine which existing assets face accelerated obsolescence versus premium repricing.
Market Dynamics
China's dual carbon mandates under MEE oversight are compressing asset obsolescence timelines while redirecting capital toward retrofit-ready properties in tier-one hubs.
Growth Catalysts
- Logistics infrastructure expansion:E-commerce fulfillment networks in the Greater Bay Area absorb modern warehouse stock at accelerating velocity.
- MIIT data center directives:Computing cluster approvals in Guiyang and Ulanqab concentrate hyperscale leasing demand in designated zones.
- Green building certification premiums:Three-star GB standards unlock floor-area-ratio bonuses from Beijing and Shanghai planning bureaus.
Market Restraints
- Reinforced concrete input volatility:Cement and steel price swings compress development margins on new Grade A office starts.
- Land bank access concentration:State-backed developers dominate prime parcel auctions in provincial capitals.
- Curtain wall technical limitations:Thermal performance gaps in legacy envelopes block retrofit pathways for pre-2015 assets.
Strategic Opportunities
- Chengdu-Chongqing corridor penetration:Western logistics hubs attract cold-chain infrastructure investment from consumer goods distributors.
- MEE carbon intensity pilots:Benchmark zones in Shenzhen and Hangzhou preview national code adoption timelines.
- Property-as-a-service platforms:Third-party management contracts decouple revenue from development cycles.
Industry Challenges
- Green building certification timelines:Three-star GB compliance documentation delays lease-up schedules.
- Retrofit capex intensity:HVAC and envelope upgrades strain REIT distribution coverage ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Commercial Real Estate Market |
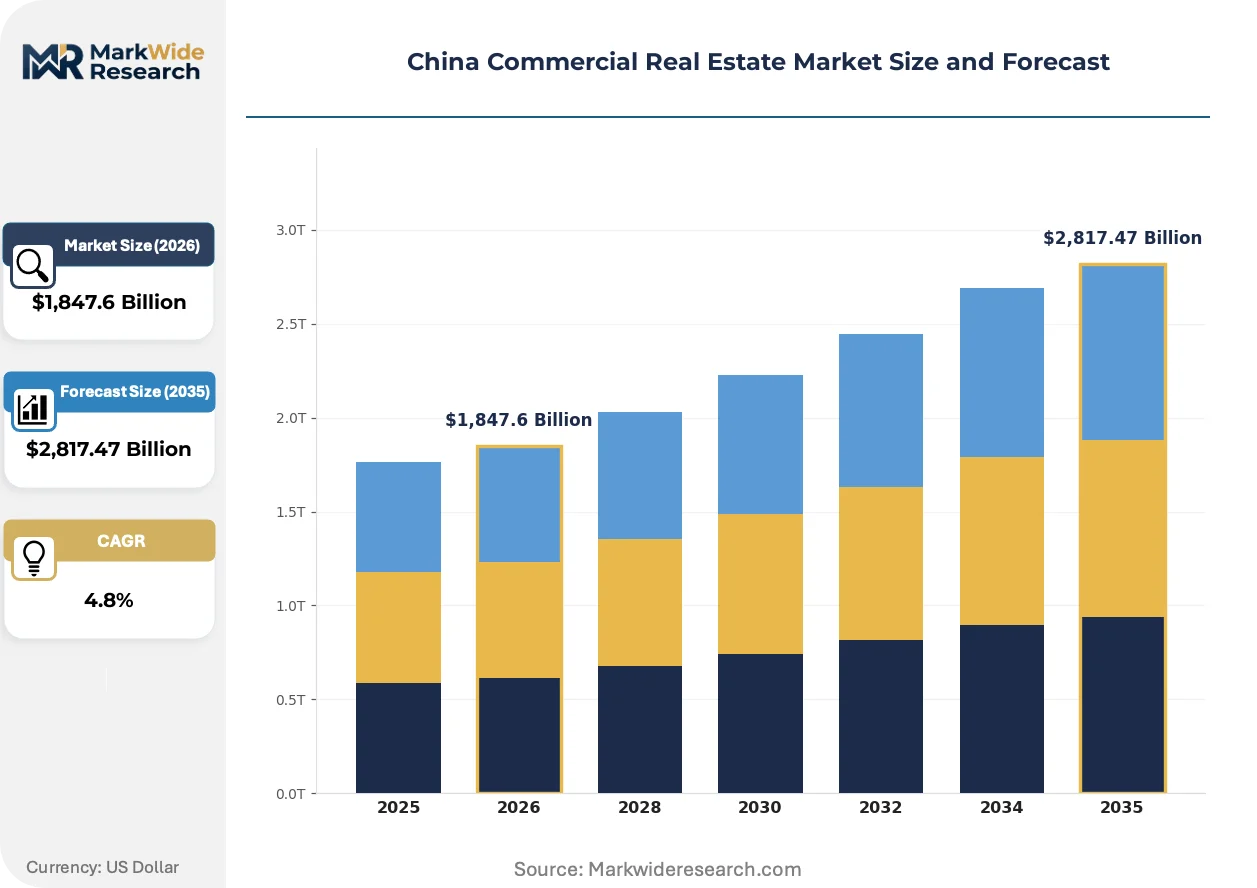
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $2,817.47 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Type: Direct Investment, REITs, Joint Ventures, Private Equity Client Type: Institutional Investors, Developers, Corporations, High-Net-Worth Individuals Transaction Type: Leasing, Purchase, Sale, Financing |
| Companies Covered | China Resources Land Ltd, Poly Developments and Holdings Group Co., China Vanke Co., Shanghai Zhangjiang Hi-Tech Park Development Co., China Merchants Shekou Industrial Zone Holdings, Longfor Group, Greenland Group, Suzhou New District Hi-Tech Industrial Co.,Ltd, Wanda Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Commercial Real Estate Market Emerging Trajectories
Digital infrastructure integration and regulatory carbon accounting are reconfiguring how commercial assets attract capital and retain tenants.
Smart building management systems is hybridizing operational data streams from elevator sensors, HVAC controls, and occupancy monitors into unified platforms. Logistics operators in Shenzhen deploy these systems to optimize energy consumption across multi-tenant facilities. The convergence compresses facility management cost structures while elevating rental premiums for certified efficient stock.
MEE dual carbon enforcement tightens energy efficiency disclosure requirements for commercial assets above 20,000 square meters. Developers must submit verified carbon intensity metrics to secure operating permits in pilot zones. Office landlords in Beijing and Shanghai accelerate sensor deployment to meet quarterly reporting mandates.
Tenant procurement of space shifts toward outcome-based utility contracts that bundle base rent with guaranteed energy performance. Logistics firms in Hangzhou prefer gross leases with efficiency clauses over traditional net structures. This preference concentrates demand in assets with verified green building certification.
China Commercial Real Estate Market Segmentation
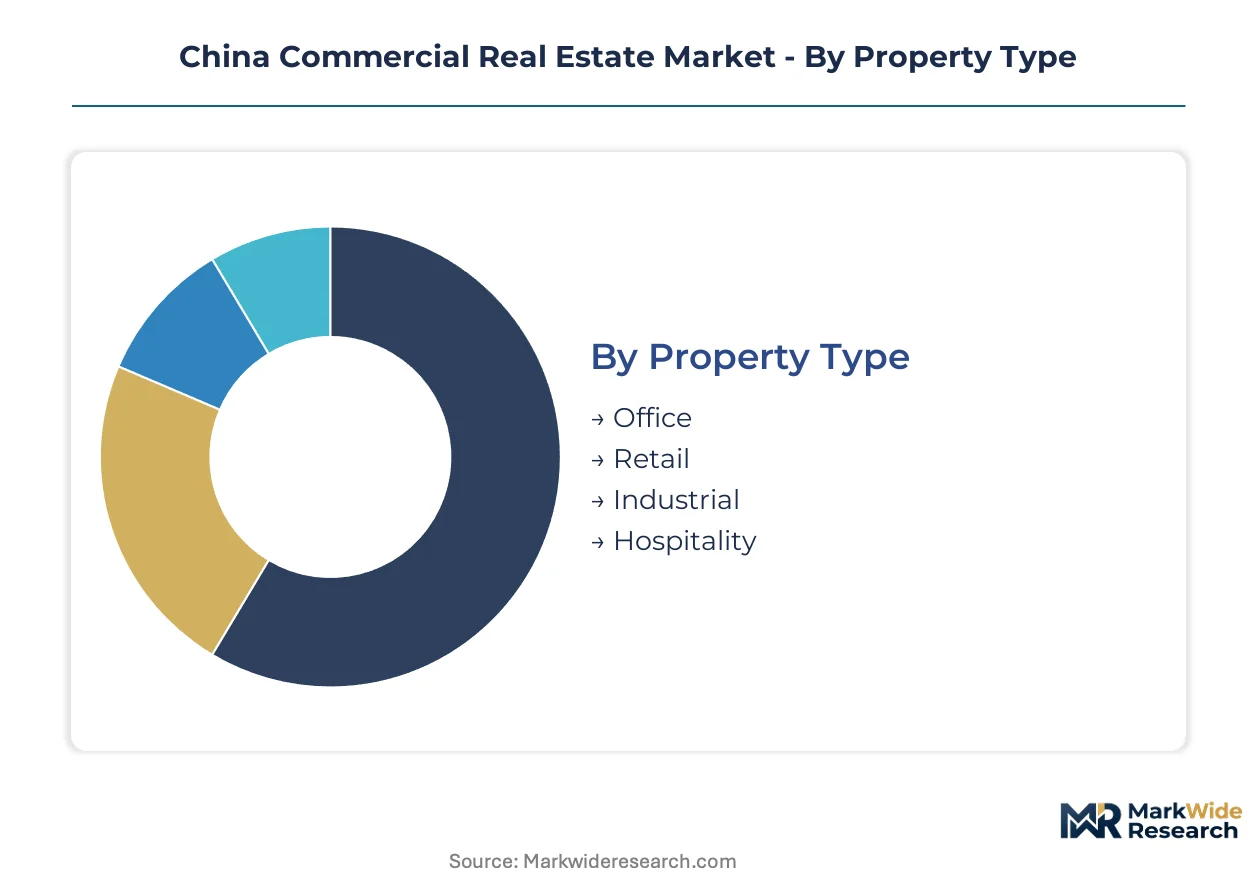
Segmentation in China's commercial real estate market exposes how capital sources, tenant profiles, and transaction structures diverge across asset classes. Understanding these fault lines clarifies where MEE carbon mandates and MIIT infrastructure directives concentrate pressure versus opportunity.
Property Type:
The use-case spectrum spans corporate workspace, consumer-facing retail, logistics infrastructure, and transient accommodation—each carrying distinct lease structures and obsolescence risk profiles.
- Office:Grade A towers with reinforced concrete cores and curtain wall envelopes serve technology and financial services tenants. Shenzhen and Hangzhou absorption rates accelerate as firms expand operational footprints, though MEE dual carbon compliance tightens energy efficiency disclosure thresholds above 20,000 square meters.
- Industrial:Modern logistics facilities with high-clearance warehousing and automated racking systems support e-commerce fulfillment networks. Greater Bay Area cold-chain infrastructure attracts sustained capital deployment from consumer goods distributors seeking proximity to dense urban consumption zones.
- Retail:Experiential formats and community shopping centers replace traditional department store anchors. Structural repricing continues as tenant mix shifts toward food-and-beverage and entertainment operators.
- Hospitality:Full-service hotels and serviced apartments track inbound business travel normalization to first-tier city hubs. Recovery velocity lags office and industrial segments due to extended international travel pipeline restoration.
The dominant share belongs to Office, while Industrial is closing the gap fastest.
Investment Type:
Capital deployment channels reflect risk-return preferences and regulatory access tiers, from balance-sheet direct ownership to securitized structures.
- Direct Investment:Sovereign wealth funds and insurance capital acquire stabilized assets outright. Beijing and Shanghai Grade A towers trade at compressed yields as domestic institutional buyers compete for income certainty.
- REITs:Publicly listed vehicles channel retail capital into income-producing portfolios. SAMR disclosure requirements and MEE carbon intensity benchmarks elevate compliance costs for portfolio managers.
- Joint Ventures:Domestic developers pair with offshore capital to access prime land parcels. State-backed partners anchor land bank access in tier-two provincial capitals.
- Private Equity:Value-add strategies target pre-2015 assets requiring HVAC and envelope retrofit. Distribution coverage ratios strain under capex intensity for green building certification upgrades.
Direct Investment commands the deepest capital pool, though REITs are expanding most quickly as retail participation broadens.
Client Type:
Buyer and operator profiles determine holding periods, leverage appetite, and operational sophistication across the asset lifecycle.
- Institutional Investors:Pension funds and insurance groups prioritize long-duration income with inflation linkage. Three-star GB certification premiums justify rental escalators in lease structures.
- Developers:Balance-sheet construction and pre-leasing activities concentrate in state-backed entities. Poly Developments leverages provincial relationships for tier-two land access.
- Corporations:End-user owner-occupiers acquire build-to-suit facilities for operational control. Technology firms in Shenzhen favor custom specifications over multi-tenant specifications.
- High-Net-Worth Individuals:Family office capital seeks trophy assets in first-tier cities with generational wealth preservation characteristics. Transaction velocity concentrates at ultra-prime price points.
Institutional Investors anchor transaction volume, while Corporations are gaining share fastest through build-to-suit development.
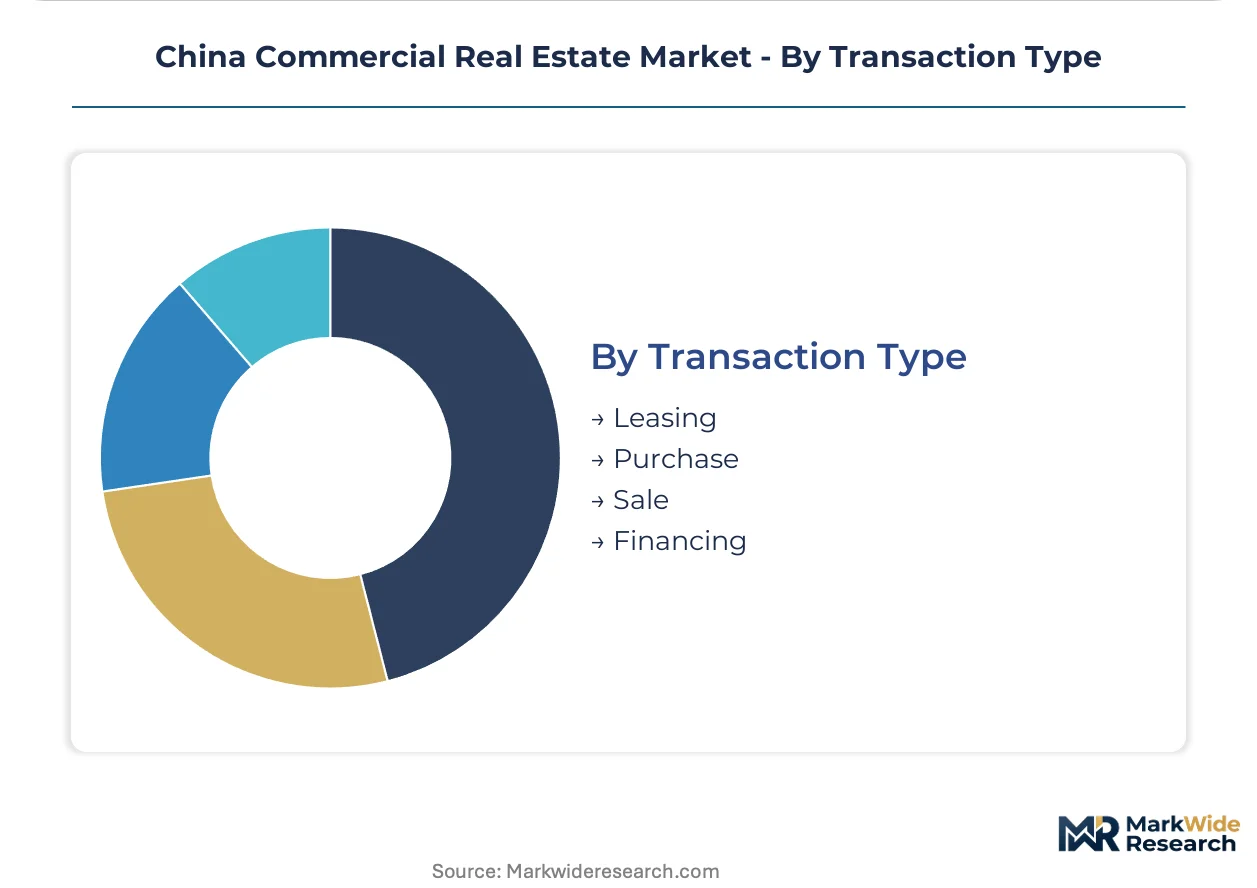
Transaction Type:
Deal mechanics align capital deployment with asset control, risk transfer, and financing optimization objectives.
- Leasing:Gross leases with efficiency clauses displace traditional net structures in Hangzhou logistics markets. Outcome-based utility contracts bundle base rent with guaranteed energy performance.
- Purchase:Asset acquisitions transfer full ownership and obsolescence risk to buyers. Due diligence timelines extend for pre-2015 stock facing curtain wall thermal performance gaps.
- Sale:Developer exit strategies monetize completed inventory to recycle capital. Asset-light operating models with third-party management contracts preserve fee streams post-divestiture.
- Financing:Construction and permanent debt facilities support development pipelines. Green building certification unlocks preferential terms from policy banks.
Leasing generates the highest transaction frequency, while Financing is climbing the fastest as green lending standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's commercial real estate sector exhibits pronounced regional variation, with capital deployment and absorption velocity diverging sharply between coastal hubs and interior growth corridors. Export-oriented manufacturing clusters in the east sustain logistics demand, while western infrastructure initiatives redirect development gravity inland.
Beijing-Tianjin-Hebei
State-owned enterprises and financial services tenants dominate Grade A office absorption in Beijing's core business districts. MEE dual carbon mandates enforce stricter energy efficiency disclosure for assets above 20,000 square meters. Tianjin's port-adjacent industrial zones attract cold-chain logistics investment from consumer goods distributors.
Yangtze River Delta
Shanghai's planning bureaus award floor-area-ratio incentives to developers achieving three-star green building certification. SAMR fire safety standards dictate material specifications for new curtain wall construction. Hangzhou's technology corridor accelerates smart building management system deployment across multi-tenant logistics facilities.
Pearl River Delta
Shenzhen's technology firms expand operational footprints at velocity outpacing national averages. MIIT data center directives concentrate hyperscale leasing demand in designated Guiyang and Ulanqab zones. The Greater Bay Area logistics infrastructure absorbs modern warehouse stock from e-commerce fulfillment networks.
Sichuan-Chongqing
Chengdu anchors western logistics hub development with high-clearance warehousing and automated racking systems. Local urban planning bureaus layer green building requirements atop national GB standards. Chongqing's manufacturing base generates sustained industrial property demand from automotive and electronics supply chains.
China Commercial Real Estate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The China commercial real estate market structures around state-backed developers with privileged land bank access, asset-light operators with third-party management platforms, and diversified conglomerates with cross-sector balance sheets. Competitive moves concentrate on portfolio diversification into logistics and data center assets, alongside strategic partnerships that decouple fee revenue from development cycles.
Within the state-backed tier, Poly Developments and Holdings Group Co. exemplifies entities leveraging provincial relationships for tier-two land access. China Vanke Co. occupies a position among asset-light operators extending property-as-a-service platforms. Longfor Group represents specialized retail mall operators sustaining differentiated tenant retention metrics.
| Leading Market Players |
|---|
| China Resources Land Ltd |
| Poly Developments and Holdings Group Co. |
| China Vanke Co. |
| Shanghai Zhangjiang Hi-Tech Park Development Co. |
| China Merchants Shekou Industrial Zone Holdings |
| Longfor Group |
| Greenland Group |
| Suzhou New District Hi-Tech Industrial Co.,Ltd |
| Wanda Group |
| Others |
Supply Flow & Price Mechanics
Cement and steel input concentration in Hebei and Shandong provinces feeds directly into margin compression for Grade A office developers in Beijing and Shanghai. Developers with captive supply arrangements through state-backed channels capture pricing power that spot-market buyers forfeit.
Pricing Analysis
Industrial OEM buyers anchor outcome-based utility contracts that bundle base rent with guaranteed energy performance. Three-star GB certification unlocks floor-area-ratio bonuses that justify rental escalators above conventional stock. Pricing pressure stems from reinforced concrete input volatility compressing development margins on new starts. Logistics operators show highest price sensitivity due to thin tenant margins, while trophy office assets in first-tier hubs retain pricing inelasticity.
Supply Chain Analysis
Upstream feedstock from domestic cement kilns, regional steel mills, and imported curtain wall glazing systems shapes construction cost trajectories. Hebei and Shandong dominate bulk material supply, while Guangdong concentrates specialized glazing fabrication. Single-source vulnerability runs through energy-intensive material processing exposed to MEE carbon intensity benchmarks. Distribution runs through developer-procurement teams with direct mill relationships, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China commercial real estate functions as a regulatory-moat market where MEE dual carbon enforcement and SAMR disclosure requirements entrench incumbents with compliance infrastructure. Switching costs for tenants seeking certified efficient stock lock in landlord pricing power.
For Market Incumbents: Build certification moats through accelerated three-star GB attainment ahead of national code propagation. Acquire pre-2015 assets with retrofit-ready envelopes before MEE benchmarks render them obsolete. State-backed developers leverage provincial land access to preempt prime parcel competition from balance-sheet-constrained rivals. For New Entrants and Emerging Players: Build out cold-chain logistics specialization in Chengdu-Chongqing corridor penetration zones. Target western logistics hubs where consumer goods distributors seek proximity to dense urban consumption zones. Deploy property-as-a-service platforms to decouple fee revenue from capital-intensive development cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed value-add specialists holding pre-2015 office stock requiring HVAC and envelope upgrades. Long-duration viability hinges on green lending standard proliferation from policy banks. Watch MEE carbon intensity pilot zone expansion as inflection indicator for national code adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Acceleration | Three-star GB attainment unlocks Beijing and Shanghai floor-area-ratio incentives before competitors. |
| Cold-Chain Logistics Infrastructure Buildout | Western corridor penetration captures consumer goods distributor demand migrating inland. |
| Property-as-a-Service Platform Launch | Third-party management contracts generate fee streams decoupled from development cycle volatility. |
| Retrofit-Ready Asset Acquisition | Pre-2015 stock with envelope upgrade pathways avoids MEE obsolescence risk concentration. |
| State-Backed Land Bank Partnership | Provincial relationships anchor tier-two parcel access against auction-competitive rivals. |
Methodological Framework
A spread of perspectives from property development executives, asset management directors, institutional investor portfolio managers, and urban planning bureau officials converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SAMR disclosure filings, MEE regulatory bulletins, provincial land auction records, and REIT distribution reports. Bottom-up lease transaction modeling and top-down capital deployment tracking were triangulated to anchor projections.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include property type, investment vehicle structure, client risk-return profile, and transaction mechanism. CAGRs were derived from absorption velocity trends and capital recycling patterns. Forecast inputs incorporated MIIT data center directive zone approvals and MEE carbon intensity pilot expansion schedules.
Stress conditions across cement-steel input volatility, MEE compliance timeline acceleration, and logistics tenant margin compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against provincial land auction clearance rates and REIT distribution coverage ratios is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market