
 Europe Commercial Real Estate Market | 2026-2036
Europe Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Real Estate Market Foresight
European logistics developers is restructuring warehouse supply around e-commerce fulfillment timelines. Vonovia SE leverages its residential-to-mixed-use conversion expertise to capture value in densifying German cities. Segro Plc anchors industrial development in Central and Eastern European markets with specialized big-box formats. Blackstone Inc. competes through scale-driven portfolio aggregation across logistics and last-mile nodes.
Europe Commercial Real Estate comprises income-producing property assets including office towers, retail centers, industrial warehouses, and mixed-use developments, typically valued through discounted cash flow models using net operating income capitalization rates between four and eight percent depending on asset class and location risk. The primary commercial purpose is to generate rental yield and capital appreciation for institutional and private capital deployers. Office stock in London and Paris retains the deepest liquidity pools, though industrial assets across the Investment Type dimension through REITs and private equity structures are capturing the fastest capital deployment growth as yield compression drives institutional rebalancing. Retail formats remain structurally challenged by channel shift, with margin pools concentrating in prime urban flagship locations and grocery-anchored neighborhood schemes.
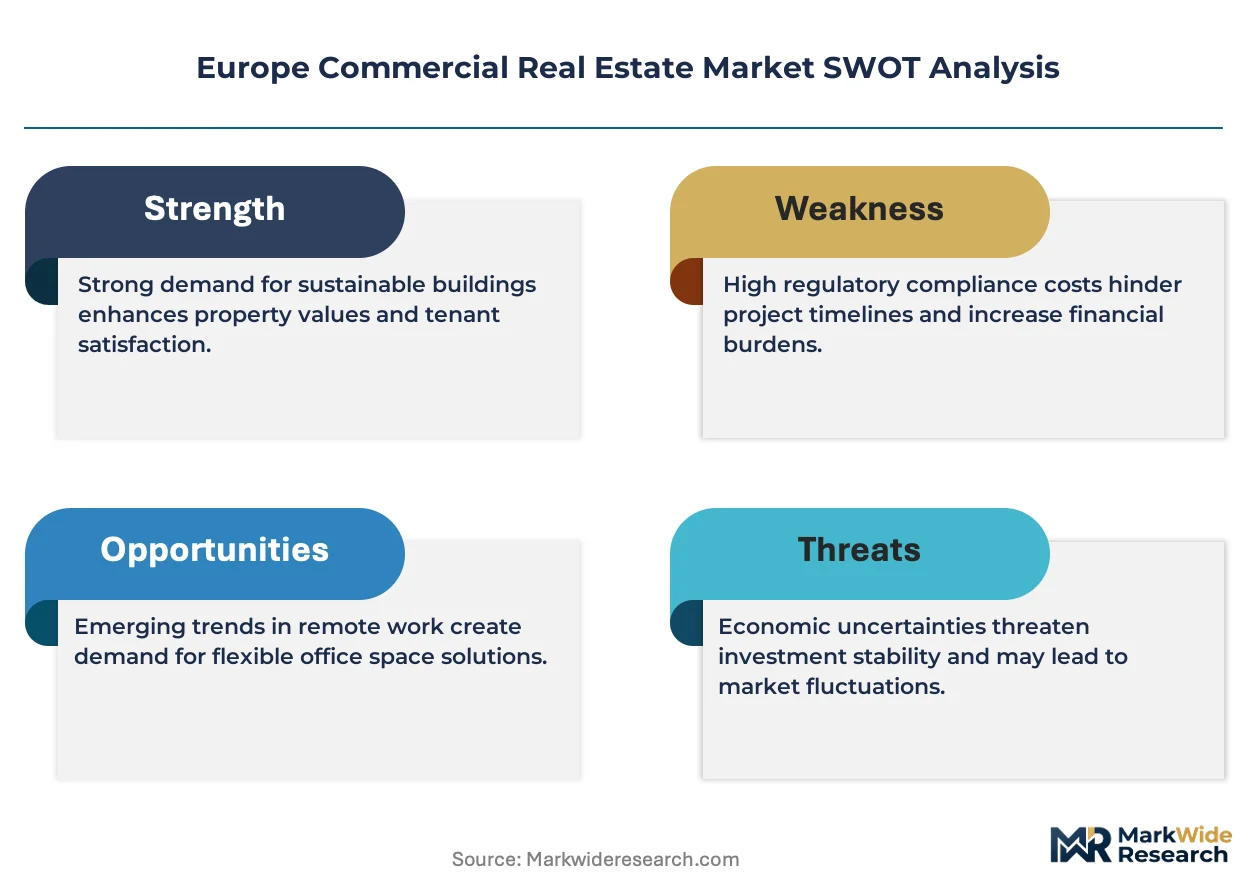
The EU Green Deal and Energy Performance of Buildings Directive are mandating minimum efficiency standards that reshape renovation timelines and obsolescence risk for pre-2000 stock. EMA frameworks for corporate sustainability reporting and CSRD disclosure requirements are forcing investors to quantify embodied carbon and transition risk in asset valuations. Stakeholders must monitor regulatory tightening on operational emissions thresholds and assess whether retrofit capital stacks can achieve compliance without eroding net operating income.
Market Dynamics
The EU Green Deal and Energy Performance of Buildings Directive are compressing renovation timelines for pre-2000 commercial stock, forcing asset owners to front-load capital expenditure or face accelerated obsolescence.
Growth Catalysts
- Last-mile logistics densification:E-commerce fulfillment operators are expanding warehouse footprints in Germany's Ruhr corridor and Poland's Łódź manufacturing belt to meet delivery compression timelines.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are redirecting institutional capital toward assets with verified operational carbon data and transition-risk quantification.
- Residential-to-mixed-use conversions:Urban densification policies in German and Dutch cities are unlocking value-capture opportunities through zoning flexibility and transit-oriented development incentives.
Market Restraints
- Construction input cost volatility:Steel and concrete price fluctuations are destabilizing development pro formas across Central European industrial projects.
- Debt market liquidity concentration:Commercial mortgage availability has compressed in London and Frankfurt, elevating refinancing risk for floating-rate exposure.
- Technical retrofit limitations:Heritage-protected office stock in Paris and Vienna faces irreconcilable tension between preservation mandates and envelope-deep efficiency upgrades.
Strategic Opportunities
- Underpenetrated CEE logistics nodes:Hungary and Romania offer yield expansion for big-box development adjacent to automotive supplier clusters.
- EU AI Act compliance infrastructure:Smart building systems integrating predictive maintenance and energy optimization command rental premiums in Amsterdam and Stockholm.
- Brown-to-green capital stack innovation:Green bond issuance and sustainability-linked loans are reducing weighted average cost of capital for certified retrofit pipelines.
Industry Challenges
- Building physics skill scarcity:Deep retrofit project management and embodied carbon accounting expertise remains concentrated among a limited pool of specialist consultants.
- Legacy system integration friction:Property management platforms and tenant experience applications require costly middleware development to interface with 1990s-era building automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Real Estate Market |
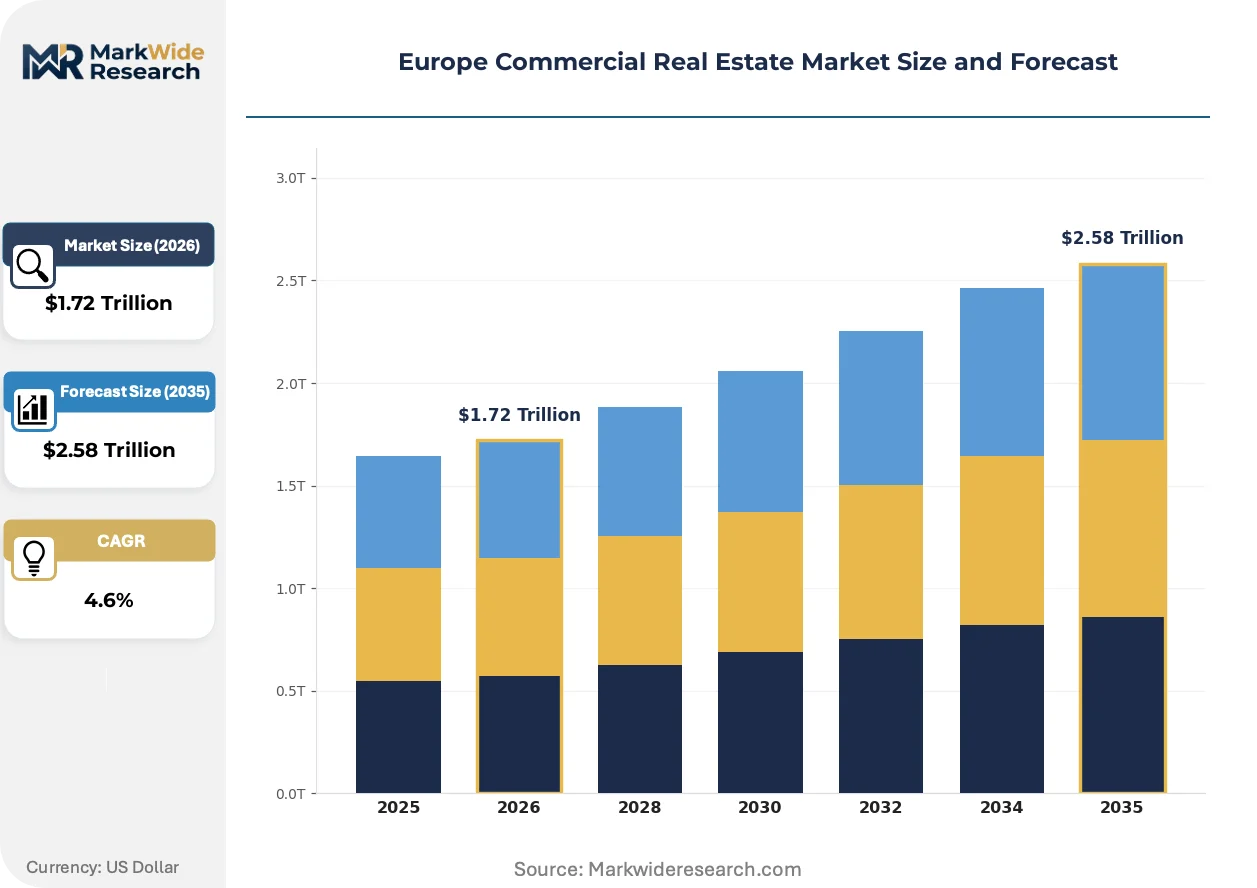
| Market Size in 2026 | $1.72 Trillion |
| Market Size in 2035 | $2.58 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Type: Direct Investment, REITs, Private Equity, Joint Ventures End User: Corporations, Investors, Tenants, Developers Transaction Size: Small, Medium, Large, Mega |
| Companies Covered | Vonovia SE, CBRE Group Inc., Blackstone Inc., Hines, Savills Plc, Jones Lang LaSalle Inc., Covivio, Segro Plc, Cushman & Wakefield Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Real Estate Market Shifts & Advancements
Digital twin technology and predictive analytics are compressing asset management cost structures while regulatory disclosure frameworks are standardizing environmental performance data across institutional portfolios.
Building information modeling integrated with IoT sensor networks is consolidating operational oversight across multi-asset portfolios. Logistics operators in the Netherlands and Belgium are deploying these systems to optimize warehouse energy consumption and predictive maintenance scheduling. The structural consequence is compressing facility management headcount while elevating data-driven lease negotiation positions.
Revised Energy Performance of Buildings Directive enforcement timelines are mandating minimum efficiency thresholds for commercial lease renewals. Asset owners in France and Germany must achieve Class A certification or face rental restrictions and valuation haircuts. Industrial assets with clear retrofit pathways are capturing capital deployment preference over office stock with ambiguous compliance trajectories.
Tenant sustainability requirements are displacing traditional lease structures with performance-linked agreements. Corporate occupiers in London and Munich now embed operational carbon clauses and renewable energy procurement obligations into long-term contracts. Logistics and life sciences verticals exhibit the most aggressive sustainability-driven procurement compression timelines.
Europe Commercial Real Estate Market Segmentation
Segmentation clarity determines capital allocation precision across Europe's heterogeneous property markets. Asset-specific risk profiles, ownership structures, and transaction scales each demand distinct underwriting frameworks and liquidity assumptions.
Property Type:
Standalone assets trade as pure-play exposures, while mixed-use developments embed diversification within single structures.
- Office:Central business district towers in London and Paris command premium rents but face hybrid work absorption uncertainty. Class A stock with flexible floorplates attracts life sciences and tech tenants seeking ESG-compliant space.
- Retail:Prime urban flagship locations retain pricing power against channel shift erosion. Grocery-anchored neighborhood schemes offer defensive income streams as experiential formats struggle with footfall volatility.
- Industrial:Logistics corridors near Germany's Ruhr and Poland's Łódź manufacturing belt concentrate last-mile fulfillment demand. Big-box formats with clear height specifications and cross-dock configurations dominate institutional deployment.
- Mixed-Use:Transit-oriented developments in Dutch and German cities combine residential, office, and retail components. Zoning flexibility and density bonuses unlock value capture unavailable to single-use assets.
Volume placements concentrate in Industrial; the faster expansion belongs to Mixed-Use.
Investment Type:
Cost tier stratification separates fee-heavy indirect vehicles from capital-intensive direct ownership.
- Direct Investment:Sovereign wealth funds and pension schemes acquire trophy assets for yield stability. Bilateral negotiations in Frankfurt and Amsterdam bypass auction premiums but require dedicated asset management infrastructure.
- REITs:Exchange-traded vehicles offer retail and institutional liquidity with regulatory disclosure discipline. Segro Plc and Vonovia SE structures dominate European listed exposure to logistics and residential-conversion themes.
- Private Equity:Value-add and opportunistic strategies target mispriced assets with clear retrofit or repositioning pathways. Closed-end fund structures align manager incentives with compressed hold periods.
- Joint Ventures:Risk-sharing arrangements pair capital providers with local development expertise. CEE logistics projects frequently deploy this structure to navigate permitting complexity and construction input volatility.
Capital flow depth favors Direct Investment; the steepest expansion trajectory sits with Private Equity.
End User:
Customer type determines lease structure rigidity and covenant strength across negotiation tables.
- Corporations:Occupier-led acquisitions concentrate in headquarters consolidation and embedded real estate on balance sheets. Sustainability-linked lease clauses now standard in Munich and London negotiations.
- Investors:Yield-focused institutions prioritize long-dated income streams with inflation linkage. Core-plus strategies target assets with 5-15% value-add upside through active management.
- Tenants:User requirements increasingly specify smart building integration and operational carbon thresholds. Logistics operators demand predictive maintenance infrastructure and energy optimization systems.
- Developers:Merchant build-to-core strategies bridge construction risk to institutional takeout. Pre-leasing commitments from e-commerce fulfillment operators de-risk speculative industrial development.
Transaction frequency peaks with Investors; the most rapid profile evolution belongs to Tenants.
Transaction Size:
Deal scale dictates buyer universe breadth and execution timeline compression.
- Small:Sub-€10 million assets attract private wealth and family office capital. Due diligence standardization remains limited, creating information asymmetry for specialized operators.
- Medium:€10-100 million range captures the deepest institutional liquidity outside trophy markets. Portfolio aggregation strategies target this segment for diversification without complexity premiums.
- Large:€100-500 million deals require consortium formation or balance sheet capacity. Blackstone Inc. and comparable platforms compete through scale-driven underwriting and execution certainty.
- Mega:€500 million-plus transactions concentrate in London and Paris office towers. Sovereign and pension capital dominates, with extended closing timelines reflecting governance and regulatory clearance requirements.
Market clearing volume clusters in Medium; the sharpest competition intensity sits with Mega.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German construction-grade limestone deposits anchor Central European cement and concrete supply chains for commercial development. Polish hard coal basins feed regional energy-intensive materials production. Scandinavian timber reserves supply cross-laminated lumber for low-carbon building envelopes.
Germany
Logistics corridor densification along the Rhine-Ruhr axis and residential conversion pipelines in Berlin and Munich concentrate institutional deployment. The revised Energy Performance of Buildings Directive mandates operational efficiency thresholds for lease renewals. Frankfurt's banking district faces Class A office obsolescence pressure as retrofit capital stacks compete with new development yields.
United Kingdom
Life sciences absorption in Cambridge and Oxford clusters and last-mile fulfillment expansion around the Midlands Golden Triangle drive sectoral demand. CSRD disclosure requirements redirect pension capital toward assets with verified carbon data. London's Canary Wharf and City submarkets exhibit bifurcated liquidity between prime and secondary office stock.
France
Corporate headquarters consolidation in La Défense and logistics node development in the Paris Basin attract yield-focused institutions. The EU Green Deal's decarbonization mandates compress renovation timelines for pre-2000 commercial stock. Lyon and Marseille industrial zones concentrate big-box development adjacent to Mediterranean port infrastructure.
Netherlands
Smart building integration in Amsterdam and Rotterdam port-adjacent logistics commands rental premiums from sustainability-driven tenants. EMA frameworks for corporate sustainability reporting standardize environmental performance disclosure across institutional portfolios. Eindhoven's technology corridor anchors mixed-use transit-oriented development with density bonuses.
Poland
Manufacturing-adjacent industrial zones around Łódź and Wrocław capture automotive supplier clustering and e-commerce fulfillment demand. EU structural funds finance infrastructure connectivity for Central European logistics networks. Warsaw's office market exhibits yield expansion relative to Western European capitals as capital deployment shifts eastward.
Europe Commercial Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized logistics formats and residential conversion expertise. The market structure consolidates around scale-driven portfolio aggregators, integrated development-service platforms, and niche specialists in sustainability-linked asset management. Three archetypes dominate: diversified real estate investment trusts with mixed-use conversion capabilities, private equity platforms with value-add retrofit pipelines, and advisory-led service providers with transaction execution scale. Competitive intensity centers on M&A-driven portfolio aggregation and sustainability certification differentiation.
Within the listed REIT tier, Vonovia SE exemplifies residential-to-mixed-use conversion specialization, while Segro Plc anchors industrial development in Central and Eastern European logistics corridors. Blackstone Inc. occupies the private equity archetype with scale-driven deployment across last-mile nodes. CBRE Group Inc. and Jones Lang LaSalle Inc. represent the advisory-service vector with integrated capital markets and property management capabilities.
| Leading Market Players |
|---|
| Vonovia SE |
| CBRE Group Inc. |
| Blackstone Inc. |
| Hines |
| Savills Plc |
| Jones Lang LaSalle Inc. |
| Covivio |
| Segro Plc |
| Cushman & Wakefield Plc |
| Others |
Supply & Pricing Matrix
Digital twin integration and predictive maintenance systems are compressing facility management cost structures while simultaneously concentrating procurement leverage among technology-enabled asset operators. The EU Green Deal's decarbonization mandates are reshaping capital stack economics as retrofit compliance costs feed into lease rate negotiations and yield compression calculations across institutional portfolios.
Pricing Analysis
Service bundling separates core rent from sustainability certification premiums and smart building technology packages. Three-tier pricing structure across premium Class A certified, standard compliant, and economy pre-2000 stock reflects Energy Performance of Buildings Directive enforcement timelines. Pricing pressure stems from yield compression as institutional capital chases limited green-certified supply. Corporate occupiers in London and Munich exhibit lowest price sensitivity for ESG-compliant space, while secondary office landlords face tenant retention challenges.
Supply Chain Analysis
Direct-to-institutional channels handle sovereign wealth and pension fund deployment at scale, while joint venture structures serve CEE logistics development. German limestone deposits and Polish hard coal basins anchor cement and energy-intensive materials production. Scandinavian timber reserves feed cross-laminated lumber demand for low-carbon envelopes. Single-source vulnerability concentrates in construction-grade steel from integrated European mills. Distribution runs through bilateral negotiations for trophy assets and auction processes for portfolio aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal and Energy Performance of Buildings Directive have erected a cost-of-compliance barrier that rewards early retrofit capital deployment and penalizes legacy stock obsolescence. CSRD disclosure requirements compound this moat by mandating verified carbon data that only compliant players can supply.
For Market Incumbents: Lock in tenant relationships through long-term sustainability-linked lease structures that embed operational carbon clauses and renewable energy procurement obligations. Accelerate Class A certification pipelines in Frankfurt and Paris office submarkets before regulatory deadlines restrict rental income from pre-2000 stock. Threat of capital flight to certified assets demands proactive retrofit scheduling. For New Entrants and Emerging Players: Capture underpenetrated logistics nodes in Hungary and Romania where yield expansion persists adjacent to automotive supplier clusters. Target brownfield industrial assets with clear envelope-deep retrofit pathways rather than competing for prime greenfield development sites. Go-to-market leverage rests on sustainability-linked loan access that reduces weighted average cost of capital below incumbent legacy financing. For Investors and Strategic Acquirers: Exit pathways concentrate in platform sales to diversified REITs seeking ESG-compliant income streams and private equity rollup strategies targeting fragmented CEE logistics. Long-term viability favors assets with unambiguous compliance trajectories and verified operational carbon data. Signal to watch is regulatory tightening on embodied carbon thresholds that would revalue retrofit capital requirements across pre-2010 stock.| Strategic Initiative | Industry Significance |
|---|---|
| Green Bond Issuance | Reduces financing costs for certified retrofit pipelines under EU Green Deal frameworks. |
| Residential-to-Mixed-Use Conversion | Unlocks density bonuses and zoning flexibility in German and Dutch urban cores. |
| Smart Building Integration | Commands rental premiums in Amsterdam and Stockholm through predictive maintenance systems. |
| CEE Logistics Expansion | Captures yield expansion in Hungary and Romania adjacent to automotive clusters. |
| CSRD Compliance Infrastructure | Enables institutional capital access through verified operational carbon disclosure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Commercial Real Estate analysis. Primary interviews with asset managers, development directors, sustainability consultants, and institutional investment officers triangulated against EMA disclosure databases, EU structural fund allocations, and national energy performance registries. Bottom-up lease transaction aggregation and top-down capital flow tracking reconciled across the analysis window.
Data-stream reconciliation across property type, investment vehicle, end-user category, and transaction size dimensions informed the modeling framework. CAGRs derived from discounted cash flow valuations using net operating income capitalization rates varying by asset class and location risk. Forecast inputs incorporated Energy Performance of Buildings Directive enforcement timelines, e-commerce fulfillment demand projections, and CSRD disclosure adoption curves.
The model holds under stable regulatory enforcement schedules and sustained institutional capital deployment; deviation in interest rate trajectories or construction input cost volatility would shift yield compression assumptions. Forecasts reflect documented base conditions with sensitivity to macroeconomic and policy triggers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market