
 India Commercial Real Estate Market | 2026-2036
India Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
India Commercial Real Estate Market Outlook
Bengaluru is tilting toward institutional-grade office absorption as India's technology corridor matures. DLF Limited anchors its competitive position through integrated township developments across the National Capital Region. Embassy Office Parks leverages its REIT platform to sustain recurring income visibility for institutional investors. Godrej Properties differentiates through green-certified developments that command rental premiums in Mumbai and Pune.
India commercial real estate encompasses income-generating properties including office towers, retail centers, industrial warehouses, and hospitality assets, typically developed with floor plates exceeding 25,000 square feet and built to seismic zone compliance standards. Office property type leads absolute absorption volumes, though industrial segments are recording the fastest lease velocity as e-commerce fulfillment networks expand. REITs as an investment type concentrate institutional capital flows into stabilized assets, while direct investment still dominates development-stage risk capital. Joint ventures between domestic developers and global funds now occupy the primary channel for large-scale project financing.
RERA mandates at the state level, BIS structural codes, and municipal development control regulations collectively shape project viability timelines and buyer protection standards. SEBI's REIT guidelines determine minimum asset sizes and distribution requirements that filter developer eligibility. Stakeholders must monitor how state-level land pooling policies and infrastructure corridor announcements redirect sub-market demand across India's metropolitan hierarchy.
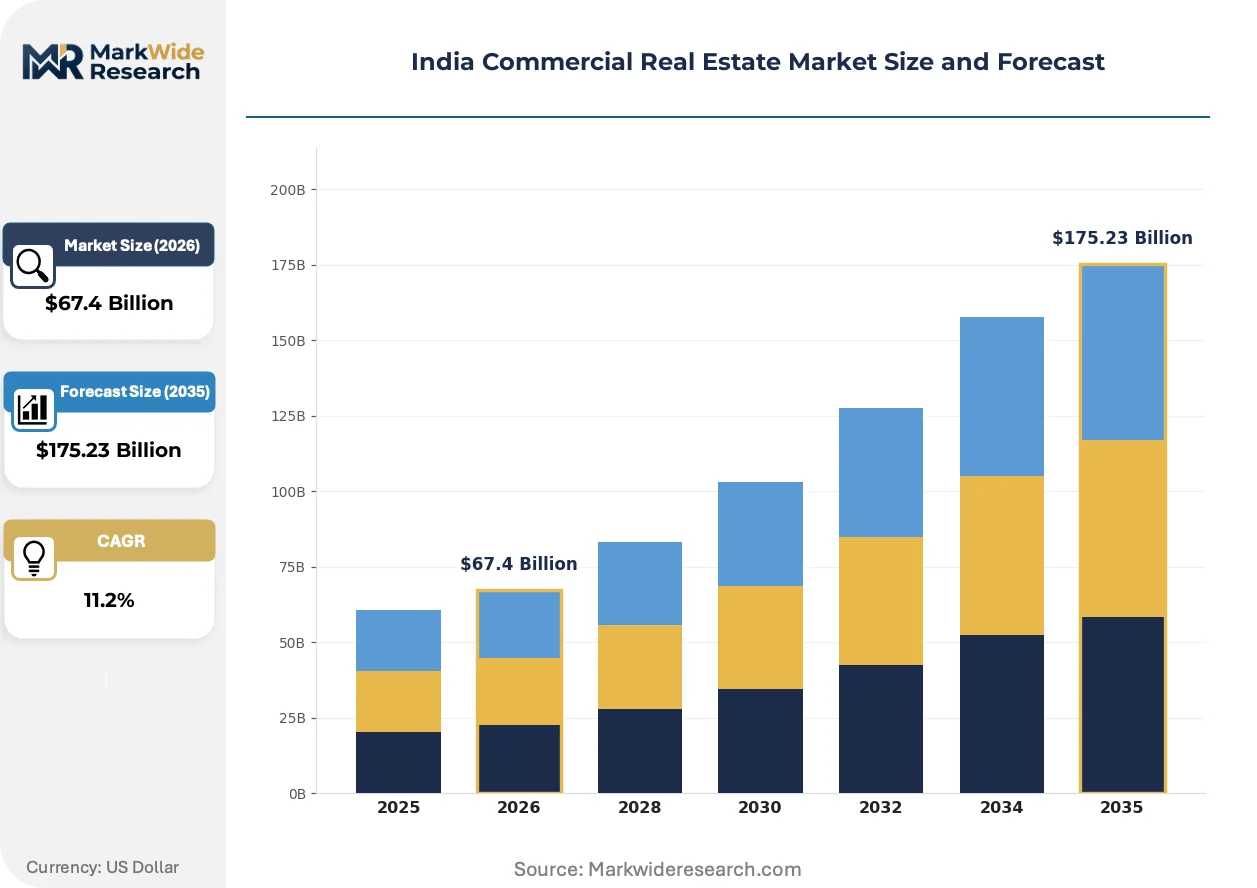
Market Dynamics
Institutional capital flows are compressing yield spreads across Grade-A office assets as SEBI's REIT guidelines mature and foreign portfolio investors deepen commitments to stabilized income streams. This capital reallocation is restructuring developer financing hierarchies and accelerating asset-level consolidation in Mumbai, Bengaluru, and Hyderabad.
Growth Catalysts
- PLI scheme incentives:Manufacturing-linked production incentives are expanding industrial land absorption in Pune and Chennai corridors as contract electronics and automotive suppliers establish captive facilities.
- Technology sector leasing:Bengaluru and Hyderabad technology campuses are driving floor plate expansion above 50,000 square feet as hybrid work protocols stabilize at three-days-in-office norms.
- Smart Cities Mission:Integrated infrastructure deployments across 100 urban centers are unlocking greenfield development zones with pre-certified utility connectivity and transit access.
Market Restraints
- State-level RERA fragmentation:Maharashtra, Karnataka, and Telangana operate divergent approval timelines and escrow requirements, creating compliance complexity for multi-city developers.
- Construction input volatility:Structural steel and cement price swings compress margin visibility on 24-36 month development cycles, particularly in secondary metropolitan markets.
- Land title opacity:Agricultural-to-commercial conversion disputes in peri-urban Gujarat and Rajasthan delay site possession by 8-14 months beyond scheduled timelines.
Strategic Opportunities
- Industrial REIT formation:SEBI's minimum asset size thresholds for warehousing and logistics parks remain unmet by most developers, creating first-mover structuring advantages for platform operators.
- Tier-II city penetration:Coimbatore, Indore, and Chandigarh exhibit sub-12% Grade-A office stock penetration relative to working-age professional populations.
- Green certification premiums:IGBC and GRIHA-rated buildings command 8-15% rental escalations in Mumbai and Pune as occupier ESG mandates harden.
Industry Challenges
- Project management talent scarcity:Quantity surveying and construction technology integration skills remain concentrated in Mumbai and Delhi-NCR, constraining execution velocity in emerging markets.
- Legacy lease rollover exposure:2017-2019 vintage nine-year leases with 5% annual escalations face repricing gaps against current 9-11% market rents, forcing capital expenditure negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Commercial Real Estate Market |
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $175.23 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Type: Direct Investment, REITs, Crowdfunding, Joint Ventures End User: Corporates, Startups, Investors, Government Development Stage: Pre-Construction, Under Construction, Completed, Renovation |
| Companies Covered | Prestige Estate Projects, Mindspace Business Parks, DLF Limited, Indiabulls Real Estate, Brookfield India REIT, Godrej Properties, Embassy Office Parks, RMZ Corp, Oberoi Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Commercial Real Estate Market Strategic Shifts
Physical-digital convergence in asset management is compressing operating expenditure structures and enabling predictive maintenance protocols across institutional portfolios. Three developments are restructuring competitive positioning.
Building operating systems are collapsing traditional facilities management cost structures through IoT-enabled energy optimization and automated tenant experience platforms. Large technology occupiers in Hyderabad and Pune are mandating smart building certifications as lease preconditions, forcing landlord capital deployment into sensor infrastructure and edge computing nodes.
SEBI's 2023 amendments to REIT investment guidelines have expanded eligible asset categories to include data centers and healthcare facilities, broadening institutional capital deployment channels beyond traditional office and retail formats. This regulatory expansion is accelerating sponsor platform formation as developers seek to monetize stabilized cash flows rather than pursue outright asset sales.
Flexible lease structures are displacing conventional long-term commitments in Mumbai and Bengaluru technology corridors as occupiers demand contraction options and capital-light expansion rights. Landlords are responding with managed space partnerships and revenue-sharing arrangements that transfer demand volatility risk while capturing premium effective rents on utilized space.
India Commercial Real Estate Market Segmentation
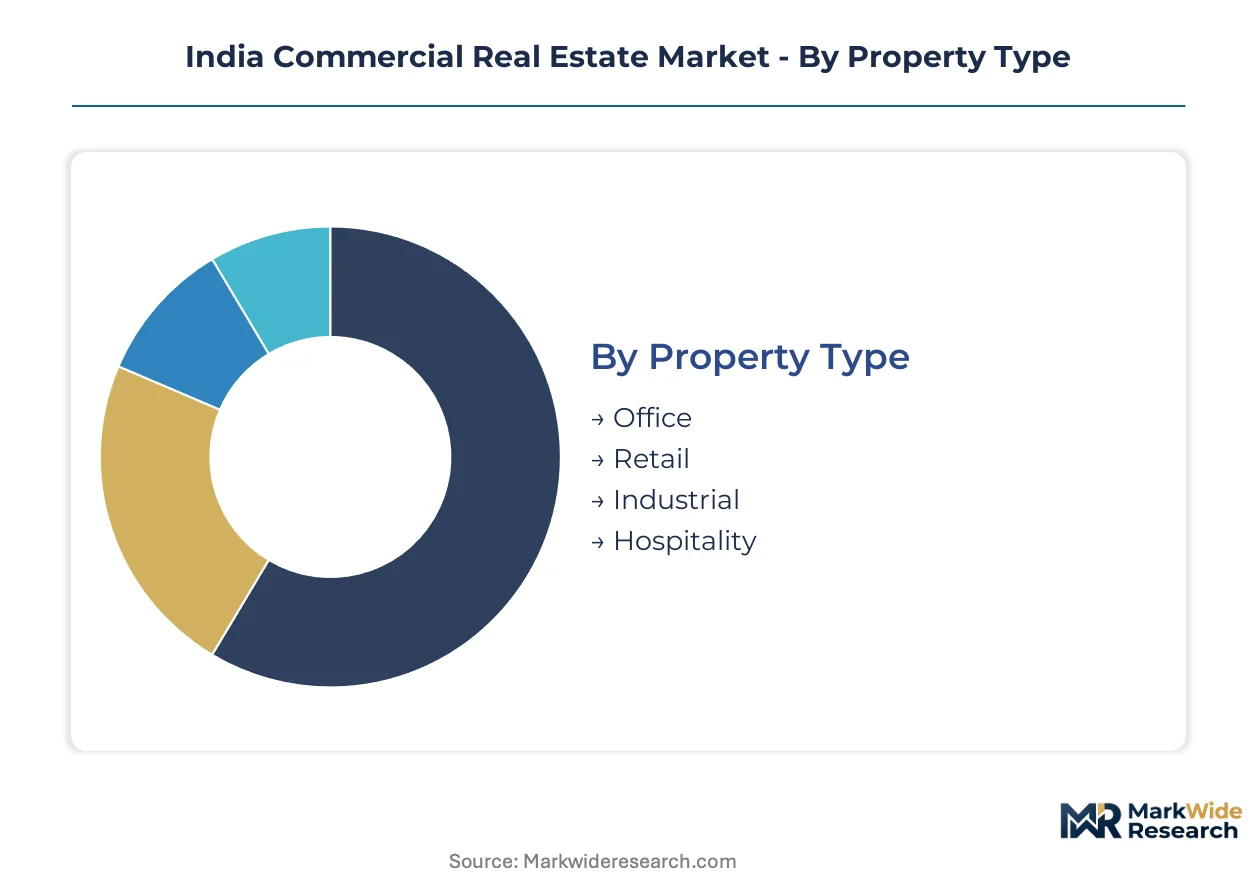
Segmentation in Indian commercial real estate reveals how capital formation, risk appetite, and development timelines intersect across asset classes. Each dimension exposes distinct liquidity profiles and regulatory exposure that reshape portfolio construction strategies.
Property Type:
Mature segments anchor institutional capital deployment while emerging formats capture structural demand shifts from e-commerce and hybrid work protocols.
- Office:Grade-A towers exceeding 25,000 square feet dominate absorption volumes in Bengaluru, Hyderabad, and Pune as technology firms consolidate floor plates above 50,000 square feet. SEBI's REIT guidelines have compressed yield spreads on stabilized assets, redirecting development risk capital toward pre-leased structures.
- Industrial:Warehousing and logistics parks are recording the fastest lease velocity as contract electronics manufacturers under PLI schemes establish captive facilities in Pune and Chennai corridors. Land title opacity in peri-urban zones remains the primary constraint on site possession timelines.
- Retail:Organized shopping centers face repricing pressure from experiential format migration, with Mumbai and Delhi-NCR landlords retrofitting anchor tenant mixes toward F&B and entertainment.
- Hospitality:Business hotels and serviced apartments concentrate in transit corridors near emerging airport infrastructure, though foreign direct investment restrictions limit branded operator penetration.
Office retains volume leadership; Industrial holds the steepest expansion curve.
Investment Type:
Capital channel selection determines liquidity horizons and governance complexity, with institutional vehicles displacing direct ownership for stabilized assets.
- Direct Investment:Development-stage risk capital flows through promoter equity and structured debt, concentrated in Mumbai and Delhi-NCR where land aggregation costs exceed secondary market thresholds. BIS structural codes and municipal development control regulations shape project viability timelines.
- REITs:SEBI's 2023 amendments expanded eligible assets to data centers and healthcare facilities, broadening sponsor platform formation beyond traditional office formats. Embassy Office Parks and Mindspace Business Parks REITs anchor institutional liquidity for Grade-A portfolios.
- Joint Ventures:Domestic developers partner with global funds for large-scale project financing, transferring construction risk while retaining operational control. These structures now occupy the primary channel for greenfield township developments.
- Crowdfunding:Fragmented regulatory treatment across state-level RERA implementations limits retail participation, confining activity to accredited investor pools in technology corridors.
Direct Investment maintains capital deployment dominance; REITs are climbing the fastest as distribution requirements mature.
End User:
Occupier category shapes lease structure preferences, with technology mandates forcing landlord capital deployment into smart building infrastructure.
- Corporates:Multinational technology and financial services firms drive Grade-A absorption, mandating IGBC and GRIHA certifications as lease preconditions in Mumbai and Pune. Three-days-in-office hybrid protocols have stabilized at floor plate configurations above 50,000 square feet.
- Startups:Flexible lease structures with contraction options and revenue-sharing arrangements displace conventional long-term commitments in Bengaluru and Hyderabad. Managed space partnerships transfer demand volatility risk while capturing premium effective rents.
- Investors:Institutional capital concentrates in stabilized income streams, with foreign portfolio investors deepening commitments as SEBI guidelines mature.
- Government:Smart Cities Mission deployments across 100 urban centers unlock greenfield zones with pre-certified utility connectivity, though procurement timelines extend 18-24 months beyond private sector equivalents.
Corporates retain volume leadership; Startups are gaining share fastest through flexible workspace adoption.
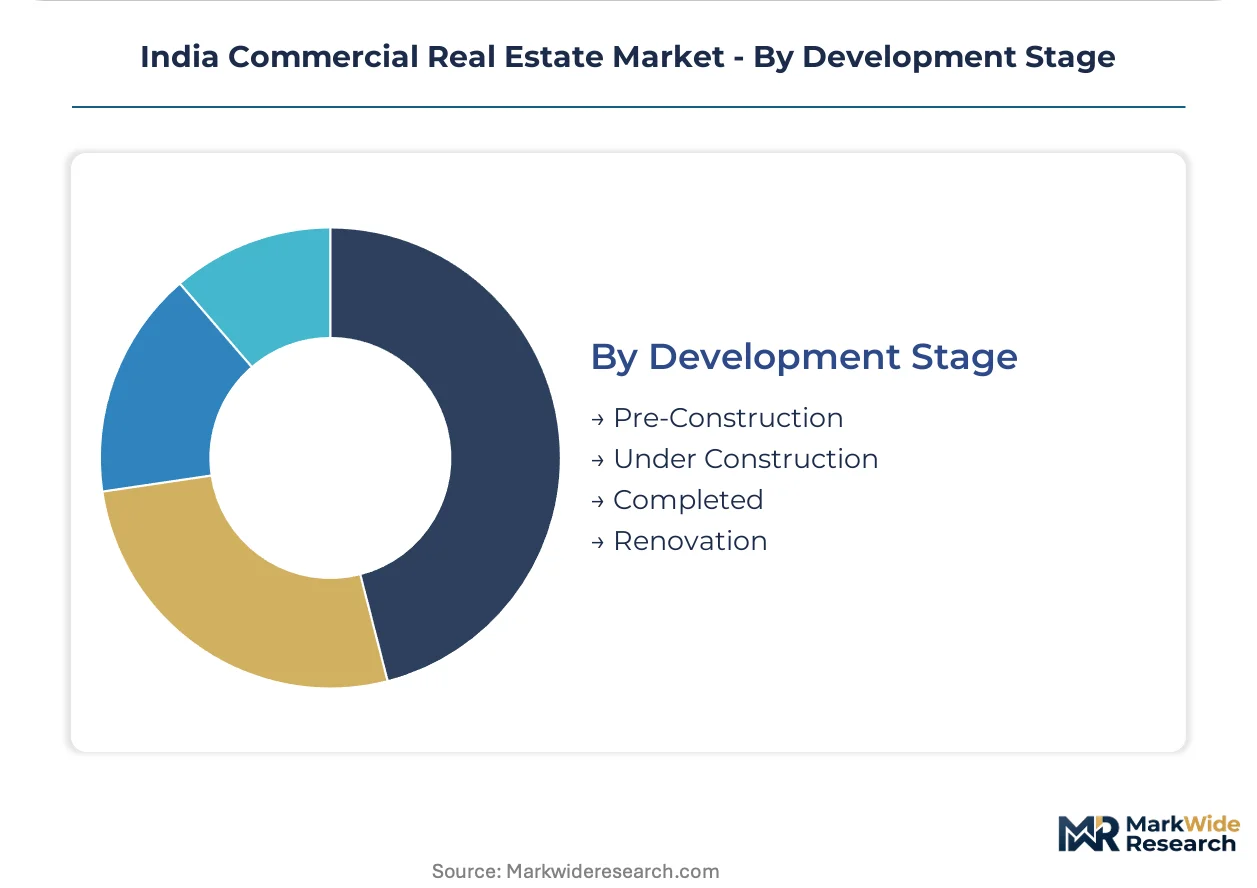
Development Stage:
Risk-return profiles stratify sharply across construction timelines, with input price volatility compressing margin visibility on 24-36 month cycles.
- Pre-Construction:Land aggregation and approval navigation dominate capital allocation, with agricultural-to-commercial conversion disputes in Gujarat and Rajasthan delaying possession 8-14 months beyond schedule. State-level RERA fragmentation creates compliance complexity for multi-city developers.
- Under Construction:Structural steel and cement price swings expose margin pressure, particularly in secondary metropolitan markets where contractor credit terms are less favorable. Quantity surveying and construction technology integration skills remain concentrated in Mumbai and Delhi-NCR.
- Completed:Stabilized assets command institutional capital at compressed yields, with 2017-2019 vintage nine-year leases facing repricing gaps against current market rents.
- Renovation:Legacy stock retrofitting for green certification and smart building compliance attracts ESG-mandated capital, though tenant displacement costs constrain feasibility in rent-controlled districts.
Completed assets retain volume leadership; Under Construction positions hold the steepest expansion curve as development pipelines reactivate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's commercial real estate consumption varies sharply across its economic geography, with western and southern metros absorbing institutional-grade office stock while northern markets prioritize integrated township formats and emerging industrial corridors.
Maharashtra
Financial services and banking headquarters drive Grade-A office absorption in Mumbai's Bandra-Kurla Complex and Lower Parel corridors. SEBI's REIT guidelines have compressed yield spreads on stabilized assets here more than any other state. The Mumbai Metropolitan Region anchors institutional capital deployment, with developers retrofitting legacy stock for smart building compliance.
Karnataka
Technology sector leasing dominates absorption volumes as global capability centers expand floor plates beyond 50,000 square feet. The state's RERA implementation mandates stricter escrow requirements than western counterparts, extending approval timelines. Bengaluru's Outer Ring Road and Whitefield clusters concentrate hybrid-work campus developments with three-days-in-office protocols now standard.
Telangana
Life sciences and pharmaceutical R&D facilities are diversifying demand beyond pure technology plays. Hyderabad's state-level land pooling policies unlock greenfield zones faster than Maharashtra's conversion procedures. The Gachibowli and HITEC City corridors command rental premiums for IGBC-certified buildings as occupier ESG mandates harden.
Tamil Nadu
PLI scheme incentives for contract electronics manufacturing are accelerating industrial land absorption in Sriperumbudur and Oragadam corridors. The state's BIS structural code enforcement for seismic zone compliance shapes project viability timelines distinct from northern markets. Chennai's peripheral warehousing markets exhibit the fastest lease velocity nationally as e-commerce fulfillment networks expand.
National Capital Region
Government procurement under Smart Cities Mission deployments creates demand for transit-oriented commercial formats. Haryana and Uttar Pradesh sub-regions operate divergent RERA approval timelines from Delhi's municipal controls. Gurugram's DLF Cyber City and Noida's sector-specific industrial parks concentrate joint venture structures between domestic developers and global funds.
India Commercial Real Estate Market Competitive Environment
Capability concentration sits with integrated township developers holding land banks across multiple metros; scale advantage sits with REIT-sponsored platforms monetizing stabilized income streams. The market structures around three tiers: diversified conglomerates with residential-commercial-industrial exposure, pure-play office specialists with institutional joint ventures, and emerging industrial platform operators. Dominant competitive moves include portfolio diversification into data centers and healthcare facilities under SEBI's expanded guidelines, and geographic expansion into Tier-II cities with sub-12% Grade-A office penetration.
Within the REIT-sponsored tier, Embassy Office Parks and Mindspace Business Parks exemplify institutional-grade platform operators with recurring income visibility. DLF Limited anchors the diversified conglomerate archetype through integrated developments spanning residential, commercial, and retail formats. Godrej Properties occupies a position within the sustainability-differentiated segment, with green-certified developments commanding rental premiums in Mumbai and Pune. These three entities collectively represent the competitive positioning spectrum: income-stabilized vehicles, diversified land-bank holders, and ESG-mandated premium developers.
| Leading Market Players |
|---|
| Prestige Estate Projects |
| Mindspace Business Parks |
| DLF Limited |
| Indiabulls Real Estate |
| Brookfield India REIT |
| Godrej Properties |
| Embassy Office Parks |
| RMZ Corp |
| Oberoi Realty |
| Others |
Value Chain & Pricing Dynamics
Structural steel and cement production clusters in Chhattisgarh, Odisha, and Karnataka feed directly into margin compression dynamics for developers in secondary metropolitan markets. Input cost volatility on 24-36 month development cycles concentrates pricing power with contractors holding forward-contracted material positions.
Pricing Analysis
Long-term offtake agreements dominate Grade-A office developments as institutional investors pre-lease floor plates above 50,000 square feet before construction commencement. Price differentiation hinges on IGBC/GRIHA certification tier and seismic zone compliance grade, with green-certified assets commanding rental escalations in Mumbai and Pune. Pricing pressure stems from legacy lease rollover exposure as 2017-2019 vintage nine-year leases face repricing gaps against current market rents. Startups and flexible workspace operators exhibit highest price sensitivity, while multinational technology firms prioritize certification premiums over absolute rent levels.
Supply Chain Analysis
India's dual-use technology controls on construction management software and IoT sensor platforms limit vendor diversification for smart building deployments. Geographic supply concentration centers on China for HVAC equipment, Germany for elevator systems, and domestic sources for structural steel and ready-mix concrete. Raw material dependencies include structural steel rebar, Portland cement, and aluminum facade systems. Single-source vulnerability runs through specialized MEP contractors concentrated in Mumbai and Delhi-NCR. Distribution runs through project-specific procurement channels with developer-led aggregation of subcontractor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Project management talent scarcity constrains execution velocity, with quantity surveying and construction technology integration skills concentrated in Mumbai and Delhi-NCR while demand expands across Tier-II corridors.
For Market Incumbents: Insulate stabilized income streams by accelerating asset-level consolidation into REIT-sponsored platforms before SEBI's minimum asset thresholds tighten further. Deepen vertical control over smart building infrastructure deployment to capture tenant experience premiums. Defend against flexible workspace operators by embedding managed space partnerships within core lease structures. For New Entrants and Emerging Players: Build out industrial platform operations in Chennai and Pune corridors where PLI scheme incentives are accelerating captive facility demand ahead of warehousing REIT formation. Target land aggregation in peri-urban Gujarat and Rajasthan where agricultural-to-commercial conversion disputes have delayed incumbent timelines. Pursue joint venture structures with global funds to transfer construction risk while retaining operational control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic developers holding 2017-2019 vintage stabilized office portfolios facing near-term lease rollover exposure. Long-term viability favors platforms with recurring income visibility across multiple metropolitan markets. Monitor state-level RERA harmonization progress as inflection indicator for multi-city developer scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Program | IGBC and GRIHA ratings command 8-15% rental premiums in Mumbai and Pune as occupier ESG mandates harden. |
| Industrial REIT Formation | SEBI's unmet minimum asset thresholds for warehousing create first-mover structuring advantages for platform operators. |
| Smart Building Infrastructure | IoT-enabled energy optimization collapses facilities management cost structures across institutional portfolios. |
| Tier-II City Penetration | Coimbatore, Indore, and Chandigarh exhibit sub-12% Grade-A office stock penetration relative to working-age professional populations. |
| Flexible Lease Structuring | Managed space partnerships transfer demand volatility risk while capturing premium effective rents on utilized space. |
Study Parameters
Initial hypotheses were tested against primary input from real estate development executives, institutional fund managers, municipal planning officers, and tenant representation brokers and refined through secondary validation. Developer financial disclosures, SEBI REIT regulatory filings, state-level RERA implementation records, and municipal development control regulations anchored quantitative assessment. Bottom-up project pipeline analysis triangulated against top-down metropolitan absorption estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach across property type, investment vehicle, end-user category, and development stage dimensions. CAGRs were derived from segment-level volume trajectories and value-per-square-foot escalations. Forecast inputs incorporated PLI scheme manufacturing incentives, Smart Cities Mission infrastructure deployment schedules, and technology sector leasing velocity in Bengaluru and Hyderabad corridors.
Stress conditions across structural steel and cement price volatility, state-level RERA approval timeline divergence, and land title dispute resolution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on hybrid work protocol stabilization and institutional capital flow continuity. Material shifts in SEBI REIT guideline amendments or central government infrastructure spending priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market