
 Oman Commercial Real Estate Market | 2026-2036
Oman Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Commercial Real Estate Market Analytics
Property management and facility services revenue is fragmenting across specialized operators and developer-affiliated units. BBH Group leverages its integrated development-to-operations model to capture recurring income streams. WUJHA Real Estate Development anchors its position through mixed-use master planning in Muscat's growth corridors. Omran Group competes by controlling tourism-linked commercial assets along Oman's coastal economic zones.
Oman commercial real estate encompasses income-producing properties including office towers, retail centers, industrial facilities, and mixed-use developments, typically constructed with reinforced concrete frames and climate-adaptive glazing systems designed to achieve cooling loads below 150 watts per square meter in Gulf conditions. These assets generate returns through lease contracts, capital appreciation, and operational cash flows for institutional and private investors. The office segment sustains premium rents in Muscat's central business district while industrial properties near Sohar Port and Duqm lead transaction velocity. REIT structures are gaining traction as the Capital Market Authority frameworks mature, though direct investment still occupies the dominant share of capital deployment.
The Ministry of Housing and Urban Planning enforces building codes through the Omani Code of Planning and Building, while the Capital Market Authority governs REIT disclosures and investor protections. Municipalities in Muscat, Salalah, and Duqm administer zoning variances that shape permissible density and use mixes across sub-markets. Stakeholders must monitor how evolving environmental performance standards and foreign ownership liberalization will reshape tenant mix decisions and exit timelines.
Market Dynamics
The Ministry of Transport, Communications and Information Technology's port modernization directives are redistributing commercial real estate demand toward logistics corridors and away from traditional Muscat-centric development patterns.
Growth Catalysts
- Duqm Special Economic Zone Authority frameworks:Tax incentives and customs exemptions are attracting heavy industry tenants requiring purpose-built warehousing and manufacturing facilities.
- Logistics operators:Port modernization at Sohar and Salalah is driving demand for cold storage and bonded warehouse construction along coastal freight corridors.
- REIT structures:Capital Market Authority disclosure requirements are maturing, enabling institutional capital deployment into income-producing assets.
Market Restraints
- Construction input volatility:Reinforced concrete and climate-adaptive glazing systems face price instability tied to global steel and aluminum supply chains.
- Foreign ownership caps:Freehold restrictions in non-tourism zones limit exit liquidity for international investors.
- Cooling load thresholds:Building codes mandating sub-150 watts per square meter performance add technical complexity to retrofit projects.
Strategic Opportunities
- Al Mawaleh South district:Mixed-use master planning around the new logistics hub offers first-mover positioning in underdeveloped Muscat sub-markets.
- Tourism-linked commercial assets:Coastal economic zones controlled by Omran Group demonstrate yield premiums from hospitality-anchored retail.
- Integrated development-to-operations models:BBH Group's captive facility management units capture recurring revenue streams unavailable to pure developers.
Industry Challenges
- Facility management talent scarcity:Specialized operators compete for technicians qualified in Building Management Systems and energy optimization.
- Municipal zoning variance timelines:Density and use-mix approvals across Muscat, Salalah, and Duqm municipalities extend project gestation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Commercial Real Estate Market |
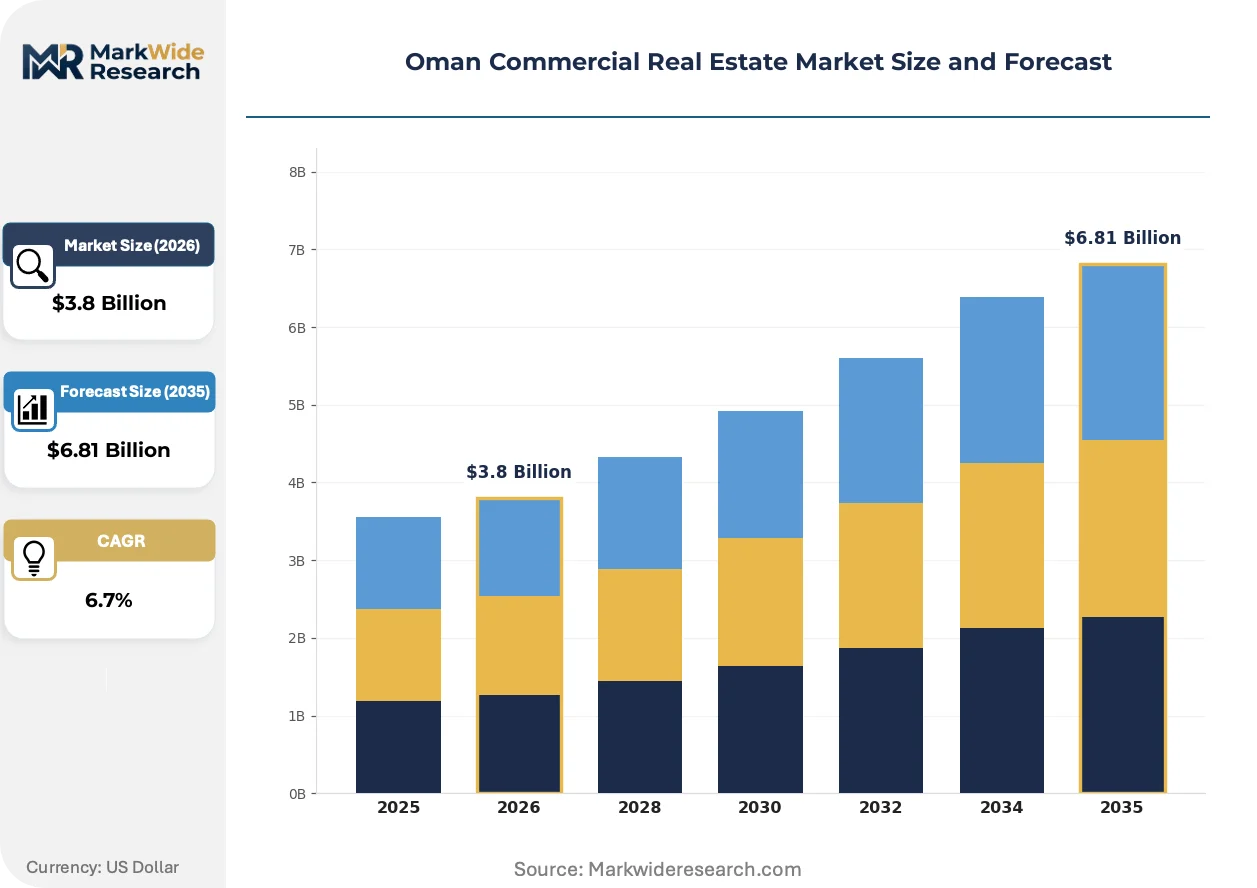
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Type: Direct Investment, REITs, Joint Ventures, Syndication Occupancy Type: Single-Tenant, Multi-Tenant, Owner-Occupied, Subleased Development Stage: Pre-Construction, Under Construction, Completed, Renovation |
| Companies Covered | BBH Group, WUJHA Real Estate Development, Omran Group, Muscat Real Estate Development, Muriya Tourism Development, Al-Taher Group, Malik Developments, Al Mouj Muscat, Shanfari Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Commercial Real Estate Market Evolving Landscape
Climate-adaptive building systems and digital asset management platforms are compressing operating cost structures while REIT governance frameworks reshape how institutional capital evaluates Omani commercial property exposure.
Smart building management systems integrating IoT sensors with predictive maintenance algorithms are collapsing energy expenditure profiles for Class A office towers. Property managers at Al Mawaleh South developments are deploying these platforms to achieve cooling load compliance without oversizing mechanical plant. The technology is compressing the payback period for green building certifications.
The Capital Market Authority's REIT disclosure standards are tightening investor protection requirements while expanding eligible asset classes. Industrial facilities near Sohar Port now qualify for inclusion alongside traditional office and retail. Logistics operators are restructuring warehouse holdings to meet these listing criteria.
Tenant procurement of space is rotating toward flexible lease structures with embedded expansion options. E-commerce fulfillment providers in the Duqm corridor are negotiating short-term warehousing with priority rights on adjacent build-to-suit pads. This pattern is displacing traditional ten-year fixed commitments in coastal industrial sub-markets.
Oman Commercial Real Estate Market Segmentation
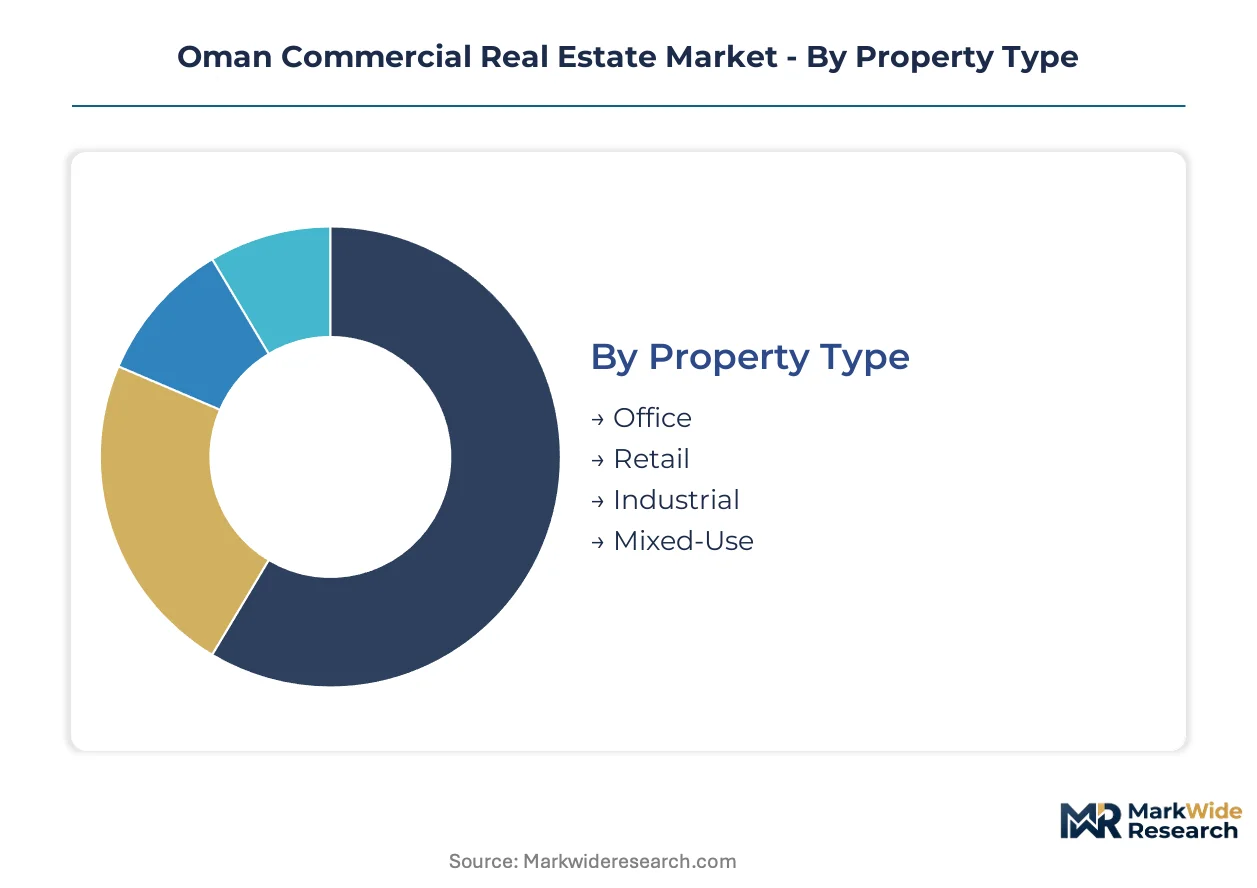
Segmentation reveals how capital deployment patterns, tenant procurement preferences, and asset lifecycle positioning fragment across distinct commercial real estate categories in Oman. Each dimension exposes different risk-return profiles and regulatory touchpoints that investors must navigate.
Property Type:
Cost tier differentiation separates premium-grade assets from functional warehousing in Oman's commercial real estate landscape.
- Office:Class A towers in Muscat's central business district command premium rents through reinforced concrete frames and climate-adaptive glazing achieving sub-150 watts per square meter cooling loads. Demand concentrates among professional services firms and government entities seeking proximity to ministerial headquarters.
- Industrial:Purpose-built manufacturing and logistics facilities near Sohar Port and Duqm Special Economic Zone lead transaction velocity. Heavy industry tenants require bonded warehouse configurations and customs-adjacent positioning that the Ministry of Transport, Communications and Information Technology's port modernization directives enable.
- Retail:Shopping centers and high-street formats serve consumer-facing tenants with location sensitivity tied to population density corridors.
- Mixed-Use:Integrated office-retail-residential developments in Al Mawaleh South district capture synergies between live-work environments and logistics hub adjacency.
Office commands the established base. The steepest expansion runs through Industrial.
Investment Type:
Application of capital varies by liquidity preference and governance sophistication across Oman's emerging institutional frameworks.
- Direct Investment:Sovereign wealth entities and family offices acquire stabilized assets outright, bearing full operational exposure and exit timing risk. This channel dominates current deployment volumes.
- REITs:Capital Market Authority disclosure requirements are maturing to accommodate industrial facilities alongside traditional office and retail, enabling broader institutional participation.
- Joint Ventures:Developer-operator pairings spread construction risk and facility management expertise across project lifecycles.
- Syndication:Pooled structures aggregate smaller investors into specific asset exposures with defined hold periods.
Direct Investment anchors current deployment. The steepest expansion trajectory belongs to REITs.
Occupancy Type:
Volume concentration in multi-tenant configurations reflects portfolio diversification strategies among institutional landlords.
- Multi-Tenant:Diversified rent rolls across numerous lessees reduce single-credit risk in Muscat office towers and retail centers. Property managers at Al Mawaleh South deploy smart building systems to allocate utility costs precisely.
- Single-Tenant:Build-to-suit arrangements for logistics operators in Duqm corridor offer long-term income visibility with embedded expansion options replacing traditional fixed commitments.
- Owner-Occupied:Corporate users control operational customization for specialized industrial processes.
- Subleased:Secondary market arrangements create flexibility for tenants with fluctuating space requirements.
Multi-Tenant configurations dominate institutional portfolios. The steepest expansion runs through Single-Tenant logistics arrangements.
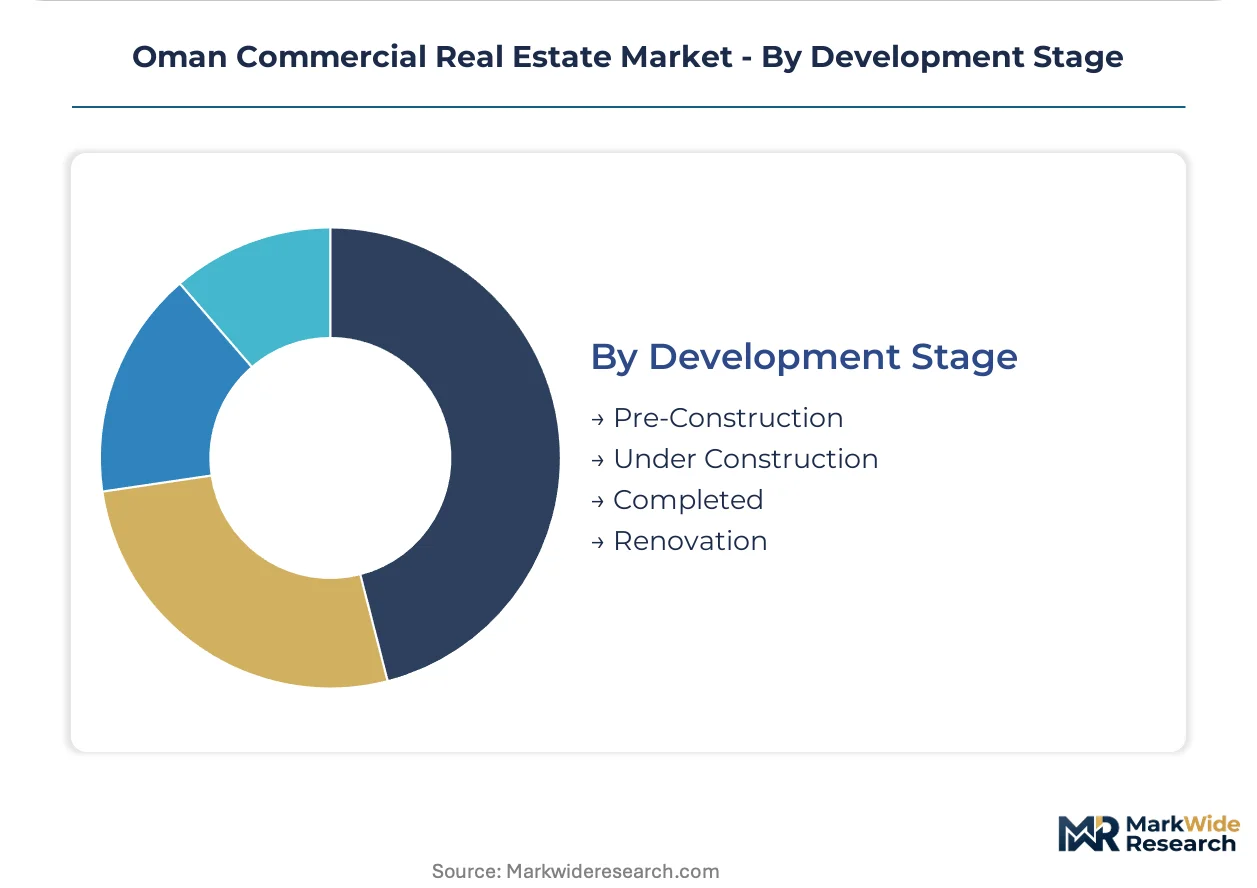
Development Stage:
Customer type differentiation separates opportunistic capital targeting construction-phase returns from yield-focused stabilized asset buyers.
- Completed:Stabilized assets with proven rent rolls attract income-focused investors seeking immediate cash flow in established Muscat sub-markets.
- Under Construction:Forward-funded developments in Duqm Special Economic Zone and Al Mawaleh South offer positioning ahead of infrastructure completion.
- Pre-Construction:Land acquisition and entitlement risk carries highest return potential contingent on municipal zoning variance approvals.
- Renovation:Retrofit projects address cooling load compliance challenges in aging stock through mechanical plant upgrades and glazing replacements.
Completed assets command the established base. The steepest expansion runs through Under Construction logistics facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Oman's commercial real estate sub-markets. Logistics corridors near port modernization zones absorb supply with minimal price resistance, while traditional Muscat office stock faces tenant negotiation pressure.
Muscat Governorate
Professional services firms and government entities drive Class A office absorption in the central business district. The Ministry of Housing and Urban Planning enforces Omani Code of Planning and Building standards that mandate cooling loads below 150 watts per square meter. Al Mawaleh South district is attracting mixed-use master planning around the new logistics hub as developers position ahead of infrastructure completion.
Al Batinah South Governorate
Industrial tenants seeking bonded warehouse configurations cluster near Sohar Port modernization zones. The Ministry of Transport, Communications and Information Technology directives on port expansion enable customs-adjacent positioning for heavy industry operators. Sohar Port corridor leads transaction velocity for purpose-built manufacturing and logistics facilities.
Al Wusta Governorate
Heavy industry tenants requiring tax incentives and customs exemptions concentrate in Duqm Special Economic Zone. Duqm Special Economic Zone Authority frameworks provide regulatory certainty for build-to-suit arrangements with embedded expansion options. The Duqm corridor is displacing traditional ten-year fixed commitments with flexible lease structures for e-commerce fulfillment providers.
Dhofar Governorate
Tourism-linked commercial assets generate yield premiums from hospitality-anchored retail along coastal economic zones. Municipal zoning variances administered in Salalah shape permissible density and use mixes for mixed-use developments. Salalah's coastal economic zone demonstrates how Omran Group-controlled assets capture recurring income from tourism-integrated commercial positioning.
Ad Dakhiliyah Governorate
Secondary market commercial activity concentrates around population density corridors serving consumer-facing retail tenants. Municipal approval timelines for density and use-mix decisions extend project gestation periods compared to coastal zones. Nizwa and surrounding urban centers attract localized retail and office development serving regional administrative functions.
Oman Commercial Real Estate Market Competitive Landscape
Capability concentration sits with integrated development-to-operations specialists; scale advantage sits with diversified holding groups controlling multiple asset classes. The market structures around three tiers: sovereign-affiliated developers with land bank control, private diversified groups with captive facility management units, and specialized operators focused on single asset categories. Dominant competitive moves include portfolio diversification into logistics-corridor positioning and backward integration into facility management services to capture recurring revenue streams.
Within the integrated development-to-operations tier, BBH Group exemplifies the captive facility management model that secures recurring income unavailable to pure developers. WUJHA Real Estate Development occupies a position in mixed-use master planning across Muscat's growth corridors. Omran Group anchors the tourism-linked commercial segment through coastal economic zone asset control. These three patterns represent how Omani commercial real estate competition separates between operational integration, geographic specialization, and sector-focused asset strategies.
| Leading Market Players |
|---|
| BBH Group |
| WUJHA Real Estate Development |
| Omran Group |
| Muscat Real Estate Development |
| Muriya Tourism Development |
| Al-Taher Group |
| Malik Developments |
| Al Mouj Muscat |
| Shanfari Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Muscat's Class A office stock compresses rental yields while tightening construction margins, forcing developers to prioritize recurring facility management revenue streams over speculative development premiums.
Pricing Analysis
Facility management service contracts now drive lifetime asset value for Omani commercial real estate operators. Three-tier pricing structure across premium, standard, and economy levels separates climate-certified Class A towers from functional warehousing near Sohar Port. Price differentiation rests on cooling load compliance certification and captive maintenance bundling. Pricing pressure stems from municipal zoning variance delays extending project gestation. Government tenants show lowest price sensitivity; e-commerce logistics operators demonstrate highest.
Supply Chain Analysis
Construction material supply concentrates with UAE-based distributors and Indian steel exporters serving Omani project pipelines. Reinforced concrete frame systems draw from UAE precast facilities and Indian rebar exporters. Climate-adaptive glazing systems rely on Chinese aluminum extrusion and German coating technologies. Single-source vulnerability runs through Sohar Port customs clearance bottlenecks. Distribution runs through developer-affiliated procurement desks and specialized logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management service attach rates are expanding faster than development margins across Oman's commercial real estate landscape, reframing asset ownership as a recurring-revenue platform rather than a capital-gain vehicle.
For Market Incumbents: Insulate rent roll stability through backward integration into smart building management systems that reduce tenant churn. BBH Group's captive facility model demonstrates how controlling Building Management System technicians mitigates talent scarcity threats. Prioritize certification investment in sub-150 watts per square meter cooling compliance to sustain premium pricing tiers against aging stock competition.
For New Entrants and Emerging Players: Pursue white-space positioning in Al Mawaleh South's underdeveloped logistics-adjacent sub-markets where municipal zoning variances remain negotiable. Duqm Special Economic Zone build-to-suit arrangements offer the most penetrable entry path for industrial facility specialization. Deploy joint venture structures with sovereign-affiliated land holders to bypass foreign ownership caps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Duqm corridor industrial developments requiring bonded warehouse configurations and customs-adjacent infrastructure. Long-term viability favors integrated development-to-operations specialists with captive facility management units over pure development plays. Monitor Capital Market Authority REIT disclosure standard expansions as the signal for institutional capital deployment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Facility Management | Captive service units secure recurring revenue streams unavailable to pure developers competing on development premiums alone. |
| REIT Structure Qualification | Capital Market Authority disclosure compliance enables institutional capital deployment into industrial facilities near Sohar Port. |
| Smart Building System Deployment | IoT-integrated platforms at Al Mawaleh South developments achieve cooling load compliance without mechanical plant oversizing. |
| Duqm SEZ Build-to-Suit Positioning | Tax incentive frameworks attract heavy industry tenants requiring purpose-built warehousing with embedded expansion options. |
| Tourism-Linked Asset Diversification | Omran Group's coastal economic zone control demonstrates yield premiums from hospitality-anchored retail positioning. |
Research Methodology
Operator-level perspectives from property managers, facility services directors, municipal planning officers, and logistics operators anchored the qualitative base. Primary interviews with BBH Group and WUJHA Real Estate Development executives combined with secondary validation from Capital Market Authority disclosure filings, Ministry of Housing and Urban Planning building code documentation, and Duqm Special Economic Zone Authority regulatory frameworks. Bottom-up project pipeline tracking and top-down macroeconomic triangulation shaped the analytical foundation.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include property type, investment vehicle structure, occupancy configuration, and development stage maturity. CAGRs derived from construction cost inflation trajectories, port modernization spend profiles, and REIT market penetration assumptions. Forecast inputs incorporated Sohar Port throughput expansion timelines and municipal zoning variance approval velocity.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows and construction material import costs would shift the trajectory. Forecasts reflect documented assumptions regarding foreign ownership liberalization pace and environmental performance standard enforcement. Quarterly review of port modernization directive implementation and REIT listing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market