
 Thailand Commercial Real Estate Market | 2026-2036
Thailand Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Commercial Real Estate Market Insights
Property management and facility services revenue is reconfiguring how developers capture lifetime value from commercial assets. Central Pattana PLC leverages its integrated retail-leisure platforms to sustain recurring income streams beyond base rents. WHA Corporation PCL anchors Thailand's logistics infrastructure through industrial estate development and warehouse leasing. Frasers Property Thailand competes on mixed-use master planning that combines office, retail, and residential components.
Thailand commercial real estate encompasses income-producing properties including office towers, retail centers, industrial facilities, and hospitality assets designed for lease or capital appreciation, typically constructed with reinforced concrete frames, curtain wall systems, and floor plates exceeding 500 square meters to accommodate tenant flexibility. The primary commercial purpose centers on generating rental yield and asset appreciation for institutional and private investors. Office and industrial segments lead transaction volumes as multinational corporations expand back-office operations and manufacturing relocation accelerates. Retail properties face structural recalibration as experiential formats replace traditional department store anchors. REITs as an investment strategy concentrate liquidity for mid-scale investors seeking exposure without direct development risk.
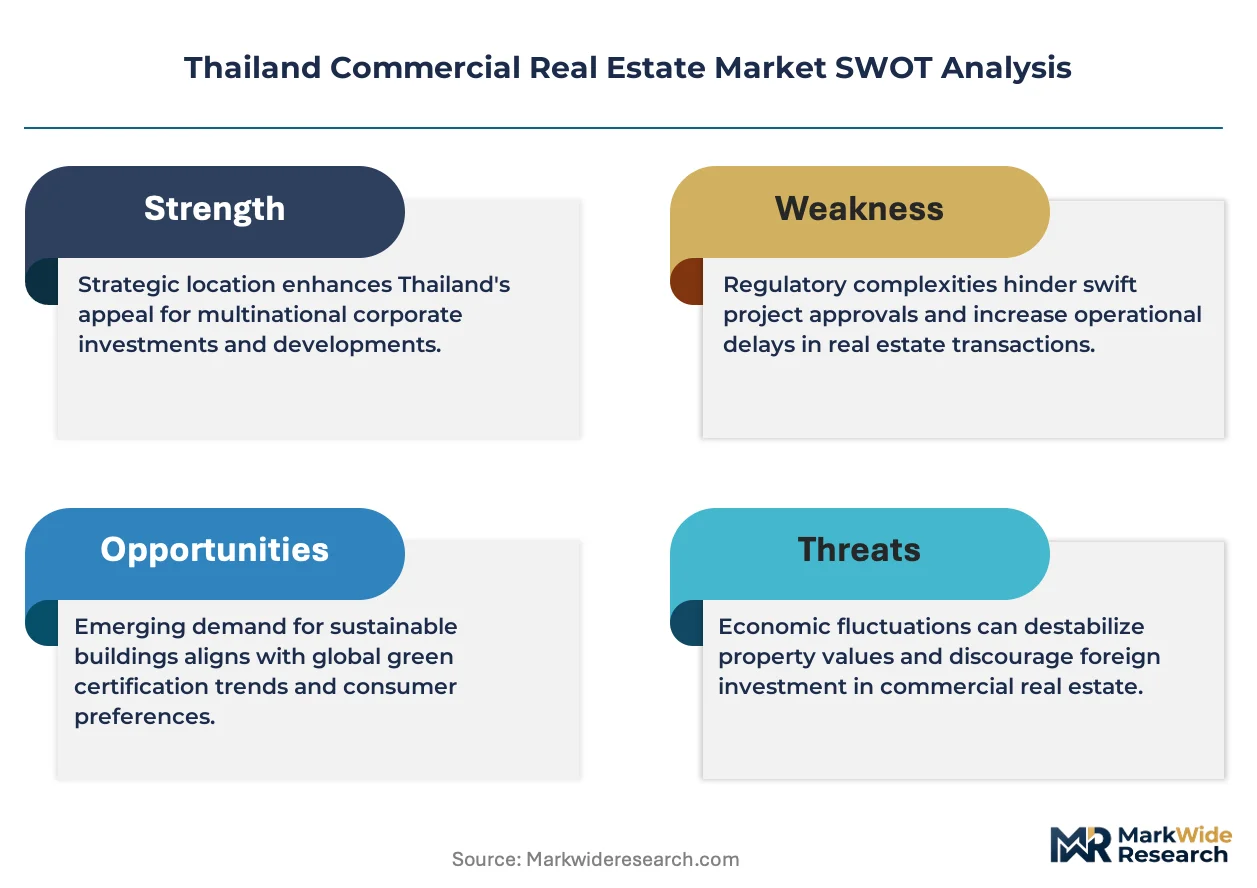
Thailand's Board of Investment coordinates with the Department of Industrial Works and the Ministry of Interior's zoning authorities to shape commercial construction through tax incentives, environmental impact assessments, and foreign ownership restrictions under the Land Code. These frameworks determine where industrial estates may expand, what sustainability standards new buildings must meet, and how overseas capital participates in property ownership. Stakeholders must monitor whether upcoming smart city designations in provincial hubs will unlock new zoning flexibility or tighten compliance burdens for speculative development.
Market Dynamics
Thailand's Board of Investment smart industrial zone incentives are redirecting developer capital toward automated warehouse and fulfillment facilities, compressing construction timelines and reshaping tenant specifications across Greater Bangkok and the Eastern Economic Corridor.
Growth Catalysts
- Eastern Economic Corridor Infrastructure:The linked provinces of Chon Buri, Rayong, and Chachoengsao concentrate logistics demand from e-commerce fulfillment operators expanding warehouse footprints.
- BOI Smart Zone Incentives:Tax advantages for automated facilities redirect capital from speculative office development toward income-producing industrial assets with higher yield stability.
- Manufacturing Relocation:Multinational corporations diversifying supply chains from China are expanding back-office operations and production facilities, driving absorption in industrial and office segments.
Market Restraints
- Foreign Ownership Restrictions:Thailand's Land Code limits overseas direct property ownership, forcing capital deployment through leasehold structures or local joint ventures that dilute control.
- Construction Input Volatility:Reinforced concrete and curtain wall system costs fluctuate with regional steel and aluminum supply disruptions, compressing developer margins on fixed-price contracts.
- Retail Format Obsolescence:Traditional department store anchors face structural displacement by experiential leisure formats, straining rental income predictability in older shopping centers.
Strategic Opportunities
- REIT Liquidity Expansion:Securities and Exchange Commission frameworks enable mid-scale investor participation without direct development risk, broadening capital pools for stabilized assets.
- Automated Facility Convergence:Integration of robotics with warehouse management systems creates premium rent tiers for fulfillment operators seeking speed-to-market advantages.
- Provincial Smart City Designations:Upcoming zoning flexibility in secondary hubs outside Greater Bangkok offers first-mover positioning for industrial estate developers.
Industry Challenges
- Environmental Impact Assessment Delays:Ministry of Natural Resources and Wildlife approval timelines extend project commencement, tying up capital during permitting phases.
- Facility Management Talent Scarcity:Shortage of technicians qualified to operate automated building systems limits operational efficiency gains from smart infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Commercial Real Estate Market |
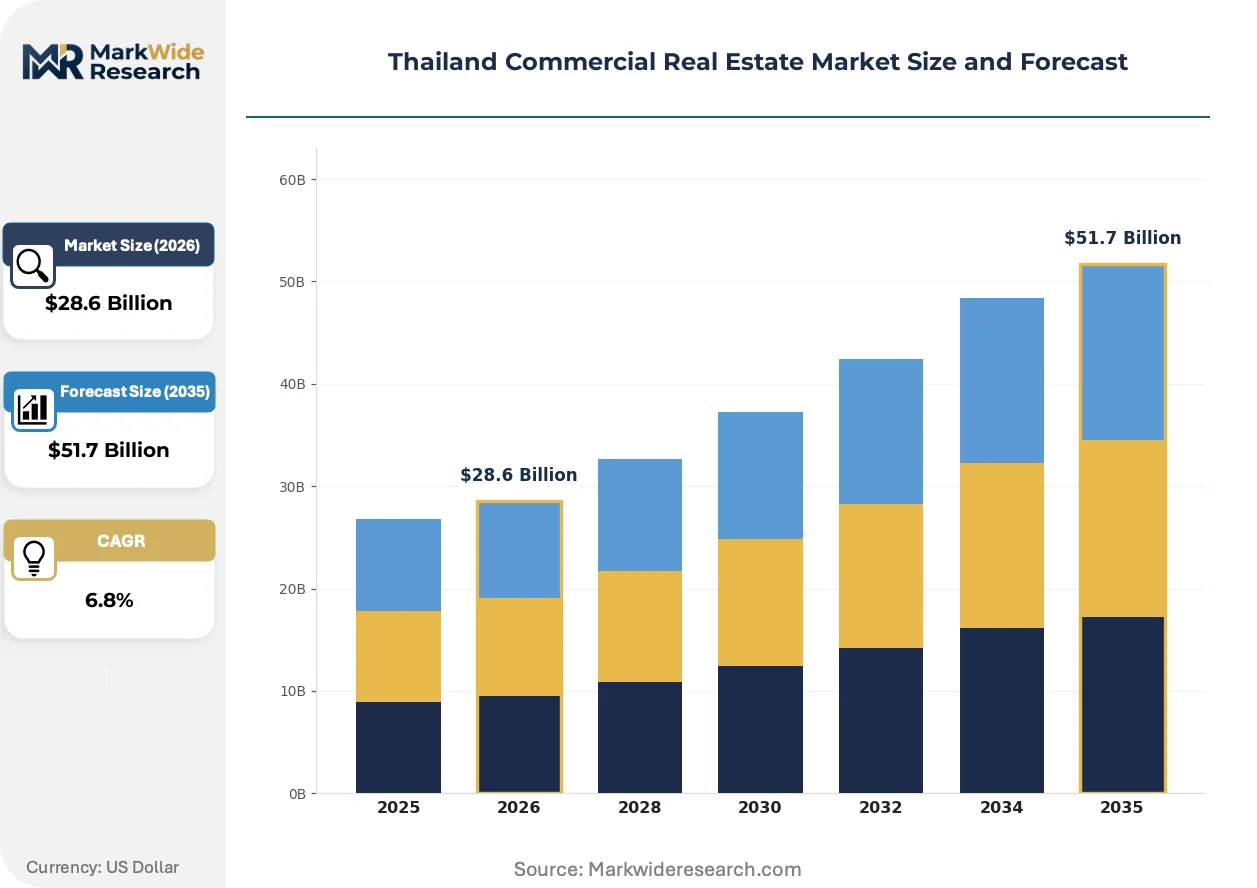
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Strategy: Direct Investment, REITs, Joint Ventures, Renovation End User: Corporations, Retailers, Investors, Government Capacity: Small Scale, Medium Scale, Large Scale, Mixed-Use |
| Companies Covered | Central Pattana PLC, WHA Corporation PCL, Asset World Corp, Frasers Property Thailand, Supalai PLC, Amata Corp PLC, Land and Houses Public Company Ltd, AP Thailand PLC, Sansiri PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Commercial Real Estate Market Trends and Innovations
Asset digitization and tenant experience platforms are reconfiguring how commercial properties generate recurring revenue beyond base rents, compressing the traditional landlord-tenant relationship into integrated service partnerships.
Building management systems are migrating from standalone HVAC and lighting controls toward unified IoT platforms that optimize energy consumption across entire industrial estates. WHA Corporation and Central Pattana PLC are deploying these systems in new developments to attract multinational tenants with sustainability reporting requirements. This migration from fragmented to integrated infrastructure is compressing operating cost spreads between premium and standard-grade assets.
Thailand's Department of Industrial Works has tightened environmental impact assessment protocols for new industrial estate expansion, mandating wastewater treatment and carbon footprint disclosure that add 8-14 months to permitting timelines. Developers are responding by pre-certifying land banks and engaging environmental consultants during site acquisition rather than post-purchase. The industrial segment faces the steepest compliance burden, with Rayong province projects experiencing the most extended review cycles.
Tenant procurement of commercial space is fragmenting from long-term single-lease commitments toward flexible tenure structures combining core premises with surge capacity options. Logistics operators in the Eastern Economic Corridor are negotiating master agreements with multiple warehouse providers rather than consolidating in single facilities. This pattern is most visible among e-commerce fulfillment specialists serving Bangkok's same-day delivery corridors, where inventory positioning flexibility outweighs cost minimization.
Thailand Commercial Real Estate Market Segmentation
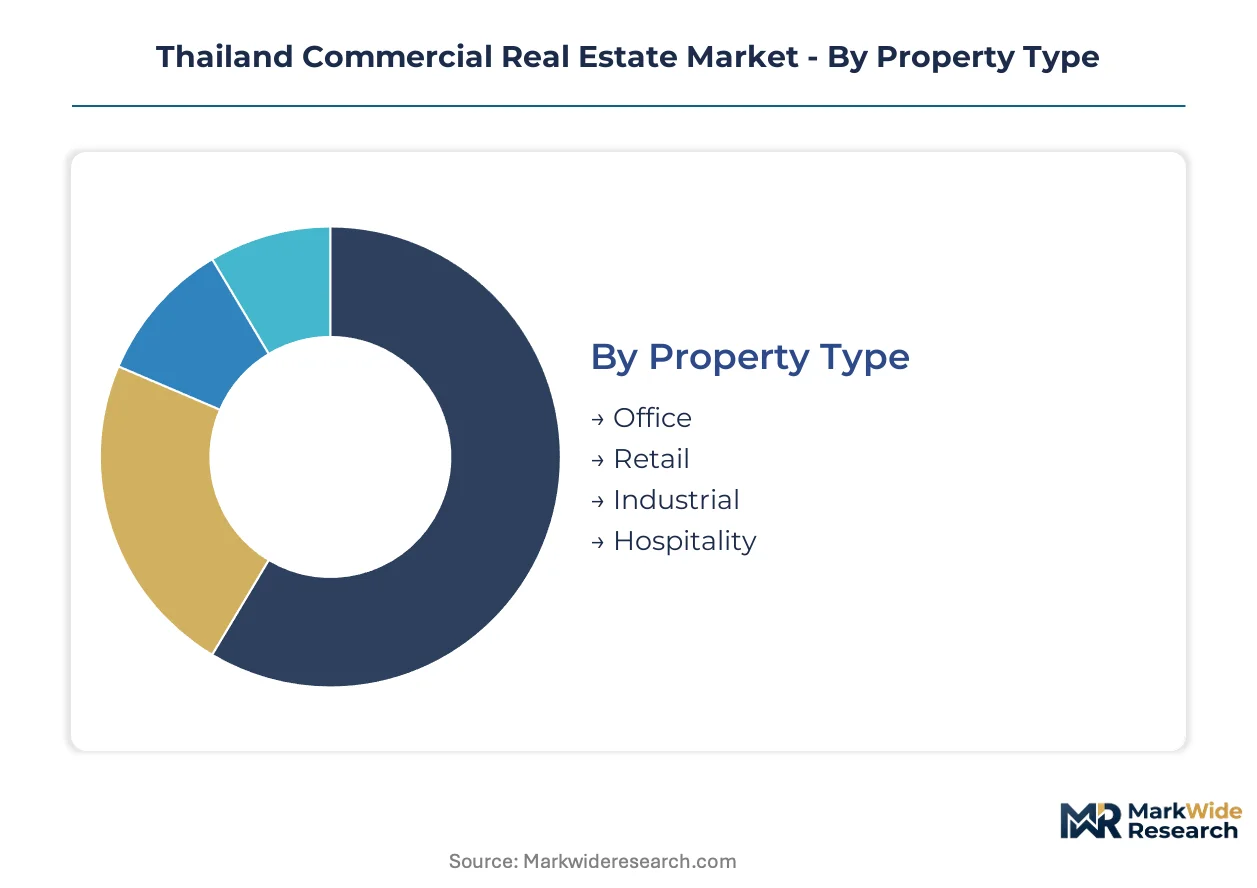
Segmentation reveals how capital allocation patterns diverge across Thailand's commercial real estate landscape. Property type and investment strategy configurations determine risk-return profiles for institutional participants navigating Bangkok's tightening yield environment and the Eastern Economic Corridor's industrial expansion.
Property Type:
After-sales service intensity varies sharply across property types, with industrial facilities demanding continuous facility management engagement versus retail's tenant-driven operational autonomy.
- Office:Grade-A towers in Bangkok's central business district feature curtain wall systems and floor plates exceeding 500 square meters. Demand concentrates among multinational corporations expanding back-office operations from Singapore and Hong Kong, with BOI incentives compressing effective rents for qualifying tenants.
- Industrial:Automated warehouses and manufacturing facilities dominate transaction velocity in Chon Buri and Rayong provinces. E-commerce fulfillment operators seek speed-to-market positioning along the Eastern Economic Corridor, where integrated logistics parks offer direct port and highway connectivity.
- Retail:Experiential leisure formats displace traditional department store anchors in Bangkok's established shopping districts.
- Hospitality:Serviced apartments and convention-adjacent hotels target extended-stay corporate demand in Greater Bangkok.
Industrial holds the largest share; momentum sits with office assets qualifying for BOI smart zone benefits.
Investment Strategy:
Cost tier differentiation separates institutional capital deployment from mid-scale investor participation, with liquidity and control trade-offs defining strategy selection.
- Direct Investment:Sovereign wealth funds and regional developers acquire stabilized assets or development land through local joint venture structures mandated by Thailand's Land Code restrictions.
- REITs:Securities and Exchange Commission frameworks enable fractional ownership of income-producing portfolios, broadening retail investor access without direct development exposure.
- Joint Ventures:Foreign capital pairs with Thai sponsors to circumvent ownership limitations while sharing construction and leasing risk.
- Renovation:Value-add strategies target aging retail and office stock in Bangkok's peripheral districts for repositioning to higher-yielding uses.
Direct investment absorbs the deepest capital pools; REITs are climbing the fastest as liquidity mechanisms mature.
End User:
Application-specific requirements shape building specifications, with government tenants imposing procurement compliance burdens distinct from private sector flexibility.
- Corporations:Multinational tenants prioritize sustainability certifications and smart building infrastructure to meet headquarters-mandated ESG reporting.
- Retailers:Omnichannel operators negotiate flexible tenure structures combining flagship presence with surge capacity options across multiple locations.
- Investors:Institutional allocators target core-plus and value-add risk profiles with 5-7 year hold periods.
- Government:State agencies and state-owned enterprises procure space through centralized tender processes with extended lease commitments.
Corporations drive premium specification adoption; retailers are expanding most quickly as format experimentation accelerates.
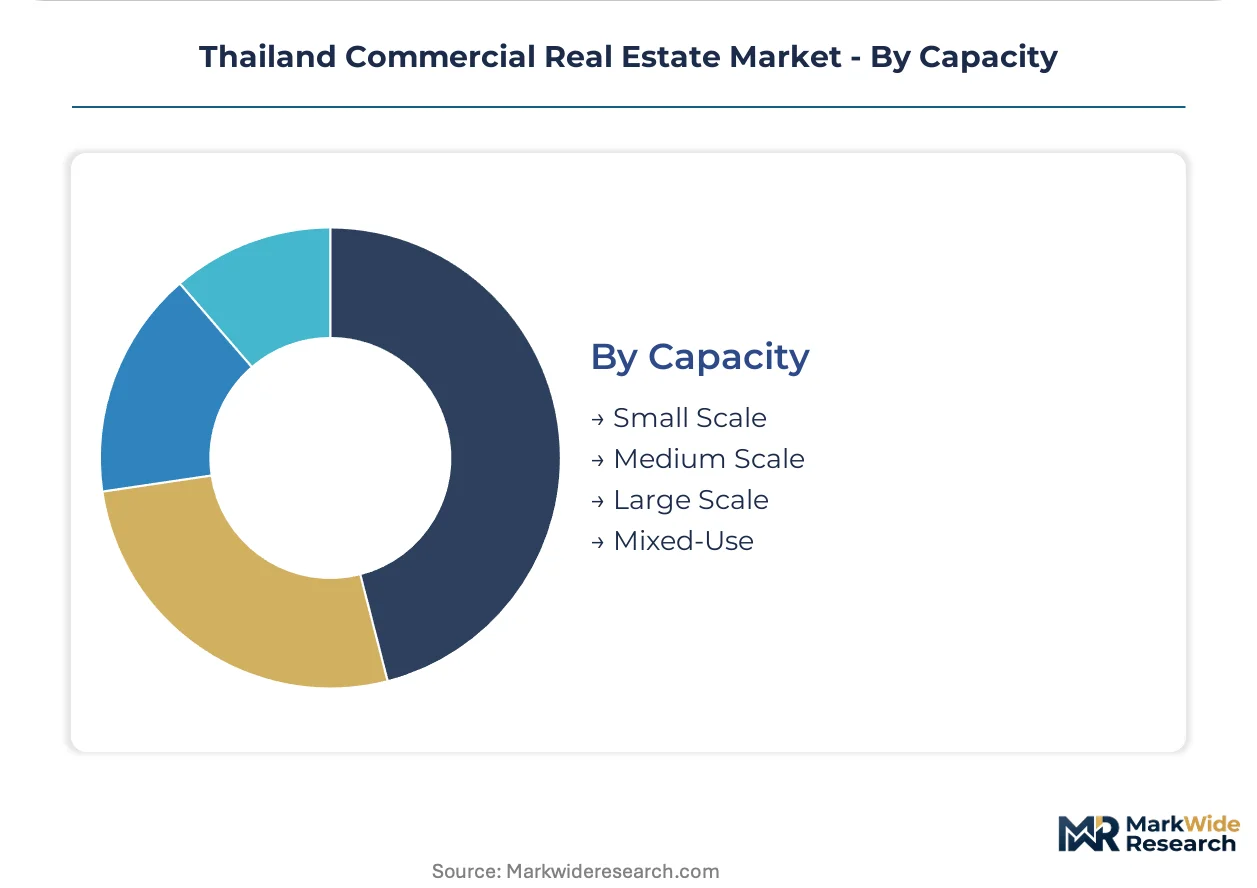
Capacity:
Volume concentration favors large-scale master-planned developments where infrastructure amortization across phases improves project-level returns.
- Large Scale:Integrated industrial estates and mixed-use townships in the Eastern Economic Corridor command institutional capital commitments exceeding regional development thresholds.
- Mixed-Use:Combined office-retail-residential configurations optimize land value capture in Bangkok's transit-oriented development zones.
- Medium Scale:Suburban office parks and neighborhood retail centers serve secondary provincial hubs.
- Small Scale:Boutique hospitality and specialized flex office products target niche tenant segments.
Large scale dominates institutional allocation; mixed-use configurations gain share fastest as zoning flexibility tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's commercial real estate consumption concentrates in Greater Bangkok's mixed-use developments, while the Eastern Economic Corridor drives industrial absorption through logistics and manufacturing demand patterns distinct from the capital's office-retail orientation.
Bangkok Metropolitan Region
Grade-A office towers and integrated retail-leisure platforms dominate capital deployment in the central business district and emerging transit-oriented zones. Thailand's Board of Investment coordinates with Bangkok Metropolitan Administration on smart city zoning incentives that redirect developer capital toward automated facilities. The Rama IX-Ratchada corridor concentrates new supply as multinational corporations expand back-office operations from regional headquarters.
Eastern Economic Corridor
Chon Buri, Rayong, and Chachoengsao provinces anchor industrial estate expansion driven by e-commerce fulfillment operators and manufacturing relocation from China. The Department of Industrial Works enforces tightened environmental impact assessment protocols that extend permitting timelines by 8-14 months. WHA Corporation and Amata Corp PLC anchor development in Rayong's integrated logistics parks with direct port connectivity.
Chiang Mai and Northern Hubs
Secondary provincial centers attract boutique hospitality and specialized flex office products targeting niche corporate demand. Thailand's Ministry of Interior zoning authorities shape construction through foreign ownership restrictions under the Land Code. Chiang Mai's creative district experiments with mixed-use configurations as zoning flexibility tightens in primary markets.
Phuket and Southern Resort Markets
Serviced apartments and convention-adjacent hospitality assets target extended-stay corporate demand in Greater Phuket. The Ministry of Natural Resources and Wildlife mandates carbon footprint disclosure for coastal developments. Patong and Laguna clusters concentrate tourism-linked commercial supply as experiential formats displace traditional retail anchors.
Northeastern Growth Corridors
Khon Kaen and Udon Thani emerge as logistics intermediaries connecting Greater Bangkok to Mekong sub-region trade flows. Provincial smart city designations under national development frameworks unlock infrastructure investment for industrial estate pre-positioning. These secondary hubs offer first-mover positioning as automated warehouse specifications standardize across the country.
Thailand Commercial Real Estate Market Competitive Landscape
Capability concentration sits with integrated retail-leisure developers; scale advantage sits with industrial estate specialists. The Thailand commercial real estate market structures around three archetypes: mixed-use master planners capturing land value through transit-oriented density, logistics infrastructure operators monetizing corridor positioning in the Eastern Economic Corridor, and residential-led developers diversifying into income-producing commercial assets. Dominant competitive moves include portfolio diversification across property types and strategic partnerships with foreign capital seeking leasehold exposure under Land Code restrictions.
Within the integrated platform tier, Central Pattana PLC exemplifies retail-leisure convergence sustaining recurring income beyond base rents. WHA Corporation PCL and Frasers Property Thailand occupy positions at the industrial and mixed-use vectors respectively, representing how capital deployment splits between automated warehouse development and office-retail-residential combinations. These three entities anchor distinct strategic positions without overlapping capability claims.
| Leading Market Players |
|---|
| Central Pattana PLC |
| WHA Corporation PCL |
| Asset World Corp |
| Frasers Property Thailand |
| Supalai PLC |
| Amata Corp PLC |
| Land and Houses Public Company Ltd |
| AP Thailand PLC |
| Sansiri PLC |
| Others |
Pricing and Supply Chain Analysis
The Eastern Economic Corridor's port-to-highway logistics network compresses freight cost spreads between Greater Bangkok and Chon Buri industrial zones, concentrating pricing power among developers with pre-certified land banks while forcing smaller players toward joint venture structures that dilute margin control.
Pricing Analysis
Long-term lease contracts anchor the industrial segment, with master agreements spanning 10-15 years locking in base rents for automated warehouse operators while variable service charges capture facility management escalation. Price differentiation hinges on BOI smart zone certification tier and proximity to Laem Chabang port, with Rayong province commanding premiums over peripheral Chachoengsao locations. Cost compression in standard-grade office stock intensifies as speculative supply outpaces multinational back-office absorption. E-commerce fulfillment operators show least price sensitivity, prioritizing speed-to-market positioning over rent minimization.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard among Thai contractors, with supply-chain finance facilities bridging working capital gaps for steel and aluminum curtain wall suppliers. Reinforced concrete frame construction draws from domestic cement production and imported Chinese steel, while smart building system components source from South Korea and Japan. Single-source vulnerability concentrates in automated warehouse robotics, where Japanese and German OEMs dominate. Distribution runs through Bangkok-based procurement consortia serving Eastern Economic Corridor developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's commercial real estate sector is approaching a platform-economics inflection where integrated facility management ecosystems displace transactional landlord-tenant relationships, with IoT-enabled building systems creating interoperability standards that lock in tenant switching costs.
For Market Incumbents: Insulate recurring revenue streams by embedding facility management services into base lease structures before competitor platforms achieve tenant data integration. WHA Corporation and Central Pattana PLC should accelerate captive technical training programs to address facility management talent scarcity. Backward integration into environmental consulting reduces permitting timeline risk from Ministry of Natural Resources and Wildlife assessment delays.
For New Entrants and Emerging Players: Build out boutique flex-office and specialized logistics products in Chiang Mai and Khon Kaen before zoning flexibility tightens in secondary hubs. Provincial smart city designations offer first-mover positioning with lower land acquisition costs than Greater Bangkok. Target government procurement contracts through centralized tender processes, where extended lease commitments provide cash flow stability absent in speculative development.
For Investors and Strategic Acquirers: Industrial estate specialists with pre-certified land banks in Rayong and automated facility capabilities represent the most defensible acquisition targets. Long-term viability rests on exposure to manufacturing relocation trends and e-commerce fulfillment demand across the analysis window. Monitor BOI incentive recalibration as the primary inflection signal for capital reallocation between office and industrial segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Zone Certification Investment | BOI incentive qualification redirects developer capital toward automated facilities with higher yield stability. |
| Pre-Certified Land Bank Acquisition | Environmental assessment pre-clearance compresses permitting timelines by 8-14 months in Rayong province. |
| Integrated Facility Management Platform | IoT-enabled building systems attract multinational tenants with headquarters-mandated ESG reporting requirements. |
| Joint Venture Structuring | Local partnership formations circumvent Land Code foreign ownership restrictions while sharing construction risk. |
| Technical Training Program Expansion | Captive technician development addresses facility management talent scarcity limiting smart infrastructure returns. |
Research Methodology
Cross-validation between primary interviews with industrial estate developers, facility management operators, and multinational tenant procurement leads anchors the qualitative findings, with secondary validation from Thailand Board of Investment incentive filings, Securities and Exchange Commission REIT disclosures, and Department of Industrial Works permitting databases. Bottom-up project pipeline analysis triangulates against top-down macroeconomic absorption modeling.
Calibration against historical transaction velocity and lease rate trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions span property type, investment strategy, end user archetype, and capacity tier, with regional regulatory cluster and BOI incentive eligibility as industry-specific forecast inputs. CAGRs derive from supply-demand gap analysis and capital deployment pattern tracking.
Stress conditions across construction input cost volatility, foreign ownership policy tightening, and e-commerce fulfillment demand deceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure completion timelines and incentive continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Turkey Commercial Real Estate Market