
 United States Co-Working Office Space Market | 2026-2036
United States Co-Working Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
United States Co-Working Office Space Market Analytics
Texas is rewriting the competitive map for flexible workspace deployment across the southern United States. Industrious leverages its premium hospitality-driven model to sustain occupancy premiums in Dallas and Houston submarkets. WeWork anchors its turnaround strategy through asset-light management agreements rather than direct leases. Regus competes on scale, operating the densest geographic footprint of any operator in secondary US cities.
Co-working office space denotes commercially leased environments where multiple unrelated tenants share infrastructure, typically provisioned with internet bandwidth exceeding 100 Mbps per workstation, ergonomic furniture, and on-demand meeting facilities. These spaces serve enterprises seeking to reduce capital commitments while preserving geographic agility for hybrid workforces. Private offices command the highest margin pools within workspace type segmentation, as enterprise clients prioritize security and brand isolation over open-plan density. Corporate packages represent the fastest-expanding service model, reflecting Fortune 500 experimentation with distributed satellite teams rather than centralized headquarters consolidation.
OSHA indoor air quality standards and local building code amendments in jurisdictions like New York City and San Francisco shape fit-out costs and ventilation specifications for multi-tenant environments. The ADA mandates accessibility compliance across common areas, influencing space design and square-footage economics for operators. Stakeholders must monitor how municipal zoning boards classify co-working facilities relative to traditional office or retail use, as reclassification risks trigger permitting delays and property tax reassessments that alter site selection calculus.
Market Dynamics
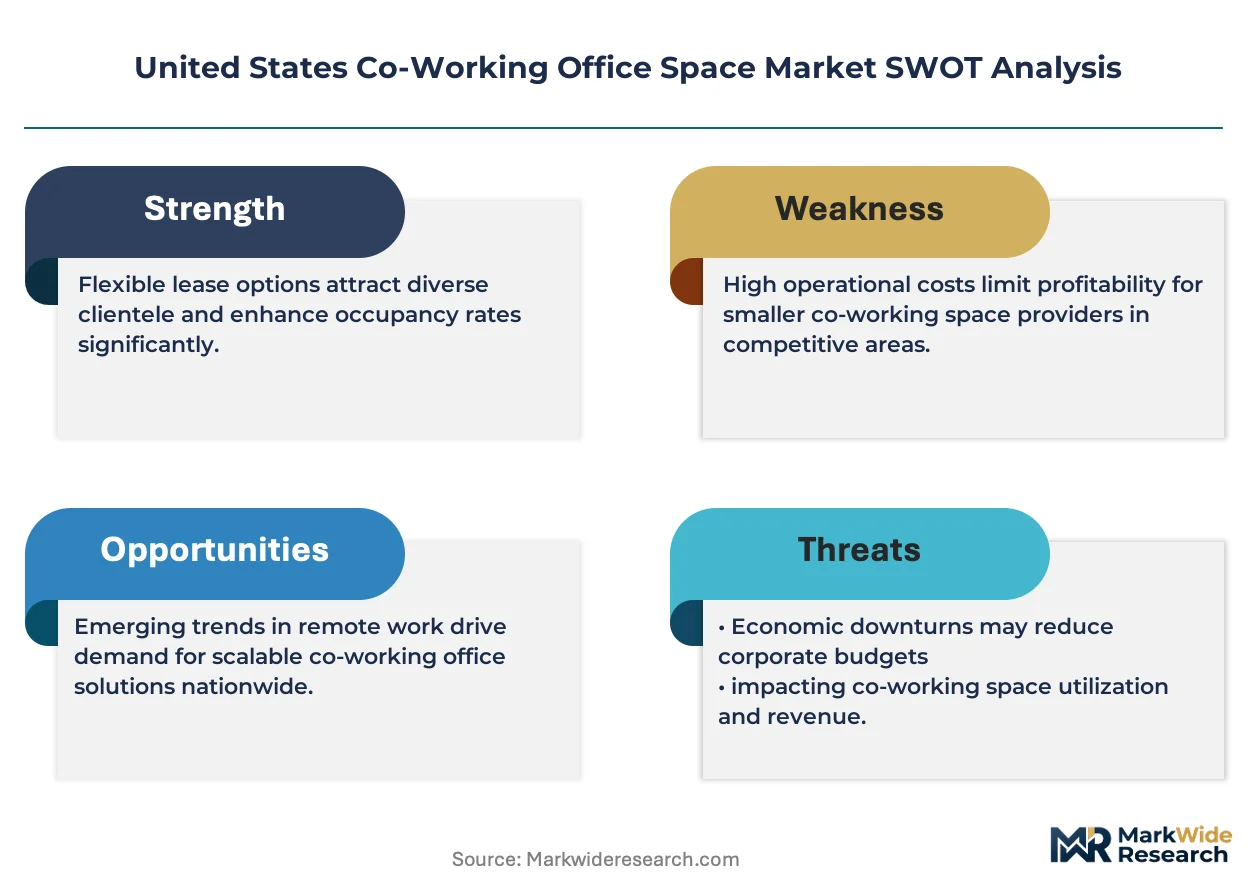
Corporate satellite office deployments are compressing lease commitment timelines across Texas metro corridors, forcing operators to restructure revenue models around short-term management agreements rather than traditional multi-year direct leases.
Growth Catalysts
- IRS Section 179:The accelerated business equipment deduction incentivizes small business workspace decisions, reducing effective occupancy costs for qualifying tenants in Dallas-Fort Worth and Houston submarkets.
- Hybrid workforce protocols:Fortune 500 experimentation with distributed satellite teams creates sustained demand for private offices and corporate packages over open-plan density.
- Technology startup expansion:Austin and Nashville venture-backed firms are scaling flexible workspace footprints to preserve capital for core R&D investment.
Market Restraints
- OSHA indoor air quality standards:Ventilation specification upgrades in multi-tenant environments inflate fit-out costs and extend pre-opening timelines.
- Municipal zoning reclassification risk:Local boards in jurisdictions like New York City and San Francisco trigger permitting delays and property tax reassessments that distort site selection calculus.
- ADA compliance mandates:Accessibility requirements across common areas consume additional square footage, compressing revenue per square foot economics.
Strategic Opportunities
- Underpenetrated secondary cities:Nashville and Austin submarkets show capacity for operator expansion beyond saturated primary metros.
- Enterprise corporate packages:Service model innovation targeting Fortune 500 satellite teams commands premium pricing over individual memberships.
- Management agreement structures:Asset-light revenue models reduce balance sheet exposure while capturing recurring fee income from property owners.
Industry Challenges
- Fit-out capital intensity:Ergonomic furniture and 100+ Mbps per workstation bandwidth requirements demand substantial upfront investment before revenue recognition.
- Legacy lease portfolio exposure:Operators with concentrated long-term direct obligations face margin compression as market pricing shifts toward flexible terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Co-Working Office Space Market |
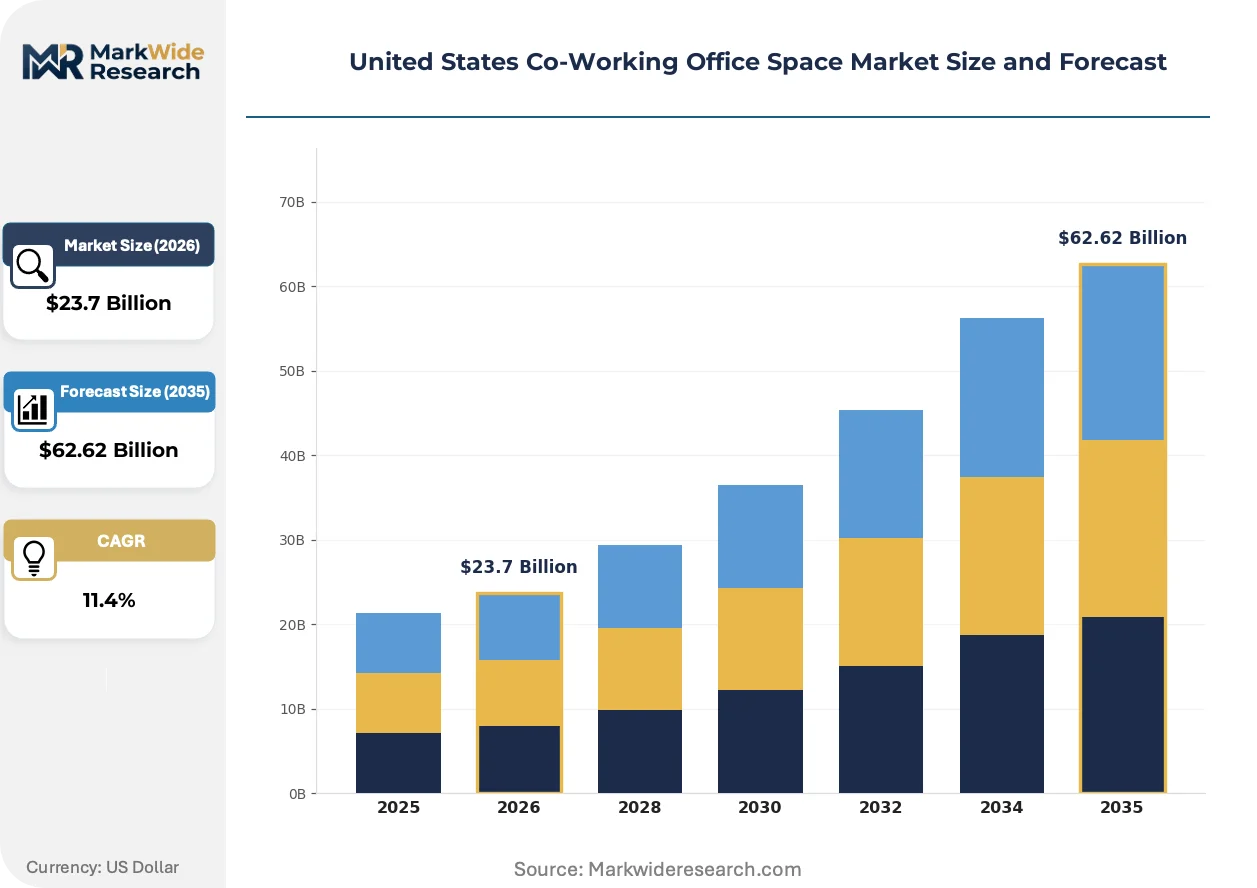
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Workspace Type: Private Offices, Dedicated Desks, Hot Desks, Meeting Rooms Client Type: Freelancers, Startups, Small Enterprises, Corporations Service Model: Membership-based, Pay-as-you-go, Partnership, Corporate Packages Networking Opportunities: Events, Workshops, Networking Mixers, Community Meetups |
| Companies Covered | Regus (IWG), WeWork, Industrious, Spaces (IWG), HQ, Venture X, Office Evolution, Serendipity Labs, Expansive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Co-Working Office Space Market Evolving Landscape
Workspace technology stacks are converging with enterprise IT infrastructure, creating seamless hybrid collaboration environments that redefine tenant expectations across Texas and southern US markets.
Smart building management systems are digitizing environmental controls, security access, and resource booking through unified platforms. Enterprise clients in Dallas and Houston are mandating these integrations as baseline requirements for satellite office contracts. This technology convergence is digitizing how operators differentiate service tiers and price workspace subscriptions.
The ADA mandates accessibility compliance across common areas, influencing space design and square-footage economics for operators. Local building code amendments in jurisdictions like New York City and San Francisco shape fit-out costs and ventilation specifications for multi-tenant environments. These regulatory layers most affect premium hospitality-driven models where brand positioning depends on visible amenity quality.
Enterprise procurement teams are consolidating vendor relationships and demanding outcome-based workspace contracts tied to utilization metrics and employee satisfaction scores. This buying-pattern shift displaces individual membership sales with negotiated corporate packages. Texas metro corridors show the most visible adoption, reflecting concentrated Fortune 500 regional headquarters activity.
United States Co-Working Office Space Market Segmentation
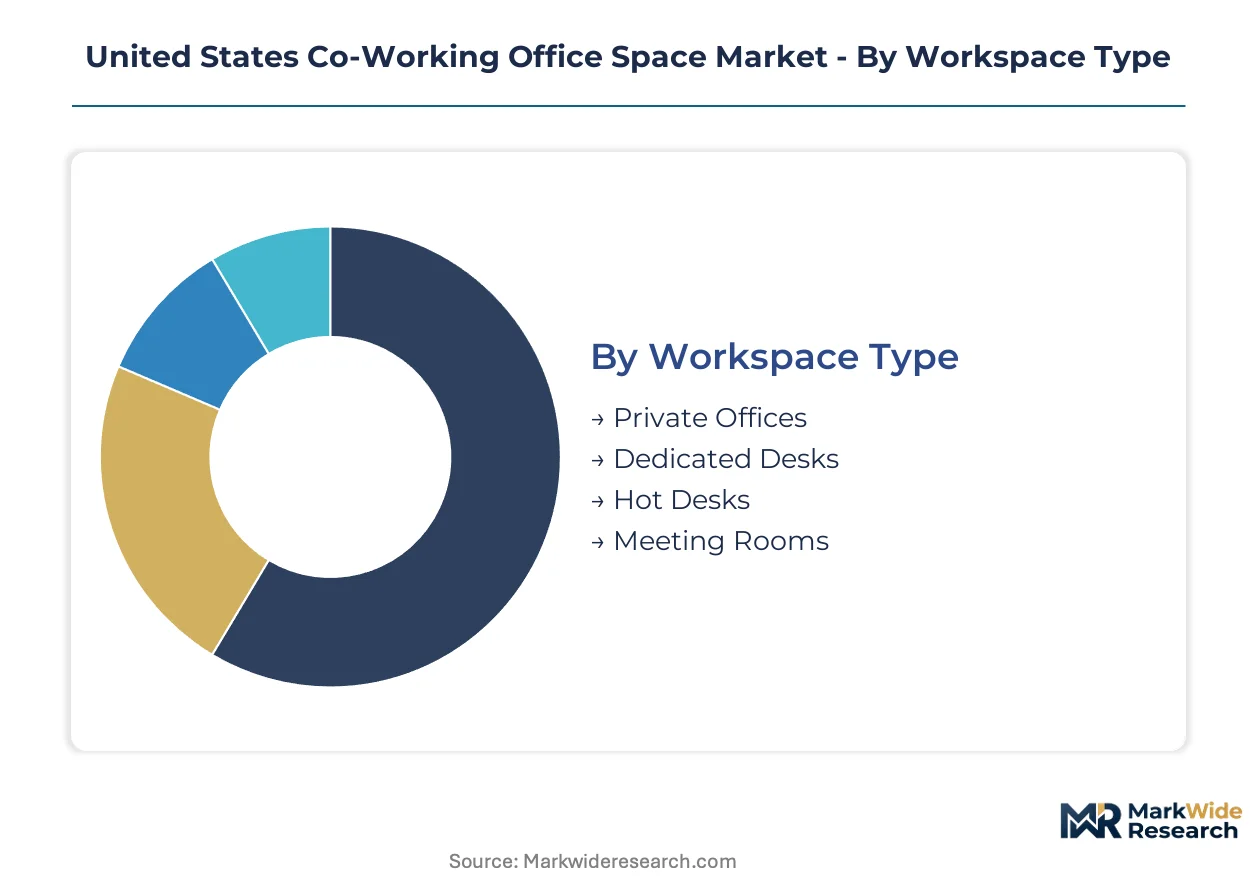
Segmentation in the United States co-working market reveals divergent capital intensity and contract velocity across workspace configurations. Operators calibrate floor plate allocation and amenity investment based on which segments command premium pricing versus rapid inventory turnover.
Workspace Type:
Cycle times vary dramatically across physical configurations, with hot desks turning daily while private offices lock in multi-year enterprise commitments.
- Private Offices:Enclosed suites with dedicated infrastructure and brand isolation capabilities. Demand concentrates in Dallas-Fort Worth and Houston where Fortune 500 satellite teams prioritize security compliance and executive confidentiality over cost minimization.
- Dedicated Desks:Permanently assigned workstations within shared environments, typically bundled with lockable storage and reserved seating. Austin venture-backed firms favor this tier for engineering teams requiring equipment permanence without full office overhead.
- Hot Desks:Unassigned seating accessed on-demand through membership credentials. Nashville consultants and itinerant professionals drive utilization.
- Meeting Rooms:Bookable conference facilities with AV infrastructure and presentation capabilities. Corporate procurement teams negotiate block reservations as satellite office supplements.
Private offices dominate installed base revenue contribution. Hot desks are where expansion concentrates as operators pursue volume-driven membership models.
Client Type:
Customer scale determines contract structure, with individual freelancers generating transactional revenue while corporate accounts anchor predictable income streams.
- Freelancers:Individual professionals purchasing month-to-month or day-pass access. IRS Section 179 deduction eligibility reduces effective cost burden for qualifying independent contractors in Texas metros.
- Startups:Venture-funded companies preserving capital for R&D rather than commercial lease commitments. Austin and Nashville show concentrated demand from Series A and B stage firms.
- Small Enterprises:Regional businesses with 10-50 employees seeking geographic flexibility without headquarters relocation. Houston energy services firms utilize this tier for field office deployment.
- Corporations:Fortune 500 and large enterprise procurement teams negotiating outcome-based contracts tied to utilization metrics. Dallas-Fort Worth anchors this segment through regional headquarters concentration.
Corporations command the steepest expansion trajectory as procurement centralization displaces fragmented individual memberships. Freelancers retain volume leadership in absolute headcount.
Service Model:
Revenue predictability scales with commitment duration, from transactional hourly access to multi-year corporate partnerships.
- Membership-based:Recurring monthly or annual subscriptions with tiered access privileges. Standard model for dedicated desk and private office inventory.
- Pay-as-you-go:Hourly or daily rates without ongoing commitment. Captures sporadic demand from remote workers and traveling professionals.
- Partnership:Strategic alliances with property owners, universities, or corporate sponsors. WeWork's asset-light turnaround relies on this structure.
- Corporate Packages:Negotiated multi-location access with centralized billing and utilization reporting. Industrious and Regus compete aggressively for this high-margin segment.
Membership-based structures dominate current revenue composition. Corporate packages are climbing the fastest as enterprise procurement teams consolidate vendor relationships.
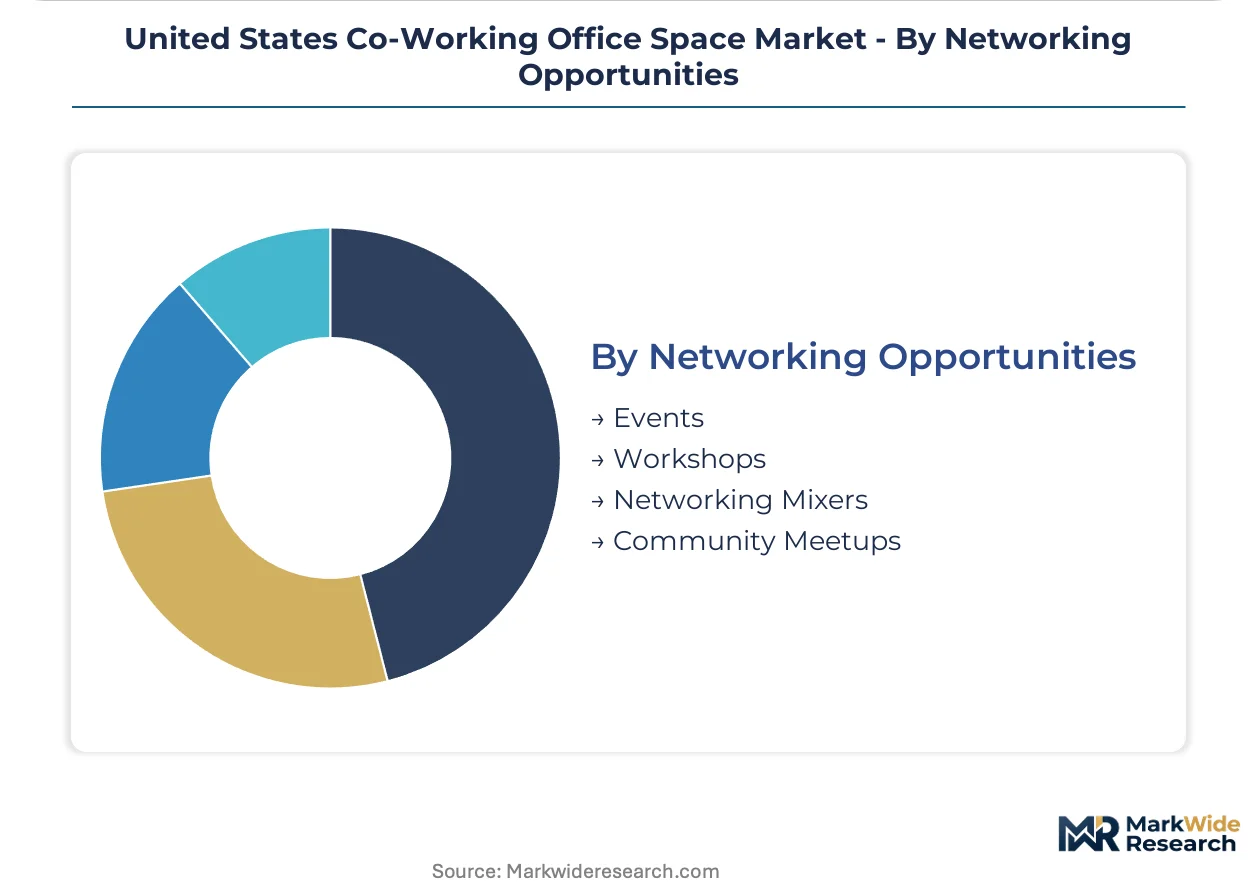
Networking Opportunities:
Programming intensity varies by operator brand positioning, with hospitality-driven models investing heavily in curated community infrastructure.
- Events:Scheduled programming including product launches, panel discussions, and industry conferences. Premium operators in Dallas and Houston differentiate through programming quality.
- Workshops:Skills-based training sessions on technology tools, business development, or regulatory compliance. Startups in Austin leverage these for talent development.
- Networking Mixers:Social gatherings facilitating professional connection across tenant base. Freelancers and small enterprises value these for client acquisition.
- Community Meetups:Self-organized gatherings around shared interests or industry verticals. Nashville's healthcare and music technology clusters show active participation.
Events programming dominates differentiation investment. Workshops are gaining share fastest as operators respond to enterprise demand for value-added services beyond physical space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operator footprints concentrate in high-mobility corridors where corporate satellite deployment and venture-funded startup density overlap. Texas metro corridors anchor national supply expansion, while secondary cities in the South and West emerge as capacity absorption zones.
Texas
Corporate satellite teams from Fortune 500 energy and technology firms drive private office absorption in Dallas-Fort Worth and Houston. OSHA indoor air quality standards shape ventilation specifications for multi-tenant fit-outs, extending pre-opening timelines. Austin's venture-backed startup ecosystem sustains demand for dedicated desk configurations among Series A and B stage companies.
California
Technology sector hybrid work protocols sustain demand for flexible satellite locations across the San Francisco Bay Area and Los Angeles basin. Local building code amendments in San Francisco inflate fit-out costs and trigger permitting complexity for operators. San Diego's life sciences cluster shows emerging demand for compliant private office suites among biotech firms.
New York
Financial services and media enterprise procurement teams consolidate vendor relationships for distributed workforce support across Manhattan and Brooklyn. Municipal zoning board reclassification risks in New York City distort site selection calculus and property tax exposure. Hudson Valley corridor communities absorb overflow demand from Manhattan-based remote workers.
Florida
Professional services firms and healthcare administrators drive membership growth in Miami and Tampa submarkets. State-level business tax incentives reduce effective occupancy costs for qualifying small enterprises. Orlando's simulation and training technology cluster generates specialized demand for secure meeting room infrastructure.
Colorado
Outdoor recreation and software-as-a-service startups favor flexible workspace commitments over traditional commercial leases in Denver and Boulder. ADA compliance mandates across common areas consume additional square footage, compressing revenue per square foot economics. Fort Collins' clean technology cluster shows emerging corporate package adoption among climate-tech scale-ups.
United States Co-Working Office Space Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base organizes around three functional tiers: global network operators with dense geographic footprints, premium hospitality-driven brands capturing occupancy premiums, and asset-light management platforms reducing balance sheet exposure. Competitive moves concentrate on restructuring lease obligations toward short-term management agreements and consolidating enterprise procurement relationships through multi-location corporate packages.
Among global network operators, Regus anchors the scale-driven archetype through its dense secondary city footprint. WeWork occupies a restructuring position emphasizing asset-light partnerships over direct lease exposure. Industrious exemplifies the premium hospitality tier, sustaining rate premiums in Dallas and Houston submarkets through curated amenity programming.
| Leading Market Players |
|---|
| Regus (IWG) |
| WeWork |
| Industrious |
| Spaces (IWG) |
| HQ |
| Venture X |
| Office Evolution |
| Serendipity Labs |
| Expansive |
| Others |
Value Network & Pricing Analysis
Interstate 35 freight corridors connecting Texas distribution hubs to furniture manufacturers in North Carolina and bandwidth infrastructure suppliers in Northern Virginia transmit cost volatility directly into metropolitan workspace pricing. Supply concentration among ergonomic furniture producers and enterprise-grade internet service providers amplifies pricing power for premium hospitality-driven operators while compressing margins in commoditized hot-desk tiers.
Pricing Analysis
IRS Section 179 dictates the pricing tier structure by reducing effective occupancy costs for qualifying small enterprises, creating a three-tier pricing structure across premium hospitality, standard flexible, and economy hot-desk levels. Price differentiation hinges on amenity intensity and geographic submarket prestige, with Dallas-Fort Worth commanding premiums over secondary Texas corridors. Cost compression in economy tiers is intensifying because venture-backed startups prioritize capital preservation over workspace expenditure. Freelancers and independent contractors exhibit highest price sensitivity, while Fortune 500 procurement teams prioritize outcome-based utilization metrics over per-square-foot economics.
Supply Chain Analysis
Ergonomic furniture feedstock draws from manufacturing clusters in China, Vietnam, and Mexico, with final assembly concentrated in North Carolina and Michigan industrial corridors. Enterprise bandwidth infrastructure rests on fiber optic cable networks, server hardware, and HVAC climate control systems sourced from domestic technology distributors. Single-source vulnerability concentrates in specialized acoustic paneling and smart building sensor suppliers. Distribution runs through regional logistics hubs in Dallas, Houston, and Austin before final mile delivery to fit-out sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States co-working office space market constitutes a high-growth disruption anchored by hybrid workforce protocols and IRS Section 179 tax incentives reshaping small enterprise real estate decisions.
For Market Incumbents: Insulate margin pools by accelerating asset-light management agreement conversions away from legacy direct lease exposure, and deepen backward integration into proprietary workspace technology stacks to differentiate against WeWork's partnership-driven turnaround. Threat concentration sits with municipal zoning reclassification risks in New York City and San Francisco triggering permitting delays and property tax reassessments. For New Entrants and Emerging Players: Pursue underpenetrated secondary city expansion in Nashville and Austin submarkets where venture-backed startup density exceeds incumbent supply, and target corporate package procurement relationships with Fortune 500 regional headquarters in Texas metro corridors. White-space concentration favors dedicated desk configurations for Series A and B stage technology firms seeking equipment permanence without full office overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors premium hospitality-driven operators with demonstrated occupancy rate premiums in Dallas and Houston submarkets. Long-term viability across the analysis window hinges on enterprise procurement consolidation trends and outcome-based contract adoption. Signal concentration centers on management agreement structure penetration as a share of total revenue portfolio.| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Partnership Conversion | WeWork's restructuring demonstrates reduced balance sheet exposure while preserving recurring fee income streams. |
| Enterprise Corporate Package Expansion | Industrious and Regus compete for Fortune 500 satellite team contracts with centralized billing and utilization reporting. |
| Smart Building Technology Integration | Dallas and Houston enterprise clients mandate unified environmental control and security access platforms as baseline requirements. |
| Secondary City Geographic Expansion | Nashville and Austin submarkets absorb capacity beyond saturated primary metros with lower fit-out cost structures. |
| Workshop Programming Differentiation | Austin startups leverage skills-based training for talent development, displacing pure physical space commoditization. |
Research Methodology
A standing panel of workspace operators, commercial real estate brokers, Fortune 500 facility managers, and municipal zoning officials provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against SEC operator filings, commercial lease transaction databases, and municipal permitting records. Bottom-up site-level revenue modeling triangulated against top-down metro corridor demand projections.
Scenario-bracketing framed low, base, and high cases across workspace type, client scale, and service model dimensions over the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated IRS Section 179 policy continuity assumptions and hybrid workforce protocol persistence metrics.
Sensitivities concentrate around municipal zoning reclassification timelines and OSHA indoor air quality standard enforcement intensity. Cross-checking against commercial real estate investment trust disclosures and CoStar lease comparables is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Flexible Office Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Bahrain Flexible Office Space Market