
 UAE Commercial Real Estate Market | 2026-2036
UAE Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Commercial Real Estate Market Analytics
Institutional capital is reorganizing the buyer landscape for UAE commercial real estate, displacing individual investors as the dominant transaction counterparty. Emaar Properties leverages its integrated development model to capture premium office yields in Dubai's prime corridors. Aldar Properties anchors Abu Dhabi's non-oil economic diversification through large-scale mixed-use masterplans on Al Reem Island. DAMAC Properties differentiates via hospitality-linked commercial assets that blend retail and serviced office concepts.
UAE commercial real estate comprises income-generating built assets designed for business operations, typically constructed with reinforced concrete frames, curtain wall glazing systems, and integrated MEP infrastructure rated for 12-16 hour daily occupancy cycles. Office spaces command the deepest liquidity pools among property types, while mixed-use developments are capturing accelerated capital allocation as developers seek revenue diversification across lease streams. Co-working spaces within the lease type dimension are expanding fastest, though long-term leases still generate the most predictable institutional cash flows.
MOHAP's healthcare facility standards and the UAE Central Bank's real estate exposure limits for financial institutions jointly shape development feasibility and financing access. Dubai's Department of Economy and Tourism enforces commercial space utilization codes that restrict residential conversion of designated office inventory. Stakeholders must monitor how Abu Dhabi's Economic Vision targets recalibrate permitted floor area ratios across new free zone permits.
Market Dynamics
Institutional capital concentration is compressing transaction timelines and elevating due diligence standards across UAE commercial real estate, as sovereign wealth funds and pension managers displace high-net-worth individuals in prime asset bidding.
Growth Catalysts
- MOHAP Healthcare Licensing:The Ministry of Health and Prevention's facility standards are redirecting developer capital toward medical-grade commercial spaces with specialized MEP infrastructure.
- Technology Sector Expansion:Cloud computing and fintech firms are absorbing Grade A office inventory in Dubai's Business Bay and DIFC districts at accelerated lease-up velocities.
- Abu Dhabi Economic Vision Recalibration:Permitted floor area ratio adjustments across new free zone permits are unlocking additional developable density on Al Reem Island masterplans.
Market Restraints
- UAE Central Bank Exposure Limits:Real estate lending caps for financial institutions are constraining construction financing access for mid-scale developers without sovereign backing.
- Curtain Wall Supply Concentration:Specialist glazing system fabrication concentrates among a limited supplier base in the GCC, creating input cost volatility for high-specification office towers.
- Residential Conversion Restrictions:Dubai's Department of Economy and Tourism utilization codes permanently remove designated office inventory from alternative use consideration.
Strategic Opportunities
- Al Reem Island Mixed-Use Density:Abu Dhabi's non-oil diversification targets are expanding permitted commercial floorplates within integrated masterplans that blend retail, hospitality, and serviced office concepts.
- Co-Working Lease Innovation:Flexible tenure structures are capturing technology sector demand that traditional 10-year institutional leases cannot accommodate.
- Medical-Grade Infrastructure Arbitrage:Healthcare facility standards create yield premiums for developers capable of delivering reinforced concrete frames with 24-hour MEP redundancy.
Industry Challenges
- Specialized Asset Management Talent:Medical-grade commercial spaces require facility managers with healthcare infrastructure expertise that the current labor pool lacks.
- Integrated Masterplan Coordination:Mixed-use developments demand synchronized phasing across retail, hospitality, and office components, complicating construction sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Commercial Real Estate Market |
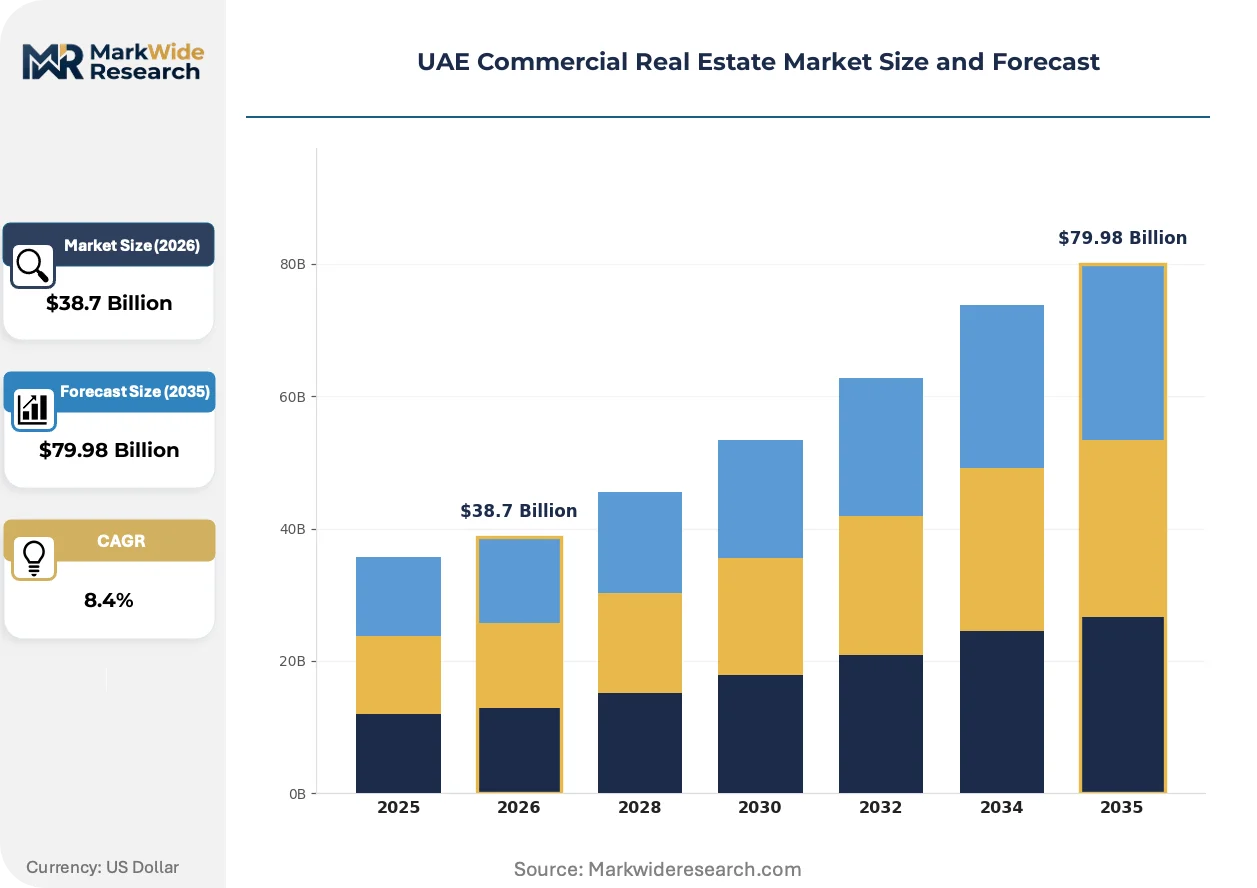
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office Spaces, Retail Outlets, Warehouses, Mixed-Use Developments Investor Type: Institutional Investors, Private Equity Firms, Individual Investors, REITs Lease Type: Long-Term Leases, Short-Term Leases, Co-Working Spaces, Sale-Leaseback End User Industry: Financial Services, Technology, Hospitality, Healthcare |
| Companies Covered | Aldar Properties, Sobha Realty, Emaar Properties, Azizi Developments, Meraas, DAMAC Properties, Dubai Holding, Sharjah Holding, Nakheel Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Commercial Real Estate Market Evolving Landscape
Smart building infrastructure is reconfiguring operational cost structures across UAE commercial assets, with sensor networks and predictive analytics compressing energy expenditures and redefining tenant experience benchmarks.
Internet of Things building management systems are fragmenting traditional facilities management contracts. Institutional landlords in DIFC are deploying edge-computing sensors for real-time occupancy optimization. This technology is fragmenting the bundled service provider market into specialized analytics, hardware, and maintenance verticals.
MOHAP's healthcare facility licensing framework is mandating redundant MEP infrastructure and specialized ventilation standards. Developers targeting medical tenants must pre-certify reinforced concrete frames and curtain wall systems during construction rather than retrofitting. Abu Dhabi's new hospital-adjacent commercial zones are experiencing the most acute compliance timeline pressure.
Tenant procurement of commercial space is compressing decision cycles from 12-month searches to 90-day executions. Technology firms are bypassing traditional brokerage channels for direct developer relationships with pre-fitted, sensor-enabled inventory. Dubai's Business Bay corridor exhibits the most pronounced channel disintermediation as co-working operators capture demand that would previously have flowed to long-term lease negotiations.
UAE Commercial Real Estate Market Segmentation
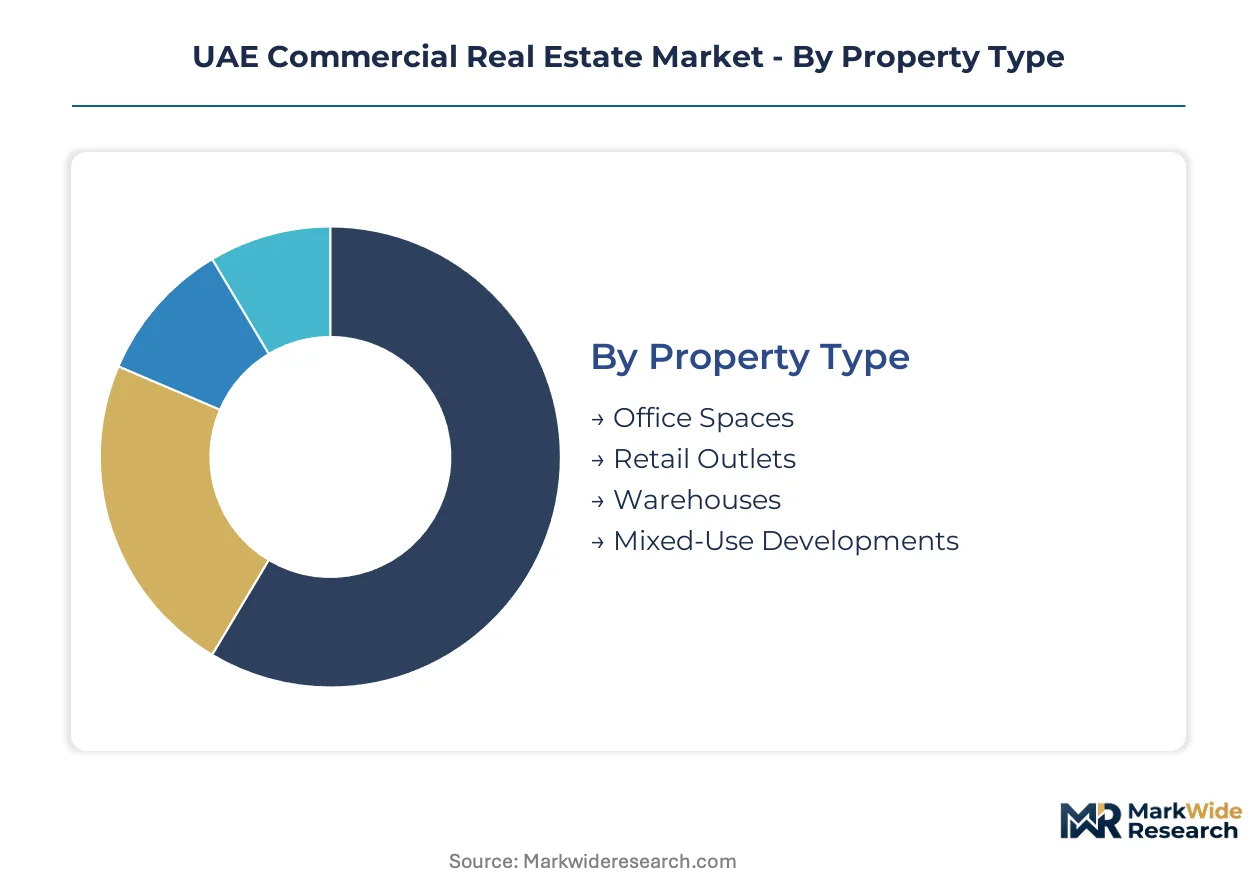
Segmentation in UAE commercial real estate reveals how capital allocation, tenant preferences, and regulatory frameworks fragment across distinct asset classes and stakeholder profiles. Understanding these divisions exposes where liquidity concentrates and where structural barriers create arbitrage opportunities for specialized developers and investors.
Property Type:
Geographic demand concentration varies sharply across property categories, with some segments driven almost entirely by domestic institutional mandates while others attract cross-border capital flows.
- Office Spaces:Grade A inventory in Dubai's Business Bay and DIFC districts commands the deepest liquidity pools among all property types. Reinforced concrete frames with curtain wall glazing systems dominate construction specifications. Demand concentrates among technology and financial services tenants seeking 12-16 hour daily occupancy ratings with integrated MEP infrastructure.
- Mixed-Use Developments:These assets blend retail, hospitality, and serviced office concepts within single masterplans. Aldar Properties anchors Abu Dhabi's supply on Al Reem Island, where Economic Vision targets recalibrate permitted floor area ratios. Institutional capital favors these assets for revenue diversification across multiple lease streams.
- Retail Outlets:Ground-floor commercial space within integrated developments captures hospitality-linked foot traffic.
- Warehouses:Logistics facilities serve last-mile distribution networks radiating from Dubai's Jebel Ali corridor.
Office spaces hold the largest share; momentum sits with mixed-use developments.
Investor Type:
Capital deployment strategies diverge sharply between domestic sovereign-backed entities and international private capital seeking yield compression in prime corridors.
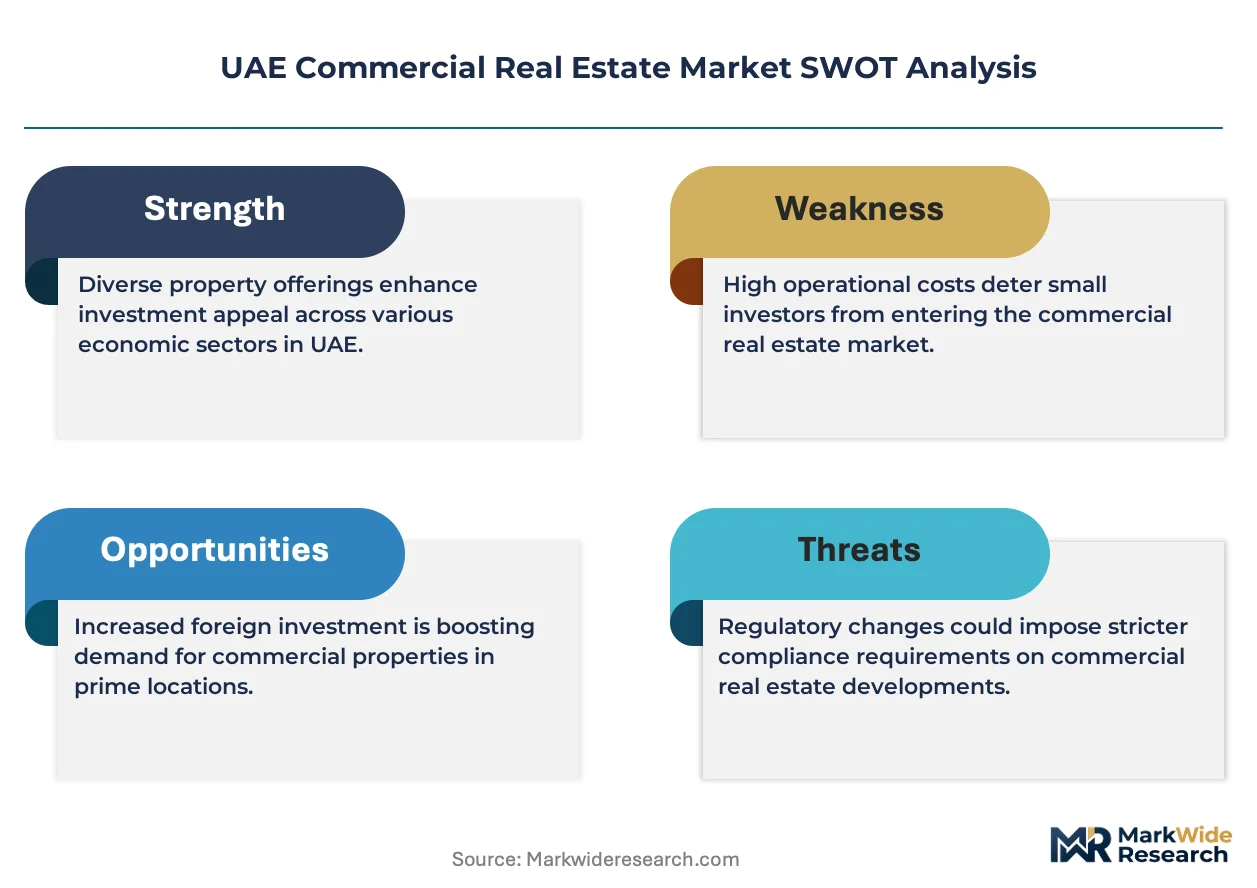
- Institutional Investors:Sovereign wealth funds and pension managers displace high-net-worth individuals as the dominant transaction counterparty in prime asset bidding. These entities compress due diligence timelines and elevate governance standards across portfolio acquisitions.
- Private Equity Firms:Opportunistic capital targets value-add repositioning of secondary office stock and development-stage mixed-use projects. These firms exploit construction financing gaps created by UAE Central Bank exposure limits affecting mid-scale developers.
- Individual Investors:Retail capital concentrates in smaller retail units and strata-titled office floors.
- REITs:Listed vehicles provide institutional liquidity for stabilized income-generating assets.
Institutional investors dominate transaction volume; private equity firms are expanding most quickly.
Lease Type:
Tenure structure preferences fragment across tenant sophistication levels, with technology sector demand driving innovation in flexible contract formats.
- Co-Working Spaces:Flexible tenure structures capture technology sector demand that traditional 10-year institutional leases cannot accommodate. Dubai's Business Bay corridor exhibits the most pronounced channel disintermediation as operators bypass traditional brokerage channels for direct developer relationships.
- Long-Term Leases:Institutional landlords in DIFC favor these contracts for predictable cash flow generation. Financial services and healthcare tenants accept rigid terms in exchange for specialized MEP infrastructure and medical-grade facility certifications.
- Short-Term Leases:Seasonal hospitality and event-driven retail operators favor these structures.
- Sale-Leaseback:Corporate occupiers monetize owned real estate while retaining operational control.
Long-term leases generate the most institutional capital; co-working spaces are gaining share fastest.
End User Industry:
Tenant sector concentration determines MEP specification requirements and drives location clustering within Dubai and Abu Dhabi's prime corridors.
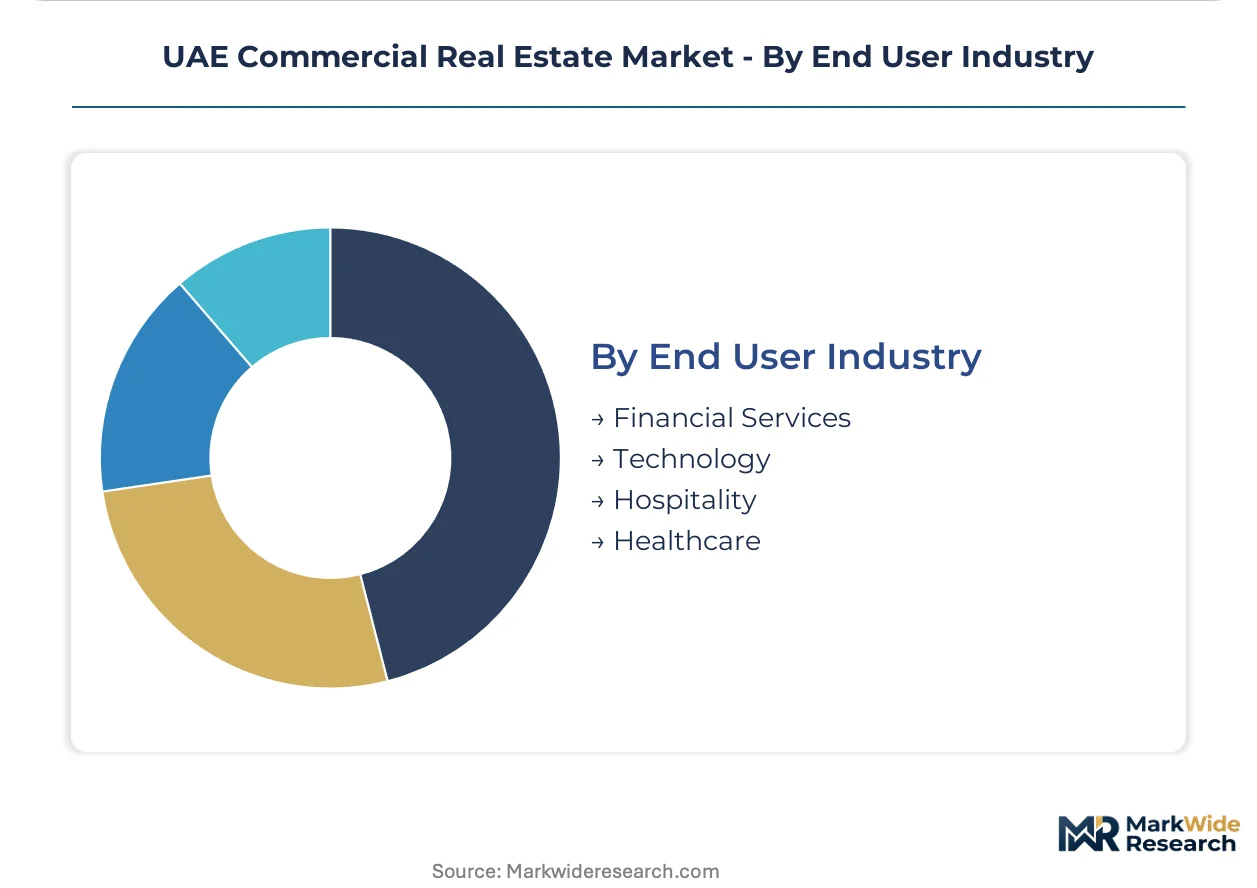
- Financial Services:Banking and asset management firms anchor demand in DIFC and Abu Dhabi Global Market districts. These tenants require redundant power systems, dedicated server room infrastructure, and compliance with financial regulator physical security mandates.
- Healthcare:MOHAP facility licensing standards redirect developer capital toward medical-grade commercial spaces with 24-hour MEP redundancy and specialized ventilation. Abu Dhabi's hospital-adjacent commercial zones experience acute compliance timeline pressure.
- Technology:Cloud computing and fintech firms absorb Grade A inventory at accelerated lease-up velocities.
- Hospitality:Hotel operators and serviced apartment concepts blend retail and accommodation functions.
Financial services occupies the largest floorplate share; healthcare demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional capital concentration across the UAE commercial real estate sector is compressing transaction timelines and elevating due diligence standards. Sovereign wealth funds and pension managers now displace high-net-worth individuals as the dominant transaction counterparty in prime asset bidding. This buyer-archetype shift concentrates liquidity in Dubai and Abu Dhabi's prime corridors while marginalizing secondary markets.
Dubai
Technology and financial services firms drive Grade A office absorption in Business Bay and DIFC districts. Dubai's Department of Economy and Tourism enforces commercial space utilization codes that permanently restrict residential conversion of designated office inventory. The Business Bay corridor exhibits pronounced channel disintermediation as co-working operators capture demand previously flowing to traditional lease negotiations.
Abu Dhabi
Aldar Properties anchors non-oil economic diversification through large-scale mixed-use masterplans on Al Reem Island. Abu Dhabi's Economic Vision recalibrates permitted floor area ratios across new free zone permits, unlocking additional developable density. Hospital-adjacent commercial zones experience acute compliance timeline pressure under MOHAP healthcare facility standards.
Sharjah
Sharjah Holding develops commercial assets targeting cost-conscious tenants priced out of Dubai prime corridors. The emirate's cultural and educational institutions generate steady demand for mid-tier office and retail space. Industrial-commercial hybrid zones near the Dubai border capture logistics and light manufacturing tenants.
Northern Emirates
Ras Al Khaimah and Fujairah concentrate hospitality-linked commercial development serving tourism and port logistics. Federal infrastructure investment connects these emirates to Dubai-Abu Dhabi economic corridors. Limited Grade A office supply constrains institutional capital deployment despite improving connectivity.
UAE Commercial Real Estate Market Competitive Landscape
Player mix skews toward integrated masterplan developers with sovereign backing or deep balance sheets. Market structure concentrates around three to five vertically integrated entities capable of delivering mixed-use schemes at scale. Strategic archetypes include sovereign-linked masterplan specialists, hospitality-anchored commercial developers, and premium office yield optimizers. Competitive moves center on land bank accumulation through government concession agreements and portfolio diversification across lease streams.
Within the integrated masterplan tier, Aldar Properties and Emaar Properties exemplify divergent geographic strategies while occupying comparable structural positions. DAMAC Properties represents the hospitality-linked commercial archetype, blending retail and serviced office concepts. These three developers anchor the competitive set, with Aldar commanding Abu Dhabi supply, Emaar dominating Dubai prime corridors, and DAMAC differentiating through asset-type innovation rather than geographic concentration.
| Leading Market Players |
|---|
| Aldar Properties |
| Sobha Realty |
| Emaar Properties |
| Azizi Developments |
| Meraas |
| DAMAC Properties |
| Dubai Holding |
| Sharjah Holding |
| Nakheel Properties |
| Others |
Value Network & Pricing Analysis
MOHAP's healthcare facility certification framework gates both supplier qualification and price differentiation simultaneously, as developers must pre-certify reinforced concrete frames and curtain wall systems during construction rather than retrofitting, embedding compliance costs into base pricing tiers that separate medical-grade from standard commercial inventory.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate construction procurement for Grade A office towers in Dubai's Business Bay corridor. Three-tier pricing structure across premium, standard, and economy levels reflects curtain wall specification grades and MEP redundancy ratings. Price differentiation hinges on 24-hour infrastructure certification and integrated smart building sensor networks. Mid-scale developers face acute margin compression because UAE Central Bank exposure limits restrict their construction financing access, forcing reliance on higher-cost private credit.
Supply Chain Analysis
Curtain wall glazing system inventory cycles stretch 16-20 weeks for high-specification office towers, constraining project phasing flexibility. Specialist fabrication concentrates in China, Germany, and the UAE, with tempered glass and aluminum extrusions drawing from concentrated GCC supplier bases. Single-source vulnerability pervades medical-grade MEP component sourcing for MOHAP-compliant facilities. Distribution runs through vertically integrated masterplan developers who control specification standards across their portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE commercial real estate sector sits at a platform-economics inflection as smart building infrastructure fragments traditional facilities management into specialized analytics, hardware, and maintenance verticals, with interoperability between sensor networks and tenant experience platforms determining competitive positioning.
For Market Incumbents: Compound land bank advantages through government concession agreements on Al Reem Island and Business Bay corridor extensions before floor area ratio adjustments attract competing bids. Deepen backward integration into curtain wall fabrication to offset GCC supplier concentration risk. Prioritize certification investment for MOHAP medical-grade infrastructure standards to capture healthcare tenant yield premiums. For New Entrants and Emerging Players: Anchor in co-working lease innovation gaps that institutional landlords in DIFC cannot address due to rigid cash flow mandates. Target technology sector demand in Dubai's Business Bay corridor where channel disintermediation bypasses traditional brokerage relationships. Pursue direct developer partnerships for pre-fitted, sensor-enabled inventory rather than competing for speculative development sites. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed value-add repositioning funds holding secondary office stock in Dubai's peripheral districts. Long-term viability across the analysis window rests on mixed-use revenue diversification rather than single-asset class concentration. Monitor Abu Dhabi Economic Vision floor area ratio recalibrations as the inflection signal for deployable density expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Infrastructure Certification | MOHAP compliance unlocks yield premiums for 24-hour MEP redundancy in hospital-adjacent zones. |
| Smart Building Platform Integration | Edge-computing sensor deployment fragments facilities management contracts across DIFC institutional portfolios. |
| Co-Working Lease Structure Innovation | Flexible tenure captures technology sector demand that traditional 10-year institutional leases exclude. |
| Backward Integration into Glazing Systems | Captive supply of curtain wall components mitigates GCC fabrication concentration and input cost volatility. |
| Mixed-Use Masterplan Density Expansion | Al Reem Island floor area ratio adjustments unlock additional commercial floorplates under Abu Dhabi Economic Vision targets. |
Research Methodology
Desk research of regulatory filing databases, construction permit records, and institutional investor disclosure documents preceded structured interviews with sovereign wealth fund portfolio managers, healthcare facility developers, commercial leasing directors, and smart building technology vendors. Primary fieldwork validated secondary data on MOHAP certification timelines and curtain wall supply concentration. Bottom-up project pipeline analysis triangulated against top-down capital flow estimates from pension manager allocation disclosures.
Variance decomposition across property type, lease structure, end-user industry, and geographic sub-market segments informed the analytical framework. Modeled dimensions included office grade tier, medical certification status, technology sector absorption velocity, and free zone regulatory framework. CAGRs derived from fitted trend extrapolation with scenario-weighted adjustments for policy recalibration events. Forecast inputs incorporated MOHAP licensing queue depths and Economic Vision floor area ratio amendment schedules.
Decision-makers should treat outputs as directional under assumptions of continued UAE Central Bank exposure limit enforcement and sustained technology sector office absorption; material deviation would warrant model refresh. Revision becomes warranted when healthcare facility licensing backlogs cross 18-month clearance thresholds or when sovereign wealth fund allocation caps to real estate shift substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market