
 India Residential Construction Market | 2026-2036
India Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India Residential Construction Market Insights
Buyer concentration among first-time purchasers is expanding across tier-2 and tier-3 cities as affordable housing schemes broaden access. DLF Limited leverages its land bank dominance in the National Capital Region to sustain premium project pipelines. Godrej Properties anchors its position through green-certified developments, while Sobha Limited differentiates via backward integration into concrete manufacturing and interior fit-outs.
India residential construction encompasses the design, engineering, and assembly of dwellings ranging from single-story brick-and-concrete units to high-rise steel-frame apartments, typically employing load-bearing masonry or reinforced concrete frame methods with M20 to M30 grade concrete for structural integrity. The sector serves shelter provision, asset accumulation, and rental income generation across urban and semi-urban settlements. Multi-family units and apartments capture the dominant volume share as urban land scarcity intensifies vertical development, while single-family homes retain margin concentration in peripheral suburbs where plot availability permits larger footprints. Concrete construction material leads structural deployment due to cost efficiency and seismic resilience, though steel is gaining traction in high-rise segments for faster erection cycles.
BIS certification mandates govern cement and steel quality standards, while RERA enforcement at state level compels project transparency and escrow-based fund management, tightening developer accountability. The CEA's building energy codes and state-level municipal bylaws on floor area ratios shape permissible density and construction specifications. Stakeholders must monitor how PMAY subsidy disbursement velocity and state RERA tribunal efficiency determine working capital cycles and pre-sale conversion rates.
Market Dynamics
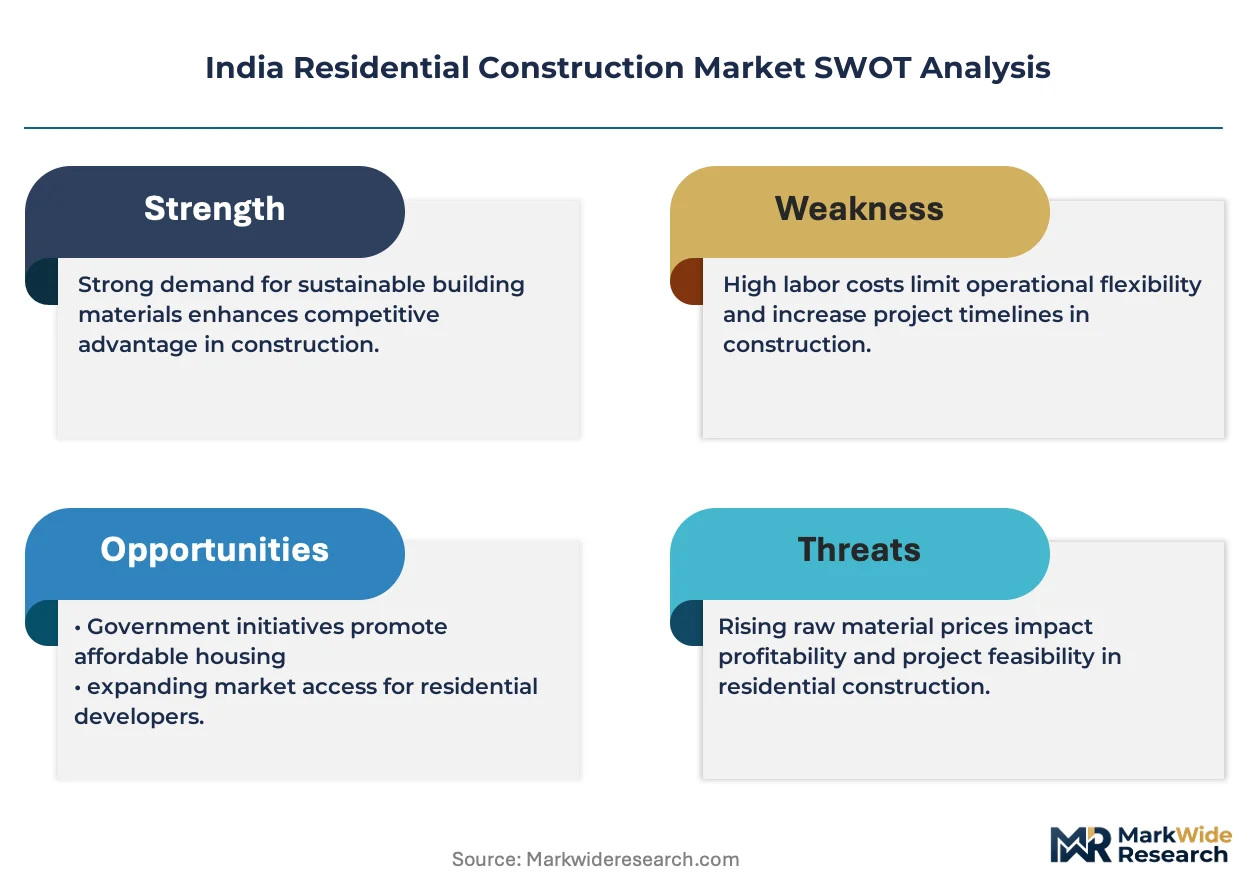
India's residential construction sector confronts a fundamental tension between RERA-mandated project transparency and the working capital squeeze from escrow-based fund management, forcing developers to restructure pre-sale financing models.
Growth Catalysts
- PMAY subsidy velocity:Interest subvention schemes accelerate first-time buyer conversion in tier-2 cities, compressing downpayment accumulation timelines.
- Maharashtra's single-window clearance:State-level digitization of building approvals cuts project gestation periods, unlocking land bank monetization.
- M30 grade concrete adoption:Higher-strength mix designs enable thinner structural sections, reducing material intensity per square foot.
Market Restraints
- Cement price volatility:Input cost swings from petcoke and diesel freight erode fixed-price contract margins.
- Reinforcing steel import dependence:Concentrated sourcing from select ports exposes projects to rupee-dollar fluctuation risk.
- BIS certification bottlenecks:Testing lab capacity constraints delay quality clearance for alternative cement blends.
Strategic Opportunities
- Telangana's peripheral municipalities:Hyderabad's ring road expansion opens greenfield plotted development zones with lower floor area ratios.
- CEA building energy code convergence:Thermal performance mandates create retrofit demand for insulation-integrated wall systems.
- Direct-to-buyer digital channels:Virtual site tours and e-stamp registration compress brokerage-dependent discovery cycles.
Industry Challenges
- Structural engineer scarcity:Specialized seismic design expertise concentrates in Mumbai and Bengaluru, constraining tier-2 project execution.
- RERA tribunal backlog:Dispute resolution delays tie up escrow releases, straining subcontractor payment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Residential Construction Market |
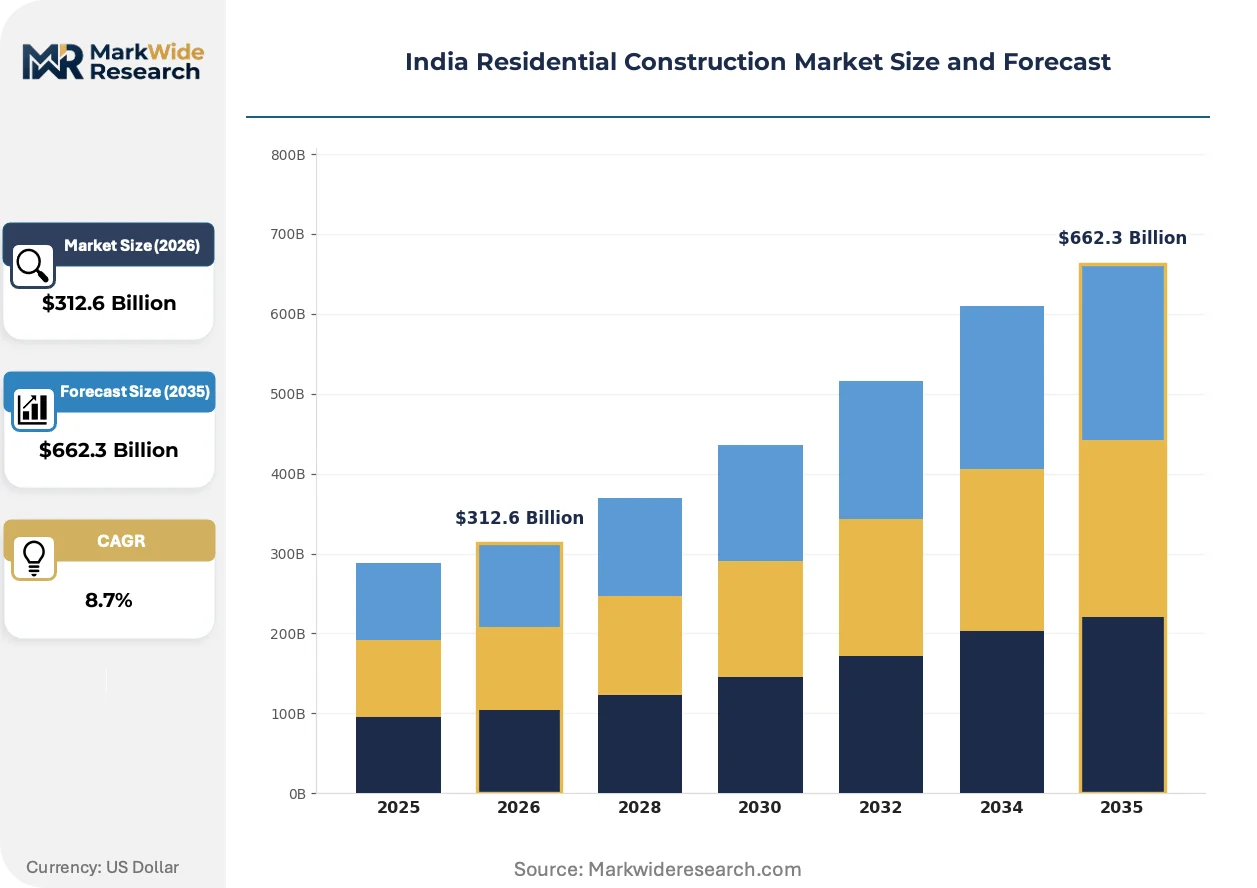
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-family Homes, Multi-family Units, Villas, Apartments End User: First-time Buyers, Real Estate Investors, Families, Retirees Construction Material: Concrete, Steel, Brick, Wood Design Style: Modern, Traditional, Eco-friendly, Minimalist |
| Companies Covered | DLF Limited, Godrej Properties, Prestige Estates Projects, Lodha Group, Macrotech Developers, Sobha Limited, Oberoi Realty, L&T Realty, Brigade Enterprises, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Residential Construction Market Trends and Innovations
Material substitution and regulatory digitization are compressing traditional construction timelines while reshaping developer-buyer interaction models across Indian metros.
Prefabricated bathroom pods are electrifying vertical construction efficiency. High-rise developers in Bengaluru and Hyderabad now specify factory-cast wet modules for 40-plus storey towers, cutting floor-cycle duration from 14 days to 9 days. This standardization is electrifying competitive pressure on conventional masonry-based contractors.
RERA's mandate for quarterly project disclosure is tightening information asymmetry. Developers must upload construction progress photographs and fund utilization statements to state portals, exposing delayed milestones to buyer scrutiny. Maharashtra and Karnataka have deployed AI-based document verification to flag escrow diversion attempts.
First-time buyers in tier-2 cities now complete purchase decisions through video-conducted site visits and digital payment of booking amounts. Developers in Lucknow and Indore have shifted 60 percent of pre-launch lead generation to WhatsApp-integrated CRM platforms, bypassing traditional broker networks. This channel compression is most visible in Telangana's municipal corporation zones with online mutation facilities.
India Residential Construction Market Segmentation
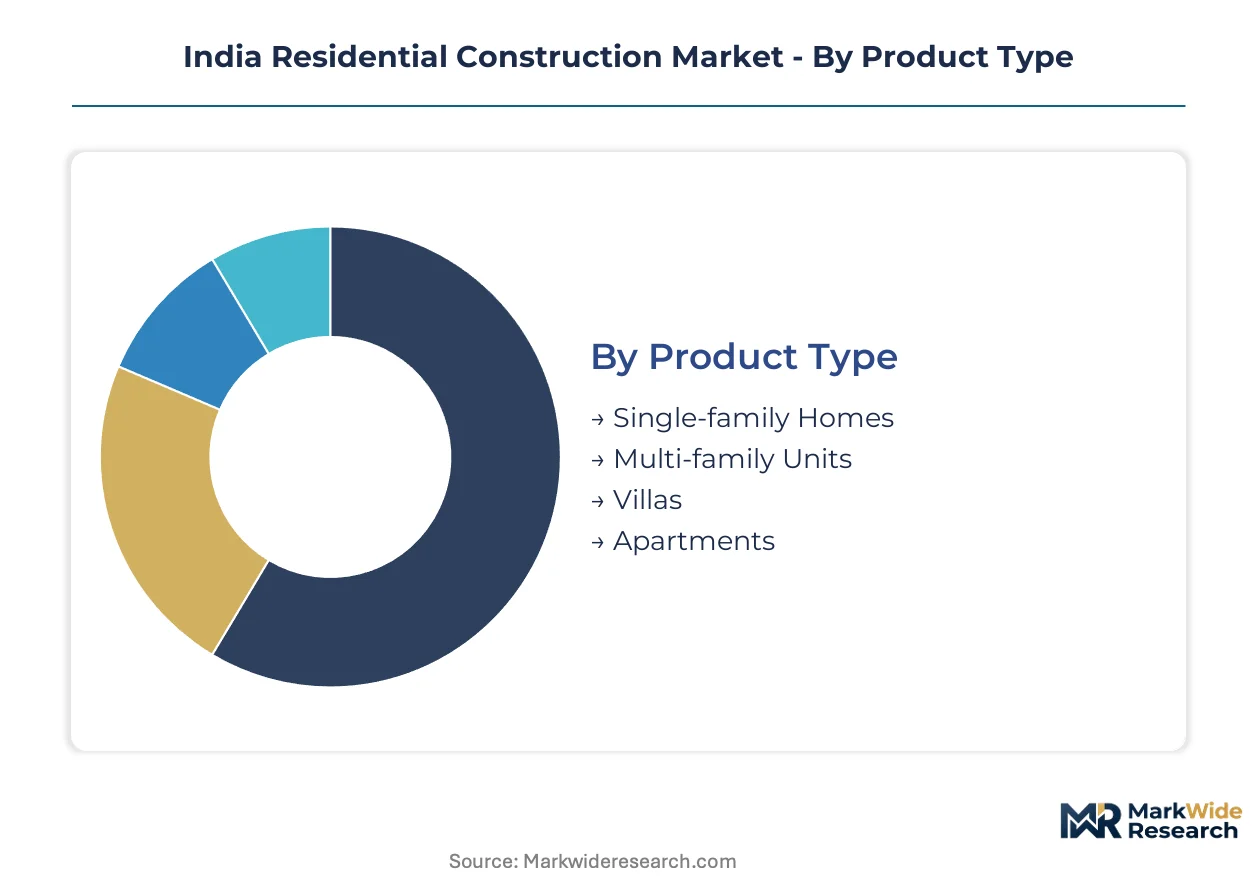
Residential construction in India fragments across buyer life stages, structural methods, and aesthetic preferences. Each segmentation axis carries distinct regulatory exposure and margin profiles that determine developer capital allocation across project pipelines.
Product Type:
Urban land scarcity and PMAY subsidy targeting reshape buyer trade-offs between density and footprint.
- Single-family Homes:Load-bearing masonry construction on individual plots dominates peripheral suburbs of Hyderabad and Pune. Retiree demand in Telangana's ring road municipalities sustains premium pricing for gated plotted developments with larger setbacks.
- Multi-family Units:Reinforced concrete frame structures with shared walls optimize land use in Bengaluru and Mumbai's extended suburbs. RERA escrow requirements compress developer margins on these volume-driven projects where pre-sale velocity determines working capital health.
- Villas:Low-rise independent dwellings with private open areas concentrate in Maharashtra's satellite townships where floor area ratios permit horizontal expansion.
- Apartments:High-rise towers above 15 storeys employ M30 grade concrete and prefabricated bathroom pods to accelerate floor cycles in dense urban cores.
Volume sits with Apartments; growth tilts toward Multi-family Units.
End User:
Purchaser financing access and subsidy eligibility segment the market into distinct sales cycle durations.
- First-time Buyers:Credit-linked subsidy scheme beneficiaries in Lucknow and Indore drive affordable housing absorption. Digital booking channels and WhatsApp-integrated CRM platforms compress discovery-to-decision timelines for this price-sensitive cohort.
- Real Estate Investors:Rental yield seekers target under-construction units in Karnataka's municipal corporation zones with online mutation facilities. RERA-mandated quarterly disclosures reduce information asymmetry for speculative capital deployment.
- Families:Multi-generational households prioritize 3-bedroom configurations in tier-2 cities where state-level single-window clearances accelerate project delivery.
- Retirees:Senior living demand concentrates in Pune and Coimbatore where healthcare infrastructure proximity commands location premiums.
First-time Buyers dominate transaction volume; investor participation is climbing the fastest as rental markets formalize.
Construction Material:
Seismic code compliance and cost volatility determine structural system selection across India's earthquake-prone zones.
- Concrete:M20 to M30 grade reinforced concrete frames provide seismic resilience for mid-rise construction. BIS certification mandates govern cement quality standards while petcoke price swings erode fixed-contract margins.
- Steel:High-rise towers in Mumbai and Bengaluru specify structural steel for faster erection cycles above 40 storeys. Rupee-dollar fluctuation risk concentrates around select port-dependent import corridors.
- Brick:Fired clay masonry retains cost advantage in low-rise plotted developments where load-bearing walls suffice.
- Wood:Engineered timber gains niche traction in hill station retirement homes where aesthetic differentiation commands premium positioning.
Concrete commands structural deployment volume; steel is gaining share fastest in vertical construction segments.
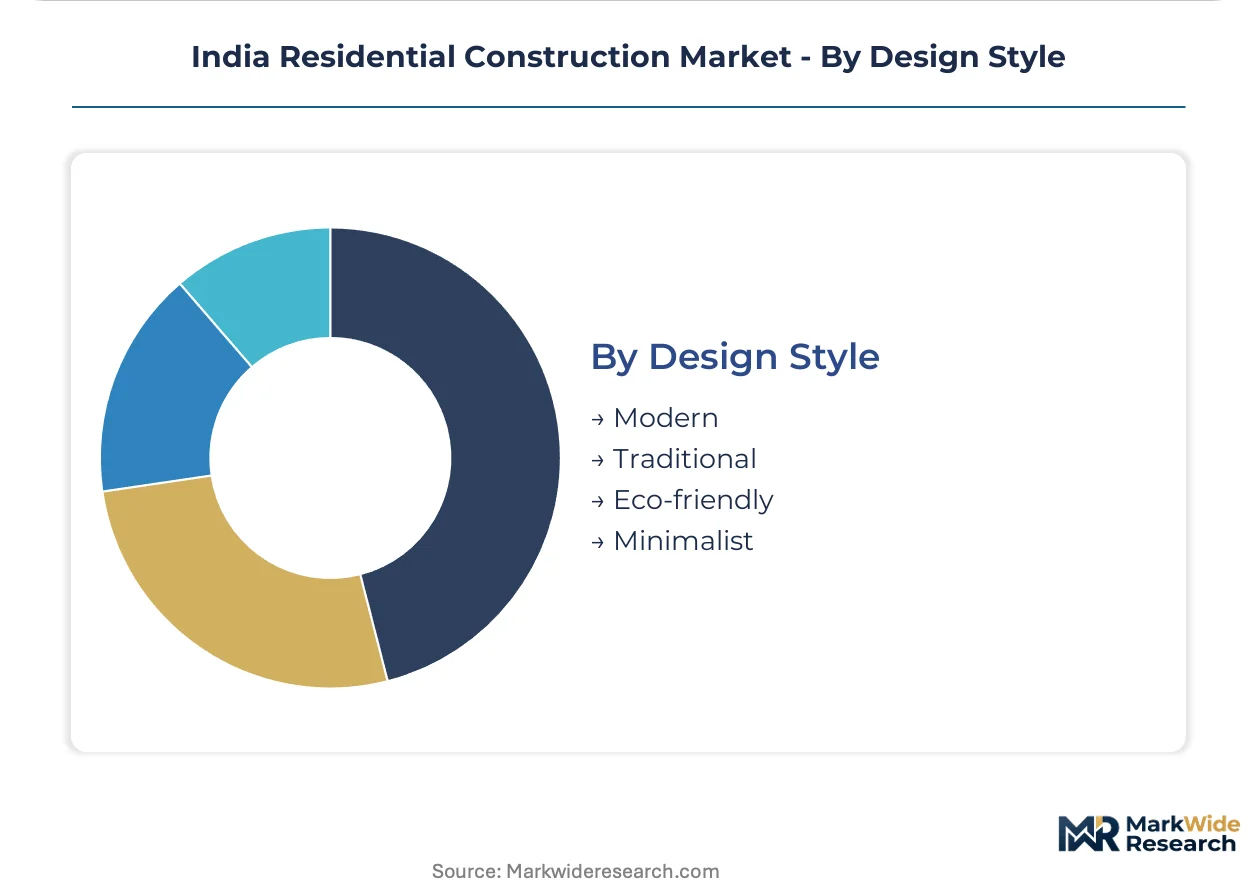
Design Style:
Energy code convergence and certification premiums segment aesthetic positioning into distinct cost tiers.
- Modern:Clean-line architecture with open floor plans dominates NCR premium projects where DLF Limited leverages land bank scale. Glass curtain walls and integrated HVAC systems align with CEA building energy code thermal performance mandates.
- Traditional:Courtyard-centric layouts and regional facade treatments retain preference in Rajasthan and Kerala where cultural continuity influences purchase decisions.
- Eco-friendly:Green-certified developments anchor Godrej Properties' positioning through rainwater harvesting and solar thermal integration. IGBC rating premiums justify 8-12 percent price elevation in Bengaluru's IT corridor.
- Minimalist:Reduced material palettes and optimized spatial efficiency target urban millennial buyers in Hyderabad's financial district.
Modern styling captures volume leadership; eco-friendly certification represents the steepest expansion trajectory as energy codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyer demand concentrates in Maharashtra, Karnataka, and Telangana, where state-level housing policies accelerate project approvals and PMAY subsidies compress downpayment timelines for affordable housing absorption.
Maharashtra
Mumbai's extended suburbs and Pune's ring road municipalities drive multi-family unit absorption among credit-linked subsidy beneficiaries. The state's single-window clearance digitization cuts building approval gestation periods, unlocking land bank monetization for developers. Thane and Navi Mumbai industrial corridors concentrate high-rise construction employing M30 grade concrete for seismic resilience.
Karnataka
Bengaluru's IT corridor anchors premium apartment demand from rental yield investors targeting under-construction units with online mutation facilities. State RERA tribunal efficiency determines escrow release velocity and subcontractor payment cycles. Mysuru and Mangaluru tier-2 markets expand first-time buyer conversion through WhatsApp-integrated CRM platforms.
Telangana
Hyderabad's financial district fuels minimalist design preference among urban millennial buyers, while peripheral municipalities open greenfield plotted development zones. State-level municipal corporation zones with online mutation facilities enable digital booking channel compression. Warangal and Karimnagar satellite markets absorb affordable housing stock.
Gujarat
Ahmedabad and Surat industrial belt expansion sustains family housing demand for multi-generational 3-bedroom configurations. Gujarat RERA enforcement mandates quarterly project disclosure and fund utilization transparency. Gandhinagar's planned infrastructure proximity commands retiree location premiums in senior living segments.
Tamil Nadu
Chennai's extended suburbs and Coimbatore's healthcare infrastructure proximity drive retiree demand for senior living developments. State-level building energy code convergence creates retrofit demand for insulation-integrated wall systems. Salem and Tiruchirappalli tier-2 markets benefit from PMAY interest subvention velocity accelerating purchase decisions.
India Residential Construction Market Competitive Landscape
Delhi-NCR producers anchor the premium tier through land bank dominance; Mumbai and Bengaluru specialists hold volume-driven positions in high-rise vertical construction. The market structure fragments across three operational scales: national developers with multi-city pipelines, regional specialists concentrating in single-state clusters, and local plotted development players. Strategic archetypes include land bank aggregators, green-certified positioning specialists, and backward-integrated contractors controlling concrete manufacturing. Competitive moves center on geographic pipeline diversification and captive supply chain control over structural materials.
Within the land bank aggregation tier, DLF Limited exemplifies NCR-centric scale positioning through premium project pipelines. Godrej Properties and Sobha Limited occupy differentiated archetypes: the former anchors green-certified development positioning, while the latter represents manufacturing-integrated construction control through captive concrete and interior fit-out production. These three developers illustrate how capital allocation diverges between geographic concentration, certification premiums, and upstream supply chain integration across India's residential construction sector.
| Leading Market Players |
|---|
| DLF Limited |
| Godrej Properties |
| Prestige Estates Projects |
| Lodha Group |
| Macrotech Developers |
| Sobha Limited |
| Oberoi Realty |
| L&T Realty |
| Brigade Enterprises |
| Others |
Pricing and Supply Chain Analysis
Prefabricated bathroom pod adoption in high-rise Bengaluru and Hyderabad towers simultaneously compresses floor-cycle economics and concentrates procurement leverage among factory-scale wet-module suppliers. This production-method transition reshapes developer cost structures while elevating port-dependent cement and steel sourcing as the dominant pricing pressure vectors.
Pricing Analysis
Volume concentrates in affordable multi-family units where PMAY subsidy eligibility compresses developer margins, while premium plotted developments in Telangana's ring road municipalities retain pricing power through land scarcity. Three-tier pricing structure across premium, standard, and economy levels separates IGBC-certified green projects from RERA-compliant baseline stock and unsubsidized peripheral inventory. Cost compression in standard-tier concrete construction is intensifying because petcoke price swings erode fixed-contract economics. First-time buyers in Lucknow and Indore exhibit highest price sensitivity, whereas retiree purchasers in Pune's healthcare-proximate zones absorb location premiums with minimal elasticity.
Supply Chain Analysis
Direct-to-developer channels handle bulk cement and rebar procurement for Maharashtra's single-window clearance projects, bypassing traditional distributor markups. India draws structural steel from select port corridors exposing projects to rupee-dollar fluctuation risk, while domestic cement production clusters in Gujarat and Rajasthan feed western and central markets. BIS certification bottlenecks at testing labs create raw material clearance delays for alternative cement blends. Distribution runs through project-site direct delivery for volume developers and regional stockist networks for tier-2 plotted development specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's residential construction market reads as supply-constrained: structural engineer scarcity in seismic design expertise props pricing power for Mumbai and Bengaluru specialists while constraining tier-2 execution capacity.
For Market Incumbents: Acquire peripheral land banks in Telangana's ring road municipalities ahead of Hyderabad's infrastructure expansion. Backward integration into captive concrete manufacturing shields margin compression from petcoke volatility. DLF Limited's NCR land aggregation model demonstrates how geographic concentration defends against RERA escrow liquidity squeezes. For New Entrants and Emerging Players: WhatsApp-integrated CRM platforms offer the lowest-friction route to bypass traditional broker networks in Lucknow and Indore affordable housing markets. Target first-time buyer segments where digital booking channels compress discovery-to-decision timelines. State-level single-window clearance efficiency in Karnataka and Maharashtra determines viable entry geography. For Investors and Strategic Acquirers: Exit pathways concentrate in green-certified development specialists commanding IGBC rating premiums. Long-term viability hinges on regulatory digitization velocity and PMAY subsidy disbursement continuity. Watch RERA tribunal backlog resolution speeds as the inflection signal for working capital cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concrete Manufacturing | Sobha Limited's captive supply of M30 grade concrete insulates margin pressure from petcoke price swings. |
| Green Certification Investment | Godrej Properties' IGBC-rated developments command 8-12 percent pricing elevation in Bengaluru's IT corridor. |
| Digital Channel Expansion | Direct-to-buyer platforms bypass brokerage costs and accelerate pre-launch lead generation in tier-2 municipal zones. |
| Peripheral Land Bank Aggregation | Hyderabad's ring road expansion unlocks greenfield plotted developments with lower floor area ratio constraints. |
| Prefabricated Module Adoption | Factory-cast bathroom pods cut high-rise floor cycles from 14 days to 9 days in 40-plus storey towers. |
Research Methodology
BIS technical standards, state RERA portal disclosures, and CEA building energy code documentation formed the secondary backbone for construction material and regulatory compliance validation. Primary interviews with project development heads, structural engineering consultants, cement procurement managers, and state housing authority officials anchored demand-side and supply-side intelligence. Bottom-up project pipeline tracking across Maharashtra, Karnataka, and Telangana triangulated against top-down state-level housing policy absorption estimates.
Bottom-up modeling aggregated individual project velocity, material intensity per square foot, and subsidy-eligible buyer conversion rates across the projection horizon. Segmentation dimensions included product type, construction material grade, end-user financing access, and state-level approval efficiency. CAGRs derived from weighted average of historical completion rates and policy-announced unit targets, with M30 grade concrete adoption curves and RERA escrow fund flow assumptions as construction-specific inputs.
The model holds under sustained PMAY subsidy disbursement and single-window clearance digitization; deviation in cement price volatility or rupee depreciation would shift developer margin assumptions. Forecasts reflect documented base conditions without contingency scenarios for regulatory rollback or macroeconomic shock. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market