
 Asia Pacific Co-Working Office Spaces Market | 2026-2036
Asia Pacific Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Co-Working Office Spaces Market Outlook
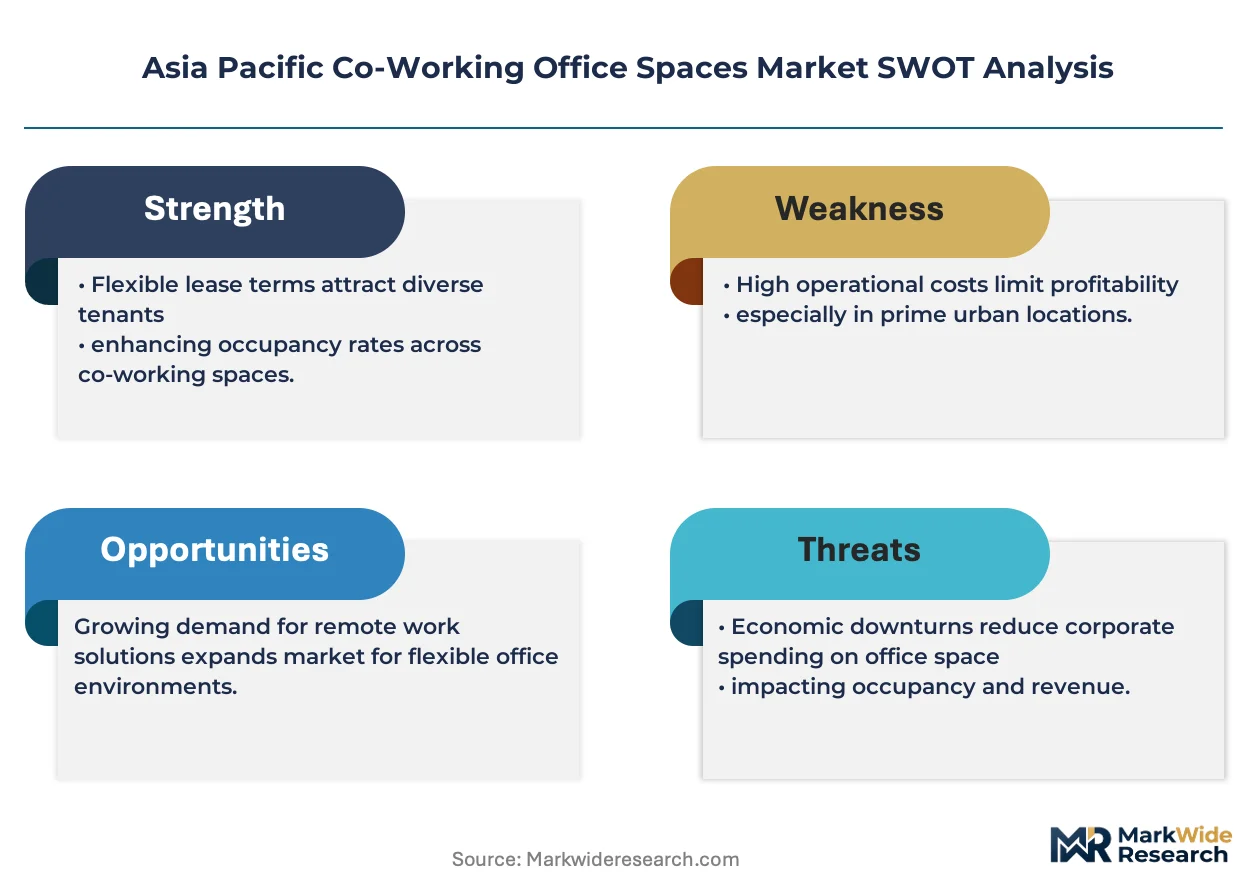
Flexible laminate surfacing is restructuring fit-out economics across premium co-working fit-outs, replacing traditional hardwood paneling with cost-efficient, modular wall systems. JustCo leverages its Singapore headquarters to anchor multi-city expansion across Southeast Asian capitals. IWG competes through franchise-heavy asset-light positioning that sustains capital efficiency at scale. Smartworks dominates the Indian enterprise segment with dedicated floor plates tailored to IT services majors.
Asia Pacific co-working office spaces comprise commercially leased environments offering shared infrastructure, typically configured with 50 to 500 seats per location, designed to serve knowledge workers through flexible tenure arrangements ranging from daily passes to multi-year contracts. These facilities integrate enterprise-grade connectivity, HVAC systems, and acoustic management to support productivity without traditional capital expenditure. Private offices capture the deepest margin pools as corporate clients prioritize secure, branded environments over open hot-desk arrangements. Flexible leasing models are expanding fastest among mid-market enterprises seeking quarterly commitment structures rather than annual contracts.
TRAI's building connectivity mandates in India, Singapore's BCA Green Mark standards, and Australia's NCC energy efficiency codes collectively shape facility specifications and operator compliance costs across the region. BIS fire safety certifications and local municipal occupancy permits further segment market access, favoring operators with established regulatory navigation capabilities. Stakeholders must monitor how evolving ESG disclosure requirements across APAC jurisdictions reshape tenant selection criteria and capital allocation toward certified sustainable buildings.
Market Dynamics
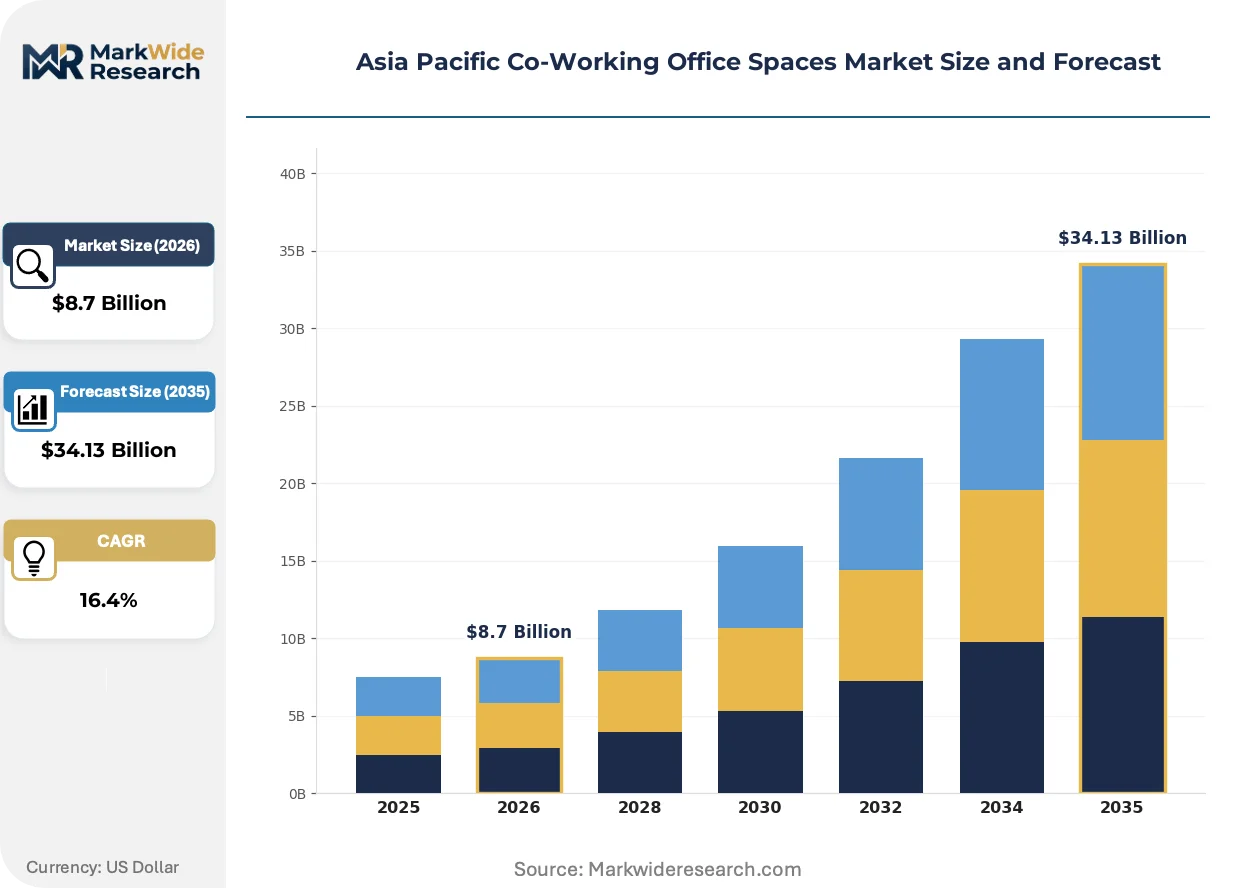
Enterprise hybrid work mandates across Singapore, Bangalore, and Sydney are compressing traditional lease tenures while expanding demand for quarterly-flexible floor plates. TRAI's building connectivity mandates and Singapore's BCA Green Mark standards are reshaping facility specifications and operator compliance investments.
Growth Catalysts
- India's PLI scheme for IT hardware manufacturing:Engineering talent clusters are forming around flexible workspace nodes in Bangalore and Hyderabad, pulling enterprise demand into co-located facilities.
- Enterprise hybrid work policies:Singapore and Australian corporations are consolidating satellite offices into managed flexible spaces, replacing fragmented leased portfolios.
- Flexible laminate surfacing:Modular wall systems are cutting fit-out timelines and capital requirements for premium co-working configurations.
Market Restraints
- Prime real estate concentration:Sydney-Melbourne corridor landlords command occupancy premiums that compress operator margins.
- BIS fire safety certification timelines:Indian municipal permitting delays extend facility launch cycles by four to six months.
- Traditional lease substitution:Long-term corporate leases with built-in contraction clauses compete directly with flexible offerings in Bangkok and Jakarta.
Strategic Opportunities
- Vietnam and Philippines expansion:Ho Chi Minh City and Manila present underpenetrated demand from regional back-office operations.
- ESG disclosure tailwinds:Australia's NCC energy efficiency codes and Singapore's Green Mark are redirecting tenant selection toward certified sustainable buildings.
- AI-driven space optimization:Convergence of occupancy sensors with automated HVAC is enabling dynamic pricing and energy arbitrage.
Industry Challenges
- Acoustic engineering skill scarcity:Open-plan density requirements exceed available talent pools for enterprise-grade sound management in Indian facilities.
- Legacy system integration:Enterprise clients demand seamless API connections with existing access control and billing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Co-Working Office Spaces Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Private Offices, Dedicated Desks, Hot Desks, Meeting Rooms Service Model: Membership Plans, Flexible Leasing, Pay-As-You-Go, Subscription Services Target Audience: Freelancers, Startups, Enterprises, Remote Workers Facility Features: High-Speed Internet, Open Space, Lounge Areas, Networking Events |
| Companies Covered | JustCo, the Hive Worldwide, IWG, Compass Offices, Servcorp, The Executive Centre, Spaces, Smartworks, WeWork, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Co-Working Office Spaces Market Strategic Shifts
Facility automation and sustainability certification are converging to redefine competitive differentiation across Asia Pacific co-working portfolios. Operators are racing to deploy sensor networks and modular construction to capture enterprise-grade contracts.
Sensor-integrated building management systems are automating real-time space allocation and energy load balancing across high-density floors. Australian and Singaporean enterprise clients are mandating these systems in RFPs for contracts exceeding two hundred seats. This automation is compressing facility operating costs while enabling dynamic per-seat pricing models that adjust to utilization patterns.
Singapore's BCA Green Mark standards and Australia's NCC energy efficiency codes are mandating net-zero-ready specifications for new flexible workspace developments. Compliance requires upgraded glazing, chilled beam HVAC, and on-site renewable generation that adds fifteen to twenty percent to base construction costs. Premium operators in Sydney and Melbourne are absorbing these costs to secure anchor tenants with published carbon reduction commitments.
Enterprise procurement teams are consolidating vendor relationships from fragmented city-by-city arrangements to regional master service agreements with single operators. This consolidation is displacing local boutique providers in favor of scaled platforms with standardized service level agreements across Singapore, Bangalore, and Sydney. The shift is most visible among IT services majors seeking consistent employee experience across distributed delivery centers.
Asia Pacific Co-Working Office Spaces Market Segmentation
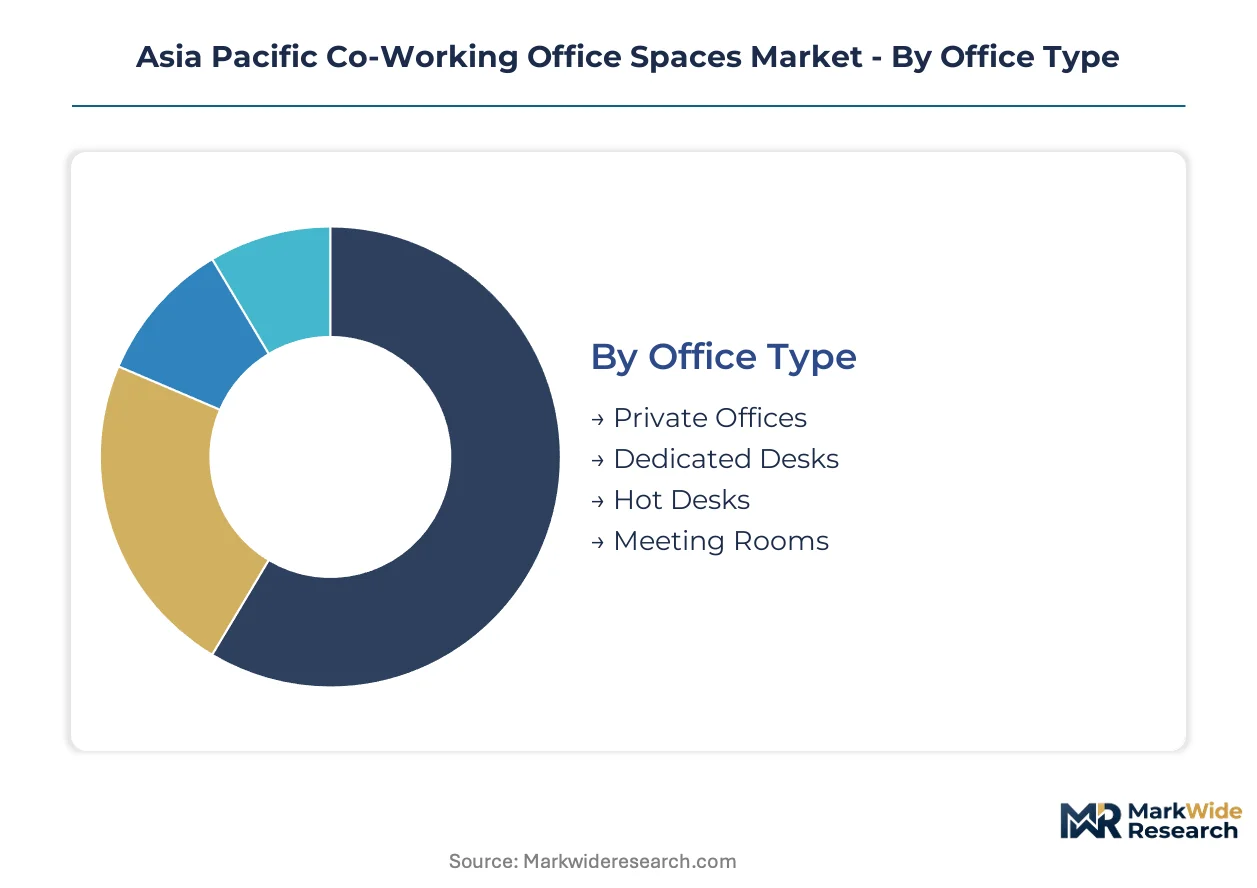
Segmentation reveals how Asia Pacific operators configure capacity, pricing, and amenities to capture distinct demand pools. Each axis reflects a strategic choice between capital efficiency and premium positioning.
Office Type:
Configuration specifications determine revenue per square meter and tenant retention economics across the region.
- Private Offices:Enclosed suites with branded entry points and dedicated HVAC zones command the highest per-seat premiums. Singaporean banking and legal tenants concentrate demand here as they require secure document handling and client confidentiality.
- Dedicated Desks:Permanently assigned workstations within shared floors balance cost control with individual territory. Bangalore IT services majors favor this format for hybrid teams requiring predictable seating without full enclosure capital expenditure.
- Hot Desks:Unassigned daily access within open-plan zones maximizes density and asset turnover. Sydney freelancers and part-time consultants drive utilization during mid-week peak periods.
- Meeting Rooms:Bookable enclosed spaces by the hour support client presentations and team workshops. Australian and Indian operators report this segment generates ancillary revenue streams exceeding base membership fees.
Mature deployment sits with Private Offices. Newer deployment is concentrated in Hot Desks.
Service Model:
Contract structure flexibility directly correlates with enterprise procurement sophistication and working capital requirements.
- Membership Plans:Monthly recurring access bundles with tiered usage allowances. Melbourne and Singapore operators report this structure captures predictable revenue while minimizing administrative overhead.
- Flexible Leasing:Quarterly to annual commitments with contraction options and expansion triggers. Enterprise procurement teams across Sydney and Bangalore are consolidating vendor relationships through this format.
- Pay-As-You-Go:Pure consumption-based access with daily or hourly settlement. Manila and Ho Chi Minh City freelancers prefer this minimal-commitment entry point.
- Subscription Services:Bundled packages combining workspace access with administrative support, IT helpdesk, and event programming. Indian IT services majors negotiate these comprehensive arrangements for distributed delivery centers.
Flexible Leasing generates the steepest expansion trajectory as procurement centralization accelerates.
Target Audience:
Customer archetype dictates location strategy, amenity investment, and sales cycle complexity.
- Freelancers:Individual knowledge workers purchasing single-seat access. Sydney and Melbourne creative professionals concentrate in CBD-adjacent locations with transit connectivity.
- Startups:Early-stage ventures requiring scalability without lease liability. Bangalore and Singapore venture-backed teams drive demand for month-to-month expansion clauses.
- Enterprises:Established corporations consolidating satellite offices into managed portfolios. Singaporean and Australian regional headquarters are the dominant demand source for contracts exceeding two hundred seats.
- Remote Workers:Distributed employees of large organizations seeking professional environments outside home offices. Australian NCC energy efficiency codes and Singapore BCA Green Mark standards increasingly influence their employer's facility selection criteria.
Enterprise procurement represents the fastest-growing trajectory as hybrid mandates solidify across the region.
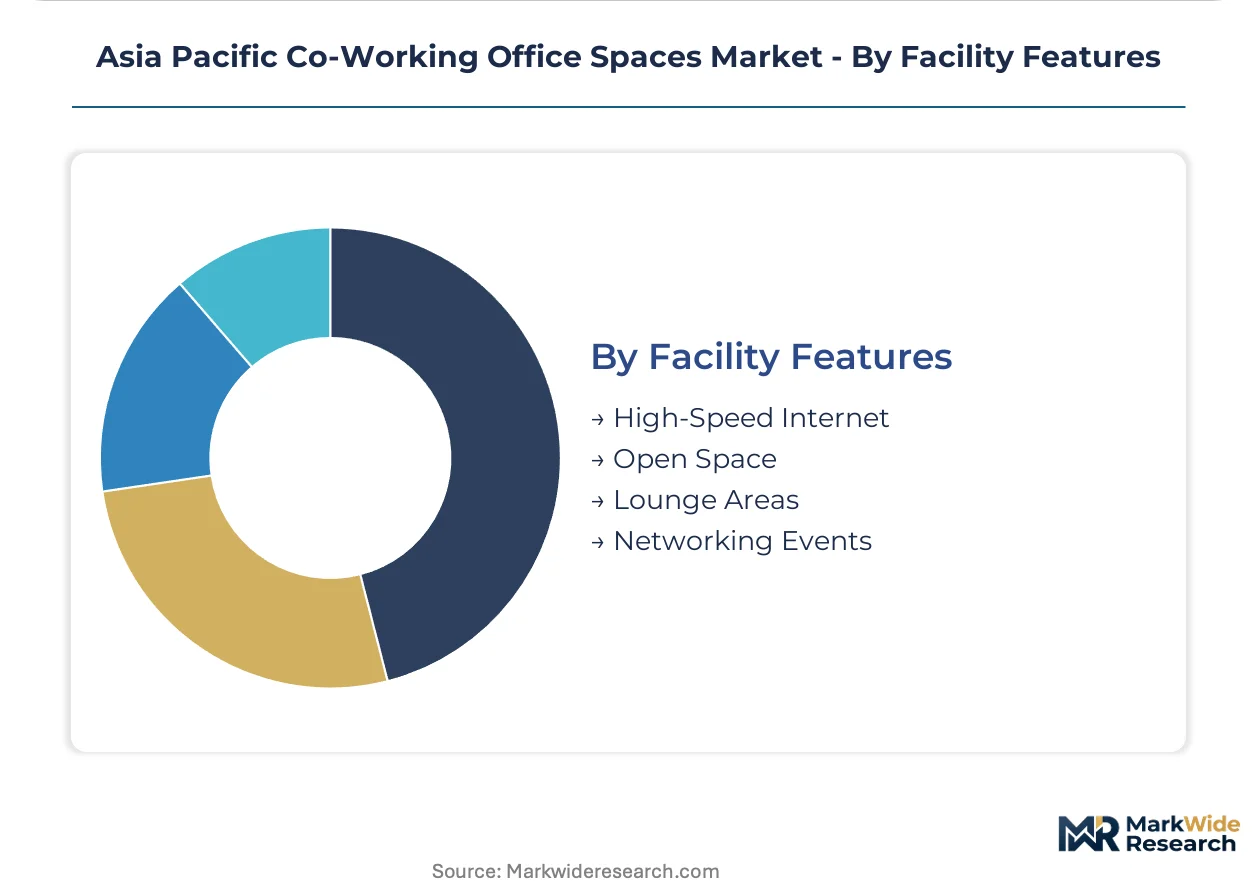
Facility Features:
Amenity specifications separate commodity providers from premium-positioned operators competing for anchor tenants.
- High-Speed Internet:Enterprise-grade fiber connectivity with redundant pathways and dedicated bandwidth allocation. TRAI building connectivity mandates in India and Singapore's Infocomm Media Development Authority requirements shape minimum specifications.
- Open Space:Unpartitioned floor plates with modular furniture supporting density reconfiguration. Acoustic engineering limitations in Indian facilities constrain deployment quality.
- Lounge Areas:Informal collision zones with soft seating and refreshment infrastructure. Sydney and Melbourne operators report these spaces drive member retention through community formation.
- Networking Events:Programmed professional gatherings and educational programming. Singapore-based operators leverage these for differentiation in a saturated CBD market.
High-Speed Internet is table stakes across all tiers. Networking Events represent the emerging differentiation axis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise hybrid mandates concentrate demand in Singapore, Bangalore, and Sydney, where procurement teams consolidate fragmented satellite portfolios into managed flexible spaces. Regulatory frameworks and talent clustering reshape facility specifications across national markets.
Singapore
Banking and legal tenants drive private office premiums in the central business district, prioritizing secure document handling and branded entry points. The Building and Construction Authority's Green Mark standards mandate net-zero-ready specifications for new developments, adding fifteen to twenty percent to base construction costs. Marina Bay and Raffles Place anchor premium flexible leasing demand as regional headquarters consolidate vendor relationships.
India
IT services majors negotiate subscription bundles combining workspace access with administrative support for distributed delivery centers. TRAI's building connectivity mandates shape minimum fiber specifications across Bangalore and Hyderabad facilities. Whitefield and Electronic City cluster engineering talent pulled by the PLI scheme for IT hardware manufacturing, expanding enterprise floor plate requirements.
Australia
Sydney and Melbourne creative professionals concentrate in CBD-adjacent locations with transit connectivity, driving hot desk utilization during mid-week peak periods. The National Construction Code's energy efficiency codes redirect tenant selection toward certified sustainable buildings. The Sydney-Melbourne corridor commands occupancy premiums that compress operator margins while sustaining premium flexible leasing demand.
Vietnam
Regional back-office operations generate underpenetrated demand in Ho Chi Minh City for quarterly-flexible floor plates. Municipal permitting frameworks favor operators with established regulatory navigation capabilities. District 1 and District 7 cluster emerging enterprise demand as procurement teams seek alternatives to Bangkok and Jakarta traditional leases.
Philippines
Freelancers and part-time consultants in Manila prefer pay-as-you-go minimal-commitment entry points. The national telecommunications regulator shapes minimum connectivity specifications for commercial building classifications. Makati and Bonifacio Global City concentrate emerging flexible workspace supply targeting business process outsourcing operations.
Asia Pacific Co-Working Office Spaces Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with franchise-heavy asset-light positioning sustaining capital efficiency at scale. The vendor base organizes around three strategic archetypes: Singapore-headquartered multi-city expansion platforms, Indian enterprise-focused dedicated floor plate providers, and Australian premium sustainable building operators. Consolidation pressures favor scaled platforms with standardized service level agreements over local boutique providers. Dominant competitive moves include geographic expansion across Southeast Asian capitals and portfolio diversification into subscription service bundles.
Within the premium-tier vector, JustCo anchors multi-city expansion across Southeast Asian capitals from its Singapore headquarters. IWG occupies a position exemplifying franchise-heavy asset-light scalability. Smartworks represents the Indian enterprise segment archetype with dedicated floor plate configurations. These three players collectively illustrate how regulatory navigation capabilities and standardized service level agreements displace fragmented city-by-city arrangements.
| Leading Market Players |
|---|
| JustCo |
| the Hive Worldwide |
| IWG |
| Compass Offices |
| Servcorp |
| The Executive Centre |
| Spaces |
| Smartworks |
| WeWork |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across fit-out material suppliers anchors both cost positioning and pricing power for Asia Pacific co-working operators. Captive sourcing of modular wall systems and laminate surfacing from consolidated manufacturing clusters in China and Vietnam compresses capital expenditure per square meter while enabling aggressive per-seat rate competition in Singapore and Sydney.
Pricing Analysis
Volume concentration in hot-desk configurations trades margin depth for asset turnover, while private office premiums sustain operator profitability. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and geographic delivery cost, with BCA Green Mark and NCC energy efficiency compliance commanding fifteen to twenty percent uplifts. Cost compression in standard tiers intensifies because of laminate surfacing substitution and modular construction adoption. Freelancers and part-time consultants in Manila and Ho Chi Minh City exhibit highest price sensitivity; Singaporean banking tenants show least.
Supply Chain Analysis
Workforce availability constraints in Chinese laminate manufacturing and Vietnamese modular furniture production shape procurement timelines for Australian and Singaporean fit-out projects. Supply concentrates in China, Vietnam, and Malaysia for engineered wood products, acoustic paneling, and sensor-integrated HVAC components. Raw material dependencies include aluminum framing systems, fiber-optic cabling, and low-emissivity glazing. Single-source vulnerability in BIS fire safety certification testing extends Indian facility launch cycles. Distribution runs through regional master service agreements consolidating fragmented city-by-city vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive fit-out manufacturing and sensor-integrated building management systems defines competitive positioning across the Asia Pacific co-working landscape. Players securing upstream control over modular construction and downstream control over enterprise client relationships capture sustainable margin pools.
For Market Incumbents: Acquire dedicated floor plate assets in Bangalore and Hyderabad to anchor enterprise subscription bundles before Smartworks consolidates IT services major relationships. Defensive positioning requires absorbing BCA Green Mark and NCC energy efficiency compliance costs to secure anchor tenants with published carbon reduction commitments. Threat substitution from traditional leases with built-in contraction clauses in Bangkok and Jakarta demands quarterly-flexible contract innovation.
For New Entrants and Emerging Players: Capture underpenetrated demand in Ho Chi Minh City and Manila for regional back-office operations seeking alternatives to fragmented traditional leasing. District 1 and Makati present most penetrable geographies given municipal permitting frameworks favoring established regulatory navigation capabilities. Go-to-market angle centers on pay-as-you-go minimal-commitment entry points converting to flexible leasing as procurement teams centralize.
For Investors and Strategic Acquirers: Exit pathways concentrate in regional master service agreement consolidation plays and franchise-heavy asset-light scalability models. Five-to-ten year viability hinges on operators achieving standardized service level agreements across Singapore, Bangalore, and Sydney footprints. Acquisition target archetype: scaled platforms with established BIS, BCA, and NCC regulatory navigation capabilities. Signal to watch: enterprise procurement team consolidation from fragmented city-by-city arrangements to single-operator regional contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Modular Construction | Captive sourcing of laminate surfacing from Vietnamese manufacturing clusters compresses fit-out timelines for Sydney facilities. |
| Green Certification Program | BCA Green Mark and NCC energy efficiency compliance secures anchor tenants with published carbon reduction commitments in Singapore. |
| Geographic Expansion | Ho Chi Minh City and Manila penetration captures underpenetrated regional back-office operations demand outside Bangkok. |
| Platform Integration | API connections with enterprise access control and billing platforms displace local boutique providers in Bangalore. |
| Long-term Supply Agreement | Regional master service agreements with IT services majors consolidate fragmented city-by-city vendor relationships across APAC. |
Study Parameters
Industry association filings, municipal permitting databases, and commercial real estate transaction records formed the secondary backbone for this analysis. Primary interviews with co-working operators, facility managers at IT services majors, commercial real estate brokers, and BCA Green Mark assessors combined with secondary validation to triangulate market sizing. Bottom-up seat capacity enumeration across Singapore, Bangalore, Sydney, Melbourne, Ho Chi Minh City, and Manila intersected with top-down flexible leasing spend estimates from enterprise procurement disclosures.
Bottom-up modeling tracked private office, dedicated desk, hot desk, and meeting room configurations across operator portfolios. Top-down analysis segmented by service model, target audience archetype, and facility feature tier. CAGRs derived from seat expansion trajectories, occupancy rate assumptions, and per-seat pricing evolution across the analysis window. Forecast inputs included TRAI building connectivity mandate compliance costs, PLI scheme talent clustering effects, and ESG disclosure requirement adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hybrid work policy permanence, regulatory compliance cost inflation, and acoustic engineering talent scarcity in Indian facilities. Forecasts reflect documented assumptions around enterprise procurement centralization velocity and sustainable building certification adoption. A small set of named triggers warrants ongoing watch: BIS fire safety certification timeline extensions, Sydney-Melbourne corridor occupancy premium volatility, and AI-driven space optimization technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market