
 IBC Rental Business Market | 2026-2036
IBC Rental Business Market Size, Share, and Industry Trends Forecast 2026-2036
IBC Rental Business Market Outlook
Pharmaceutical logistics is expanding as a high-value end-use vertical for IBC rental services, driven by stringent hygiene requirements and temperature-sensitive bulk transport needs. Brambles (CHEP) leverages its global pooling network to dominate cross-regional pharmaceutical container movements. SCHÜTZ sustains manufacturing scale through integrated blow-molding and steel-cage production in European plants. Mauser Packaging Solutions anchors its position via closed-loop reconditioning infrastructure that extends container life cycles across chemical and food-grade applications.
An IBC rental business provides reusable intermediate bulk containers—typically composite units with polyethylene inner bottles encased in galvanized steel cages, rated for volumes between 275 and 330 gallons—on a lease-return-recondition model for bulk liquid and powder transport. The rigid IBC segment leads in chemical industry deployment due to structural durability under repeated filling cycles, while collapsible IBC variants represent the fastest-growing category as food and beverage processors seek empty-container volume reduction for return logistics. Rental service revenue pools concentrate in long-term contractual arrangements with integrated cleaning and inspection protocols, whereas supply chain service bundles command premium positioning by embedding tracking technology and demand forecasting tools.
REACH compliance in Europe mandates full material traceability and residue documentation for containers handling chemical substances, directly shaping reconditioning protocols and inspection frequency requirements. The FDA's Current Good Manufacturing Practice regulations for pharmaceutical contact materials impose validation standards that limit supplier qualification to rental operators with dedicated cleanroom reconditioning capabilities. Stakeholders must monitor how evolving extended producer responsibility frameworks in France and Germany alter cost allocation between container owners and end-users across the rental value chain.
Market Dynamics
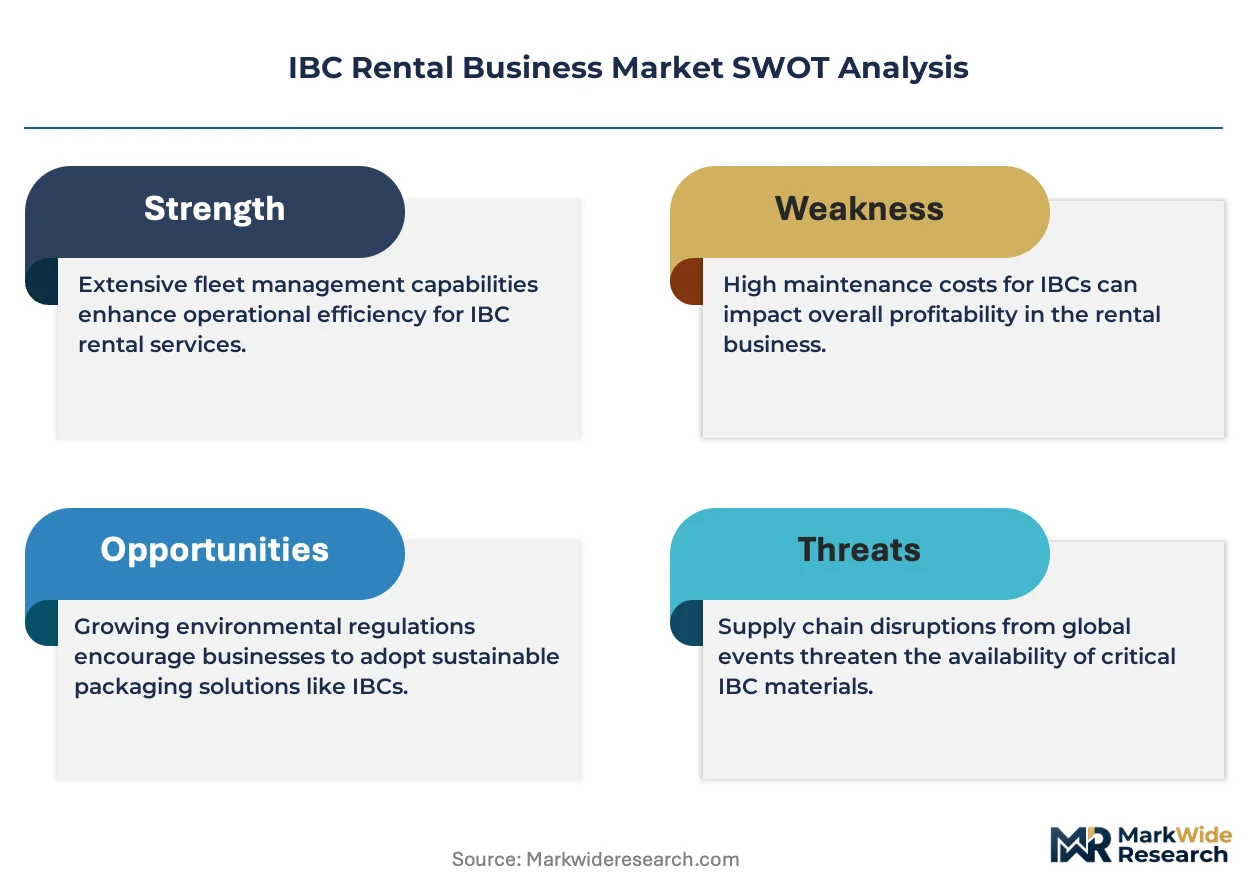
The EU F-Gas Regulation and REACH compliance mandates are forcing rental operators to reengineer reconditioning workflows and residue documentation protocols across chemical and pharmaceutical supply chains.
Growth Catalysts
- Extended Producer Responsibility frameworks:France and Germany are tightening cost allocation rules between container owners and end-users, accelerating pooling model adoption over single-use alternatives.
- Pharmaceutical cold-chain expansion:Temperature-sensitive bulk transport requirements for biologics and vaccines are pulling insulated IBC variants into high-value rental contracts with dedicated hygiene protocols.
- Rhine chemical corridor density:Germany's concentrated petrochemical and specialty chemical production supports efficient container rotation networks that minimize empty-mile logistics costs.
Market Restraints
- Steel and polyethylene input volatility:Composite IBC manufacturing depends on galvanized steel cage and HDPE inner bottle costs that fluctuate with energy and petrochemical feedstock markets.
- Reconditioning facility concentration:FDA-validated cleanroom capabilities for pharmaceutical-grade container refurbishment cluster in Germany, the Netherlands, and Belgium, creating geographic supply risk.
- Collapsible IBC durability limits:Foldable fabric or plastic variants reduce return shipping volume but face shorter cycle life under repeated filling stress in chemical applications.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's tightening GMP requirements for bulk drug substance transport create demand for certified rental containers with integrated temperature monitoring.
- RFID-telemetry convergence:Asset tracking platforms combining radio-frequency identification with IoT sensors enable predictive maintenance and real-time location services for high-value cargo.
- Food-grade rental expansion:FSSAI and EFSA alignment on contact material standards opens pooled container deployment for edible oils, syrups, and liquid ingredients in processed food supply chains.
Industry Challenges
- Cross-contamination validation:REACH-mandated residue testing and material traceability require specialized analytical chemistry capabilities that rental operators must maintain across multiple reconditioning sites.
- Legacy ERP integration:Container pool management systems must interface with customer warehouse management and enterprise resource planning platforms, creating data standardization friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IBC Rental Business Market |
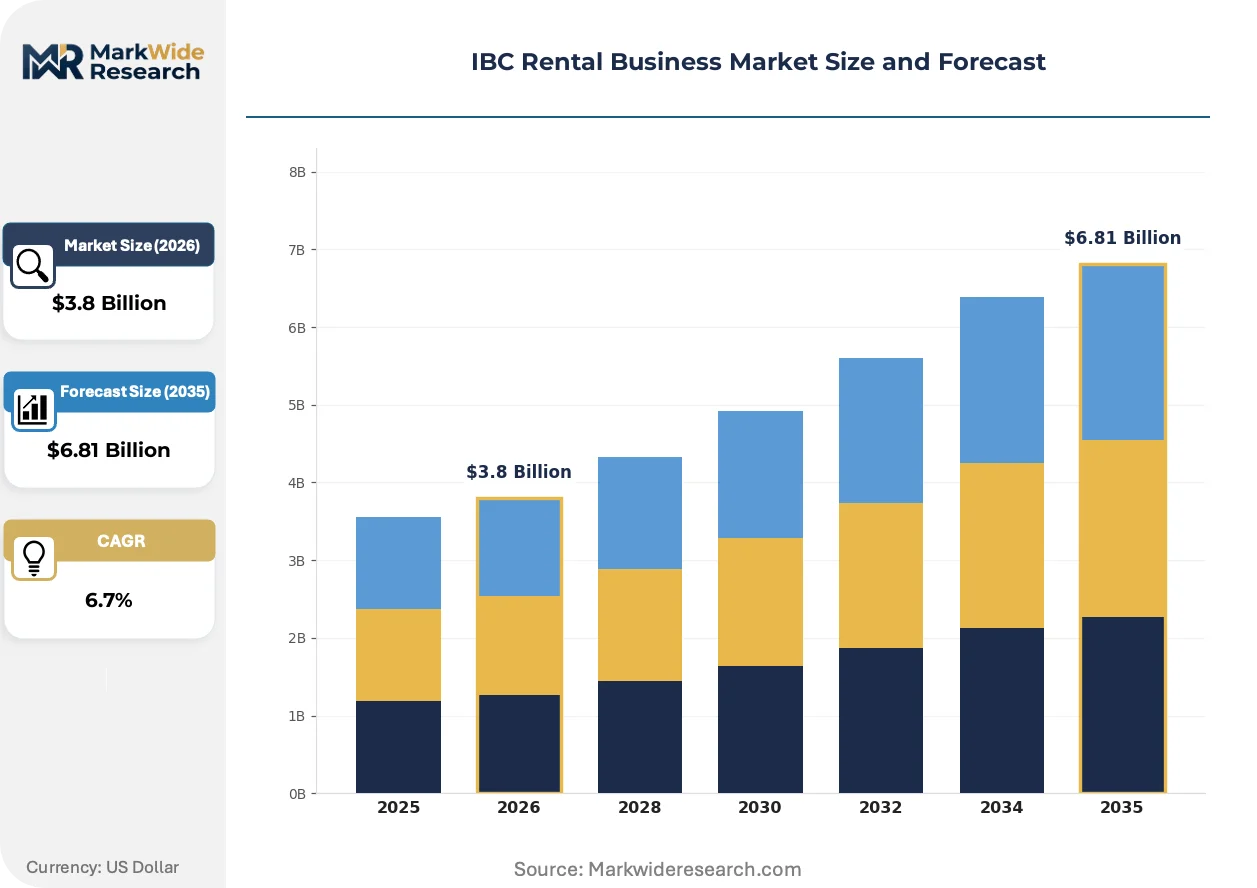
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible IBC, Rigid IBC, Intermediate Bulk Container, Custom IBC End User: Chemical Industry, Food & Beverage, Pharmaceutical Sector, Construction Service Type: Rental Service, Cleaning Service, Maintenance Service, Supply Chain Service Distribution Channel: Online Channel, Direct Sales, Third-Party Distributors, Rental Agencies |
| Companies Covered | Brambles (CHEP), SCHÜTZ, Snyder Industries, Greif, Hoover Ferguson Group, Mauser Packaging Solutions, Goodpack Pte Ltd, TPS Rental Systems Ltd, Precision IBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IBC Rental Business Market Strategic Shifts
Telemetry integration and regulatory data requirements are compressing the technology stack that rental operators must maintain, while procurement patterns favor bundled service contracts over standalone container leases.
RFID-enabled IBC tracking is unifying asset visibility with compliance documentation. Pharmaceutical logistics teams in Germany and Switzerland are deploying these systems fastest. The technology is unifying container location data with automated residue reporting and inspection timestamp records into single-platform audit trails.
REACH Article 33 obligations on Substances of Very High Concern are forcing reconditioning facilities to maintain detailed material composition databases for every container in circulation. Chemical manufacturers now demand full batch-level traceability for contact surfaces. Specialty chemical producers in the Netherlands and Belgium are responding by qualifying only rental operators with integrated laboratory testing partnerships.
Long-term contractual bundling is displacing transactional spot rentals in chemical and food processing procurement. Integrated cleaning, inspection, and replacement services command preference over bare container leases. This pattern is most visible in Germany's Rhine corridor, where multi-year agreements with embedded demand forecasting tools lock in capacity for major chemical manufacturers.
IBC Rental Business Market Segmentation
IBC rental operators structure service portfolios around container durability specifications and regulatory complexity tiers. Segmentation choices directly determine capital allocation between steel-cage manufacturing assets and reconditioning infrastructure.
Product Type:
Structural integrity and return-logistics efficiency define the technology axis across container formats.
- Rigid IBC:Composite construction pairs galvanized steel outer cages with high-density polyethylene inner bottles rated for repeated filling cycles. Chemical manufacturers along Germany's Rhine corridor deploy these for hazardous material transport under REACH-mandated residue documentation protocols.
- Collapsible IBC:Foldable fabric or plastic variants reduce empty return volume by 75% versus rigid formats. Food and beverage processors in France and Belgium favor these for edible oil and syrup logistics where container rotation frequency outpaces durability concerns.
- Intermediate Bulk Container:Standard 275-330 gallon capacity units serve as the baseline rental pool asset across European chemical networks.
- Custom IBC:Modified specifications address pharmaceutical cold-chain requirements with integrated insulation and telemetry mounting points.
Mature deployment sits with Rigid IBC. Newer deployment is concentrated in Collapsible IBC.
End User:
Regulatory stringency and residue tolerance thresholds segment demand by application vertical.
- Chemical Industry:Petrochemical and specialty chemical producers generate the highest container turnover rates. ECHA's Substances of Very High Concern database mandates batch-level traceability for contact surfaces, favoring rental operators with integrated laboratory testing partnerships in the Netherlands and Belgium.
- Pharmaceutical Sector:Biologics and vaccine bulk transport requires FDA-validated cleanroom reconditioning capabilities clustered in Germany, the Netherlands, and Belgium. Temperature-sensitive cargo commands premium positioning with embedded IoT monitoring.
- Food & Beverage:Processed food manufacturers seek EFSA-aligned contact material certification for edible oils and liquid ingredients.
- Construction:Adhesives, sealants, and coating raw materials drive seasonal demand spikes with lower hygiene protocol barriers.
Revenue concentration clusters in Chemical Industry. Steepest expansion trajectory appears in Pharmaceutical Sector.
Service Type:
Contract bundling patterns separate standalone asset leases from integrated operational support.
- Rental Service:Long-term contractual arrangements dominate chemical procurement, with multi-year agreements embedding demand forecasting tools and capacity guarantees.
- Supply Chain Service:Premium positioning combines container provision with real-time tracking technology and predictive maintenance algorithms. Pharmaceutical logistics teams in Germany and Switzerland deploy these bundled offerings fastest.
- Cleaning Service:REACH-mandated residue testing and material traceability require specialized analytical chemistry capabilities across reconditioning sites.
- Maintenance Service:Container life cycle extension through steel cage refurbishment and HDPE bottle replacement.
Standalone Rental Service commands volume leadership. Integrated Supply Chain Service captures margin expansion.
Distribution Channel:
Customer scale and procurement sophistication determine channel selection patterns.
- Direct Sales:Major chemical manufacturers negotiate enterprise agreements directly with pooling network operators. Germany's dense chemical corridor supports dedicated account management structures.
- Rental Agencies:Regional specialists aggregate small and mid-sized processor demand with flexible term structures.
- Third-Party Distributors:Logistics service providers bundle container access with freight forwarding capabilities.
- Online Channel:Digital platforms enable spot rental procurement for seasonal or project-based demand spikes.
Direct Sales anchors large-account capture. Rental Agencies serve fragmented mid-market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Germany's Rhine corridor concentrate IBC pooling infrastructure through targeted logistics incentives and REACH compliance clustering.
Germany
Chemical manufacturers along the Rhine corridor generate dense container rotation networks for hazardous material transport. ECHA's REACH Article 33 mandates batch-level traceability for contact surfaces, forcing rental operators to maintain integrated laboratory testing partnerships. The BASF-Ludwigshafen cluster anchors Europe's largest IBC reconditioning hub with FDA-validated cleanroom capabilities.
United States
Pharmaceutical bulk transport demand from Boston-Cambridge biotech corridors pulls insulated IBC variants into cold-chain logistics. FDA's Current Good Manufacturing Practice regulations limit supplier qualification to operators with dedicated pharmaceutical reconditioning infrastructure. The Houston Ship Channel petrochemical complex sustains high container turnover rates for specialty chemical producers.
France
Extended Producer Responsibility frameworks tighten cost allocation rules between container owners and end-users across chemical supply chains. ANSM's pharmaceutical transport guidelines align with EMA cold-chain standards for biologics distribution. The Lyon-Saint-Étienne chemical basin supports regional pooling networks with embedded demand forecasting tools.
India
CDSCO's tightening GMP requirements for bulk drug substance transport create demand for certified rental containers with integrated temperature monitoring. FSSAI alignment with EFSA contact material standards opens pooled container deployment for edible oil processors. The Ahmedabad-Vadodara pharmaceutical corridor concentrates cold-chain IBC deployment for generic API exports.
Netherlands
Rotterdam port logistics operators bundle container access with freight forwarding capabilities for chemical exporters. ECHA's Substances of Very High Concern database mandates residue documentation protocols that favor rental operators with captive laboratory testing. The Chemelot industrial cluster in Limburg anchors Benelux reconditioning capacity for cross-border chemical movements.
IBC Rental Business Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pooling network operators commanding long-term contractual arrangements while regional fabricators serve spot rental demand. The vendor base concentrates around three strategic archetypes: global pooling specialists with integrated reconditioning infrastructure, regional container manufacturers with captive steel-cage production, and logistics service providers bundling asset access with freight forwarding. Competitive moves center on backward integration into HDPE blow-molding capacity and geographic expansion through dedicated account management structures in chemical corridor clusters.
Among global pooling specialists, Brambles (CHEP) and Mauser Packaging Solutions exemplify the integrated service model, while SCHÜTZ anchors the manufacturing-scale archetype through European production assets. These three occupy positions spanning the premium-tier bundled service segment and the standardized rental pool market, representing divergent capital allocation strategies between reconditioning infrastructure and captive manufacturing.
| Leading Market Players |
|---|
| Brambles (CHEP) |
| SCHÜTZ |
| Snyder Industries |
| Greif |
| Hoover Ferguson Group |
| Mauser Packaging Solutions |
| Goodpack Pte Ltd |
| TPS Rental Systems Ltd |
| Precision IBC |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical cold-chain procurement mandates for FDA-validated cleanroom reconditioning are compressing supplier qualification lists and concentrating pricing power among operators with captive laboratory infrastructure in Germany and the Netherlands.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent pharmaceutical deployments from scheduled chemical industry rotations. Three-tier pricing structure across premium pharmaceutical-grade, standard chemical-grade, and economy construction-grade levels reflects certification burden and residue documentation intensity. Pricing pressure stems from steel and polyethylene input volatility tied to energy feedstock markets. Chemical manufacturers exhibit highest price sensitivity due to commodity-like container utilization patterns, while pharmaceutical logistics teams absorb premiums for validated cold-chain assurance.
Supply Chain Analysis
Certification and qualification gating through REACH Article 33 and FDA Current Good Manufacturing Practice regulations concentrates supply among operators with integrated laboratory testing partnerships. Manufacturing draws from galvanized steel cage production in Germany and HDPE blow-molding capacity in the Netherlands and Belgium. Raw material dependencies center on petrochemical feedstocks, zinc coating inputs, and specialized cleaning chemistries. Single-source vulnerability clusters around FDA-validated cleanroom refurbishment capacity concentrated in the Rhine corridor. Distribution runs through direct enterprise agreements with major chemical manufacturers and regional rental agency networks serving fragmented processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom reconditioning capacity scarcity props pricing premiums and creates durable competitive moats for qualified operators.
For Market Incumbents: Cement market position through backward integration into HDPE blow-molding capacity and expansion of captive laboratory testing partnerships. Defend against emerging regional fabricators by locking multi-year enterprise agreements with embedded demand forecasting tools. Prioritize certification investment in CDSCO-aligned GMP capabilities for Indian pharmaceutical corridor access. For New Entrants and Emerging Players: Begin with collapsible IBC deployment for French and Belgian food and beverage processors where EFSA contact material standards create lower regulatory barriers than pharmaceutical tiers. Target Indian edible oil and syrup logistics where FSSAI alignment opens pooled container adoption. Pursue digital platform spot-rental procurement as the go-to-market angle for seasonal construction chemical demand. For Investors and Strategic Acquirers: The window for entry favors operators with integrated reconditioning infrastructure and established laboratory testing partnerships. Long-term viability rests on regulatory compliance capabilities that resist commoditization across the projection horizon. Acquisition targets should demonstrate captive cleanroom capacity and multi-year contractual revenue concentration. Watch CDSCO enforcement intensity as the signal for Indian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Blow-Molding | Captive bottle production insulates margin from petrochemical feedstock volatility. |
| FDA-Validated Cleanroom Expansion | Cleanroom capacity scarcity props pricing premiums in pharmaceutical cold-chain segments. |
| RFID-Telemetry Platform Deployment | Real-time asset tracking unifies compliance documentation with operational visibility. |
| Indian Pharmaceutical Corridor Entry | CDSCO GMP alignment opens access to generic API export logistics demand. |
| Long-Term Contractual Bundling | Integrated service contracts displace transactional spot rentals in Rhine corridor procurement. |
Study Parameters
Independent corroboration across primary interviews with reconditioning facility managers, pharmaceutical logistics procurement leads, chemical plant supply chain directors, and rental network operators underwrites the qualitative findings. Secondary validation draws from ECHA substance databases, FDA inspection records, customs trade flows for IBC classifications, and SEC filings of listed pooling operators. Bottom-up container fleet estimates triangulate against top-down chemical and pharmaceutical production volume allocations.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include container structural format, regulatory compliance tier, end-use vertical, service bundling intensity, and geographic corridor density. CAGRs derive from trend-line extrapolation of fleet utilization rates and contractual pricing trajectories. Industry-specific forecast inputs incorporate REACH Article 33 enforcement patterns and pharmaceutical cold-chain expansion curves.
Underlying measurement precision varies by segment; rigid IBC chemical deployments carry tighter precision than emerging collapsible formats in food applications. Forecasts reflect assumptions about regulatory enforcement continuity and input cost normalization. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or CDSCO GMP certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Global Home Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Green Lease Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Singapore Customs Brokerage Market