
 Turkey Commercial Real Estate Market | 2026-2036
Turkey Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Commercial Real Estate Market Insights
Cross-laminated timber is hardening its position against conventional steel framing in mid-rise commercial developments across Turkey's Aegean and Marmara regions. Torunlar GYO leverages its integrated construction-to-lease pipeline to lock in tenant commitments before breaking ground. Ağaoğlu Group anchors its portfolio around mixed-use towers that blend office, retail, and hospitality functions. Rönesans Holding competes on engineering-intensive builds, including seismic-resistant core designs that differentiate its assets in Istanbul's high-risk zones.
Turkey commercial real estate comprises income-generating properties designed for business occupancy, typically engineered to seismic Zone 1 standards with reinforced concrete shear walls or steel moment frames, and valued on capitalization rates tied to lira-denominated lease streams. Office stock in Istanbul's Levent-Maslak corridor commands premium rents due to limited Grade-A supply and concentration of multinational headquarters. Retail assets in Anatolian secondary cities sustain faster rent growth as modern shopping center penetration lags Istanbul. Industrial and logistics facilities near the Gebze-Dilovası organized zone absorb the fastest-growing demand, driven by e-commerce fulfillment requirements and Turkey's position as a nearshoring bridge between Europe and Asia.
The Ministry of Environment, Urbanisation and Climate Change enforces seismic retrofit mandates and energy performance certificates that filter out obsolete stock from institutional-grade portfolios. BIS standards for structural materials and the CEA's building insurance requirements shape construction quality thresholds and financing eligibility. Stakeholders must weigh currency hedging mechanisms against lira lease exposure while tracking which sub-markets institutional capital will certify as core-plus eligible.
Market Dynamics
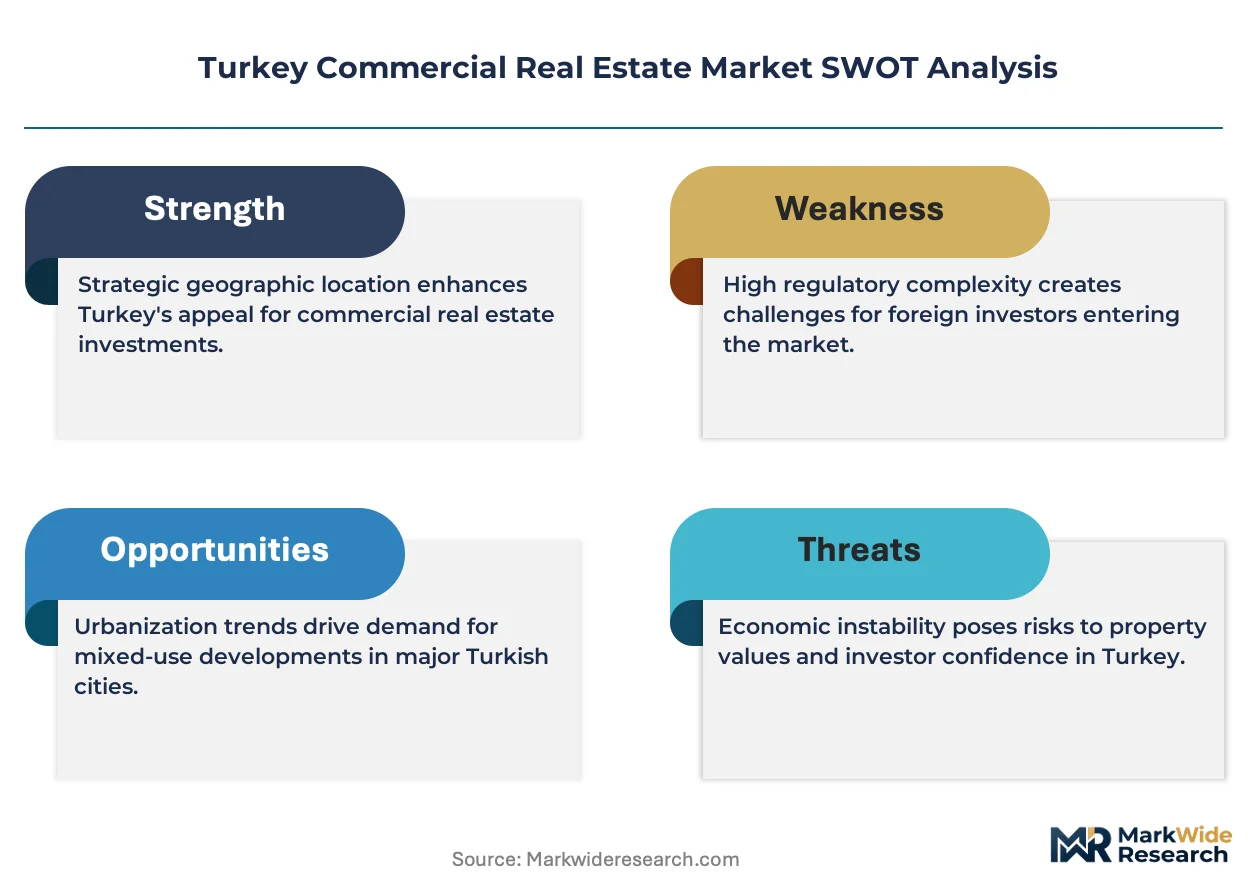
The Ministry of Environment, Urbanisation and Climate Change is accelerating brownfield redevelopment approvals while seismic retrofit mandates filter obsolete stock from institutional-grade portfolios. Currency hedging mechanisms compete against lira-denominated lease exposure as logistics operators expand across the Anatolian corridor.
Growth Catalysts
- Nearshoring Bridge Position:Turkey's geographic position between Europe and Asia draws e-commerce fulfillment demand to industrial zones near Gebze-Dilovası. Multinational headquarters concentrate in Istanbul's Levent-Maslak corridor where Grade-A office supply remains constrained.
- Energy Performance Mandates:The Ministry's energy performance certificate requirements accelerate replacement of obsolete buildings. Institutional capital redirects toward certified assets that meet BIS structural material standards and CEA insurance thresholds.
- Cross-Laminated Timber Adoption:Engineered wood products gain traction in mid-rise commercial developments across Aegean and Marmara regions. Developers leverage lighter structural systems to reduce foundation costs in seismic zones.
Market Restraints
- Lira Volatility:Currency depreciation compresses real returns for foreign investors holding unhedged lease streams. Capitalization rate spreads widen against euro-denominated regional alternatives.
- Seismic Zone Concentration:Istanbul's high-risk Zone 1 classification elevates insurance premiums and engineering costs. Reinforced concrete shear walls and steel moment frames add 15-25% to structural budgets versus lower-risk geographies.
- Secondary City Infrastructure Gaps:Anatolian logistics expansion faces port connectivity limitations and highway capacity constraints outside the Istanbul-Ankara axis.
Strategic Opportunities
- Ataşehir Financial District Absorption:Istanbul's emerging central business district captures overflow demand from saturated Levent-Maslak supply. Mixed-use towers blending office, retail, and hospitality functions command rent premiums.
- Secondary City Retail Modernization:Modern shopping center penetration lags in Anatolian cities versus Istanbul saturation. Fast-fashion and electronics retailers seek anchor positions in Bursa, Konya, and Gaziantep.
- Brownfield Redevelopment Pipeline:Updated zoning legislation streamlines approvals for contaminated industrial sites. Developers access entitled land at 30-40% discounts to greenfield alternatives.
Industry Challenges
- Seismic Engineering Talent Scarcity:Qualified structural engineers familiar with performance-based design remain concentrated in Istanbul. Ankara and Izmir projects face recruitment delays and cost premiums.
- Retrofit Coordination Complexity:Occupied building upgrades require phased construction sequencing that extends timelines. Tenant relocation clauses and business interruption coverage add negotiation friction.
- Green Financing Verification:Sustainability-linked loan eligibility demands third-party certification timelines that misalign with development schedules. LEED and BREEAM assessor capacity bottlenecks in Turkey extend documentation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Commercial Real Estate Market |
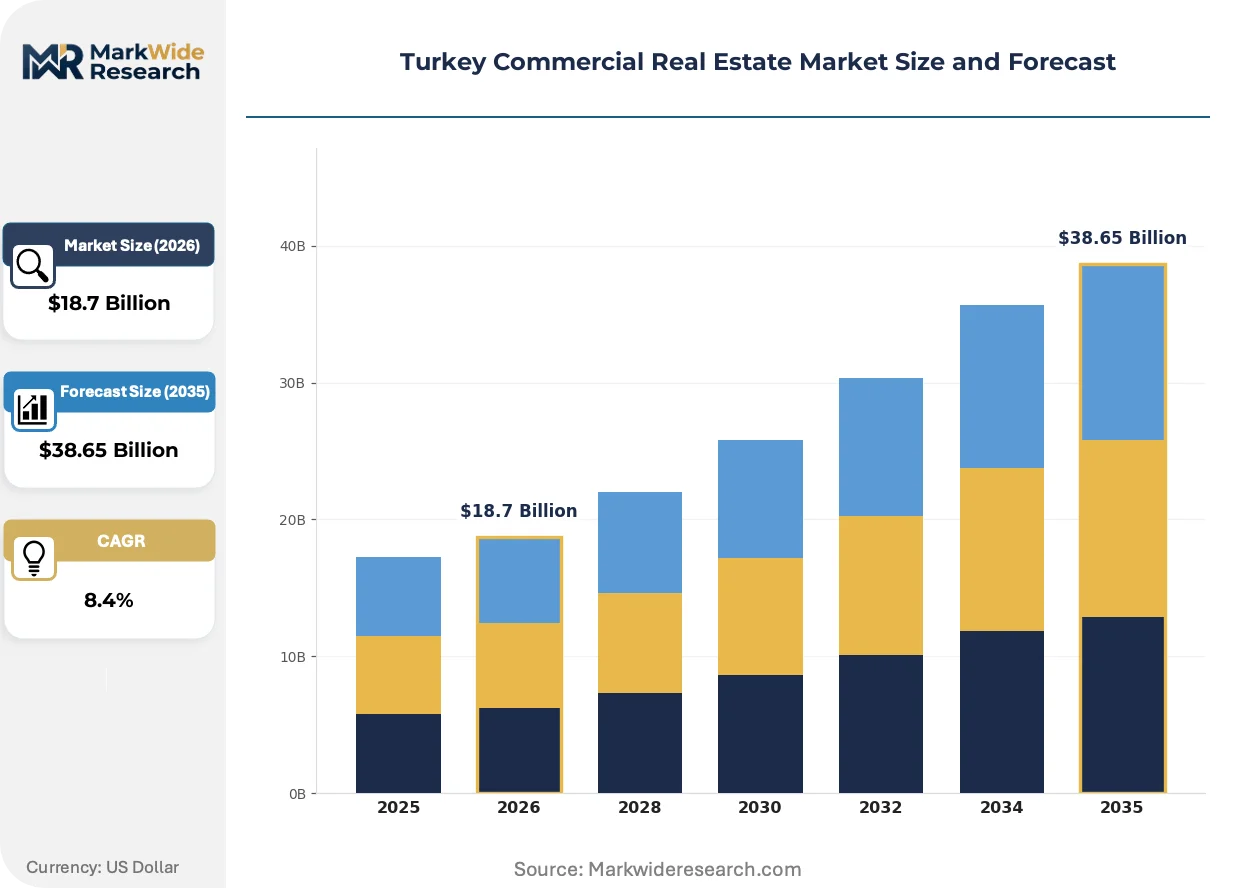
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Buyer Type: Institutional Investors, High-Net-Worth Individuals, Real Estate Funds, Developers Lease Structure: Gross Lease, Net Lease, Percentage Lease, Modified Gross Lease Investment Strategy: Value-Add, Core, Core Plus, Opportunistic |
| Companies Covered | Torunlar GYO, Calik Holding, Ağaoğlu Group, Fiba Commercial Properties, Nurol GYO, Rönesans Holding, Sinpaş GYO, Blue Capital, Emlak Konut GYO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Commercial Real Estate Market Trends and Innovations
Building systems are converging with digital infrastructure while regulatory pressure hardens performance standards. Material substitution and procurement model evolution reshape competitive positioning across asset classes.
Building information modeling is integrating with IoT sensor networks to enable predictive maintenance across commercial portfolios. Property managers in Istanbul's premium office stock deploy digital twins to optimize HVAC energy consumption. The technology is compressing operating expenditure spreads between Grade-A and secondary assets.
The Ministry of Environment, Urbanisation and Climate Change enforces mandatory energy performance certificates that disqualify non-compliant assets from institutional financing. Commercial mortgage eligibility now hinges on minimum efficiency ratings that 40% of existing stock fails to meet. Office landlords in Ankara's Söğütözü zone accelerate envelope upgrades to retain tenant credit quality.
Corporate occupiers are consolidating vendor relationships through integrated facility management contracts that bundle property services with lease obligations. Single-provider arrangements replace fragmented service procurement in logistics and warehousing facilities. This concentration is most visible among e-commerce operators near the Gebze-Dilovası organized zone seeking operational standardization.
Turkey Commercial Real Estate Market Segmentation
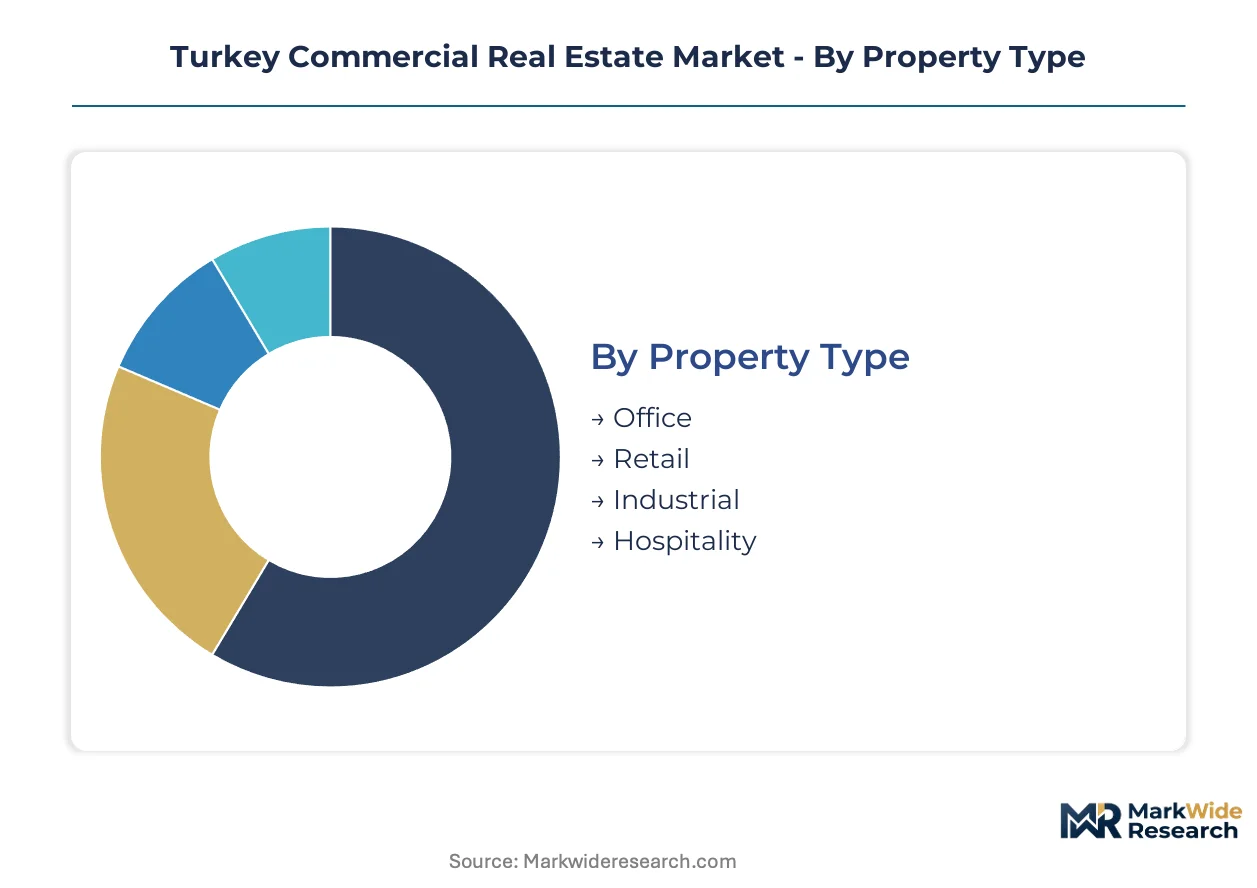
Segmentation in Turkish commercial real estate reveals how capital flows cluster around risk-return profiles and regulatory compliance tiers. Property type classification determines seismic engineering requirements and energy certificate eligibility. Buyer composition shapes transaction velocity and lease structure preferences across Istanbul's financial districts versus Anatolian secondary markets.
Property Type:
Structural specification and occupancy function define engineering standards, insurance premiums, and tenant covenant quality across Turkey's seismic zones.
- Office:Grade-A stock in Istanbul's Levent-Maslak corridor commands premium rents due to multinational headquarters concentration and limited supply. Reinforced concrete shear walls or steel moment frames meeting Zone 1 seismic standards filter out obsolete buildings from institutional portfolios. Energy performance certificates now gate financing eligibility for this segment.
- Industrial:Logistics facilities near Gebze-Dilovası absorb e-commerce fulfillment demand driven by Turkey's nearshoring bridge position. Cross-docked warehouses with high-clearance racking dominate new supply. Rail connectivity and highway access determine site selection outside the Istanbul-Ankara axis.
- Retail:Modern shopping centers in Anatolian cities sustain faster rent growth as penetration lags saturated Istanbul. Fast-fashion anchors seek expansion in Bursa, Konya, and Gaziantep. Percentage rent structures align landlord-tenant interests in discretionary spending environments.
- Hospitality:Mixed-use towers integrate hotel functions with office and retail in Ataşehir and Söğütözü developments. Tourism-dependent cash flows require currency hedging against lira volatility. Operational complexity elevates management fee structures versus passive asset classes.
Mature deployment sits with Office. Newer deployment is concentrated in Industrial.
Buyer Type:
Capital source dictates holding period expectations, leverage tolerance, and regulatory compliance depth across Turkey's commercial property transactions.
- Institutional Investors:Pension funds and insurance companies mandate seismic Zone 1 compliance and energy performance certification for portfolio eligibility. Long-dated liabilities match core office assets in Istanbul's financial districts. Currency hedging programs offset lira-denominated lease exposure.
- Real Estate Funds:Value-add strategies target brownfield redevelopment sites entitled under accelerated Ministry approvals. Closed-end structures align with 5-7 year holding periods for repositioning plays. Fee structures emphasize promote over management income.
- Developers:Integrated construction-to-lease pipelines lock in tenant commitments before breaking ground in Ankara's Söğütözü zone. Torunlar GYO and similar operators capture development margin plus stabilized yield. Pre-leasing requirements constrain speculative starts.
- High-Net-Worth Individuals:Direct ownership concentrates in retail condominiums and small-scale office buildings. Personal balance sheet financing avoids covenant restrictions. Estate planning objectives extend holding periods beyond institutional benchmarks.
Capital concentration is heaviest among Institutional Investors. Transaction velocity is climbing fastest with Real Estate Funds.
Lease Structure:
Risk allocation between landlord and tenant determines operating expense predictability and net operating income stability across Turkey's commercial contracts.
- Gross Lease:Landlord absorbs property tax, insurance, and maintenance costs in exchange for fixed rent streams. Istanbul's legacy office stock predominantly employs this structure. Operating expense escalations compress net operating income during inflationary periods.
- Net Lease:Tenant responsibility for operating expenses aligns incentives for energy efficiency and maintenance discipline. Industrial facilities near Gebze-Dilovası increasingly adopt triple-net structures. Creditworthy tenants reduce landlord management burden.
- Percentage Lease:Base rent plus revenue participation dominates retail and hospitality segments. Fast-fashion and electronics retailers negotiate breakpoint structures. Sales reporting requirements add administrative complexity.
- Modified Gross Lease:Hybrid structures allocate specific expense categories to each party. Utility pass-throughs with caps limit tenant exposure to energy price volatility. Negotiation friction centers on expense base year selection.
Contract standardization is deepest with Gross Lease. Structural shift is most visible toward Net Lease.
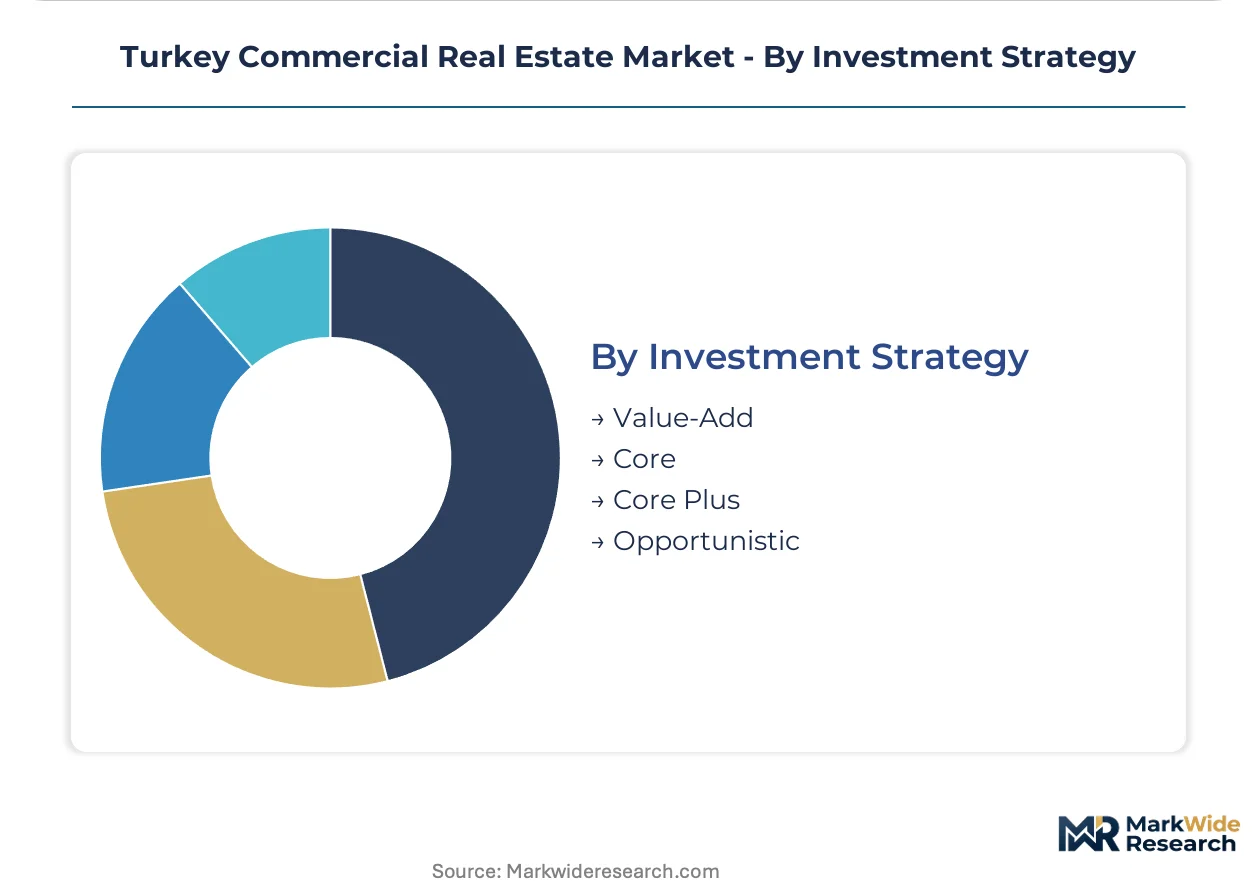
Investment Strategy:
Risk-adjusted return targets and operational intensity requirements sort capital across Turkey's commercial real estate opportunity set.
- Core:Stabilized assets in Istanbul's Levent-Maslak corridor with long-leased, investment-grade tenants. Seismic compliance and energy certification satisfy institutional mandates. Low leverage and long holds match pension fund liabilities.
- Core Plus:Light value-add through lease rollover optimization or minor capital improvements. Ataşehir financial district absorption plays fit this profile. Moderate leverage enhances returns without development risk.
- Value-Add:Brownfield redevelopment and seismic retrofit of obsolete stock. Ministry of Environment, Urbanisation and Climate Change zoning accelerations improve entitlement timelines. Tenant relocation clauses add execution complexity.
- Opportunistic:Distressed acquisitions and ground-up development in emerging submarkets. Cross-laminated timber mid-rise projects in Aegean and Marmara regions exemplify this category. Highest return thresholds compensate for construction and leasing risk.
Capital allocation is deepest in Core. Risk appetite is expanding fastest toward Value-Add.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gebze-Dilovası Organized Industrial Zone anchors Turkey's logistics corridor, drawing e-commerce fulfillment investment through customs-free processing and highway-rail intermodal access. Tax incentives for manufacturing tenants accelerate absorption in this Marmara sub-region.
Istanbul
Multinational headquarters concentrate in Levent-Maslak where Grade-A office supply remains constrained. The Ministry of Environment, Urbanisation and Climate Change enforces seismic retrofit mandates that filter obsolete stock from institutional portfolios. Ataşehir's emerging financial district captures overflow demand through mixed-use towers blending office, retail, and hospitality functions.
Ankara
Public sector procurement and defense contractors sustain office demand in the Söğütözü business zone. Energy performance certificate requirements now gate commercial mortgage eligibility, accelerating envelope upgrades among landlords. The Konya Road corridor absorbs logistics expansion serving central Anatolia distribution networks.
Izmir
Cross-laminated timber gains traction in mid-rise commercial developments across the Aegean coast. Port modernization programs enhance container throughput capacity for export-oriented manufacturing tenants. The Bornova and Konak sub-markets concentrate Grade-B office stock awaiting repositioning capital.
Bursa
Automotive supplier networks drive industrial absorption near the Gemlik port and organized industrial zones. Fast-fashion retailers seek anchor positions as modern shopping center penetration lags Istanbul saturation. The Ministry's brownfield redevelopment approvals streamline conversion of former textile facilities.
Antalya
Tourism-dependent hospitality assets require currency hedging against lira volatility in operating cash flows. Mixed-use developments integrate residential condominiums with retail podium functions to diversify revenue streams. The Konyaaltı and Lara beach corridors concentrate international branded hotel supply.
Turkey Commercial Real Estate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated developers commanding premium positions in Istanbul's financial districts while regional operators capture secondary city logistics. The market structures around three tiers: construction-to-lease pipelines, mixed-use tower specialists, and engineering-intensive seismic builders. Consolidation pressures favor operators with captive land banks and pre-leasing capabilities. Dominant competitive moves include brownfield site assembly and integrated facility management contract bundling.
Within the integrated development tier, Torunlar GYO and Ağaoğlu Group exemplify contrasting approaches to risk allocation. Torunlar's construction-to-lease pipeline locks tenant commitments prior to groundbreaking, while Ağaoğlu anchors portfolios around mixed-use towers. Rönesans Holding occupies a position among engineering-intensive builders, differentiating assets through seismic-resistant core designs in Istanbul's high-risk zones.
| Leading Market Players |
|---|
| Torunlar GYO |
| Calik Holding |
| Ağaoğlu Group |
| Fiba Commercial Properties |
| Nurol GYO |
| Rönesans Holding |
| Sinpaş GYO |
| Blue Capital |
| Emlak Konut GYO |
| Others |
Pricing and Supply Chain Analysis
Energy performance certificate mandates from Turkey's Ministry of Environment, Urbanisation and Climate Change gate both qualified material supply and premium-tier asset pricing access. Developers holding certified cross-laminated timber and seismic-grade steel inventories command 15-25% structural cost premiums over uncertified competitors.
Pricing Analysis
Lead-time compression pricing dominates Turkey's commercial construction procurement, with pre-committed tenant pipelines securing 8-12 month material scheduling discounts while spot-market buyers absorb availability premiums. Three-tier pricing structure across premium certified, standard compliant, and economy unverified grades reflects BIS structural material standards and CEA insurance thresholds. Cost compression in economy-grade reinforced concrete intensifies as lira depreciation elevates import dependency for epoxy-coated rebar. Institutional investors exhibit lowest price sensitivity, prioritizing seismic Zone 1 compliance over per-square-meter savings.
Supply Chain Analysis
Certification gating from BIS and CEA restricts qualified supply to domestic mills in Karabük and Iskenderun plus Turkish-certified German and Italian engineered timber importers. Cross-laminated timber panels draw from Austrian and Slovenian producers, while seismic-grade steel moment frames rest on scrap metal feedstock from Black Sea port collections. Single-source vulnerability concentrates in epoxy-coated rebar where Iskenderun Bay capacity constraints create bottleneck exposure. Distribution runs through Gebze-Dilovası organized zone logistics hubs serving Anatolian corridor expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's commercial real estate market is a vertical-integration race. Captive construction-to-lease pipelines anchor competitive positioning against lira-denominated lease volatility.
For Market Incumbents: Deploy pre-leasing lock-in mechanisms to secure tenant commitments before groundbreaking, insulating development margins against material cost spikes. Accelerate brownfield site assembly under Ministry zoning accelerations to capture 30-40% land cost discounts. Substitute technology threat from modular construction demands faster entitlement timelines. For New Entrants and Emerging Players: Begin with secondary city retail modernization in Bursa, Konya, and Gaziantep where modern shopping center penetration lags Istanbul saturation. Target fast-fashion anchor procurement relationships seeking Anatolian expansion. Go-to-market angle centers on percentage rent structures aligning landlord-tenant interests in discretionary spending recovery. For Investors and Strategic Acquirers: Ministry energy performance certificate enforcement acceleration is the leading indicator that institutional capital will redirect toward certified assets. Long-term viability frames around 5-10 year seismic retrofit mandate compliance windows. Acquisition target archetype: brownfield redevelopment sites with accelerated entitlement timelines. Signal to watch: CEA insurance threshold tightening disqualifying additional obsolete stock.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Site Assembly | Ministry zoning accelerations compress entitlement timelines for contaminated industrial conversions. |
| Pre-Leasing Pipeline Lock-In | Torunlar GYO model secures tenant commitments before construction financing drawdown. |
| Cross-Laminated Timber Adoption | Aegean and Marmara developers reduce foundation costs in seismic zones via lighter structural systems. |
| Integrated Facility Management Bundling | E-commerce operators near Gebze-Dilovası consolidate vendor relationships for operational standardization. |
| Seismic Retrofit Coordination | CEA insurance requirements filter obsolete stock from institutional-grade portfolios. |
Research Methodology
Independent corroboration across development executives, structural engineering consultants, institutional portfolio managers, and Ministry zoning officials underwrites the qualitative findings. Primary interviews with construction-to-lease pipeline operators, brownfield remediation specialists, and CEA insurance underwriters combined with secondary validation from BIS structural material standards, CEA building insurance requirements, and Ministry of Environment, Urbanisation and Climate Change regulatory filings. Bottom-up project pipeline enumeration and top-down capital flow triangulation anchor sizing estimates.
Comparable-period anchoring to historical absorption velocity in Istanbul's Levent-Maslak corridor and Ankara's Söğütözü zone calibrates the forecast framework across the analysis window. Segmentation dimensions modeled include property type, buyer type, lease structure, and investment strategy tier. CAGRs derive from rolling average absorption rates applied to entitled supply pipelines. Industry-specific forecast inputs incorporate seismic retrofit mandate compliance timelines and energy performance certificate penetration curves.
Underlying measurement precision varies by segment; Grade-A office stock in Istanbul financial districts carries tighter precision than hospitality assets in Antalya. Forecasts reflect assumptions around lira stabilization trajectory and Ministry enforcement consistency. A model refresh is warranted upon material change in CEA insurance threshold tightening or energy performance certificate mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market