
 North America Coworking Spaces Market | 2026-2036
North America Coworking Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coworking Spaces Market Analytics
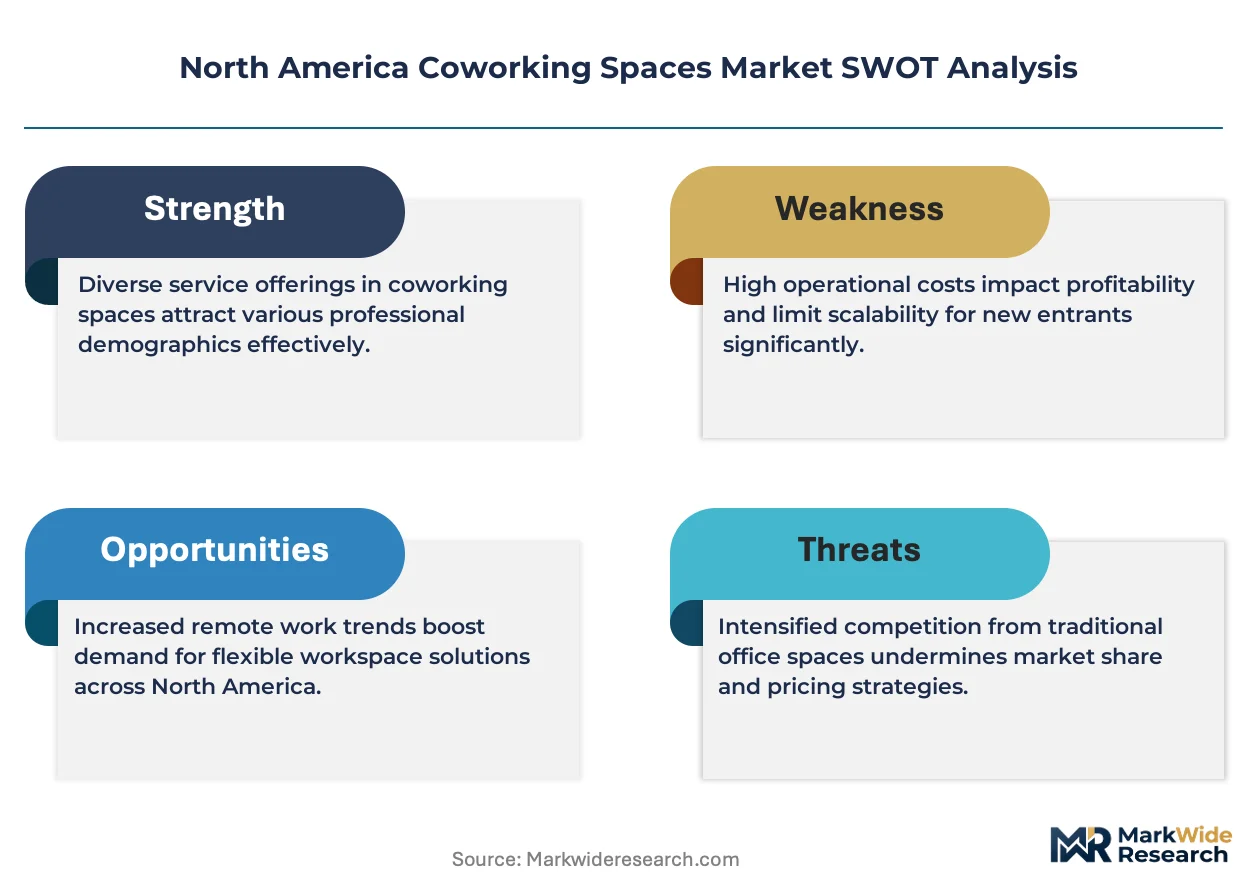
Asset-light franchise and management-agreement models are reshaping competitive entry in the North America coworking sector, allowing regional operators to scale without balance-sheet property exposure. WeWork Inc. leverages its brand recognition and technology platform to sustain member retention across volatile lease cycles. Industrious LLC anchors its position through landlord-partnership structures that shift real estate risk to property owners. IWG competes through a multi-format portfolio spanning serviced offices, flexible workspaces, and hybrid meeting solutions.
North America coworking spaces constitute commercially operated work environments providing shared infrastructure including high-speed connectivity, climate control, ergonomic furnishings, and on-demand conference facilities to individuals and organizations without traditional long-term lease obligations. The primary commercial purpose centers on converting fixed real estate overhead into variable operating expenditure while enabling geographic flexibility for distributed workforces. Private offices and dedicated desks within the business model dimension command premium pricing due to enterprise demand for security and brand isolation. Flexible workspace facilities are absorbing the fastest membership growth as hybrid employers seek drop-in capacity without seat guarantees. Meeting rooms and event spaces represent concentrated margin pools given their per-hour yield premiums over base membership fees.
OSHA workplace safety standards, the US Internal Revenue Service remote worker tax guidelines, and Canadian provincial employment standards collectively shape operator compliance burdens and employer subsidy structures for flexible workspace expenditure. Municipal zoning boards across major US and Canadian cities increasingly classify coworking under commercial office rather than retail or light industrial designations, altering permissible locations and parking requirements. Stakeholders must monitor how municipal tax abatement policies for commercial vacancy reduction influence landlord willingness to convert traditional office stock into flexible formats.
Market Dynamics
Enterprise hybrid work mandates are compressing traditional office lease durations while fragmenting employee geographic distribution, forcing landlords to absorb vacancy risk through management-agreement partnerships with flexible workspace operators.
Growth Catalysts
- US IRS remote worker guidelines:Multi-state employers face payroll tax complexity when workers relocate, creating incentive to consolidate satellite staff into registered coworking locations with clear nexus documentation.
- Technology startup cluster formation:Austin, Toronto, and New York City attract venture-funded firms seeking talent density without five-year lease commitments, concentrating demand in metropolitan cores with transit accessibility.
- OSHA workplace safety standards:Compliance with ventilation, ergonomics, and emergency egress requirements becomes streamlined when employers outsource facility management to specialized operators rather than self-certifying home offices.
Market Restraints
- Commercial mortgage debt maturities:Regional banks hold concentrated exposure to 2019-vintage office loans, constraining landlord willingness to convert Class A space to flexible formats amid refinancing uncertainty.
- Municipal zoning reclassification:Parking minimums and fire code occupancy calculations designed for traditional single-tenant buildings create permitting delays for multi-tenant coworking retrofits in suburban jurisdictions.
- Virtual collaboration platforms:Synchronous video infrastructure and asynchronous project management tools reduce the functional necessity of physical presence for knowledge work coordination.
Strategic Opportunities
- Canadian provincial employment standards harmonization:British Columbia and Ontario are aligning remote work expense reimbursement rules, creating clarity for employers subsidizing flexible workspace memberships as taxable benefits.
- Life sciences laboratory coworking:Wet lab infrastructure with shared equipment access and hazardous waste handling permits addresses venture-stage biotech firms priced out of dedicated research park leases.
- AI-enabled space optimization:Computer vision occupancy tracking and predictive HVAC scheduling converge to reduce per-seat energy costs while improving air quality compliance documentation.
Industry Challenges
- Facilities engineering talent scarcity:Operators competing for building systems technicians capable of maintaining enterprise-grade network redundancy and biophilic environmental controls face wage pressure from data center and healthcare sectors.
- Enterprise security certification timelines:SOC 2 Type II and ISO 27001 audits for shared infrastructure environments require 12-18 month implementation cycles, delaying contract execution with financial services and defense contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coworking Spaces Market |
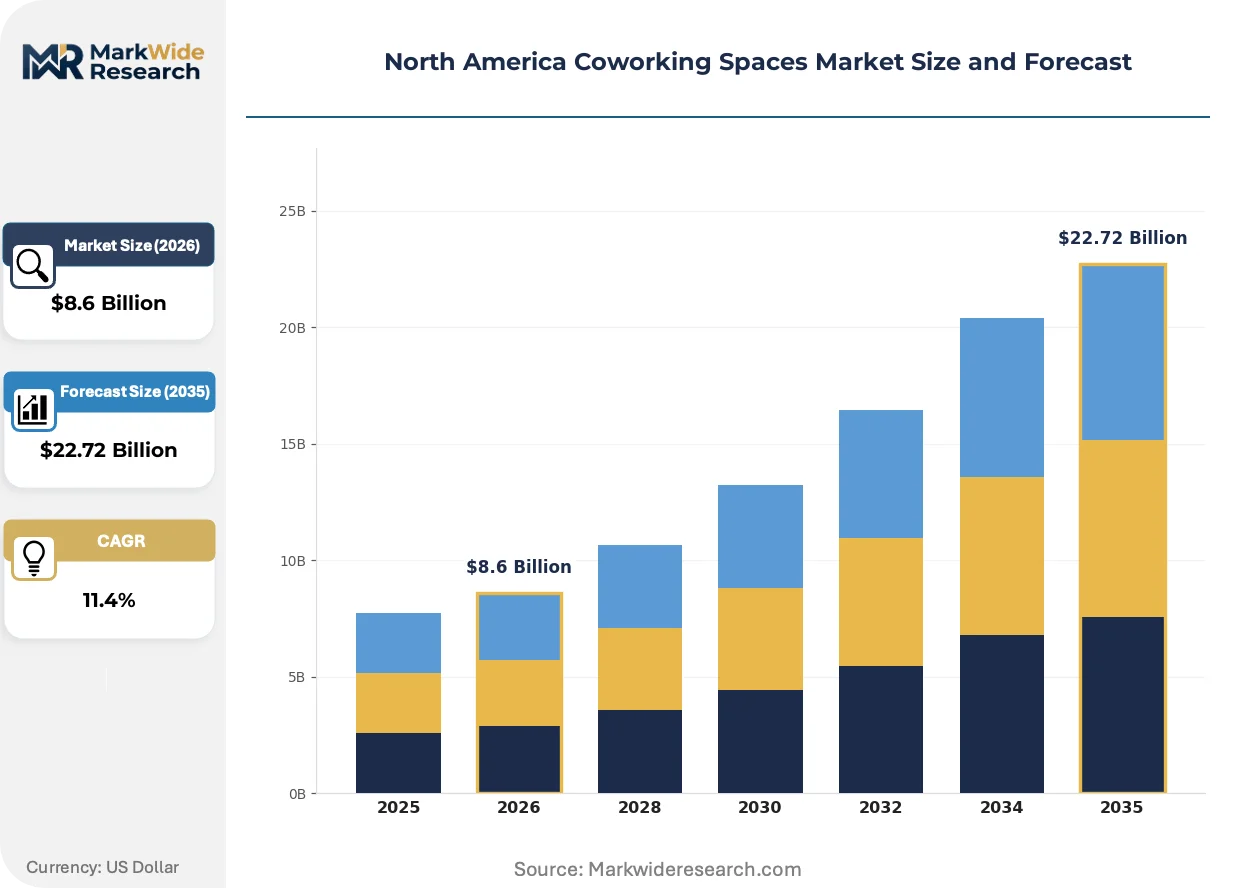
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $22.72 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Membership, Pay-as-You-Go, Private Offices, Dedicated Desks Facility Type: Corporate, Academic, Startup, Flexible Workspace End User: Freelancers, Startups, SMEs, Enterprises Service Offering: Virtual Office, Meeting Rooms, Event Spaces, Networking Events |
| Companies Covered | International Workplace Group (IWG), WeWork Inc., Industrious LLC, Serendipity Labs, Premier Workspaces, Convene, Expansive, Vast Coworking Group, Impact Hub, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coworking Spaces Market Evolving Landscape
Workspace technology stacks are converging with enterprise IT infrastructure, erasing the historical boundary between landlord-provided amenities and tenant-managed systems while generating new data governance obligations.
Smart building sensors measuring occupancy density, acoustic comfort, and indoor air quality is hybridizing physical infrastructure with wellness certification frameworks. Enterprise occupiers pursuing WELL Building Standard and Fitwel ratings are mandating these installations as lease conditions. The technology is compressing the due diligence timeline for portfolio expansion by providing standardized environmental performance documentation across distributed locations.
Canadian provincial employment standards boards and US state labor departments are clarifying remote work expense reimbursement obligations. Ontario's Employment Standards Act amendments and California Labor Code provisions now explicitly address flexible workspace subsidies as compensable benefits. Multi-state employers are responding by centralizing satellite office procurement through managed workplace service contracts rather than individual employee reimbursement programs.
Corporate real estate teams are unbundling the traditional bundled lease model, separating physical space from technology infrastructure, hospitality services, and community programming. Financial services and professional services firms in Manhattan and Toronto are piloting membership-based access across multiple operator networks rather than committing to single-vendor exclusive arrangements. This procurement fragmentation is most visible in the technology and consulting verticals where project-based staffing creates unpredictable headcount fluctuations.
North America Coworking Spaces Market Segmentation
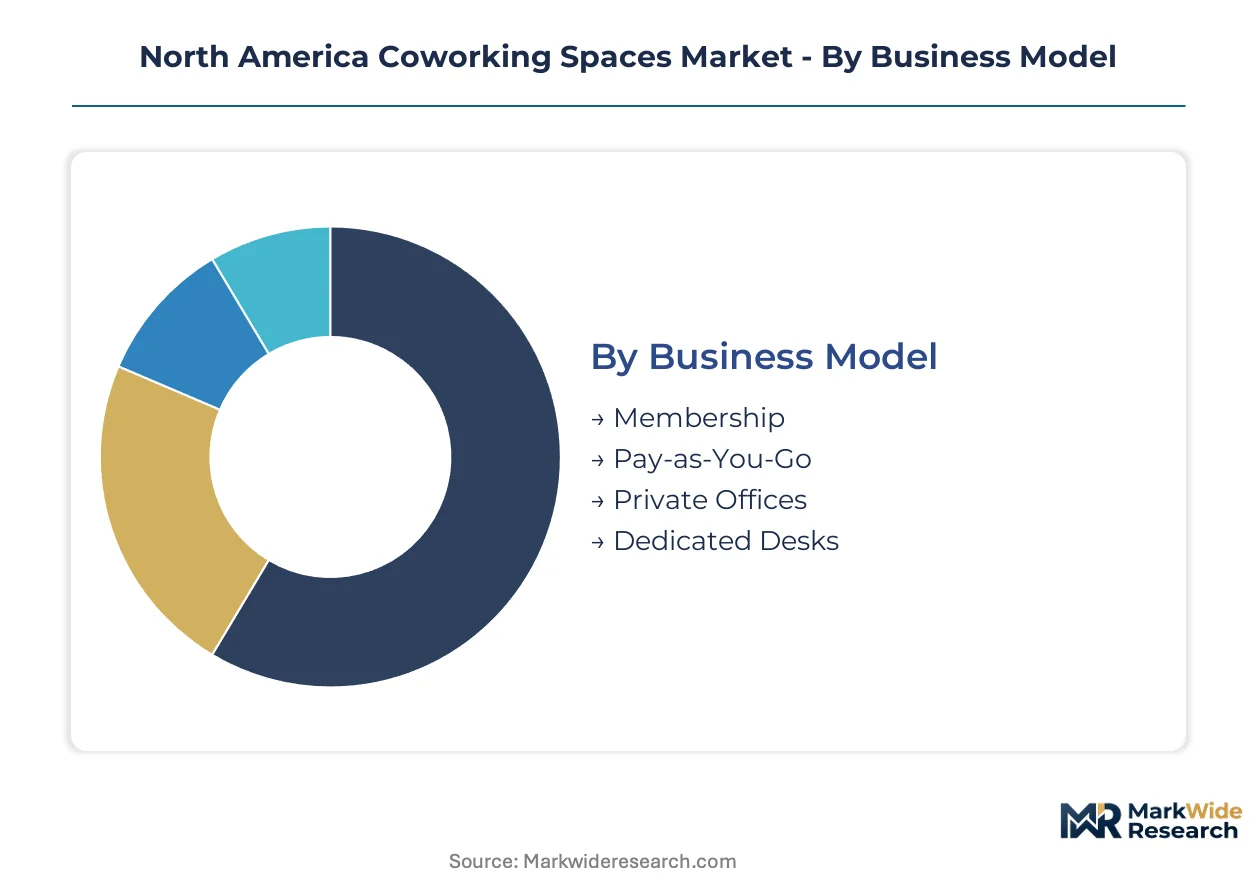
North American coworking operators structure pricing and service tiers around commitment duration, facility infrastructure, and professional support intensity. Segmentation reveals how revenue concentrates in recurring membership models while growth accelerates in on-demand formats serving distributed enterprise teams.
Business Model:
After-sales service intensity varies dramatically across commitment structures, with long-term contracts demanding proactive account management and short-term formats requiring frictionless self-service platforms.
- Membership:Recurring monthly or annual contracts bundle workspace access with amenities, community programming, and dedicated support channels. Demand concentrates among SMEs in Austin and Toronto seeking cost predictability without property management burdens. Enterprise procurement teams favor this model for satellite office standardization across multiple cities.
- Private Offices:Enclosed suites with brand isolation and security controls command premium positioning. Financial services firms in Manhattan and defense contractors near Washington D.C. drive uptake where data protection requirements exceed open floor capabilities.
- Dedicated Desks:Reserved workstations within shared environments balance permanence with cost efficiency. Technology startups in Seattle and Boston favor this tier during growth phases before committing to full suites.
- Pay-as-You-Go:Drop-in day passes and hourly credits serve unpredictable schedules. Hybrid employers subsidizing employee-chosen work locations generate fastest volume expansion in this category.
By volume, Membership leads. By growth pace, Pay-as-You-Go is climbing the fastest as employers decentralize workforce location policies.
Facility Type:
Cost tier differentiation separates purpose-built corporate campuses from repurposed industrial conversions, with capital intensity determining operator partnership structures.
- Flexible Workspace:Multi-tenant facilities with hot-desking, reservable offices, and event infrastructure dominate new supply. Landlord management agreements in Vancouver and Chicago shift construction risk to property owners while operators focus on tenant experience.
- Corporate:Single-tenant flexible formats within larger office buildings serve enterprise satellite requirements. Professional services firms in Dallas and Atlanta lease these for project teams needing proximity to client sites without long-term obligations.
- Startup:Accelerator-integrated spaces combine coworking with venture programming and investor access. Density in Silicon Valley and New York City creates network effects that sustain above-market pricing.
- Academic:University-affiliated facilities bridge student entrepreneurship and commercial research commercialization. Boston and Toronto campuses anchor demand where institutional partnerships reduce customer acquisition costs.
By footprint, Flexible Workspace leads. By margin expansion, Corporate formats are gaining share fastest as enterprise procurement centralizes.
End User:
Customer type determines service bundling complexity, with enterprise accounts demanding customized SLAs and individual users prioritizing digital self-service.
- Enterprises:Multi-location contracts with standardized security, technology, and wellness specifications. Fortune 500 real estate teams in Manhattan and San Francisco consolidate vendor relationships to simplify hybrid work compliance documentation.
- SMEs:Regional businesses seeking professional address credibility and meeting infrastructure without capital expenditure. Professional services and creative agencies in Denver and Miami represent core demand.
- Startups:Venture-funded firms prioritizing talent density and scaling flexibility over cost minimization. Austin and Toronto technology clusters concentrate this segment.
- Freelancers:Individual practitioners purchasing access for client meetings and productivity separation from residential environments. Growth correlates with platform economy participation rates across US metropolitan areas.
By contract value, Enterprises lead. By headcount growth, Startups are expanding most quickly as venture deployment concentrates in select hubs.
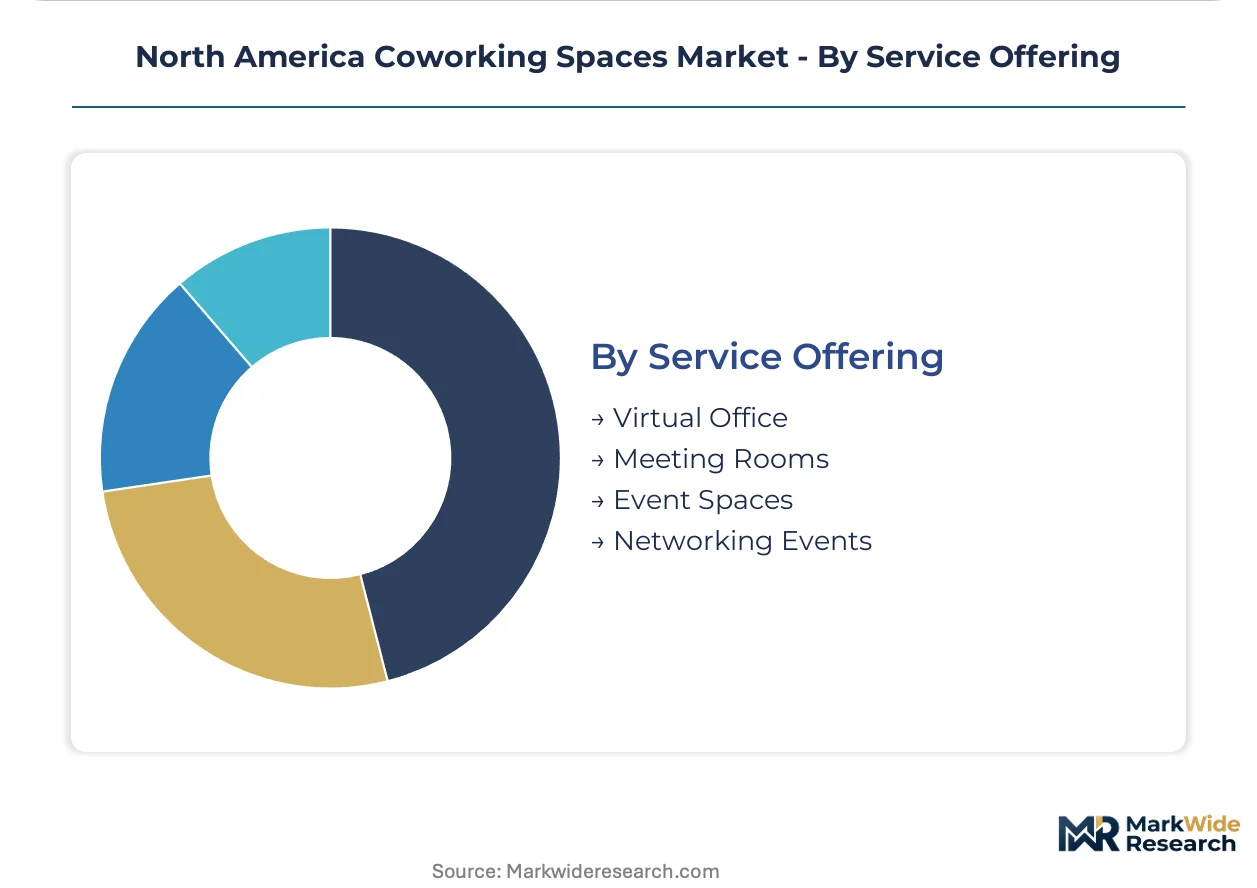
Service Offering:
Margin structure varies by asset utilization pattern, with physical space commanding hourly premiums and digital services scaling without occupancy constraints.
- Meeting Rooms:Reservable conference facilities with AV infrastructure and catering coordination. Per-hour yield multiples over base membership make this the highest-margin physical offering. Legal and consulting firms in Washington D.C. and Chicago drive premium tier demand.
- Virtual Office:Business address, mail handling, and phone answering without physical workspace. Remote-first companies seeking market presence in multiple cities sustain volume across Texas and Florida markets.
- Event Spaces:Large-format rooms for product launches, training sessions, and networking programming. Corporate marketing teams in Los Angeles and Toronto purchase episodically for campaign activations.
- Networking Events:Curated programming connecting members across industries and funding stages. Venture capital firms sponsor these to source deal flow, subsidizing operator programming costs in Boston and Seattle.
By revenue contribution, Meeting Rooms lead. By scalability, Virtual Office services are gaining share fastest as distributed work normalizes permanent remote structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border capital flows into flexible workspace infrastructure favor importing management expertise from established US operators into Canadian and Mexican markets, while Canadian pension funds export real estate investment capital into US coworking property acquisitions.
United States
Enterprise hybrid mandates and technology startup formation concentrate demand in Austin, New York City, and Seattle. OSHA workplace safety standards and US IRS remote worker tax guidelines create compliance complexity that employers resolve through registered coworking locations with clear nexus documentation. Manhattan and Brooklyn anchor the highest-value contracts as financial services firms consolidate satellite office procurement.
Canada
Ontario and British Columbia employment standards harmonization clarifies remote work expense reimbursement rules for flexible workspace subsidies. Health Canada guidelines on workplace ventilation and indoor air quality align with municipal commercial zoning reclassifications in Toronto and Vancouver. The Toronto-Waterloo corridor concentrates technology startup demand seeking talent density without long-term lease exposure.
Mexico
Nearshoring manufacturing investment from US firms generates satellite office demand for engineering and administrative support in Monterrey and Guadalajara. Mexican federal labor law amendments address remote work expense obligations, creating framework clarity for employers subsidizing coworking memberships. Mexico City anchors premium flexible workspace supply serving multinational corporate regional headquarters.
North America Coworking Spaces Market Competitive Landscape
On the supply side, the industry is consolidating around asset-light franchise and management-agreement models that shift real estate risk to property owners. Three strategic archetypes dominate: brand-leveraged platform operators, landlord-partnership specialists, and multi-format portfolio managers. Competitive moves concentrate on management agreement expansion and technology platform licensing rather than balance-sheet property acquisition.
Within the brand-leveraged tier, WeWork Inc. and IWG occupy positions exemplifying scale-driven platform approaches, while Industrious LLC represents the landlord-partnership archetype. These three entities anchor competitive dynamics through differentiated risk allocation structures and enterprise contract positioning.
| Leading Market Players |
|---|
| International Workplace Group (IWG) |
| WeWork Inc. |
| Industrious LLC |
| Serendipity Labs |
| Premier Workspaces |
| Convene |
| Expansive |
| Vast Coworking Group |
| Impact Hub |
| Others |
Value Network & Pricing Analysis
Undercapacity in premium flexible workspace facilities across Manhattan and San Francisco is compressing lease spreads and forcing operators to prioritize yield-per-square-foot over volume occupancy, reshaping both supplier financing terms and tenant pricing tiers.
Pricing Analysis
Enterprise procurement teams anchor pricing structures through multi-year membership contracts that stratify across premium private suites, standard dedicated desks, and economy hot-desking tiers. Price differentiation hinges on security certification level (SOC 2 Type II compliance commands 15-25% premiums) and geographic delivery cost (urban core transit-accessible locations sustain above-suburban pricing). Cost compression in the economy tier is intensifying because landlord management agreements are shifting real estate risk to property owners, squeezing operator margins. Freelancers and individual practitioners demonstrate highest price sensitivity, while defense contractors and financial services firms exhibit least sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as operators negotiate supply-chain finance facilities with furniture manufacturers and AV infrastructure vendors. Physical infrastructure concentrates in the United States, Canada, and Mexico, with Canadian pension funds exporting capital into US property acquisitions while importing management expertise from established US operators. Raw material dependencies include ergonomic furniture systems, enterprise-grade networking equipment, and biophilic environmental controls. Single-source vulnerability in specialized HVAC and air quality monitoring systems creates operational risk. Distribution runs through landlord-partnership structures that shift construction and retrofit risk to property owners while operators retain tenant experience management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America coworking spaces represent a high-growth disruption as enterprise hybrid work mandates and IRS remote worker tax guidelines create structural demand for registered satellite office locations with clear nexus documentation.
For Market Incumbents: Harden enterprise security certification pipelines to compress SOC 2 Type II and ISO 27001 implementation cycles from 18 months toward 12 months, defending against specialized operators targeting financial services and defense contractor contracts. Deepen backward integration into proprietary workspace technology platforms that embed with tenant IT infrastructure, creating switching costs that sustain retention across volatile lease cycles. For New Entrants and Emerging Players: Establish a beachhead in life sciences laboratory coworking across Boston and San Diego, where wet lab infrastructure scarcity and hazardous waste handling permits create defendable moats against generalist operators. Target Canadian provincial markets where employment standards harmonization is clarifying remote work expense reimbursement rules, reducing employer procurement friction. For Investors and Strategic Acquirers: Long-term, this sits as a real estate technology play because workspace platforms are converging with enterprise IT infrastructure and generating proprietary occupancy data with recurring SaaS-like revenue characteristics. Monitor municipal zoning reclassification momentum as the signal indicating landlord willingness to convert traditional office stock into flexible formats at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Management Agreement Expansion | Asset-light scaling shifts real estate risk to property owners while operators capture recurring revenue streams. |
| Enterprise Security Certification | SOC 2 Type II and ISO 27001 compliance unlocks financial services and defense contractor contract opportunities. |
| Technology Platform Licensing | White-label workspace management software generates recurring revenue from regional operator partnerships. |
| Life Sciences Infrastructure Buildout | Wet lab coworking addresses venture-stage biotech firms priced out of dedicated research park leases. |
| Canadian Provincial Market Entry | Ontario and British Columbia employment standards harmonization reduces employer procurement friction. |
Research Methodology
Initial hypotheses were tested against primary input from corporate real estate directors, flexible workspace operators, landlord partnership managers, and enterprise facilities procurement leads, and refined through secondary validation against municipal zoning board records, OSHA workplace safety filings, SEC real estate investment trust disclosures, and Canadian provincial employment standards amendments. Bottom-up location-level demand modeling triangulated against top-down metropolitan cluster economic indicators.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across business model (membership, private office, dedicated desk, pay-as-you-go), facility type (flexible workspace, corporate, startup, academic), and end user (enterprise, SME, startup, freelancer). CAGRs were derived through trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Forecast inputs included venture capital deployment patterns into technology clusters and commercial mortgage debt maturity schedules affecting landlord conversion willingness.
Stress conditions across commercial office vacancy rates, remote work tax guideline enforcement intensity, and virtual collaboration platform functionality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise hybrid work policy persistence and municipal zoning reclassification velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market