
 Latin America Commercial Real Estate Market | 2026-2036
Latin America Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Commercial Real Estate Market Insights
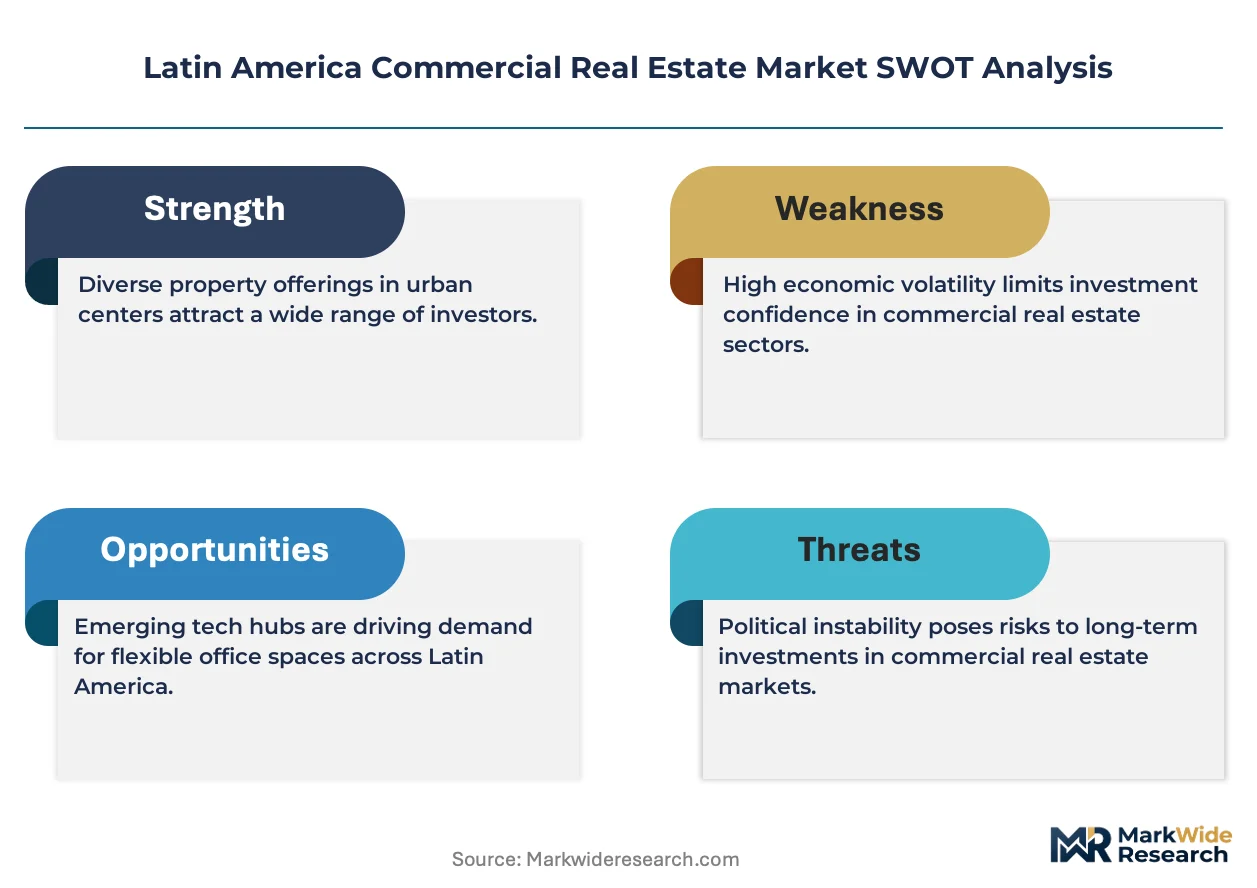
Brazilian logistics developers is expanding speculative warehouse supply near São Paulo's Guarulhos cargo hub. CBRE Group leverages its tenant representation platform to capture cross-border leasing mandates. JLL sustains valuation advisory dominance across Mexico City's Polanco and Santa Fe submarkets. Cushman & Wakefield competes through industrial site-selection services tied to automotive and electronics nearshoring.
Latin America commercial real estate encompasses income-producing properties including office towers, retail centers, industrial warehouses, and mixed-use developments, typically engineered with reinforced concrete frames, curtain-wall facades, and floor plates spanning 1,000–4,000 square meters to accommodate flexible tenant configurations. These assets generate returns through lease contracts, capital appreciation, or development profits, serving institutional portfolios seeking yield diversification beyond fixed-income instruments. Office stock in Mexico City and Santiago retains premium pricing despite hybrid-work headwinds, while industrial assets in Monterrey and Querétaro command the fastest absorption rates due to manufacturing relocation from Asia. Retail properties face structural repricing as e-commerce penetration alters foot-traffic patterns, concentrating investor interest in last-mile logistics conversion opportunities.
Brazil's Lei Geral do Urbanismo and Mexico's Normas Oficiales Mexicanas shape building codes, environmental compliance, and density allowances that directly affect project feasibility timelines. ANVISA guidelines influence pharmaceutical-grade industrial specifications, while BIS-equivalent local certification bodies enforce structural safety standards across Argentine and Chilean developments. Stakeholders must monitor how pending ESG disclosure rules from securities regulators in Brazil and Mexico will reshape capital access for non-compliant assets.
Market Dynamics
Nearshoring manufacturing relocation from Asia is compressing industrial land absorption cycles across Mexico's northern corridor, forcing developers to pre-lease speculative warehouse stock before breaking ground.
Growth Catalysts
- Lei Geral do Urbanismo:Brazil's consolidated urban planning framework accelerates mixed-use project approvals in São Paulo, reducing entitlement timelines for vertical developments.
- Automotive nearshoring:Original equipment manufacturers from Asia and Europe are securing long-term industrial leases in Querétaro and Monterrey, creating sustained demand for Class A logistics facilities.
- Curtain-wall glazing advances:High-performance facade systems reduce HVAC loads in Mexico City office towers, improving net operating income margins for institutional landlords.
Market Restraints
- Reinforced concrete input volatility:Cement and steel price fluctuations across Brazil and Mexico compress development yields, forcing sponsors to secure fixed-price contracts before construction financing closes.
- Land banking concentration:Industrial site availability concentrates among a handful of domestic landholders in Monterrey's Apodaca corridor, limiting competitive bidding for anchor tenants.
- Hybrid-work permanence:Occupancy rates in Class A office submarkets remain structurally below pre-pandemic baselines, repricing core assets in Polanco and Santa Fe.
Strategic Opportunities
- Last-mile logistics conversion:Underperforming retail centers in São Paulo's peripheral zones offer repositioning potential for e-commerce fulfillment facilities serving same-day delivery networks.
- ESG disclosure alignment:Pending securities regulator mandates in Brazil and Mexico will bifurcate capital access, creating first-mover advantage for developers with certified green building stock.
- Cross-border capital platforms:Chilean pension funds and Colombian insurance pools are deploying incremental allocations into Mexican industrial REITs, expanding the institutional buyer base.
Industry Challenges
- Environmental licensing velocity:SEMARNAT permitting timelines for industrial projects in Mexico frequently exceed 18 months, creating carry-cost burdens that erode project returns.
- Structural engineering specialization:Seismic design expertise for high-rise commercial towers concentrates among a limited pool of certified firms in Santiago and Mexico City, constraining development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Commercial Real Estate Market |
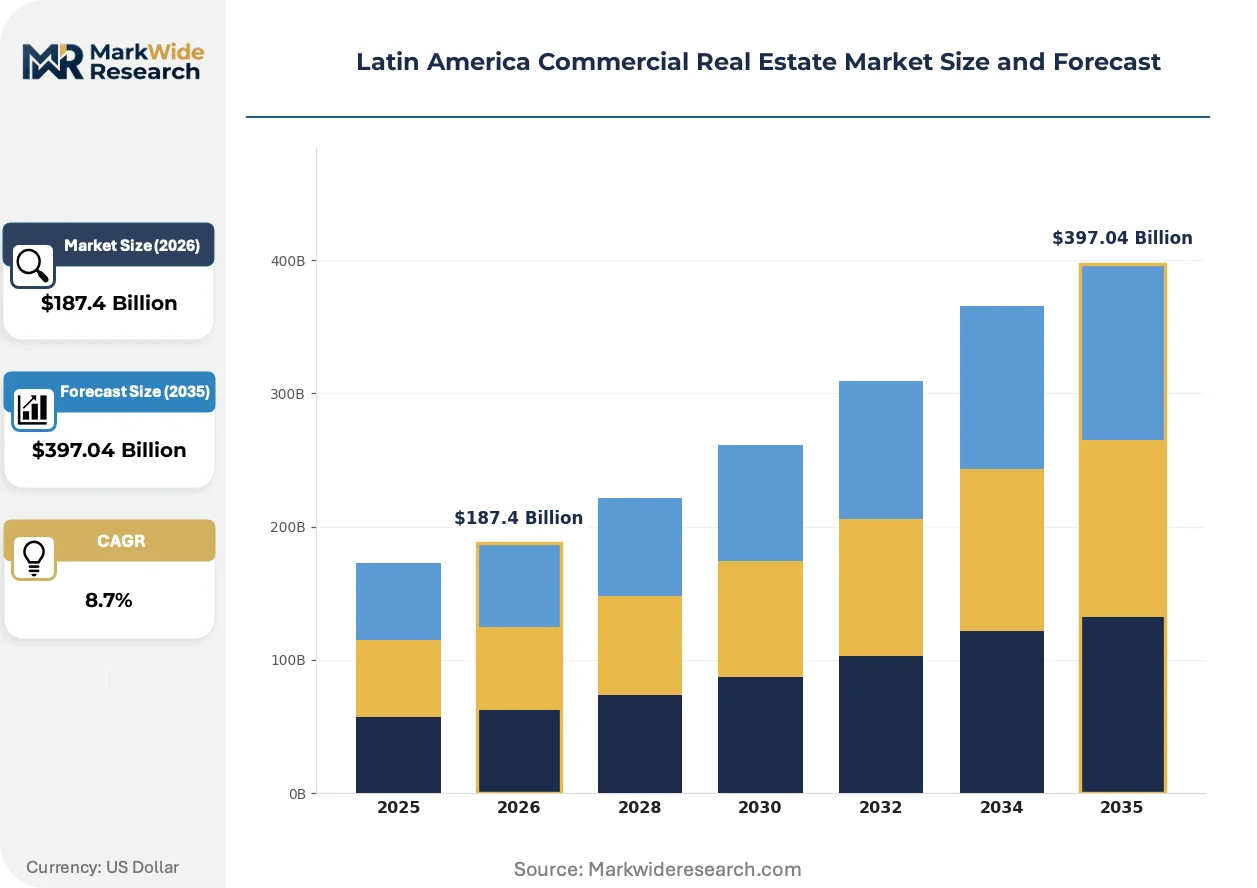
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Strategy: Core, Value-Add, Opportunistic, Debt Client Type: Institutional Investors, Private Equity, REITs, Family Offices Delivery Model: Leasing, Sales, Joint Ventures, Development |
| Companies Covered | CBRE Group, JLL, Cushman & Wakefield, LOGAN, Cyrela Brazil Realty, OAS, Andrade Gutierrez, Empresa ICA, Newmark, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Commercial Real Estate Market Trends and Innovations
Digital infrastructure integration and sustainability certification are compressing the traditional development playbook, forcing asset managers to retrofit operating assumptions for connected buildings and carbon-accounting transparency.
Building management systems deploying IoT sensor networks across HVAC, lighting, and security infrastructure are automating energy optimization in Class A office towers. Institutional landlords in Mexico City's Santa Fe submarket are mandating smart building specifications for new leases. This automation is compressing operating expense ratios and extending asset competitive positioning against older stock.
Normas Oficiales Mexicanas updates for energy efficiency in commercial buildings are tightening envelope performance standards for new construction. Developers in Monterrey's industrial corridor must now incorporate solar-ready roofing and EV charging infrastructure into speculative warehouse designs. The industrial segment is responding by pre-certifying assets to LEED or EDGE standards before marketing to multinational tenants.
Tenant representation models are fragmenting as occupiers unbundle brokerage, project management, and workplace strategy advisory into separate procurement streams. Corporate real estate directors in São Paulo and Santiago are directly engaging specialized logistics site-selection consultants for industrial mandates, bypassing traditional full-service relationships. This disintermediation is most visible among automotive and electronics manufacturers executing nearshoring strategies.
Latin America Commercial Real Estate Market Segmentation
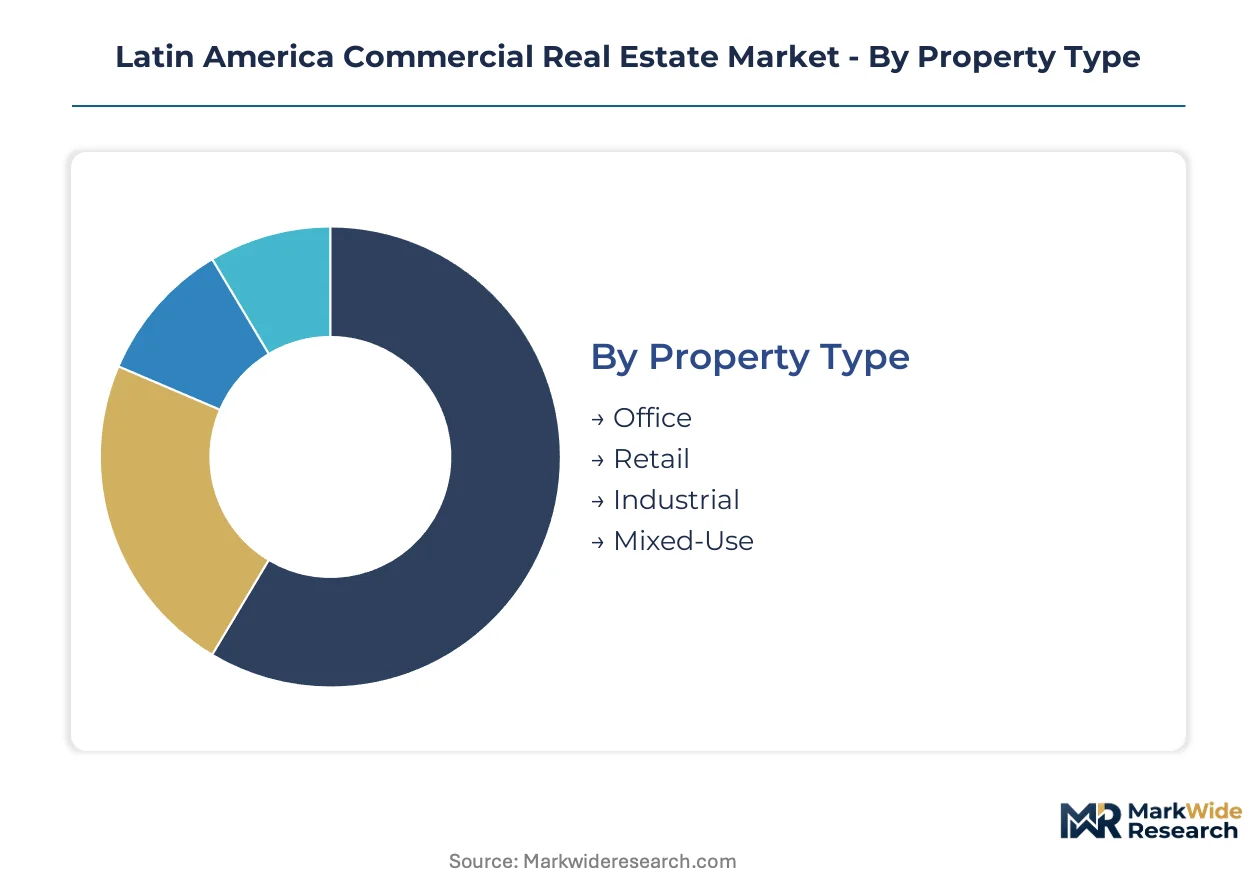
Commercial real estate segmentation in Latin America reveals distinct capital deployment patterns, with property type and investment strategy combinations determining risk-return profiles. Institutional capital flows disproportionately toward stabilized industrial assets and value-add office repositioning, while development-stage exposure concentrates in mixed-use vertical projects.
Property Type:
Capital intensity varies sharply across property types, with mixed-use developments requiring the highest upfront land assembly and vertical construction costs.
- Office:Reinforced concrete frames and curtain-wall facades dominate Class A construction in Mexico City's Santa Fe and Polanco submarkets. Demand concentrates in Santiago's financial district despite hybrid-work occupancy compression, as institutional landlords prioritize long-term lease structures over short-term yield.
- Industrial:Speculative warehouse stock near São Paulo's Guarulhos cargo hub and Monterrey's Apodaca corridor commands pre-leasing requirements before ground-breaking. Automotive and electronics manufacturers executing nearshoring strategies are securing long-term logistics leases in Querétaro, accelerating absorption cycles.
- Retail:Peripheral shopping centers in São Paulo face structural repricing from e-commerce penetration, redirecting investor interest toward last-mile conversion opportunities and grocery-anchored neighborhood formats.
- Mixed-Use:Brazil's Lei Geral do Urbanismo is accelerating vertical project approvals in São Paulo, reducing entitlement timelines for residential-office-retail combinations that capture density premiums.
Industrial absorbs the bulk of installed capacity; mixed-use is expanding most quickly.
Investment Strategy:
Risk tolerance and return hurdles segment capital deployment, with core strategies commanding the lowest target yields and opportunistic approaches requiring the highest.
- Core:Stabilized Class A office in Mexico City and Santiago attracts Chilean pension funds and Colombian insurance pools seeking yield diversification. Long-term lease structures and institutional tenant credit underpin defensive positioning.
- Value-Add:Office repositioning in Polanco and retail-to-logistics conversions in São Paulo's peripheral zones capture renovation-driven IRR expansion. Sponsors must secure fixed-price construction contracts before financing closes to protect against cement and steel volatility.
- Opportunistic:Ground-up development in Monterrey's industrial corridor and entitlement-stage land banking concentrate among domestic operators with SEMARNAT permitting expertise. Carry-cost burdens from 18-month environmental licensing timelines erode project returns.
- Debt:Construction financing and mezzanine structures fill capital stack gaps for vertical developments, with Brazilian and Mexican securities regulator ESG disclosure mandates reshaping terms for non-compliant borrowers.
Core strategies deploy the greatest capital volume; opportunistic approaches are climbing the fastest.
Client Type:
Capital source determines investment horizon and liquidity requirements, with institutional pools favoring longer holds and REITs prioritizing distribution visibility.
- Institutional Investors:Chilean AFPs and Colombian insurers are deploying incremental allocations into Mexican industrial REITs, expanding the institutional buyer base for stabilized logistics assets.
- Private Equity:Value-add and opportunistic mandates target São Paulo mixed-use and Monterrey industrial development, with 5-7 year hold periods aligned to sponsor promote structures.
- REITs:Mexican FIBRAs and Brazilian FIIs require distribution-sustaining cash flows, concentrating portfolios in leased office and industrial with minimal development risk.
- Family Offices:Patient capital enables land banking in Querétaro and direct development of trophy assets, often through joint venture structures with institutional operating partners.
Institutional investors anchor transaction volume; private equity is gaining share fastest.
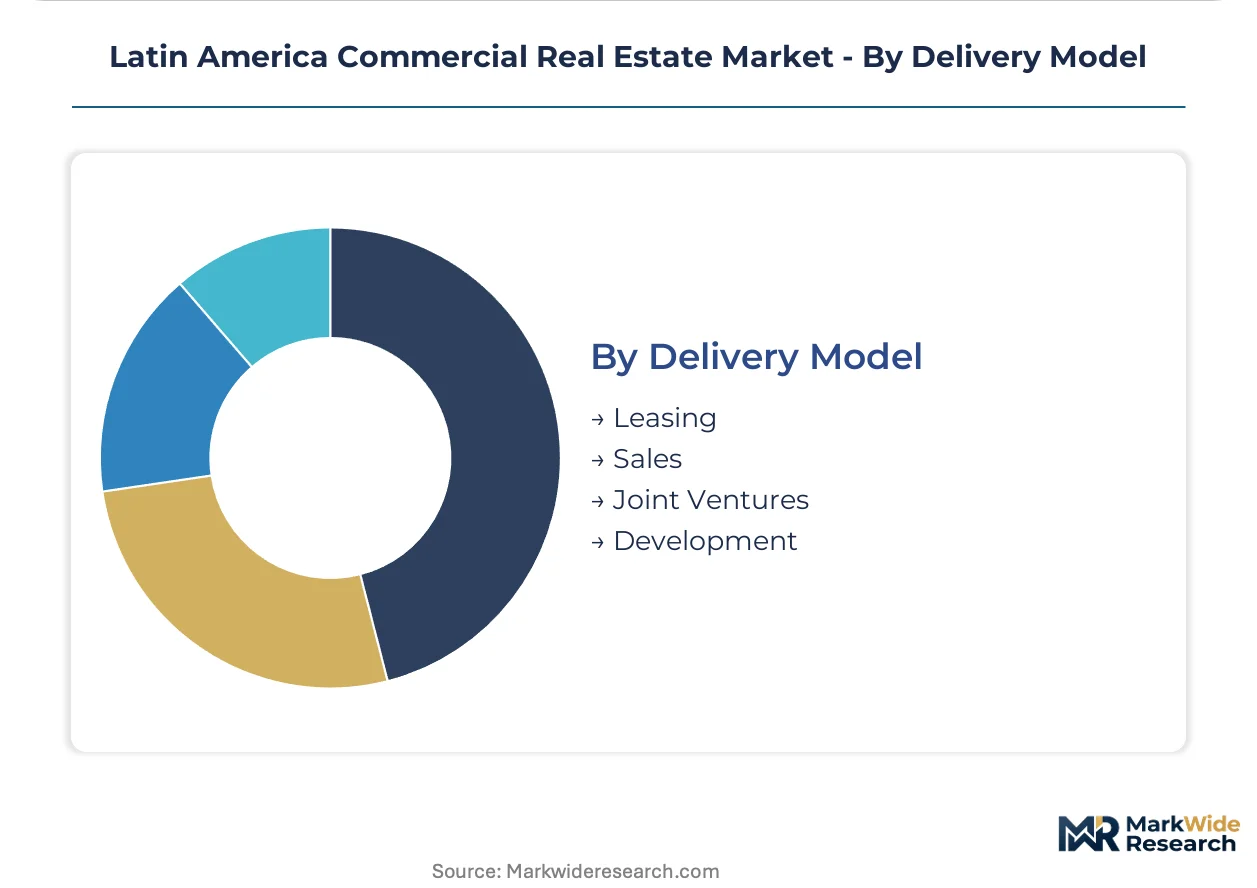
Delivery Model:
Revenue recognition timing and risk allocation differentiate delivery structures, with development carrying the highest execution risk and leasing providing the most predictable income.
- Leasing:Tenant representation platforms capture cross-border mandates as corporate real estate directors unbundle brokerage services. Smart building specifications are becoming mandatory for new Class A office leases in Santa Fe.
- Sales:Trophy asset dispositions concentrate in Mexico City and São Paulo, with foreign capital competing for stabilized core properties that meet pending ESG certification requirements.
- Joint Ventures:Local developers contribute land and entitlements while institutional partners provide construction capital, splitting promotes on industrial and mixed-use projects across the region.
- Development:Speculative warehouse pre-leasing and build-to-suit manufacturing facilities for nearshoring OEMs dominate Monterrey and Querétaro pipelines, with solar-ready roofing and EV charging now mandatory under updated Normas Oficiales Mexicanas.
Leasing generates the steadiest fee income; development is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone quarries in Mexico's Yucatán Peninsula supply the calcium carbonate feedstock for cement production anchoring industrial construction across the region. Brazilian iron ore deposits in Minas Gerais state underpin rebar manufacturing for reinforced concrete frames. Chilean copper mines feed electrical infrastructure for smart building integration.
Brazil
Automotive nearshoring and e-commerce fulfillment networks drive warehouse absorption in São Paulo's Guarulhos corridor. ANVISA guidelines shape pharmaceutical-grade industrial specifications for Class A logistics facilities. Developers in São Paulo state accelerate mixed-use vertical projects under Lei Geral do Urbanismo streamlining.
Mexico
Electronics manufacturers from Asia secure long-term industrial leases in Querétaro and Monterrey. SEMARNAT environmental licensing timelines frequently exceed 18 months for industrial developments. Monterrey's Apodaca corridor concentrates speculative warehouse construction serving nearshoring demand.
Chile
Pension fund capital deployment into stabilized income-producing assets sustains office pricing in Santiago's financial district. The country's securities regulator advances ESG disclosure mandates affecting institutional capital access. Santiago's seismic design expertise concentrates among certified engineering firms constraining high-rise development capacity.
Colombia
Insurance pool allocations into Mexican industrial REITs expand cross-border capital flows from Bogotá-based institutional investors. BIS-equivalent local certification bodies enforce structural safety standards for commercial developments. Medellín's construction sector adopts curtain-wall glazing advances reducing HVAC loads in Class A towers.
Argentina
Logistics site-selection demand from automotive suppliers concentrates in Buenos Aires metropolitan industrial zones. Local certification bodies equivalent to BIS enforce reinforced concrete structural standards. Rosario's agribusiness corridor generates ancillary commercial real estate demand for processing and distribution facilities.
Latin America Commercial Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized advisory niches and technology-enabled service platforms. The market structures around three distinct maturity tiers: global brokerage networks with full-service platforms, regional development specialists with land banking expertise, and boutique consultancies targeting unbundled tenant representation. Consolidation pressure intensifies as cross-border capital mandates require multi-jurisdictional service capabilities. Dominant competitive moves include strategic partnerships linking capital sources with development expertise, and portfolio diversification into ESG-certified asset classes.
Among global service networks, CBRE Group, JLL, and Cushman & Wakefield exemplify the full-service archetype spanning valuation advisory, tenant representation, and investment sales across Mexico City, São Paulo, and Santiago. These entities occupy positions as primary gateways for institutional capital deploying into Latin American industrial and office assets. Regional development specialists including Cyrela Brazil Realty and OAS anchor the ground-up construction tier, concentrating entitlement-stage expertise within specific metropolitan corridors. Newmark represents the mid-tier expansion vector, competing through selective market entry and cross-border leasing mandate capture.
| Leading Market Players |
|---|
| CBRE Group |
| JLL |
| Cushman & Wakefield |
| LOGAN |
| Cyrela Brazil Realty |
| OAS |
| Andrade Gutierrez |
| Empresa ICA |
| Newmark |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up logistics developers in Mexico's northern corridor exert pricing discipline through pre-lease requirements before ground-breaking, compressing speculative warehouse margins while cementing long-term tenant relationships. This ownership concentration ties supply availability directly to capital access, as sponsors must secure fixed-price construction contracts before financing closes to protect against cement and steel volatility.
Pricing Analysis
Service-bundling separates full-service brokerage platforms from unbundled advisory offerings, with CBRE Group and JLL commanding premium fees for cross-border tenant representation while specialized site-selection consultants capture automotive nearshoring mandates at lower price points. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with LEED or EDGE pre-certified industrial assets in Monterrey's Apodaca corridor pricing above uncertified stock. Cost compression in standard-grade office repositioning intensifies because cement and steel input volatility erodes development yields, forcing sponsors toward fixed-price contracting. Corporate occupiers executing nearshoring strategies demonstrate lowest price sensitivity for Class A logistics with solar-ready roofing and EV charging infrastructure, while peripheral retail conversion projects face acute buyer resistance.
Supply Chain Analysis
Certification gating through ANVISA guidelines and BIS-equivalent local bodies concentrates qualified structural engineering capacity among certified firms in Santiago and Mexico City, constraining development velocity for pharmaceutical-grade and seismic-resistant commercial towers. Raw material dependencies draw from Brazilian iron ore deposits in Minas Gerais for rebar manufacturing, Mexican limestone quarries in the Yucatán Peninsula for cement feedstock, and Chilean copper mines for electrical infrastructure. Single-source vulnerability runs through SEMARNAT environmental licensing timelines that frequently exceed eighteen months for industrial projects, creating carry-cost burdens. Distribution runs through domestic landholders in Monterrey's Apodaca corridor who control industrial site availability, limiting competitive bidding for anchor tenants and compressing land banking margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America commercial real estate is consolidating around multi-jurisdictional service capabilities, with pending ESG disclosure mandates from Brazilian and Mexican securities regulators threatening capital access for non-compliant sponsors and forcing weaker players toward exit.
For Market Incumbents: Deploy smart building specification mandates to capture tenant representation platforms as corporate real estate directors unbundle brokerage services. Incumbents must secure fixed-price construction contracts before financing closes to neutralize cement and steel input volatility eroding development yields. Channel control through cross-border capital platforms linking Chilean pension funds with Mexican industrial REITs reinforces defensive positioning against emerging logistics site-selection specialists. For New Entrants and Emerging Players: The price-point gap between premium LEED-certified industrial assets and economy-grade speculative warehouse stock offers entry into São Paulo's peripheral retail-to-logistics conversion opportunities. New entrants should target underpenetrated automotive supplier site-selection advisory in Querétaro, where nearshoring OEMs bypass traditional full-service relationships. A go-to-market angle anchored in SEMARNAT permitting expertise captures entitlement-stage mandates from domestic operators facing eighteen-month environmental licensing timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor opportunistic development specialists with land banking expertise in Monterrey's industrial corridor, where carry-cost burdens from prolonged environmental licensing erode sponsor returns. Long-term viability across the analysis window hinges on ESG-certified asset accumulation ahead of securities regulator mandates bifurcating capital access. The signal to watch is pre-leasing velocity for speculative warehouse stock, as compression in absorption cycles indicates sustained nearshoring demand or emerging oversupply.| Strategic Initiative | Industry Significance |
|---|---|
| ESG Certification Pre-Loading | Developers securing LEED or EDGE certification before marketing capture first-mover advantage as Brazilian and Mexican securities regulators advance disclosure mandates. |
| Cross-Border Capital Platform Construction | Joint ventures linking Chilean AFP allocations with Mexican FIBRA structures expand institutional buyer bases for stabilized logistics assets. |
| Smart Building Retrofit Mandate | IoT sensor deployment across HVAC and lighting infrastructure compresses operating expense ratios for Class A office towers in Mexico City's Santa Fe submarket. |
| Last-Mile Logistics Conversion | Repositioning underperforming São Paulo peripheral retail centers into e-commerce fulfillment facilities captures same-day delivery network demand. |
| Fixed-Price Contracting Lock-In | Sponsors securing construction pricing before financing closes protect development yields against Brazilian and Mexican cement and steel volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among commercial real estate developers, tenant representation brokers, institutional portfolio managers, and SEMARNAT permitting consultants. SEC filings from Mexican FIBRAs and Brazilian FIIs, ANVISA pharmaceutical-grade facility guidelines, and national cement production statistics supplied validation layers. Bottom-up project pipeline tracking across Monterrey, São Paulo, and Santiago merged with top-down institutional capital flow analysis to establish market sizing.
Data-stream reconciliation across property type segmentation, investment strategy tiers, and client type allocations generated consistent volume and value outputs throughout the forecast period. The analytical framework modeled industrial absorption cycles, office occupancy compression patterns, and retail conversion velocity alongside ESG disclosure mandate implementation timelines. CAGRs derived from regression against manufacturing relocation flows, urban zoning code amendments, and cross-border pension fund allocation trends.
Inputs from Brazilian and Mexican securities regulators, Chilean pension fund administrators, and national statistics institutes were available through the study window; gaps in real-time pre-leasing transaction data introduce uncertainty bands around speculative warehouse absorption forecasts. Forecasts reflect assumptions regarding nearshoring manufacturing relocation continuity and environmental licensing timeline stability. A model refresh is warranted upon material change in SEMARNAT permitting velocity or Lei Geral do Urbanismo implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market