
 Global Shared Office Spaces Market | 2026-2036
Global Shared Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shared Office Spaces Market Foresight
Capital-intensity divergence between asset-heavy landlords and flexible operators is bifurcating competitive dynamics. IWG plc leverages its global property portfolio to sustain occupancy arbitrage across tier-one cities. Industrious anchors premium positioning through hospitality-driven design standards. WeWork Inc. competes on network density despite restructuring its lease obligations.
Shared office spaces deliver commercially furnished work environments through short-term contractual arrangements, typically provisioning high-speed connectivity, meeting infrastructure, and reception services under unified management. Co-working space leads volume absorption among office type segments, while private office commands superior per-desk economics. Monthly subscription dominates booking model adoption among remote teams, though day pass utilization accelerates fastest among freelancers seeking project-based access. Meeting rooms capture concentrated margin pools from corporate overflow demand.
OSHA workplace safety standards in the United States, the EU's GDPR framework governing tenant data processing, and India's BIS building code certifications collectively elevate compliance thresholds for operators. These regulations shape demand by mandating ventilation benchmarks, data sovereignty protocols, and structural fire ratings that filter subscale providers. Stakeholders must monitor how municipal zoning reforms in target cities redistribute permissible commercial density for flexible workspace deployment.
Market Dynamics
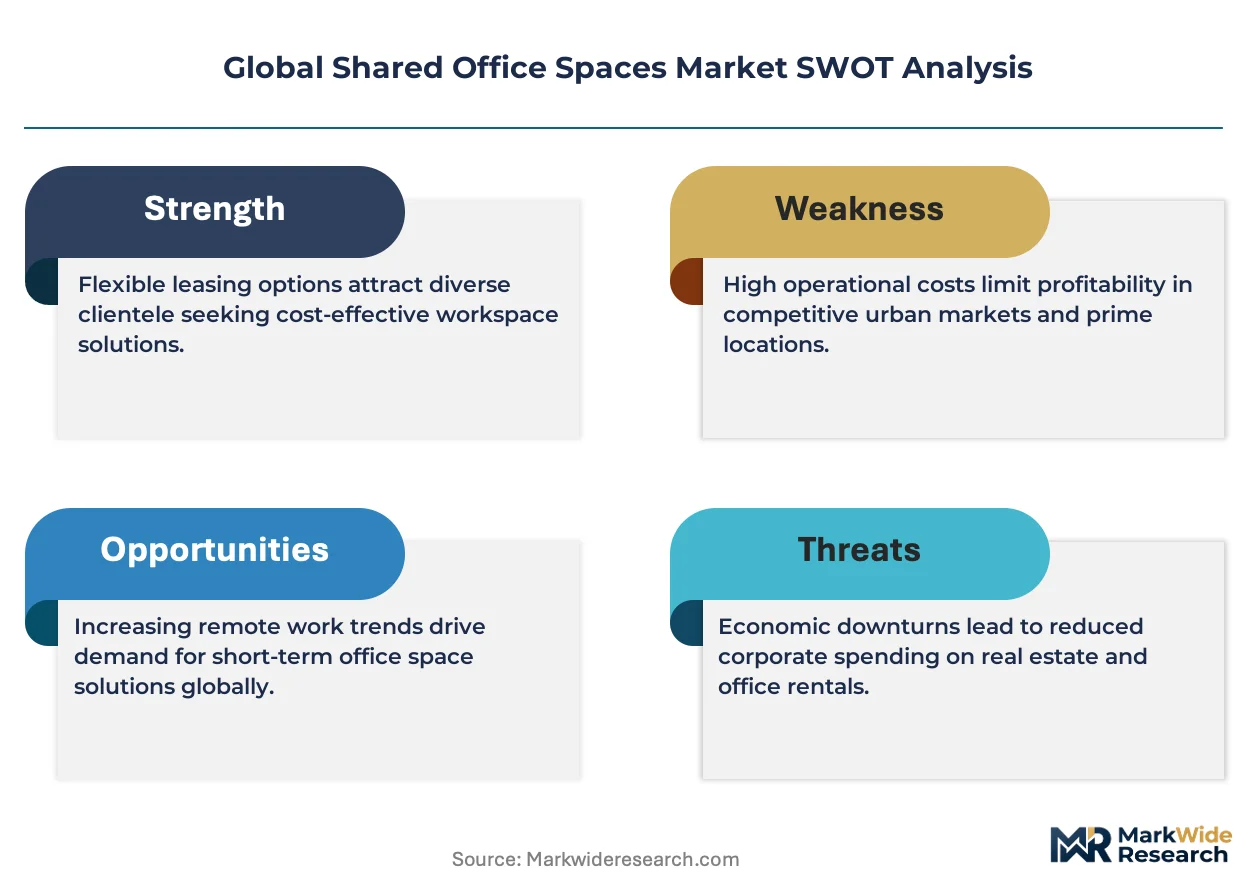
The EU's CSRD reporting mandates are forcing asset-heavy landlords to retrofit portfolios for sustainability compliance, bifurcating competitive dynamics between capital-intensive property owners and nimble flexible operators.
Growth Catalysts
- India's PLI scheme for IT hardware:Bengaluru and Hyderabad clusters attract multinational satellite offices seeking compliant workspace infrastructure. Subsidy eligibility requires domestic facility investment.
- Remote-first enterprise normalization:Technology firms anchor demand for distributed satellite locations. Short-term contractual flexibility aligns with quarterly headcount volatility.
- GDPR data sovereignty protocols:EU tenants mandate localized server infrastructure and encrypted meeting systems. Operators investing in compliant tech stacks capture corporate overflow demand.
Market Restraints
- Prime commercial rent volatility:London, New York, and Singapore CBD rates fluctuate with central bank policy. Lease obligation restructuring consumes operator liquidity.
- Building code certification delays:India's BIS fire rating approvals extend facility launch timelines by 8-14 months. Subscale providers lack capital to bridge revenue gaps.
- Corporate real estate captive expansion:Amazon and Microsoft deploy internal flexible workspace programs. Direct landlord relationships bypass operator intermediation.
Strategic Opportunities
- Secondary city penetration in India:Pune and Chennai offer 40-60% rent arbitrage versus Mumbai. Infrastructure investment lags create first-mover positioning for branded operators.
- AI-driven space optimization:Computer vision and occupancy sensors converge with building management systems. Real-time desk allocation maximizes yield per square meter.
- EU Green Deal taxonomy alignment:CSRD-compliant operators access preferential financing from ESG-mandated institutional capital. Certification premiums justify 15-25% rate differentials.
Industry Challenges
- Hospitality-service talent scarcity:Premium operators compete with hotels for front-of-house staff. Training programs for community management roles lack standardized curricula.
- Legacy lease portfolio renegotiation:Asset-heavy incumbents face 10-15 year committed obligations. Revenue-share restructuring with landlords requires complex legal arbitration.
- Multi-jurisdiction compliance integration:Operators spanning US OSHA, EU GDPR, and India BIS must maintain parallel certification audits. Fragmented regulatory technology stacks inflate overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shared Office Spaces Market |
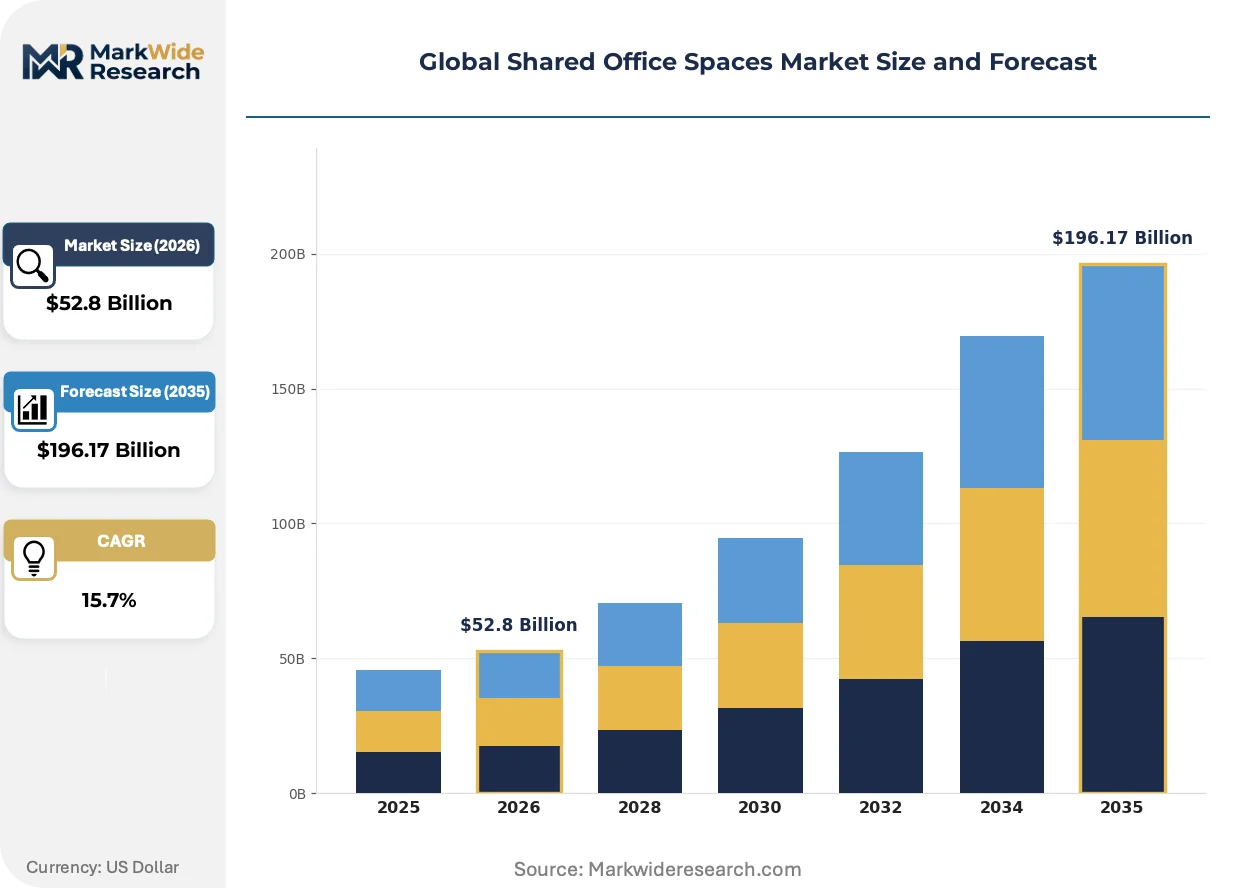
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $196.17 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Co-working Space, Private Office, Virtual Office, Meeting Rooms, Event Space Service Offering: Administrative Support, IT Infrastructure, Networking Events, Cleaning Services, Reception Services End User Industry: Startups, Freelancers, Remote Teams, Small Enterprises, Creative Agencies Booking Model: Monthly Subscription, Day Pass, Hourly Rental, Long-Term Lease, Pay-as-You-Go |
| Companies Covered | IWG plc, WeWork Inc., Industrious, Servcorp, The Executive Centre, JustCo, Mindspace, Convene, Knotel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shared Office Spaces Market Shifts & Advancements
Workspace technology is decomposing traditional facility management into modular, API-connected service layers. Sustainability certification and behavioral analytics now determine competitive positioning as much as location.
Smart building infrastructure is decomposing static HVAC and lighting systems into responsive, occupancy-triggered environments. Technology firms and financial services tenants demand real-time air quality dashboards and automated wellness interventions. This capability compression forces mid-market operators to outsource facility tech stacks or exit premium segments entirely.
CSRD sustainability disclosure requirements are mandating granular carbon accounting across landlord and tenant scopes. Industrial real estate investment trusts and pension fund allocators now screen flexible workspace providers for Science Based Targets initiative alignment. German and French corporate tenants lead contractual enforcement, inserting penalty clauses for missed emissions benchmarks.
Subscription fatigue among remote teams is fragmenting booking behavior into project-based, day-pass utilization. Freelance consultants and creative agencies in Berlin and Amsterdam reject monthly minimums, forcing operators to rebuild revenue models around dynamic yield management. This pattern compression rewards platforms with real-time inventory visibility and mobile-first reservation interfaces.
Global Shared Office Spaces Market Segmentation
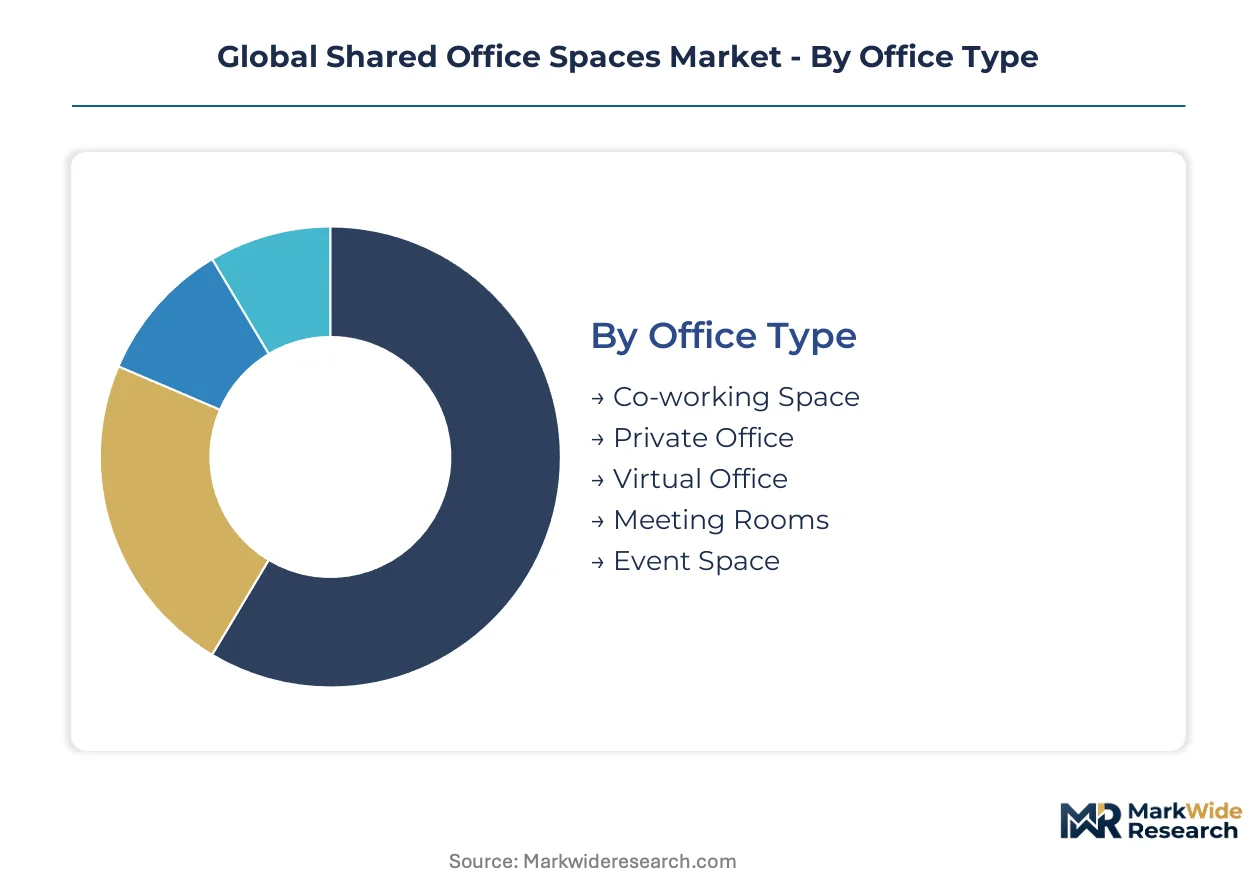
Segmentation in shared office spaces determines how operators configure capital deployment, staffing models, and technology stacks. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Office Type:
Regulatory differentiation across jurisdictions favors certain facility configurations. OSHA ventilation benchmarks in the United States, EU CSRD carbon disclosure requirements, and India's BIS fire ratings each elevate compliance costs differently by space type.
- Co-working Space:Open-plan environments with hot-desking and shared amenities dominate volume absorption. Technology firms in Bengaluru and Hyderabad anchor demand through satellite office deployment under India's PLI scheme.
- Private Office:Enclosed suites with dedicated access control command superior per-desk economics. GDPR-compliant operators in Berlin and Frankfurt capture corporate overflow demand through encrypted meeting infrastructure.
- Virtual Office:Business address and mail handling services without physical occupancy.
- Meeting Rooms:Bookable conference facilities with AV infrastructure for corporate overflow.
- Event Space:Configurable venues for workshops, product launches, and networking functions.
Co-working space handles the majority of throughput; private office is the fastest mover on share.
Service Offering:
Cost tier differentiation separates premium operators from commodity competitors. Bundled hospitality services justify rate premiums in saturated tier-one cities where location alone no longer differentiates.
- Administrative Support:Document processing, travel coordination, and executive assistance. Creative agencies in Amsterdam and Copenhagen demand multilingual support staff for cross-border client management.
- IT Infrastructure:High-speed connectivity, localized servers, and cybersecurity protocols. EU tenants mandate GDPR-compliant data sovereignty through encrypted meeting systems and domestic server hosting.
- Networking Events:Curated professional programming and industry-specific gatherings.
- Cleaning Services:Sanitization protocols meeting OSHA and BIS workplace safety standards.
- Reception Services:Front-desk staffing and visitor management with hospitality training.
IT infrastructure commands the highest margin contribution; networking events are expanding most quickly as a retention tool.
End User Industry:
Application concentration varies dramatically by geography and facility tier. Remote-first enterprise policies have redistributed demand across customer types previously served by traditional leases.
- Startups:Venture-backed companies seeking flexible scaling without capital commitment. Y Combinator and Techstars portfolio companies in San Francisco and New York drive seasonal absorption spikes.
- Remote Teams:Distributed employees of technology firms requiring satellite locations. Amazon and Microsoft internal programs compete directly with operators for this segment.
- Freelancers:Independent consultants seeking project-based workspace access.
- Small Enterprises:Professional services firms with 10-50 employees outsourcing facility management.
- Creative Agencies:Design and media studios prioritizing aesthetic environment and client meeting capacity.
Remote teams generate the most predictable recurring revenue; freelancers are gaining share fastest through day-pass adoption.
Booking Model:
Customer type and contract structure determine yield management complexity. Subscription fatigue among independent workers is fragmenting traditional monthly commitment patterns.
- Monthly Subscription:Recurring desk access with fixed billing cycles. Remote teams from technology firms anchor this segment through quarterly headcount volatility that resists long-term lease structures.
- Day Pass:Single-day access without recurring commitment. Freelance consultants in Berlin and Amsterdam reject monthly minimums, forcing dynamic yield management systems.
- Hourly Rental:Short-duration access for meeting rooms and phone booths.
- Long-Term Lease:Multi-year agreements with customization rights and branding permissions.
- Pay-as-You-Go:Usage-based billing with mobile-first reservation interfaces.
Monthly subscription retains the largest revenue base; day pass is climbing the fastest as booking behavior fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan commands per-desk premiums that exceed Mumbai rates by multiples, yet Bengaluru generates faster absorption velocity through technology firm clustering. This pricing-power asymmetry between established financial centers and emerging innovation hubs redistributes operator capital deployment priorities across the forecast window.
United States
Technology firms and financial services tenants anchor demand in Manhattan, San Francisco, and Austin. OSHA ventilation benchmarks and workplace safety standards elevate compliance costs for operators retrofitting legacy commercial stock. The Hudson Yards and Seaport District clusters in New York concentrate premium inventory where corporate overflow demand meets hospitality-driven design standards.
Germany
Frankfurt and Berlin attract GDPR-mandated corporate satellite offices requiring encrypted meeting infrastructure and localized server hosting. The EU's CSRD reporting mandates force landlords to disclose granular carbon accounting, filtering subscale providers from premium segments. The Friedrichshain-Kreuzberg district exemplifies how sustainability certification premiums justify rate differentials in tight supply conditions.
India
Bengaluru and Hyderabad clusters absorb multinational satellite offices seeking PLI scheme compliance for IT hardware manufacturing. BIS fire rating approvals extend facility launch timelines, advantaging capitalized operators who can bridge revenue gaps. The Outer Ring Road corridor and HITEC City concentration demonstrate how infrastructure investment lags create first-mover positioning for branded flexible workspace providers.
United Kingdom
London's West End and City districts face prime commercial rent volatility tied to Bank of England policy shifts. Lease obligation restructuring consumes operator liquidity while corporate tenants demand shorter contractual commitments. The Shoreditch Tech City cluster illustrates how creative agencies and venture-backed startups drive seasonal absorption spikes through project-based workspace procurement.
Singapore
Marina Bay and Raffles Place financial district tenants prioritize network density and cross-border meeting infrastructure for ASEAN operations. Municipal zoning reforms redistribute permissible commercial density, creating deployment opportunities in emerging submarkets. The Paya Lebar and Jurong Lake District developments show how government-planned commercial hubs attract operator pre-commitment through infrastructure guarantees.
Global Shared Office Spaces Market Competitive Landscape
Concentration sits with asset-heavy landlords who leverage global property portfolios against nimble flexible operators competing on hospitality-service differentiation. The vendor base stratifies across three tiers: integrated property conglomerates with captive supply chains, premium-positioned design specialists, and technology-enabled platform operators. M&A activity concentrates among mid-scale regional platforms seeking geographic footprint expansion, while strategic partnerships between landlords and hospitality brands reshape service-level competition.
Among listed operators, IWG plc exemplifies the asset-heavy archetype through scale-driven network density across tier-one cities. WeWork Inc. occupies a restructuring-dependent position where lease obligation renegotiation determines liquidity sustainability. Industrious anchors the premium-tier vector through hospitality-driven design standards that command rate premiums in saturated urban markets. These three company representations illustrate how capital structure and service positioning bifurcate competitive dynamics within the sector.
| Leading Market Players |
|---|
| IWG plc |
| WeWork Inc. |
| Industrious |
| Servcorp |
| The Executive Centre |
| JustCo |
| Mindspace |
| Convene |
| Knotel |
| Others |
Supply & Pricing Matrix
Revenue-share lease structures with landlords lock in supply access while capping price volatility exposure for flexible workspace operators. These arrangements tether occupancy costs to actual utilization, insulating balance sheets from prime commercial rent fluctuations in Manhattan, London, and Singapore.
Pricing Analysis
The customization-premium spread between configured private suites and standard hot-desking arrangements determines operator margin capture. Three-tier pricing structure across premium hospitality-driven environments, standard amenity-inclusive tiers, and economy no-frills access separates Industrious from WeWork from commodity regional players. Price differentiation hinges on CSRD sustainability certification premiums and GDPR-compliant encrypted meeting infrastructure. Cost compression in economy tiers is intensifying because freelance day-pass adoption fragments traditional monthly commitment patterns. Freelance consultants exhibit highest price sensitivity; financial services tenants leasing private offices demonstrate lowest elasticity.
Supply Chain Analysis
Just-in-time furniture procurement and modular fit-out systems dominate operator inventory strategy, minimizing capital lock-up in volatile demand environments. Supply concentration rests on China for smart building sensors, Germany for HVAC control systems, and India for BIS-certified fire suppression equipment. Raw material dependencies include steel framing, acoustic paneling, and IoT occupancy detection hardware. Single-source vulnerability in Chinese sensor supply creates exposure to tariff and logistics disruption. Distribution runs through landlord-integrated property management platforms and direct operator-tenant contractual relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shared office spaces market sits in early-cycle expansion as remote-first enterprise policies normalize distributed satellite infrastructure. India's PLI scheme for IT hardware manufacturing accelerates multinational facility deployment in Bengaluru and Hyderabad clusters.
For Market Incumbents: Consolidate lease portfolios through revenue-share restructuring with asset-heavy landlords, converting fixed obligations to variable cost structures. Deepen vertical integration into hospitality-service talent pipelines, addressing scarcity that premium operators face against hotel competitors. CSRD compliance investment separates scalable providers from subscale exits. For New Entrants and Emerging Players: Anchor in secondary Indian cities—Pune and Chennai—where 40-60% rent arbitrage versus Mumbai creates first-mover positioning before infrastructure investment catches demand. Target day-pass yield management platforms for freelance consultants in Berlin and Amsterdam, where subscription fatigue fragments booking behavior. Deploy mobile-first reservation interfaces as primary go-to-market channel. For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled platform operators with real-time inventory visibility and AI-driven space optimization capabilities. Long-term viability favors providers integrating computer vision occupancy sensors with building management systems. Watch for inflection when corporate captive programs at Amazon and Microsoft stall expansion, signaling external operator demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Sustainability Certification | EU Green Deal taxonomy alignment unlocks preferential ESG-mandated institutional financing for compliant operators. |
| AI-Driven Space Optimization | Computer vision and occupancy sensors maximize yield per square meter through real-time desk allocation algorithms. |
| Revenue-Share Lease Restructuring | Variable cost structures with landlords insulate liquidity from prime commercial rent volatility in tier-one cities. |
| GDPR-Compliant Tech Stack Investment | Localized server infrastructure and encrypted meeting systems capture corporate overflow demand from EU tenants. |
| Secondary City Geographic Expansion | Pune and Chennai infrastructure investment lags create first-mover positioning for branded operators seeking rent arbitrage. |
Research Methodology
A spread of perspectives from flexible workspace operators, commercial real estate asset managers, corporate real estate executives, and facility technology vendors converged on the working assumptions driving this analysis. Primary interviews with IWG plc regional directors, Industrious design leads, and WeWork restructuring advisors combined with secondary validation from SEC 10-K filings, EU CSRD disclosure databases, and India BIS certification records. Bottom-up desk-level absorption modeling and top-down property stock assessment triangulated volume estimates.
Segmentation dimensions modeled include office type configuration, service offering tier, end-user industry vertical, and booking model contract structure across the analysis window. CAGRs derive from regression against technology firm headcount volatility, PLI scheme subsidy trajectories, and municipal zoning reform timelines. Forecast inputs incorporate remote-first policy adoption curves and CSRD compliance cost pass-through elasticity.
Decision-makers should treat outputs as directional under assumptions of sustained remote-work normalization and stable central bank policy; material deviation would warrant model refresh. Revision becomes warranted when corporate captive program expansion crosses thresholds that eliminate external operator intermediary demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market