
 Canada Hospitality Real Estate Sector Market | 2026-2036
Canada Hospitality Real Estate Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hospitality Real Estate Sector Market Outlook
Canadian urban hotel development is consolidating around mixed-use precincts in Toronto, Vancouver, and Montreal. Brookfield Asset Management leverages its institutional capital base to anchor large-scale hospitality-integrated assets in major metros. Germain Hotels differentiates through design-forward boutique properties in Quebec and Ontario. Hilton Worldwide (Canada) extends its flagged management agreements to capture fee revenue without direct real estate ownership.
The Canada Hospitality Real Estate Sector comprises income-producing commercial properties purpose-built for temporary lodging, food service, and guest amenities, typically structured as limited partnerships or REIT vehicles with weighted average lease terms under five years. These assets generate returns through nightly room revenue, ancillary F&B operations, and event space rentals, with operational performance tied to revenue per available room metrics. Hotels and Resorts dominate current transaction volume, while Hostels represent the fastest-growing property type among experiential travelers seeking social lodging formats. Large Scale and Mega Projects concentrate institutional capital deployment, though Small Scale boutique conversions in heritage buildings command premium yield profiles.
Health Canada guidelines on commercial indoor air quality, alongside provincial building codes in Ontario and British Columbia, mandate upgraded HVAC filtration and ventilation rates for licensed accommodations. The Canada Mortgage and Housing Corporation's financing programs and municipal zoning boards in Toronto and Vancouver shape project feasibility through density bonuses and heritage preservation requirements. Stakeholders must monitor interest rate trajectories and immigration-driven demand patterns to calibrate development timelines and asset positioning.
Market Dynamics
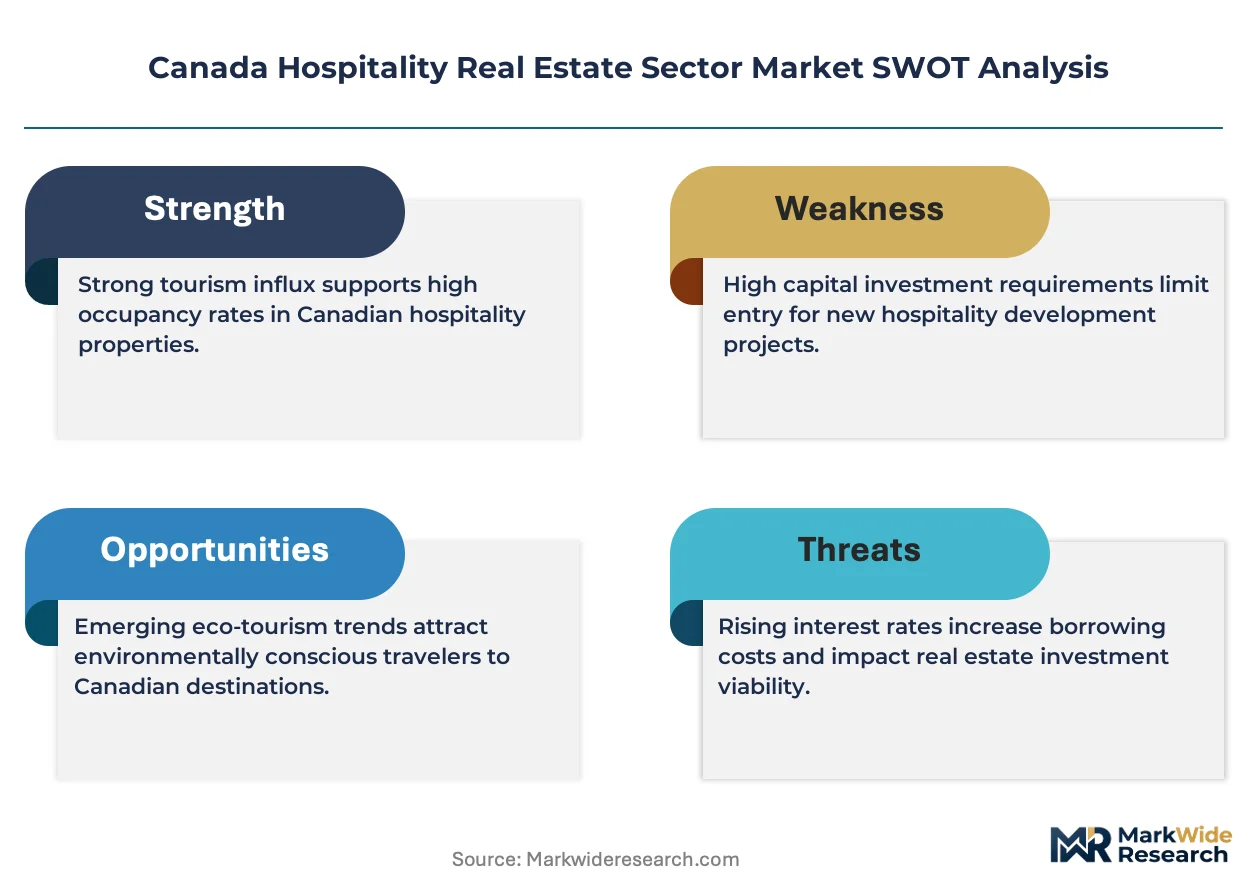
Health Canada's post-pandemic indoor air quality mandates are forcing capital reallocation across Canada's hospitality real estate portfolio, with Ontario and British Columbia building codes amplifying compliance burdens on existing assets.
Growth Catalysts
- Immigration-Driven Demand:Federal immigration targets are expanding Toronto and Vancouver's visitor base. Hotel occupancy in these corridors benefits from sustained population inflows.
- Canada Mortgage and Housing Corporation Programs:CMHC financing vehicles reduce debt-service costs for purpose-built hospitality assets. Institutional developers leverage these structures for mixed-use precincts.
- Experiential Travel Formats:Hostel and boutique segments capture younger demographics seeking social lodging. Heritage building conversions in Montreal and Quebec City command yield premiums.
Market Restraints
- Interest Rate Sensitivity:Floating-rate construction debt exposes development timelines to Bank of Canada policy shifts. Prolonged tightening cycles compress project feasibility.
- HVAC Retrofit Costs:Health Canada filtration mandates require mechanical system overhauls in pre-2010 assets. Older properties face capital-intensive compliance or functional obsolescence.
- Land Assembly Complexity:Toronto and Vancouver density bonuses demand multi-parcel aggregation. Municipal heritage preservation requirements extend entitlement timelines.
Strategic Opportunities
- Quebec Expansion Corridor:Montreal's under-supplied downtown core offers first-mover positioning. Provincial tourism incentives reduce effective development costs.
- Revenue Management Convergence:Dynamic pricing algorithms integrate with property management systems. Mid-scale operators capture rate optimization previously limited to flagged portfolios.
- Indigenous Partnership Structures:First Nations land development frameworks unlock greenfield sites near major corridors. Joint-venture structures align capital with sovereign asset control.
Industry Challenges
- Skilled Trades Shortage:Specialized hospitality construction labor concentrates in Toronto and Vancouver. Project delays cascade from mechanical and electrical contractor scarcity.
- Flagged Management Contract Complexity:Brand standards enforcement creates friction with boutique positioning. Independent operators face royalty escalation and capital improvement obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hospitality Real Estate Sector Market |
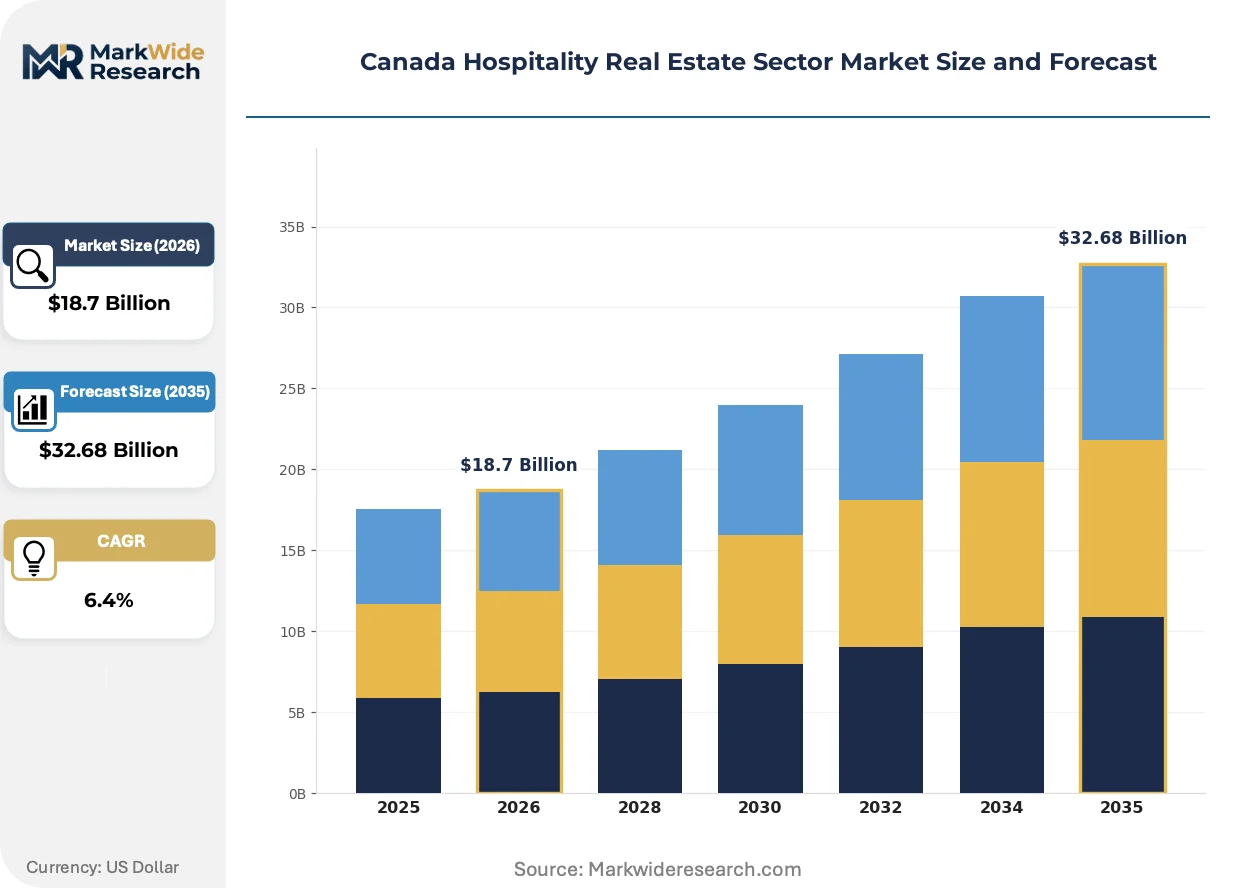
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Motels, Resorts, Hostels Service Type: Room Service, Concierge, Catering, Housekeeping Client Type: Business Travelers, Tourists, Event Organizers, Families Investment Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Superior Lodging Corp, Germain Hotels, Brookfield Asset Management, Marriott International (Canada), Hilton Worldwide (Canada), InnVest Hotels, Coast Hotels, Sunray Group, Westmont Hospitality Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hospitality Real Estate Sector Market Strategic Shifts
Digital infrastructure is compressing operational cost structures across Canada's hospitality real estate sector, with property-level automation and regulatory compliance technologies commanding disproportionate capital allocation.
Building management systems with integrated IoT sensor networks are automating energy consumption optimization across Toronto and Vancouver hotel portfolios. Mid-scale operators in Ontario are adopting these platforms faster than legacy flagged assets. The technology is automating manual engineering oversight, reducing headcount intensity in 150-plus room properties.
Health Canada's commercial indoor air quality guidelines, layered atop Ontario and British Columbia building code amendments, mandate MERV-13 filtration and increased fresh air exchange rates. These requirements are accelerating HVAC replacement cycles in assets built before 2015. Boutique conversions in heritage buildings face the steepest compliance retrofit costs.
Corporate travel procurement departments are consolidating preferred supplier agreements with mixed-use hospitality-integrated assets. Direct booking platforms and membership programs are displacing traditional online travel agency intermediaries for Toronto's downtown core properties. This concentration is most visible among technology and financial services sector accounts with sustained Vancouver-Toronto travel corridors.
Canada Hospitality Real Estate Sector Market Segmentation
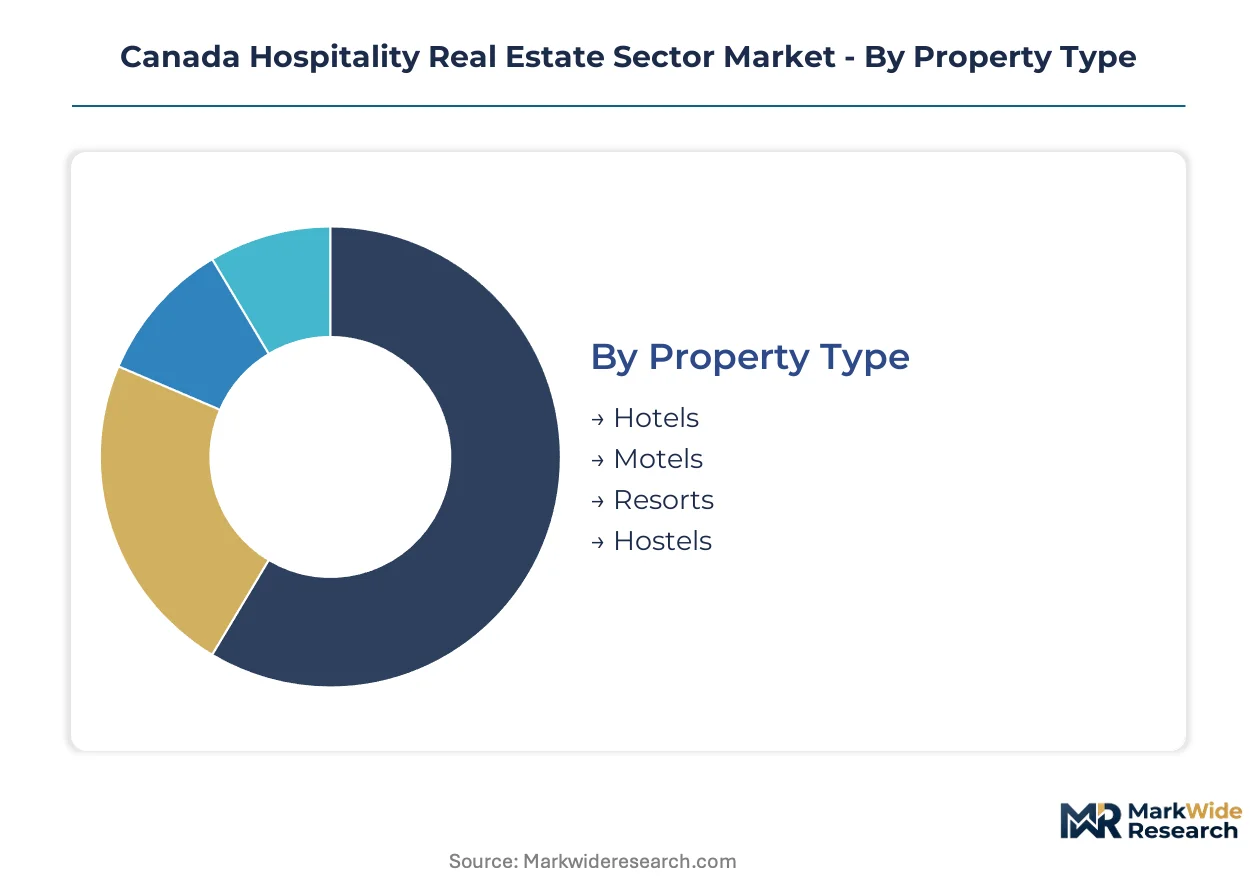
Segmentation in Canadian hospitality real estate exposes divergent capital deployment patterns across asset classes. Property type and investment size determine financing structures, operational complexity, and exit liquidity. Understanding these divisions clarifies where institutional capital concentrates versus where entrepreneurial operators find yield premiums.
Property Type:
Capital intensity varies dramatically across lodging formats, with full-service assets demanding substantially higher upfront investment than limited-service alternatives.
- Hotels:Full-service assets with food and beverage operations, meeting facilities, and concierge services command the highest construction costs per key. Toronto's downtown core and Vancouver's waterfront corridor concentrate institutional investment in flagged properties serving corporate accounts.
- Resorts:Destination properties integrate recreational amenities, spa facilities, and extensive land holdings. British Columbia's mountain and coastal regions attract development targeting experiential leisure demand with extended average length of stay.
- Motels:Drive-up properties with exterior corridors and limited amenities serve highway corridor demand. Ontario's 400-series highway network supports this format for transient commercial travelers.
- Hostels:Shared-room lodging with communal facilities targets budget-conscious and social travelers. Montreal and Quebec City heritage conversions are gaining share fastest among younger demographics seeking experiential formats.
Hotels absorb the bulk of installed capacity; hostels are expanding most quickly.
Service Type:
Service intensity directly correlates with labor cost structures and operational complexity across Canadian hospitality assets.
- Room Service:In-room dining operations require dedicated kitchen infrastructure, insulated transport systems, and extended staffing hours. Toronto luxury properties maintain this amenity for premium positioning despite margin compression.
- Concierge:Guest services coordination demands specialized labor and vendor relationship management. Vancouver's tourism-dependent properties leverage concierge networks to capture activity revenue share.
- Catering:Event food service operations generate ancillary revenue through banquet facilities and off-site execution. Montreal's convention-adjacent assets depend on catering for shoulder-season occupancy.
- Housekeeping:Room preparation and maintenance functions represent the largest labor category across all property types. Ontario properties face wage pressure from Toronto's competitive service labor market.
Housekeeping commands the greatest operational expenditure; catering delivers the highest incremental margin per labor hour.
Client Type:
Demand segmentation reveals divergent rate sensitivity, booking patterns, and amenity requirements across traveler categories.
- Business Travelers:Corporate account demand concentrates in Toronto's financial district and Vancouver's technology corridor. These guests prioritize location efficiency, loyalty program recognition, and expense management integration.
- Tourists:Leisure demand segments into domestic regional travel and international visitation. Quebec's cultural destinations capture extended-stay leisure demand with heritage authenticity positioning.
- Event Organizers:Group bookings for conferences, weddings, and corporate functions drive shoulder-season occupancy. Toronto's mixed-use precincts integrate hospitality with dedicated event infrastructure.
- Families:Multi-room demand seeks connecting accommodations, recreational amenities, and value-oriented pricing. Ontario resort properties target this segment with package pricing and activity programming.
Business travelers generate the highest average daily rate; tourists provide the deepest demand pool with greater seasonality.
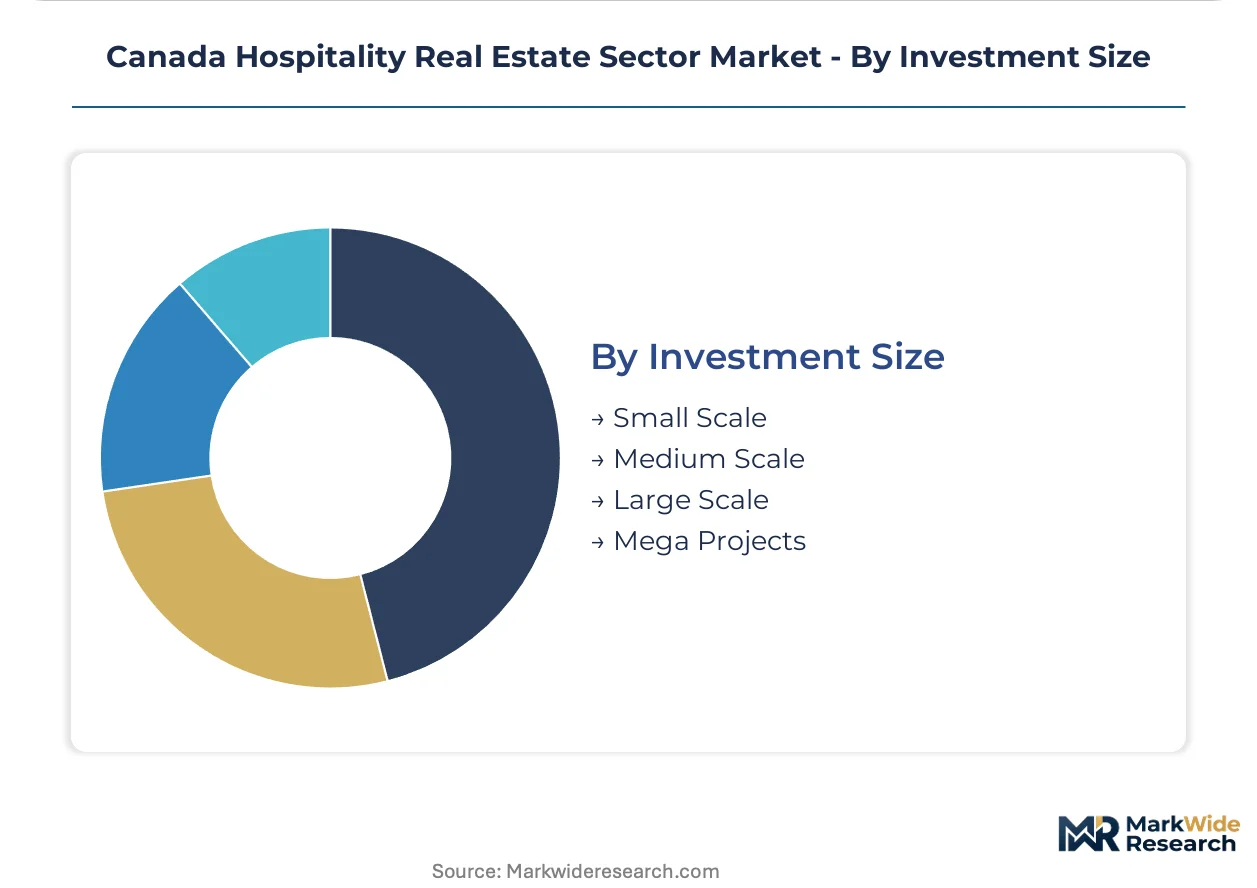
Investment Size:
Scale determines access to financing vehicles, regulatory pathways, and institutional capital partnerships in Canadian hospitality development.
- Large Scale:Assets exceeding 200 rooms require structured financing through CMHC programs or institutional debt funds. Brookfield and similar capital deploys at this scale in Toronto and Vancouver mixed-use developments.
- Mega Projects:Hospitality-integrated precincts spanning multiple towers and uses demand multi-year capital commitments. These projects reshape submarket supply dynamics upon delivery.
- Medium Scale:Properties between 100 and 200 rooms balance operational efficiency with financing accessibility. Regional operators in Ontario secondary markets concentrate at this scale.
- Small Scale:Boutique conversions and limited-service assets under 100 rooms enable entrepreneurial entry. Montreal and Quebec City heritage building adaptations command yield premiums at this scale.
Large Scale projects attract the majority of institutional capital deployment; Small Scale conversions are climbing the fastest as a share of new supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's limestone bedrock and Quebec's St. Lawrence waterway historically anchored hospitality construction materials, while contemporary capital flows concentrate in Toronto's mixed-use precincts and Vancouver's waterfront corridor.
Ontario
Toronto's financial district and Ottawa's government corridor drive business traveler demand for full-service properties. CMHC financing programs reduce debt-service burdens for developers assembling multi-parcel sites in the downtown core. The Greater Toronto Area concentrates institutional investment in hospitality-integrated mixed-use towers exceeding 200 rooms.
British Columbia
Vancouver's technology sector and Victoria's tourism economy generate divergent demand profiles across the province. Health Canada indoor air quality guidelines amplify retrofit costs for pre-2010 assets in coastal markets. Whistler and Vancouver Island resort submarkets attract experiential leisure investment targeting extended-stay formats.
Quebec
Montreal's under-supplied downtown core and Quebec City's heritage tourism base create distinct development opportunities. Provincial tourism incentives reduce effective development costs for boutique conversions in historic districts. The Montreal-Quebec City corridor commands yield premiums for design-forward properties under 100 rooms.
Alberta
Calgary's energy sector and Edmonton's government institutions sustain corporate account demand despite commodity price volatility. Municipal zoning in both cities permits density bonuses for hospitality-integrated developments near transit nodes. The Calgary-Banff corridor captures seasonal leisure overflow from mountain destination resorts.
Atlantic Canada
Halifax's port city positioning and St. John's offshore energy presence anchor provincial demand. Federal infrastructure programs support hospitality-adjacent development in secondary markets. Heritage building stock in Charlottetown and Halifax enables boutique conversion strategies at small-scale investment tiers.
Canada Hospitality Real Estate Sector Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue experiential formats and heritage conversions outside major metros. Asset-heavy institutional capital deploys through REIT structures and limited partnerships, while fee-based operators expand flagged management agreements without direct property ownership. Three archetypes dominate: integrated asset managers, boutique design specialists, and brand-licensed operators. Competitive moves concentrate on mixed-use precinct aggregation and dynamic pricing technology integration.
Among Canada-based hospitality operators, Brookfield Asset Management, Germain Hotels, and Hilton Worldwide (Canada) occupy distinct competitive positions. Brookfield anchors large-scale institutional deployment in Toronto and Vancouver mixed-use developments. Germain exemplifies the design-forward boutique archetype across Quebec and Ontario markets. Hilton Worldwide (Canada) represents the fee-based expansion model through flagged management structures capturing revenue without real estate ownership.
| Leading Market Players |
|---|
| Superior Lodging Corp |
| Germain Hotels |
| Brookfield Asset Management |
| Marriott International (Canada) |
| Hilton Worldwide (Canada) |
| InnVest Hotels |
| Coast Hotels |
| Sunray Group |
| Westmont Hospitality Group |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of HVAC filtration systems anchors both supply security and pricing power for Canadian hospitality developers navigating Health Canada mandates. Operators with backward integration into mechanical contracting command margin protection that outsourced procurement cannot replicate.
Pricing Analysis
Service-bundling separates capital improvement obligations from pure management fees across flagged contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by amenity intensity and loyalty program tier. Pricing pressure stems from CMHC financing rate adjustments compressing developer yields. Business travelers demonstrate lowest price sensitivity; hostel-seeking leisure segments exhibit highest elasticity.
Supply Chain Analysis
Ontario and British Columbia building code amendments are reshaping sourcing toward MERV-13 filtration and enhanced ventilation components. Domestic manufacturing concentrates in Ontario's industrial corridor; specialized mechanical equipment draws from US and German suppliers. Single-source vulnerability runs through HVAC compressor assemblies. Distribution runs through regional mechanical contractors with direct-to-site logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's indoor air quality mandates construct a compliance moat that elevates capital requirements and filters out undercapitalized competitors.
For Market Incumbents: Acquire pre-2010 assets in Toronto and Vancouver corridors requiring HVAC retrofit to capture value-add repositioning premiums. CMHC financing access provides leverage for consolidation plays against rate-sensitive challengers. Vertical integration into mechanical contracting secures supply chain priority during skilled trades shortages. For New Entrants and Emerging Players: Quebec provincial tourism incentives in Montreal open a window for boutique conversion plays under 100 rooms with heritage tax abatements. First Nations partnership structures unlock greenfield sites near Vancouver-Toronto corridors with sovereign land advantages. Target experiential hostel formats in under-supplied downtown cores. For Investors and Strategic Acquirers: Exit pathways concentrate in REIT take-private transactions and institutional platform sales to Brookfield-type capital. Long-term viability favors assets with completed Health Canada compliance retrofits and CMHC-insured debt structures. Watch Bank of Canada policy trajectory as inflection signal for construction timeline feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| HVAC Retrofit Completion | Health Canada compliance unlocks CMHC refinancing and occupancy premiums in Ontario assets. |
| First Nations Joint Venture | Sovereign land frameworks near Vancouver corridor bypass municipal zoning delays. |
| Dynamic Pricing Platform Integration | Revenue management convergence captures rate optimization previously limited to flagged portfolios. |
| Heritage Building Conversion | Quebec City and Montreal tax incentives reduce effective basis for boutique yield premiums. |
| CMHC Financing Structure Optimization | Insured debt vehicles reduce debt-service burdens and extend feasible hold periods. |
Study Parameters
Multi-period observation of CMHC disbursement flows, municipal permitting timelines, and RevPAR trajectories anchored the trend analysis, supplemented by interviews with hotel development executives, mechanical contracting principals, heritage preservation officers, and institutional asset managers. Secondary validation drew from Canada Mortgage and Housing Corporation financing reports, municipal zoning board records, Health Canada regulatory filings, and provincial building code amendments. Bottom-up project pipeline tracking triangulated against top-down capital flow estimates from REIT disclosures and limited partnership fundraising.
Segment-weighting across property type, service intensity, client category, and investment scale calibrated value distribution throughout the projection horizon. CAGRs derived from fitted growth curves against historical absorption patterns. Forecast inputs incorporated immigration-driven demand elasticity, interest rate sensitivity coefficients, and compliance cost inflation for pre-2010 asset stocks.
The model assumes a particular technology adoption path for IoT-enabled building management systems; alternative pathways for legacy mechanical automation would alter the outlook for operational cost compression. Forecasts reflect documented assumptions regarding CMHC program continuity and skilled trades availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market