
 Vietnam Commercial Real Estate Market | 2026-2036
Vietnam Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Commercial Real Estate Market Insights
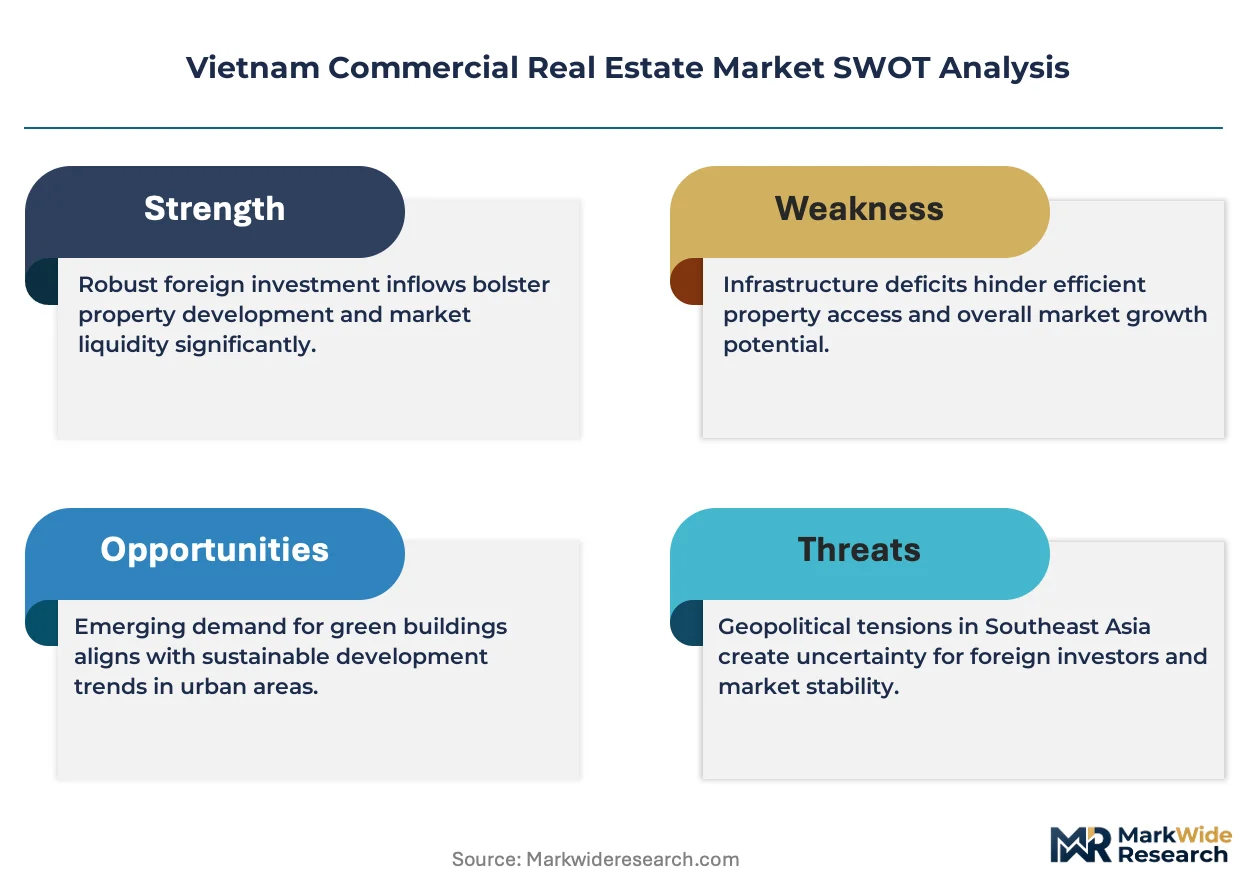
Vietnam's green building certification mandate from the Ministry of Construction is decoupling new supply from conventional construction practices. Vingroup JSC leverages its integrated development model to control project timelines from land acquisition to tenant handover. CapitaLand Vietnam Holdings anchors premium office portfolios in Ho Chi Minh City and Hanoi through sustained foreign capital deployment. Keppel Land Vietnam differentiates via mixed-use precincts that combine residential, retail, and Grade-A office functions.
Vietnam commercial real estate encompasses income-producing properties including office towers, retail centers, industrial logistics facilities, and mixed-use developments, typically engineered with reinforced concrete cores, curtain wall glazing systems, and floor loading capacities of 300-500 kg per square meter for standard office use. The primary commercial purpose centers on generating rental yield and capital appreciation for institutional and private investors while serving corporate operational needs. Industrial property leads transaction velocity as manufacturing relocations from China accelerate warehouse and factory absorption. Office space in the small-to-medium building size category captures the fastest-growing tenant segment as startups and mid-market corporates seek flexible lease terms. Retail stabilizes as a mature margin pool where opportunistic investment stage strategies target distressed mall assets for repositioning.
Vietnam's Ministry of Construction enforces green building standards that elevate material specifications and energy performance thresholds for new commercial permits. The country's national land regulator implements Land Law revisions that constrain foreign ownership structures and extend site clearance timelines for large-scale projects. BIS-equivalent technical standards for structural safety and fire suppression shape product compliance across all property types. Stakeholders must monitor how provincial People's Committees interpret central zoning directives when selecting between Ho Chi Minh City, Hanoi, and emerging secondary city entry points.
Market Dynamics
Vietnam's Ministry of Construction green building certification mandate is decoupling new commercial supply from conventional construction practices. Developers now face elevated compliance costs for materials and energy performance thresholds that reshape project feasibility calculations.
Growth Catalysts
- Manufacturing Relocation Wave:Industrial property near Hai Phong and Bac Ninh absorbs tenant demand as supply chains exit China. Warehouse and factory absorption accelerates transaction velocity in northern industrial zones.
- Revised Land Law Framework:Vietnam's national land regulator implements ownership structure reforms that clarify foreign investment pathways. Extended site clearance timelines create competitive moats for developers with capital patience.
- Small-to-Medium Office Demand:Startups and mid-market corporates seek flexible lease terms in Ho Chi Minh City. This tenant segment captures the fastest-growing building size category.
Market Restraints
- Green Material Cost Volatility:Elevated specifications for curtain wall glazing and reinforced concrete cores inflate construction budgets. BIS-equivalent technical standards for structural safety compound input cost pressure.
- Site Clearance Concentration Risk:Provincial People's Committees interpret central zoning directives unevenly. Large-scale projects face extended timeline risk in secondary city entry points.
- Foreign Ownership Structure Friction:The Land Law constrains direct freehold acquisition by offshore investors. Complex holding structures add legal overhead to capital deployment.
Strategic Opportunities
- Distressed Retail Repositioning:Opportunistic investment strategies target mature mall assets for conversion. Secondary cities offer lower entry valuations for value-add retail plays.
- Mixed-Use Precinct Development:Technology convergence between residential, retail, and Grade-A office functions creates integrated demand. Developers control project timelines from land acquisition to tenant handover.
- Flexible Lease Innovation:Co-working operators and serviced office providers pioneer subscription-based occupancy models. This channel innovation captures startup and SME demand in Hanoi.
Industry Challenges
- Green Certification Timeline Compression:The Ministry of Construction mandates tighter energy performance thresholds for new permits. Developers face compressed design-review cycles to maintain project schedules.
- Integrated Project Delivery Complexity:Mixed-use developments require coordination across residential sales, retail leasing, and office tenant fit-out. Legacy siloed development teams struggle with synchronized handover protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Commercial Real Estate Market |
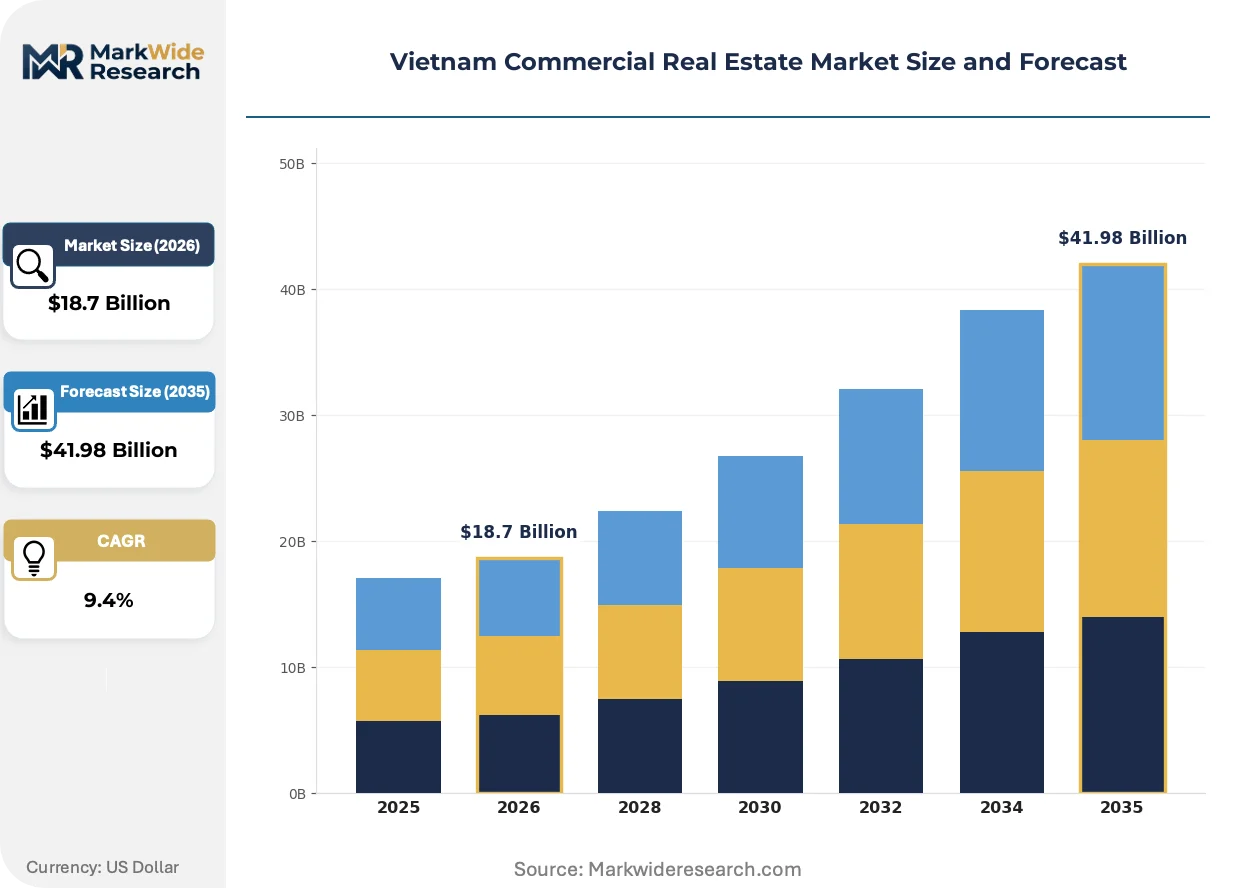
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Stage: Development, Stabilized, Value-Add, Opportunistic Building Size: Small, Medium, Large, Mega End User: Corporates, Startups, Investors, Others |
| Companies Covered | Vingroup JSC, CapitaLand Vietnam Holdings, Keppel Land Vietnam, Sun Group, Novaland Group, Nam Long Investment Corporation, Dat Xanh Group, Becamex IDC Corporation, Frasers Property Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Commercial Real Estate Market Trends and Innovations
Smart building systems and sustainable material specifications are actively reshaping how commercial assets attract capital and retain tenants. Three distinct shifts are restructuring competitive positioning.
Building-integrated photovoltaic glazing is absorbing rooftop and facade surface area for on-site energy generation. Grade-A office developers in Ho Chi Minh City deploy this technology to meet Ministry of Construction energy thresholds. The structural consequence is compressing payback periods for green premium investments as electricity cost savings accrue.
Vietnam's Ministry of Construction enforces progressively tighter green building standards that elevate material specifications for new commercial permits. The industrial consequence is bifurcating developer capabilities between compliance-ready firms and those facing stranded conventional inventory. Premium office portfolios in Hanoi and Ho Chi Minh City respond fastest, anchoring foreign capital deployment in certified assets.
Corporate tenants now bundle facility management, flexible space access, and sustainability reporting into unified service agreements. Traditional gross lease structures face displacement from outcome-based contracts that transfer operational risk to landlords. This pattern concentrates in technology and professional services firms leasing space in District 1 and District 7.
Vietnam Commercial Real Estate Market Segmentation
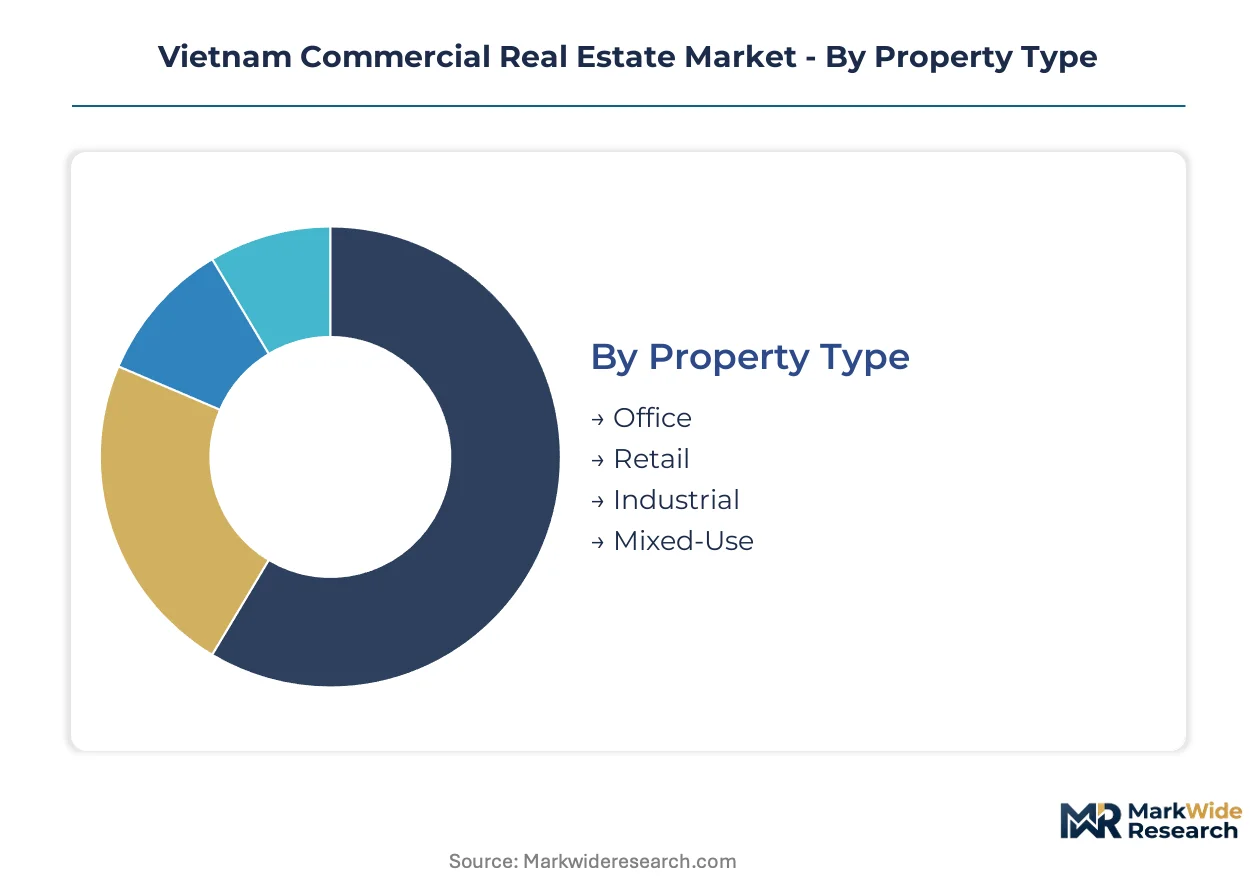
Vietnam's commercial real estate market fragments across four distinct dimensions that determine capital deployment strategy and risk-return profiles. Property type and investment stage classifications drive institutional allocation decisions, while building size and end-user segmentation shape development feasibility and lease structuring.
Property Type:
Capital intensity peaks in mixed-use developments requiring synchronized construction across multiple asset classes, followed by Grade-A office towers with premium curtain wall and MEP specifications.
- Office:Grade-A towers in Ho Chi Minh City's District 1 and Hanoi's Cau Giay district command premium rents through floor loading capacities of 300-500 kg per square meter and smart building integration. Demand concentrates among technology firms from South Korea and Japan expanding regional headquarters operations, constrained by Ministry of Construction green certification timelines that compress design-review cycles.
- Industrial:Warehouse and factory assets near Hai Phong and Bac Ninh absorb manufacturing relocations from China with accelerated transaction velocity. Northern industrial zones capture the steepest tenant interest as supply chain diversification accelerates, though site clearance concentration risk from uneven provincial People's Committee interpretation of central zoning directives extends development timelines.
- Retail:Shopping centers and street-front commercial units in mature mall formats face repositioning pressure from e-commerce displacement.
- Mixed-Use:Integrated precincts combining residential, retail, and office functions require complex project delivery coordination across sales and leasing channels.
Most installed capacity flows through Industrial assets. Expansion is steepest in Mixed-Use developments.
Investment Stage:
Risk-return profiles stratify sharply across the development lifecycle, with development-stage assets demanding the longest capital lock-up periods and opportunistic plays targeting distressed repositioning in secondary cities.
- Development:Greenfield construction and major redevelopment projects face elevated compliance costs from revised Land Law frameworks and tighter Ministry of Construction material specifications.
- Stabilized:Income-producing assets with established tenant bases and predictable cash flows anchor core institutional portfolios in Ho Chi Minh City and Hanoi.
- Value-Add:Assets requiring capital improvements or lease restructuring offer intermediate risk profiles, particularly in retail conversion plays targeting secondary city entry points with lower initial valuations.
- Opportunistic:Distressed or complex assets with significant repositioning requirements concentrate in mature mall assets seeking alternative use conversion, where extended site clearance timelines create competitive moats for developers with capital patience.
Institutional capital concentrates in Stabilized assets. Value-Add strategies are climbing the fastest as retail distress creates entry opportunities.
Building Size:
Scale economics favor large-format developments in prime locations, while small-to-medium buildings capture fragmented demand from price-sensitive tenant segments.
- Small:Buildings under 5,000 square meters serve boutique professional services and localized retail, concentrated in Hanoi's emerging districts where flexible lease innovation from co-working operators gains traction.
- Medium:Mid-scale assets of 5,000-20,000 square meters capture the fastest-growing tenant segment as startups and mid-market corporates seek flexible lease terms in Ho Chi Minh City, with District 7 emerging as a preferred cluster for technology and professional services firms.
- Large:20,000-50,000 square meter developments anchor Grade-A office portfolios through sustained foreign capital deployment, requiring BIS-equivalent technical standards for structural safety and fire suppression compliance.
- Mega:Developments exceeding 50,000 square meters demand integrated project delivery capabilities across residential sales, retail leasing, and office tenant fit-out synchronization.
Development pipelines concentrate in Large-format assets. Medium-size buildings are expanding most quickly.
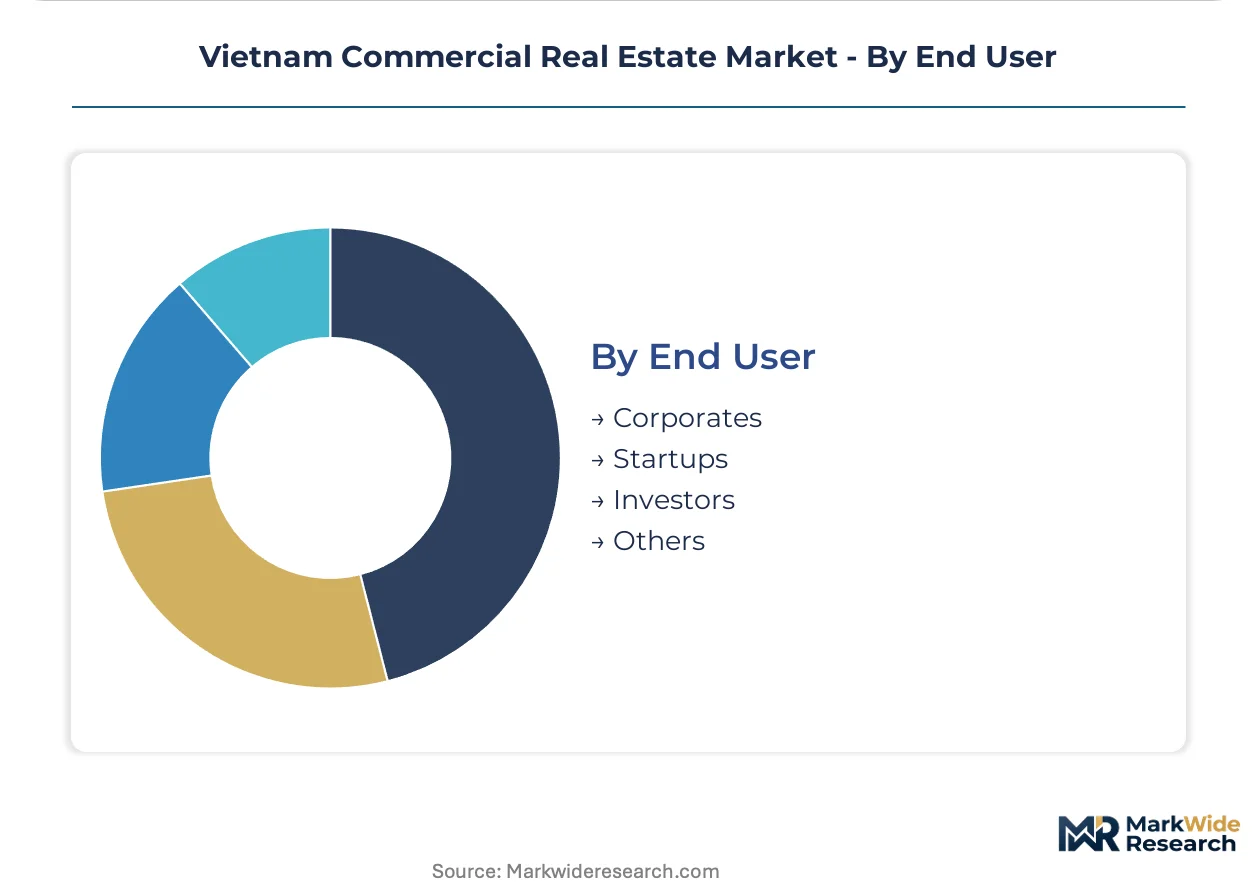
End User:
Tenant sophistication and lease structuring requirements vary substantially across user categories, with corporates demanding long-term stability and investors prioritizing yield optimization.
- Corporates:Multinational and domestic enterprises lease space for operational headquarters, regional offices, and back-office functions, bundling facility management and sustainability reporting into unified service agreements that displace traditional gross lease structures in District 1 and District 7.
- Startups:Early-stage companies prioritize flexible terms and scalable footprints, driving subscription-based occupancy models through serviced office providers in Hanoi and Ho Chi Minh City.
- Investors:Institutional and private capital deploys across the risk spectrum for rental yield and capital appreciation, constrained by Land Law restrictions on direct freehold acquisition that necessitate complex holding structures.
- Others:Government entities, educational institutions, and non-profit organizations occupy specialized commercial space with distinct procurement and lease term requirements.
Lease volume flows predominantly through Corporates. Startup demand is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering and construction talent clusters in Vietnam's northern industrial corridor anchor the country's commercial real estate development pipeline. Workforce concentration around Hai Phong and Bac Ninh accelerates project delivery timelines for manufacturing-anchored assets. This regional distribution shapes where institutional capital deploys across the forecast period.
Ho Chi Minh City
Technology firms from South Korea and Japan drive Grade-A office absorption in District 1 and District 7. The Ministry of Construction enforces green building certification mandates that compress design-review cycles for new permits. Startup and mid-market corporate demand concentrates in medium-format buildings where flexible lease terms dominate tenant negotiations.
Hanoi
Co-working operators and serviced office providers pioneer subscription-based occupancy models in Cau Giay and emerging districts. Provincial People's Committees interpret central zoning directives with uneven consistency, extending site clearance timelines for large-scale projects. Small-format buildings under 5,000 square meters capture boutique professional services demand.
Hai Phong
Manufacturing relocations from China accelerate warehouse and factory absorption in northern industrial zones. The revised Land Law framework clarifies foreign investment pathways while constraining direct freehold acquisition. Industrial property near deep-water port infrastructure commands premium logistics positioning for export-oriented tenants.
Bac Ninh
Supply chain diversification from China concentrates electronics and automotive component manufacturing demand. BIS-equivalent technical standards for structural safety and fire suppression shape product compliance across all industrial property types. Extended site clearance timelines create competitive moats for developers with capital patience and established government relationships.
Secondary Cities
Distressed retail repositioning opportunities emerge in lower-entry-valuation markets outside the primary metros. The Ministry of Construction's green material specifications elevate construction budgets uniformly across provincial jurisdictions. Value-add strategies target mature mall assets for alternative use conversion where opportunistic capital seeks higher risk-adjusted returns.
Vietnam Commercial Real Estate Market Competitive Landscape
Capital-heavy developers with integrated land-to-handover capabilities compete with asset-light operators focused on lease management and tenant services. The market structure concentrates around conglomerate-affiliated property arms with patient capital backing and specialized foreign-invested platforms deploying sustained institutional funding. Three archetypes dominate: integrated development conglomerates controlling entire project timelines, foreign-invested premium office specialists, and industrial zone operators leveraging government relationships for site clearance. Competitive intensity manifests through mixed-use precinct expansion and green certification speed-to-market rather than price-based rivalry.
Among integrated Vietnamese conglomerates, Vingroup JSC exemplifies the full-control development archetype spanning residential sales through commercial leasing. CapitaLand Vietnam Holdings and Keppel Land Vietnam represent foreign-invested platforms anchoring premium portfolios through sustained capital deployment. These three entities occupy distinct positioning vectors—domestic vertical integration versus cross-border institutional scale—while converging on mixed-use and certified-green asset strategies.
| Leading Market Players |
|---|
| Vingroup JSC |
| CapitaLand Vietnam Holdings |
| Keppel Land Vietnam |
| Sun Group |
| Novaland Group |
| Nam Long Investment Corporation |
| Dat Xanh Group |
| Becamex IDC Corporation |
| Frasers Property Vietnam |
| Others |
Pricing and Supply Chain Analysis
Conglomerate-affiliated property arms with patient capital backing anchor supply discipline across Vietnam's commercial real estate pipeline, translating land-bank depth into pricing power that resists margin compression from green material cost volatility. Their integrated control from site acquisition to tenant handover insulates lease rate negotiations from the input cost spikes that strain fragmented developers.
Pricing Analysis
The bundled-vs-unbundled service split defines how landlords capture value across Vietnam's commercial property tiers. Premium Grade-A office towers in Ho Chi Minh City command gross lease structures that embed facility management and sustainability reporting, while secondary city retail assets trade on net lease terms that shift operational risk to tenants. Price differentiation hinges on Ministry of Construction green certification status and floor loading specifications that signal structural quality. Cost compression in conventional construction tiers is intensifying because BIS-equivalent technical standards for reinforced concrete cores and curtain wall glazing inflate baseline budgets. Startup and SME tenants in District 7 exhibit highest price sensitivity, whereas multinational technology firms from South Korea and Japan absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of low-emissivity glass and high-performance HVAC systems that dominate equipment specifications for Ministry of Construction compliance. Vietnam's commercial real estate development draws from concentrated supply bases in China, South Korea, and Japan for curtain wall glazing, smart building automation, and fire suppression components. Raw material dependencies center on imported aluminum framing, photovoltaic glazing substrates, and reinforced steel bar grades that meet seismic load requirements. Tariff exposure on building-integrated photovoltaic systems creates procurement timeline risk for developers targeting compressed green certification cycles. Distribution runs through regional distributor networks anchored in Ho Chi Minh City and Hanoi, with project-scale bulk purchasing concentrated through conglomerate procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam commercial real estate represents a late-cycle quality story where tenant demand shifts decisively toward Ministry of Construction-certified assets with embedded energy performance guarantees. This specification premium rewards developers with accelerated approval timelines and superior rent retention.
For Market Incumbents: Lock in land-bank positions in Hai Phong and Bac Ninh industrial corridors before provincial People's Committees tighten zoning interpretations under revised Land Law frameworks. Accelerate backward integration into green material sourcing to offset cost volatility from BIS-equivalent technical standards, while consolidating project delivery capabilities across mixed-use precincts to outpace fragmented competitors on handover synchronization. For New Entrants and Emerging Players: Enter via distressed retail repositioning in secondary cities where opportunistic capital faces lower entry valuations and extended site clearance timelines create competitive moats for patient investors. Target medium-format office buildings in Hanoi's emerging districts where co-working operators have validated subscription-based demand but institutional supply remains thin. Pursue joint venture structures with provincial developers to navigate uneven central zoning directive implementation. For Investors and Strategic Acquirers: Valuations sit cheapest among secondary city retail assets requiring capital improvements and lease restructuring, where yield spreads compensate for execution complexity over a five-to-ten year hold period. Prioritize acquisition targets with established government relationships that compress site clearance timelines. Monitor Ministry of Construction permit issuance velocity as the inflection indicator for green supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Acceleration | Ministry of Construction timelines compress competitive positioning for compliant developers in Ho Chi Minh City. |
| Industrial Zone Expansion | Hai Phong port-adjacent land captures manufacturing relocation demand from China with logistics cost advantages. |
| Mixed-Use Precinct Integration | Synchronized residential sales and office leasing reduce capital lock-up periods for patient capital backers. |
| Flexible Lease Innovation | Subscription-based occupancy models capture startup demand in District 7 and Cau Giay. |
| Distressed Retail Conversion | Secondary city mall repositioning offers value-add entry points below replacement cost thresholds. |
Research Methodology
Direct dialogue with property development executives, provincial planning officers, institutional investment managers, and construction procurement leads grounded qualitative assessment of site clearance timelines and green certification bottlenecks. Secondary validation drew from Ministry of Construction permit databases, provincial People's Committee zoning filings, customs records on building material imports, and conglomerate annual disclosures. Bottom-up project pipeline tracking and top-down capital flow analysis were triangulated against rent trajectory indicators in Ho Chi Minh City and Hanoi.
Segment-level projections across property type, investment stage, building size, and end-user category were generated through the analysis window using demand absorption models calibrated to manufacturing relocation velocity and foreign direct investment permit trends. CAGRs were derived from fitted growth curves incorporating Land Law revision implementation phases and green building standard adoption rates. Forecast inputs included electronics and automotive component manufacturing expansion plans in northern industrial zones, plus technology firm regional headquarters leasing commitments.
Inputs from Ministry of Construction disclosure filings and provincial statistical yearbooks were available through the study window; gaps in secondary city transaction-level data introduce uncertainty bands around retail repositioning return assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market