
 Italy Luxury Residential Real Estate Market | 2026-2036
Italy Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Luxury Residential Real Estate Market Outlook
Italy's Superbonus 110% tax credit for energy-efficient building upgrades is expanding renovation pipelines for aging villas and historical estates. Knight Frank Italy leverages its cross-border HNWI network to source off-market inventory in Tuscany and Umbria. Sotheby's International Realty anchors its Italian presence through exclusive lakefront and vineyard estate mandates. Engel & Völkers Italia competes via boutique offices in Milan, Rome, and Florence that control premium neighborhood coverage.
Italy luxury residential real estate comprises freehold and leasehold dwellings valued above institutional price thresholds, typically featuring bespoke architectural elements, certified heritage status, or exclusive locational attributes such as UNESCO-protected views or private waterfront access. These properties serve wealth preservation, lifestyle migration, and generational asset transfer objectives for transnational buyers. Villas and historical estates command the deepest buyer queues and longest marketing periods, while penthouse apartments in Milan generate the fastest transaction velocity. HNWIs and family offices represent the dominant buyer profile, with purchase purpose skewing toward vacation homes and rental investment rather than primary residence use.
Italy's Agenzia delle Entrate administers property valuation benchmarks that shape mortgage lending and transfer tax calculations, while the Ministry of Culture imposes heritage constraints on alterations to listed buildings. The Superbonus regime, managed through the Revenue Agency, directly subsidizes green retrofit costs and elevates asset values for compliant properties. Stakeholders must monitor how Rome's evolving building code interpretations and EU energy performance mandates reshape renovation economics and buyer underwriting criteria.
Market Dynamics
Italy's Superbonus 110% tax credit regime is compressing renovation timelines for aging villas while redirecting institutional capital toward energy-compliant trophy assets. This fiscal mechanism now dominates transaction underwriting across Tuscany, Lombardy, and Lazio.
Growth Catalysts
- Superbonus 110%:Italy's Agenzia delle Entrate administers this tax credit covering 110% of energy retrofit costs, accelerating capital deployment into historical estates requiring thermal upgrades.
- Cross-border HNWI networks:Northern European and Middle Eastern family offices are expanding acquisition pipelines in Lake Como and Umbria, drawn by UNESCO-protected locational attributes and generational wealth preservation utility.
- Geothermal and photovoltaic integration:Renewable energy retrofits are elevating asset values for rural villas while satisfying EU energy performance mandates ahead of enforcement deadlines.
Market Restraints
- Heritage constraint complexity:Italy's Ministry of Culture imposes strict alteration limits on listed buildings, extending permitting timelines and compressing developer margins in Rome's historic center.
- Construction input volatility:Specialized restoration materials including Carrara marble and traditional lime plasters face supply concentration among artisan producers in Tuscany and Veneto.
- Transfer tax calculation rigidity:Agenzia delle Entrate valuation benchmarks often exceed market clearing prices, inflating transaction costs for cross-border buyers.
Strategic Opportunities
- Calabria and Basilicata coastlines:These underpenetrated southern regions offer comparable Mediterranean attributes at substantial discounts to Tuscan equivalents, attracting lifestyle migration capital.
- Smart home convergence:Integration of building automation with heritage-sensitive retrofit design is creating premium pricing tiers for tech-enabled historical properties.
- Short-term rental regulatory arbitrage:Municipal zoning variations across Milan, Florence, and Bologna create channel opportunities for institutional operators targeting transient luxury demand.
Industry Challenges
- Restoration artisan scarcity:Specialized stonemasonry and fresco conservation skills are concentrating among aging practitioners in Umbria and Marche, constraining renovation throughput.
- Green certification timeline compression:EU energy performance mandates require APE (Attestato di Prestazione Energetica) upgrades within accelerating windows, forcing simultaneous capital deployment across multiple properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Luxury Residential Real Estate Market |
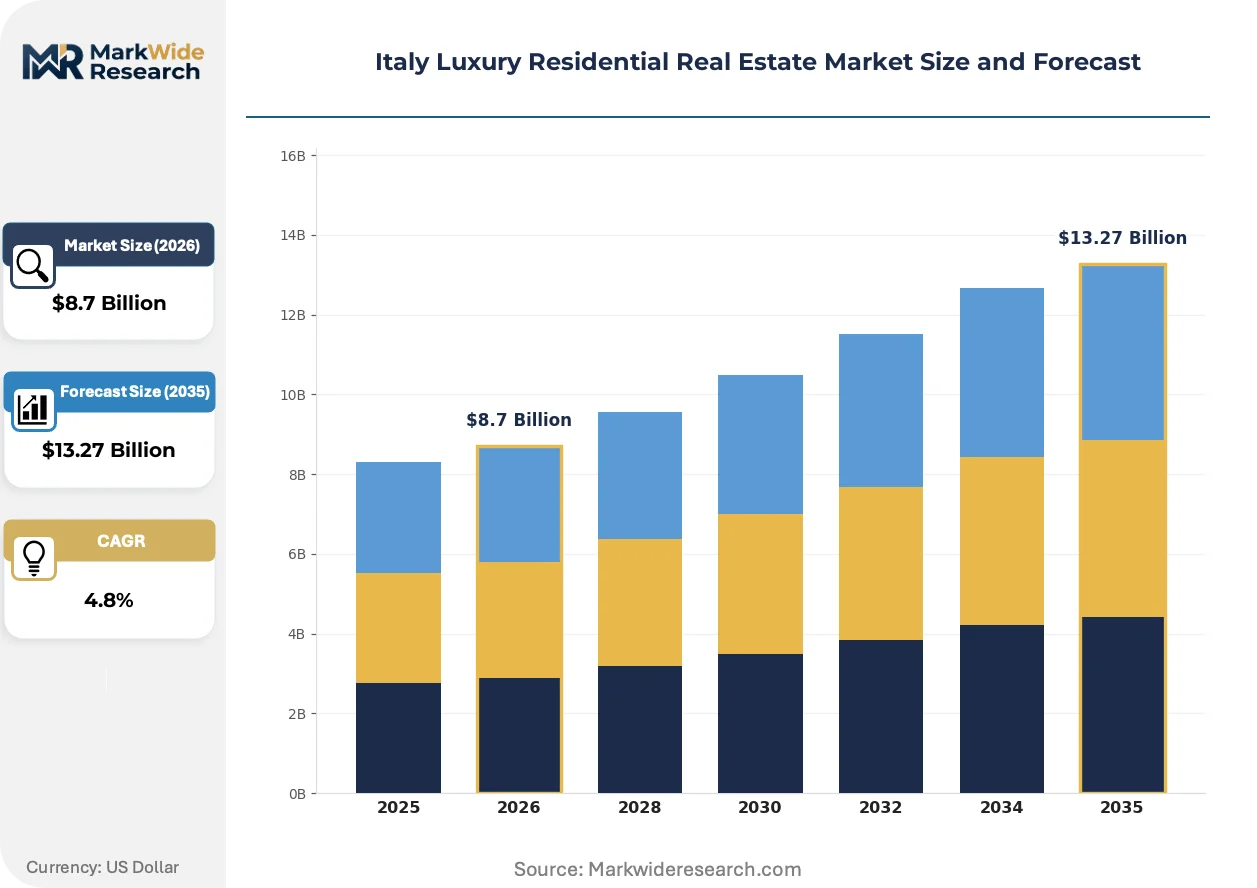
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Penthouse Apartments, Historical Estates, Beachfront Homes, Mountain Chalets Buyer Profile: HNWIs, Family Offices, International Investors, Private Trusts, Luxury Brokers Purchase Purpose: Primary Residence, Vacation Home, Rental Investment, Retirement Property, Corporate Housing Sales Channel: Real Estate Agencies, Online Portals, Auctions, Private Deals, Boutique Firms |
| Companies Covered | Carratelli Real Estate, Knight Frank Italy, Sotheby's International Realty, Immobilinvest Real Estate, Savills Italy, Christie's International Real Estate, Engel & Völkers Italia, Chianti Estates SRL, Lionard Luxury Real Estate, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Luxury Residential Real Estate Market Strategic Shifts
Digital transaction infrastructure and regulatory compliance technology are compressing due diligence cycles while elevating transparency requirements for cross-border capital deployment into Italian trophy assets.
Geothermal heat pump systems are integrating with underfloor heating in Renaissance-era villas, preserving architectural integrity while satisfying Superbonus eligibility criteria. Milan-based developers are adopting these configurations fastest, compressing marketing periods for compliant inventory. The technology is integrating heritage conservation with energy performance, creating a new asset class of certified sustainable historical properties.
Italy's Agenzia delle Entrate has tightened anti-money laundering verification protocols for non-EU buyers, extending closing timelines but reducing title risk for institutional sellers. This regulatory shift elevates compliance costs for family office purchasers while compressing speculative flipping activity. Rome and Florence transaction volumes are responding with elongated escrow structures and enhanced beneficial ownership disclosure.
Direct-to-seller digital platforms are disintermediating traditional brokerage channels for vineyard estates and lakefront villas, compressing commission structures and accelerating price discovery. HNWIs from Germany and Switzerland are adopting these channels fastest, bypassing exclusive mandates held by established networks. This behavioral shift concentrates in secondary markets including Piedmont's Langhe region and Lake Garda's western shore.
Italy Luxury Residential Real Estate Market Segmentation
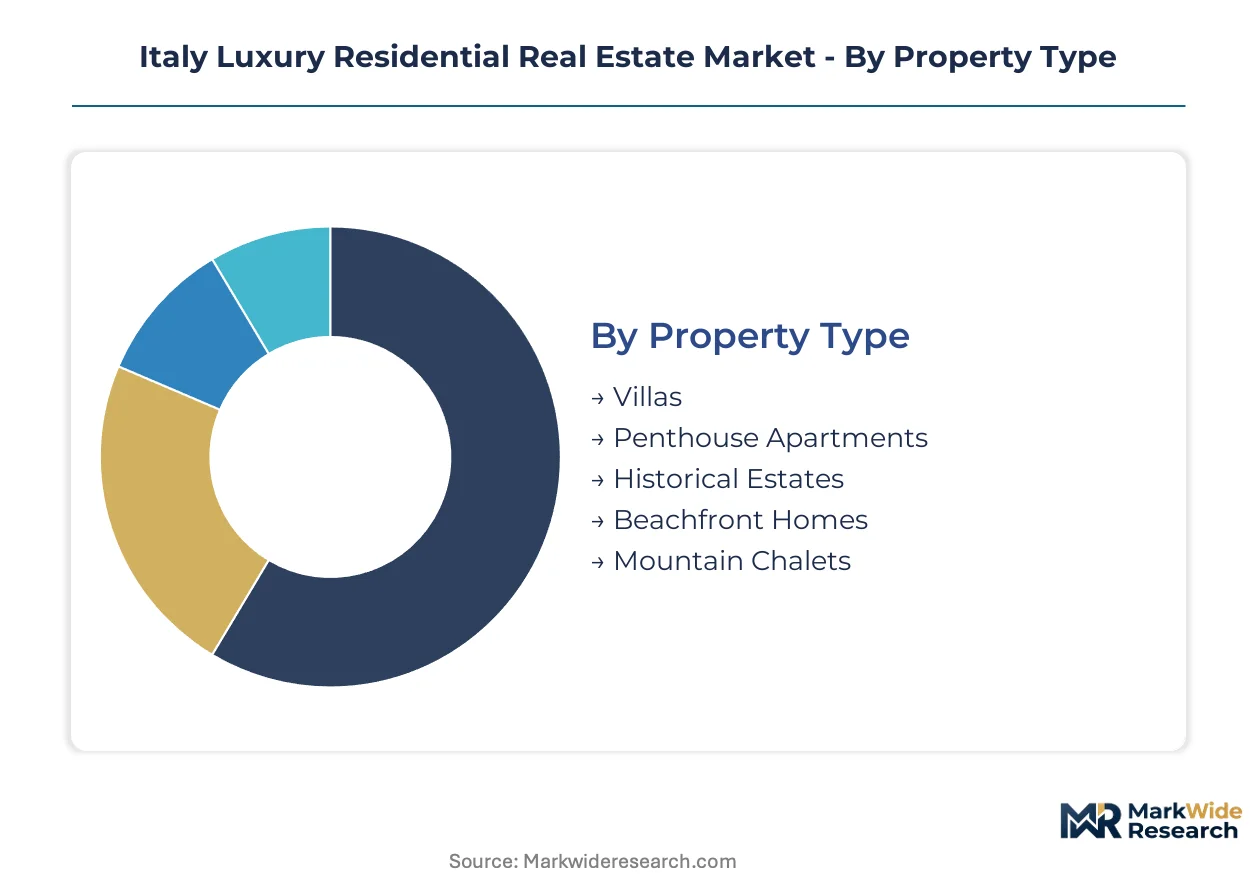
Segmentation in Italy's luxury residential market reveals how buyer motivation, property character, and transaction mechanics intersect to create distinct commercial ecosystems. Each dimension carries regulatory, pricing, and liquidity implications that reshape capital deployment strategies across Tuscany, Lombardy, and Lazio.
Property Type:
Buyer preference for heritage authenticity versus contemporary convenience drives allocation across architectural categories.
- Villas:Standalone rural residences featuring original stonework, terracotta roofing, and agricultural outbuildings. Demand concentrates in Chianti and Val d'Orcia where Northern European family offices seek generational wealth preservation vehicles compliant with Superbonus retrofit pathways.
- Penthouse Apartments:Top-floor urban units with private terraces and concierge services in Milan's Porta Nuova and Rome's Trieste district. These assets generate the fastest transaction velocity among international investors prioritizing liquidity over heritage exposure.
- Historical Estates:Listed palazzos and noble residences subject to Ministry of Culture oversight.
- Beachfront Homes:Coastal villas in Sardinia's Costa Smeralda and Amalfi Coast municipalities.
- Mountain Chalets:Alpine residences in Cortina d'Ampezzo and Aosta Valley ski domains.
Villas lead on scale; penthouse apartments lead on momentum.
Buyer Profile:
Capital source and governance structure determine underwriting complexity and closing timeline elasticity.
- HNWIs:Individual purchasers with liquid assets exceeding institutional thresholds, typically executing cash transactions without mortgage dependency. German and Swiss buyers dominate Lake Como and Lake Garda acquisition queues, drawn by UNESCO-protected locational attributes and Schengen mobility advantages.
- Family Offices:Multi-generational wealth vehicles deploying capital through Luxembourg or Swiss holding structures. These entities concentrate in Tuscany's vineyard estates and Umbria's agriturismo conversions, prioritizing rental yield optimization through short-term hospitality platforms.
- International Investors:Cross-border capital pools including Middle Eastern sovereign-linked entities.
- Private Trusts:Fiduciary arrangements managing generational asset transfer for Italian diaspora families.
- Luxury Brokers:Principal traders acquiring inventory for portfolio aggregation and resale.
Family offices lead on scale; HNWIs lead on momentum.
Purchase Purpose:
Intended use duration and income generation profile shape due diligence intensity and regulatory exposure.
- Primary Residence:Full-time occupancy declarations triggering Italian tax residency and worldwide income reporting obligations. Milan's Porta Nuova district attracts corporate executives from pharmaceutical and luxury goods sectors requiring proximity to headquarters infrastructure.
- Vacation Home:Seasonal occupancy patterns concentrated in coastal and alpine municipalities. Lake Como and Amalfi Coast properties in this category face intensified municipal short-term rental zoning restrictions that compress yield assumptions for prospective buyers.
- Rental Investment:Income-focused acquisition targeting transient hospitality demand.
- Retirement Property:Long-horizon purchases by Northern European buyers leveraging Italy's elective residency visa regime.
- Corporate Housing:Employer-subsidized accommodation for rotating executive assignments.
Vacation homes lead on scale; rental investment leads on momentum.
Sales Channel:
Information asymmetry and commission structure fragmentation create channel-specific buyer-seller matching efficiencies.
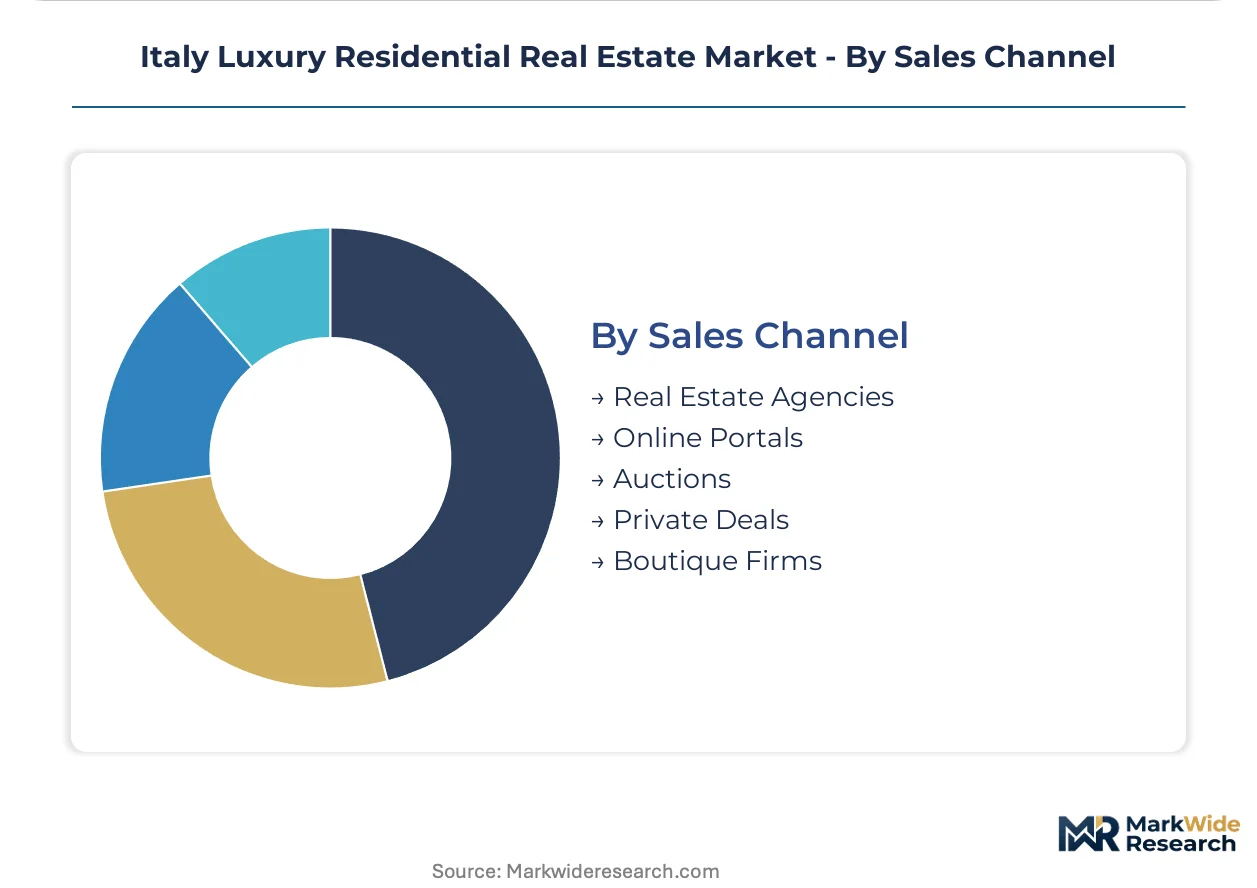
- Real Estate Agencies:Full-service brokerages holding exclusive mandates on trophy inventory. Knight Frank Italy and Sotheby's International Realty dominate this channel for estates exceeding institutional price thresholds, leveraging cross-border HNWI networks to source off-market opportunities in Umbria and Tuscany.
- Online Portals:Digital listing platforms disintermediating traditional brokerage for standardized inventory. German and Swiss buyers increasingly adopt these channels for Piedmont's Langhe region and Lake Garda western shore transactions, compressing price discovery cycles.
- Auctions:Judicial and voluntary sale mechanisms for distressed or disputed assets.
- Private Deals:Direct bilateral negotiations bypassing formal marketing.
- Boutique Firms:Specialized agencies controlling hyperlocal neighborhood coverage.
Real estate agencies lead on scale; online portals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's luxury residential market traces its modern form to post-war aristocratic estate liquidations that established Tuscany and Lake Como as trophy asset destinations. Regional variation now reflects divergent buyer demographics, regulatory exposure, and renovation incentive uptake across the peninsula.
Lombardy
Milan's Porta Nuova district concentrates institutional capital seeking liquidity and concierge-serviced penthouses. The Agenzia delle Entrate administers Superbonus 110% credits that accelerate thermal retrofit deployment across aging urban stock. Lake Como's western shore attracts German and Swiss HNWIs pursuing UNESCO-protected waterfront villas with Schengen mobility advantages.
Tuscany
Chianti and Val d'Orcia host Northern European family offices acquiring vineyard estates for generational wealth preservation. The Ministry of Culture imposes heritage constraints on listed palazzo alterations, extending permitting timelines. Florence's periphery sees boutique developers aggregating agricultural outbuildings into compliant hospitality inventory.
Lazio
Rome's historic center draws Middle Eastern sovereign-linked capital toward trophy palazzos with certified provenance. The Revenue Agency's valuation benchmarks often exceed market clearing prices, inflating transfer tax exposure for cross-border purchasers. Trastevere and Aventine submarkets concentrate penthouse inventory targeting pharmaceutical and luxury goods executives.
Veneto
Lake Garda's western shore experiences digital platform disintermediation as German buyers bypass traditional brokerage channels. Specialized restoration artisans in Verona and Vicenza provinces face capacity constraints from Superbonus-driven demand. Cortina d'Ampezzo's alpine chalet market serves seasonal occupancy patterns with intensified short-term rental zoning scrutiny.
Piedmont
Langhe region vineyard estates trade at substantial discounts to Tuscan equivalents, attracting lifestyle migration capital. The Agenzia delle Entrate's anti-money laundering protocols extend closing timelines for non-EU beneficial ownership structures. Alba and Asti municipalities concentrate agriturismo conversion activity targeting transient hospitality yield optimization.
Italy Luxury Residential Real Estate Market Competitive Environment
Capital-heavy agencies holding exclusive trophy mandates compete with asset-light digital platforms disintermediating secondary market transactions. Market structure concentrates around three strategic archetypes: heritage-network brokerages leveraging cross-border HNWI relationships, boutique operators controlling hyperlocal neighborhood coverage, and direct-to-seller platforms compressing commission structures. Dominant competitive moves include exclusive inventory aggregation in underpenetrated southern regions and compliance technology deployment to accelerate non-EU buyer verification cycles.
Within the heritage-network tier, Knight Frank Italy and Sotheby's International Realty exemplify archetypes built on aristocratic estate liquidation lineage and cross-border family office access. Engel & Völkers Italia occupies a position representing boutique footprint density across Milan, Rome, and Florence premium submarkets. These entities anchor competitive positioning through off-market sourcing capabilities rather than price-based rivalry.
| Leading Market Players |
|---|
| Carratelli Real Estate |
| Knight Frank Italy |
| Sotheby's International Realty |
| Immobilinvest Real Estate |
| Savills Italy |
| Christie's International Real Estate |
| Engel & Völkers Italia |
| Chianti Estates SRL |
| Lionard Luxury Real Estate |
| Others |
Value Chain & Pricing Dynamics
Geothermal heat pump integration with Renaissance-era underfloor heating systems is simultaneously elevating renovation cost baselines and concentrating specialized contractor capacity in Milan and Florence. This technology shift tightens pricing power among heritage-certified installers while compressing margins for developers unable to secure Superbonus-compliant workmanship.
Pricing Analysis
Three-tier pricing structure across trophy heritage estates, energy-retrofitted villas, and standard rural residences dominates transaction economics. Price differentiation rests on Ministry of Culture certification status and Superbonus eligibility tier, with Agenzia delle Entrate valuation benchmarks often exceeding market clearing prices. Cost compression in standard rural inventory is intensifying because German and Swiss buyers bypass traditional brokerage channels. Family offices exhibit lowest price sensitivity, while individual HNWIs purchasing vacation homes demonstrate highest elasticity to transfer tax exposure.
Supply Chain Analysis
Freight costs for Carrara marble and traditional lime plasters from Tuscany and Veneto artisan producers are inflating restoration budgets across Central Italy. Supply concentration centers on Italy for heritage materials, with Germany and Switzerland providing geothermal and photovoltaic equipment. Raw material dependencies include terracotta roofing tiles, specialized stonework, and certified conservation-grade timber. Single-source vulnerability concentrates among aging fresco conservation practitioners in Umbria and Marche. Distribution runs through exclusive brokerage mandates for trophy assets, with direct-to-seller platforms gaining share in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's luxury residential market functions as a geographic-arbitrage mechanism, with Calabria and Basilicata coastlines offering Mediterranean attributes at substantial discounts to Tuscan equivalents while Superbonus incentives compress renovation cost differentials.
For Market Incumbents: Cement exclusive inventory pipelines in underpenetrated southern regions before regulatory arbitrage windows close. Deepen backward integration into restoration artisan networks to defend against capacity constraints in fresco conservation and specialized stonemasonry. Channel control through boutique office density in Milan, Rome, and Florence premium submarkets remains the critical lever.
For New Entrants and Emerging Players: Launch via direct-to-seller digital platforms targeting German and Swiss HNWIs in Piedmont's Langhe region and Lake Garda's western shore. White-space concentration sits in smart home convergence for heritage-sensitive retrofit design, with Calabria coastline vacation homes representing the most penetrable geography. Go-to-market acceleration depends on compliance technology deployment for non-EU buyer verification cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among agriturismo conversion operators in Alba and Asti municipalities with unoptimized short-term rental yield structures. Long-term viability across the analysis window hinges on EU energy performance mandate compliance and Superbonus regime continuity. Watch Agenzia delle Entrate building code interpretations as the inflection signal for renovation economics repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage-Compliant Energy Retrofit | Superbonus 110% eligibility elevates asset values for certified thermal upgrades in Tuscany and Umbria. |
| Direct-to-Seller Platform Launch | Digital disintermediation compresses commission structures for German buyers in Piedmont's Langhe region. |
| Southern Region Exclusive Mandate | Calabria and Basilicata coastline aggregation captures lifestyle migration capital at Tuscan discounts. |
| Restoration Artisan Network Acquisition | Captive supply of fresco conservation and stonemasonry capacity mitigates permitting timeline risk. |
| Smart Home Heritage Integration | Building automation convergence creates premium pricing tiers for tech-enabled historical properties. |
Study Parameters
Direct dialogue with luxury brokerage principals, restoration contractors, Agenzia delle Entrate officials, and family office investment officers grounded qualitative findings in operational reality. Secondary validation drew from Ministry of Culture heritage listings, Agenzia delle Entrate valuation benchmark publications, EU energy performance directive filings, and regional customs transaction records. Bottom-up property-level transaction analysis triangulated against top-down regional market sizing across the segmentation dimensions.
Market value and transaction volume outputs across the projection horizon reflect econometric modeling of buyer demographic flows, regulatory incentive uptake rates, and renovation cost elasticity. Segmentation dimensions modeled include property type, buyer profile, purchase purpose, and sales channel, with regional regulatory cluster and Superbonus compliance tier as industry-specific overlays. CAGRs derived from historical transaction velocity patterns and forward-looking HNWI capital deployment surveys.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Superbonus regime modification or accelerated EU energy performance enforcement. Forecasts reflect assumptions regarding cross-border capital mobility, artisan labor supply continuity, and municipal short-term rental zoning stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market