
 Australia Commercial Real Estate Market | 2026-2036
Australia Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Commercial Real Estate Market Analysis
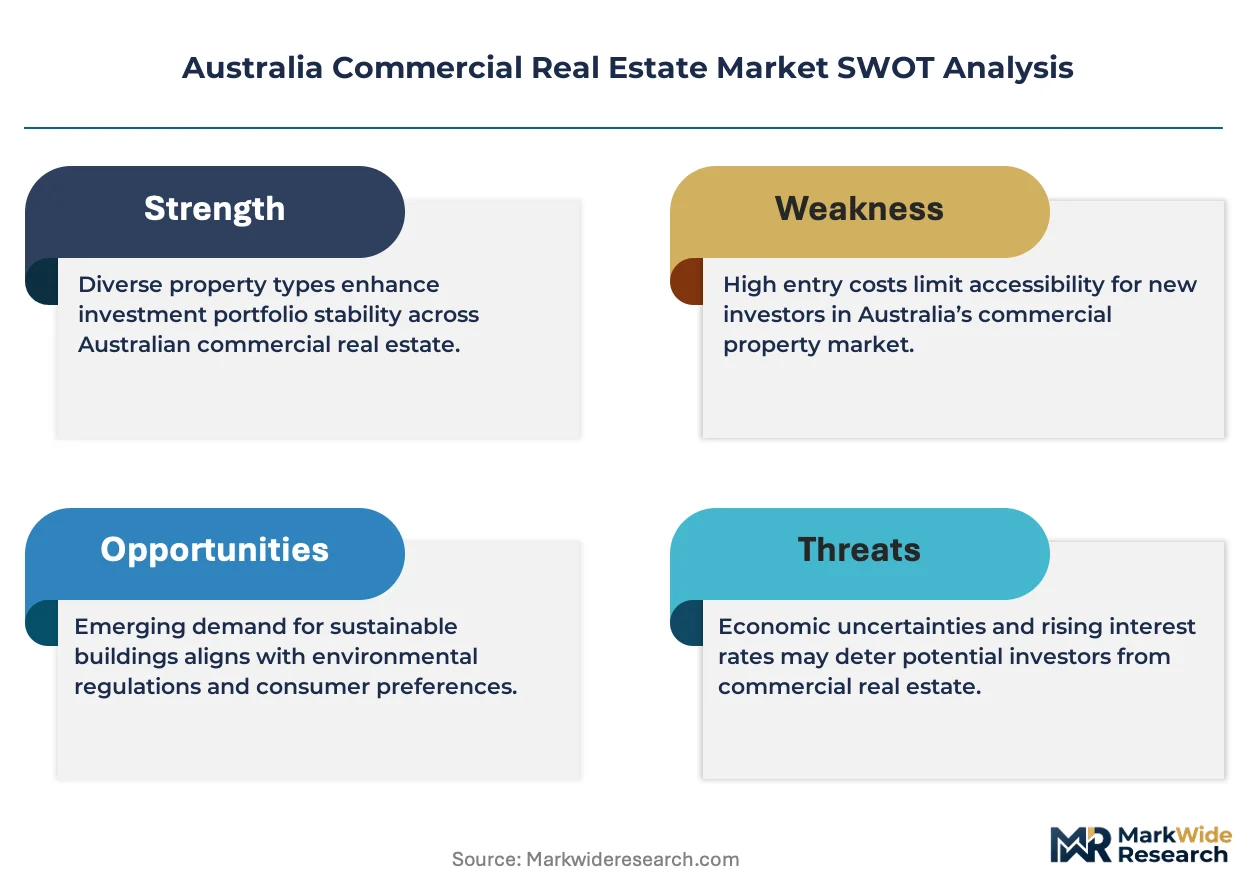
Multi-source development partnerships is pivoting as the dominant capital deployment model across Australian commercial property. Goodman Group leverages its industrial land bank to control last-mile logistics sites in every mainland capital. Scentre Group anchors premium retail throughput through its Westfield portfolio dominance. Stockland competes across master-planned communities with integrated commercial precincts.
Australia commercial real estate comprises income-producing property assets including office towers, retail centres, industrial warehouses, and mixed-use developments, typically structured through freehold or leasehold tenure with weighted average lease expiries measuring income stability. These assets generate returns through contractual rental streams and capital appreciation, serving institutional investors, corporate occupiers, and small business tenants. Industrial assets lead capital value growth as e-commerce fulfillment demand reshapes logistics requirements across the eastern seaboard. REITs sustain liquidity advantages for retail investors seeking property exposure without direct asset management, while direct investment concentrates among superannuation funds pursuing long-duration inflation-linked returns. Joint ventures occupy the development risk layer, pairing capital partners with operating expertise on speculative office and mixed-use projects.
The Australian Prudential Regulation Authority shapes lending standards for commercial property exposures, while the National Construction Code mandates minimum energy performance thresholds that filter development feasibility. TGA building material certifications intersect with state-based planning regimes to determine project timelines and compliance costs. Stakeholders must monitor interest rate transmission into debt-dependent development pipelines and assess which lease structures transfer operating cost volatility to tenants.
Market Dynamics
Interest rate transmission into debt-dependent development pipelines is compressing project feasibility across Australian commercial property, forcing capital partners to recalibrate joint venture structures and lease terms that transfer operating cost volatility to tenants.
Growth Catalysts
- Technology sector expansion:Cloud computing and artificial intelligence firms are absorbing premium office space in Sydney and Melbourne, driving net effective rents in core CBD submarkets.
- National Construction Code updates:Minimum energy performance thresholds are accelerating building retrofit cycles and creating compliance-driven refurbishment demand across aging stock.
- Queensland logistics corridor concentration:E-commerce fulfillment networks are clustering distribution facilities along Brisbane's motorway corridors, tightening industrial vacancy to historic lows.
Market Restraints
- Construction cost escalation:Structural steel and concrete input volatility is eroding development margins on speculative office and mixed-use projects.
- Debt market concentration:Australian Prudential Regulation Authority lending standards restrict commercial property exposure concentration among major domestic banks.
- Lease structure rigidity:Traditional gross lease formats prevent immediate operating cost pass-through, exposing landlords to utility and maintenance inflation.
Strategic Opportunities
- Perth office submarket:Resources sector consolidation has suppressed CBD rents below replacement cost, positioning value-add repositioning strategies.
- Last-mile infill logistics:Urban consolidation constraints are elevating rental premiums for sub-5,000 square metre facilities within 15 kilometres of Sydney and Melbourne CBDs.
- Build-to-rent residential convergence:Institutional capital is migrating toward integrated mixed-use precincts combining commercial income with residential annuity streams.
Industry Challenges
- Development approval timelines:State-based planning regime variations and TGA building material certification requirements are extending project gestation periods.
- Weighted average lease expiry compression:Tenant preference for shorter commitment terms is destabilizing income visibility for institutional investors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Commercial Real Estate Market |
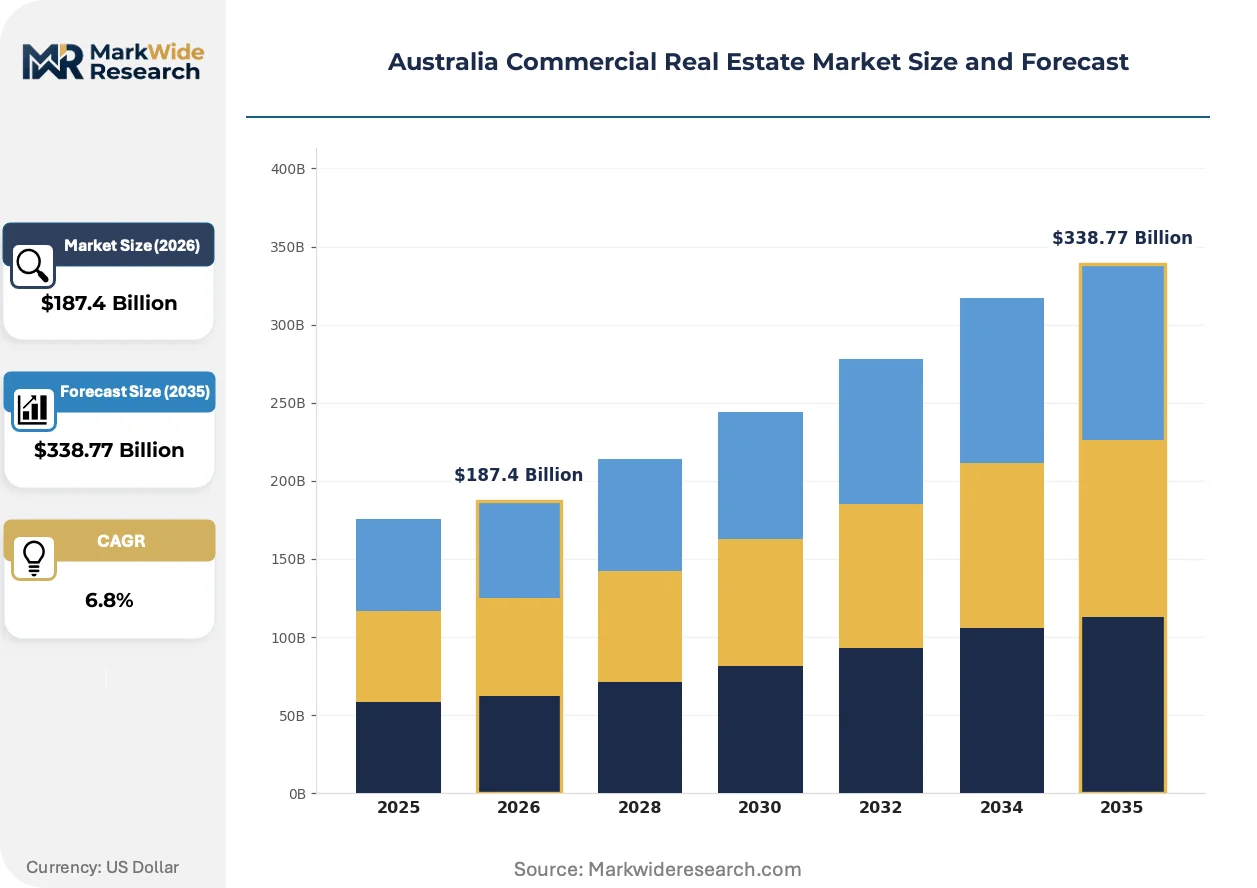
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Type: Direct Investment, REITs, Joint Ventures, Funds Lease Structure: Gross Lease, Net Lease, Percentage Lease, Modified Gross Building Class: A-Class, B-Class, C-Class, Adaptive Reuse |
| Companies Covered | Goodman Group, Scentre Group, Stockland, Lendlease Corporation, GPT Group, Dexus, Charter Hall Group, Mirvac, Multiplex Constructions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Commercial Real Estate Market Emerging Trajectories
Smart building infrastructure and sustainability certification are redefining asset competitiveness across Australian commercial property, separating investable grade from obsolescent stock.
Building management system integration with grid-responsive energy platforms is electrifying operational efficiency across premium office towers. Major corporate occupiers in Sydney and Melbourne are mandating NABERS Energy ratings above 5 stars as lease preconditions. This technology convergence is compressing capital expenditure recovery periods for landlords who retrofit ahead of compliance deadlines.
The National Construction Code's trajectory toward net-zero-ready standards is mandating embodied carbon disclosure for construction materials above specified thresholds. Developers are responding by pre-certifying projects through Green Star and NABERS frameworks to secure institutional capital commitment. Industrial assets face the steepest compliance cost escalation given their energy-intensive operational profiles.
Tenant decision-making is consolidating around flight-to-quality preferences that prioritize wellness certification and flexible space configurations. Traditional secondary-grade office stock in peripheral locations is experiencing demand erosion as occupiers cluster in premium, transit-linked precincts. This behavioral shift is most pronounced in Melbourne's Docklands and Sydney's Barangaroo, where amenity-rich environments command sustained rental premiums.
Australia Commercial Real Estate Market Segmentation
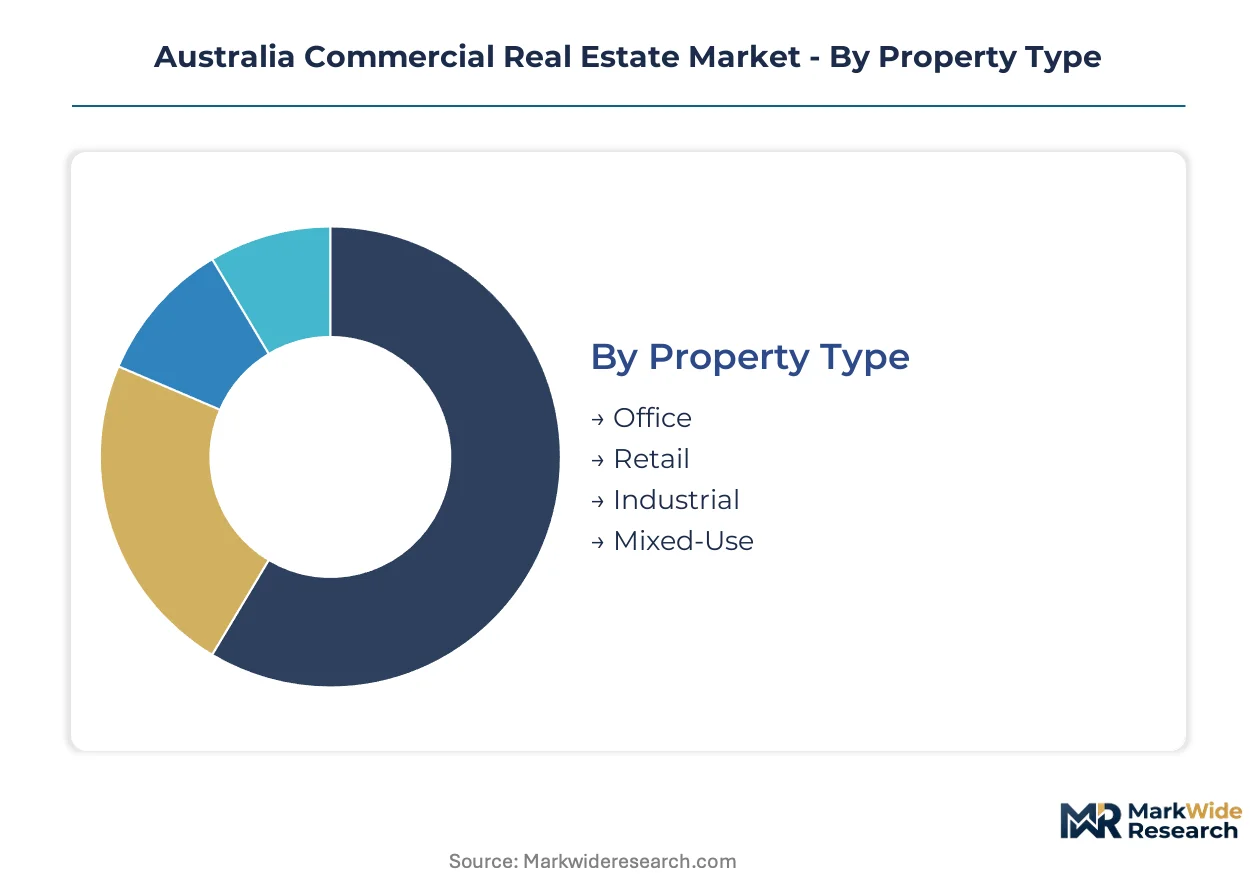
Segmentation reveals how capital allocation preferences and regulatory pressures fragment Australia's commercial property landscape. Each dimension exposes distinct risk-return profiles that institutional investors must weigh against lease duration and compliance exposure.
Property Type:
Industrial assets command volume leadership through e-commerce fulfillment demand, while office towers retain premium pricing power in Sydney and Melbourne CBDs.
- Office:Premium-grade towers in Sydney and Melbourne CBDs attract technology sector tenants mandating NABERS Energy ratings above 5 stars. Cloud computing and artificial intelligence firms are absorbing premium space, driving net effective rents in core submarkets despite interest rate headwinds.
- Industrial:Last-mile logistics facilities concentrate along Brisbane's motorway corridors where e-commerce fulfillment networks have tightened vacancy to historic lows. Warehouse assets lead capital value growth as supply constraints elevate rental premiums for sub-5,000 square metre facilities within 15 kilometres of major CBDs.
- Retail:Premium throughput anchors through dominant portfolio positions in metropolitan catchments, though experiential and convenience formats are displacing traditional department store footprints.
- Mixed-Use:Integrated precincts combining commercial income with residential annuity streams are attracting institutional capital seeking inflation-linked duration.
Today's leader: Industrial. Tomorrow's challenger: Mixed-Use.
Investment Type:
Direct investment concentrates among superannuation funds pursuing long-duration inflation-linked returns, while REITs sustain liquidity advantages for retail investors.
- Direct Investment:Superannuation funds deploy patient capital into freehold assets with weighted average lease expiries exceeding five years. This channel dominates trophy asset ownership in Sydney and Melbourne core markets.
- REITs:Exchange-traded structures provide retail investors property exposure without direct asset management burdens. Liquidity premiums trade off against fee drag and portfolio rigidity.
- Joint Ventures:Development risk layer pairs capital partners with operating expertise on speculative office and mixed-use projects.
- Funds:Pooled vehicles aggregate institutional commitments for diversification across property types and geographies.
Direct Investment holds the dominant position. Joint Ventures are climbing the fastest as development pipelines expand.
Lease Structure:
Gross lease formats dominate legacy stock, though net lease structures are gaining traction as landlords seek operating cost volatility transfer.
- Gross Lease:Traditional formats prevent immediate operating cost pass-through, exposing landlords to utility and maintenance inflation. Aging stock in peripheral locations relies heavily on this structure.
- Net Lease:Tenants assume property tax, insurance, and maintenance obligations, stabilizing landlord cash flows. Industrial assets increasingly adopt this format.
- Percentage Lease:Retail tenants pay base rent plus percentage of gross sales, aligning landlord returns with tenant performance.
- Modified Gross:Hybrid structures split operating cost responsibilities, common in transitioning office assets.
Net Lease is gaining share fastest. Modified Gross structures are expanding most quickly in retrofit cycles.
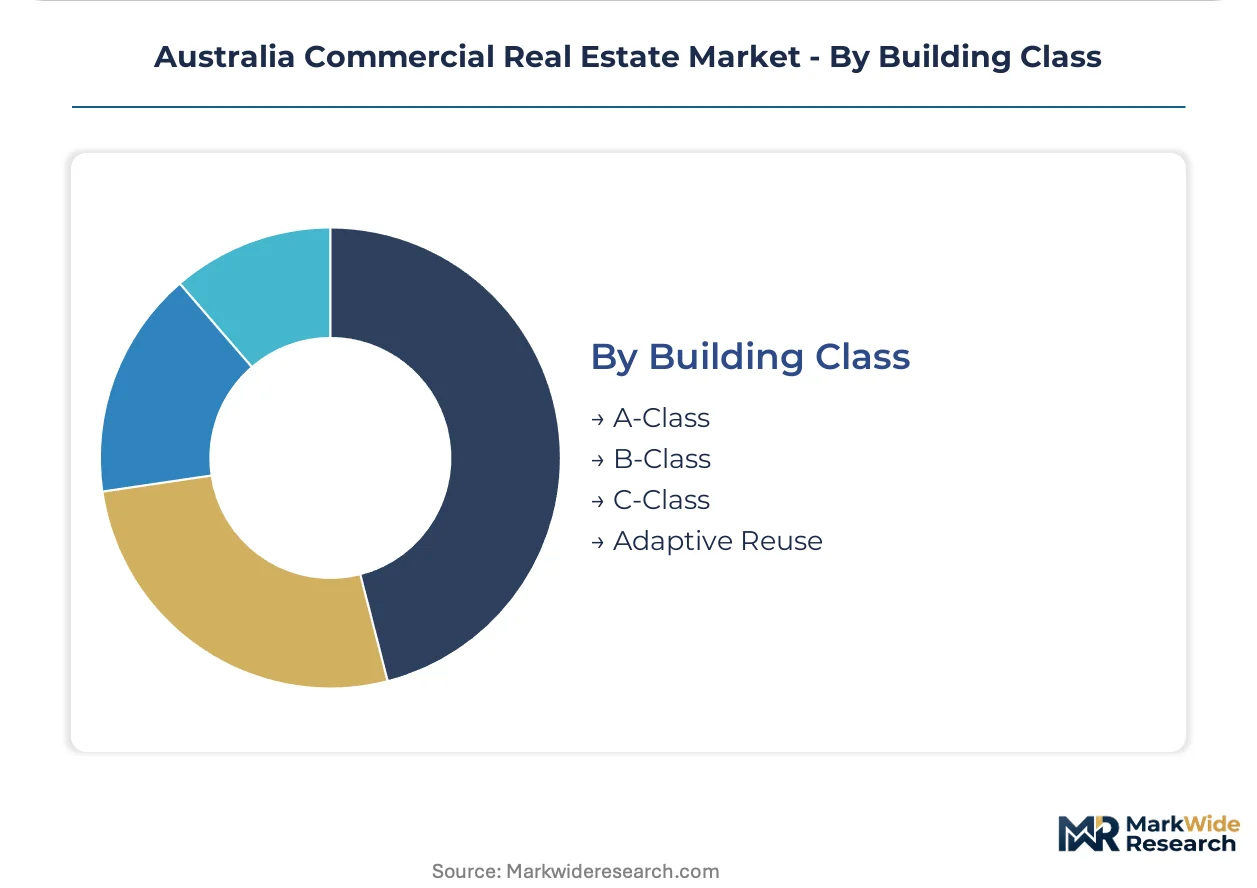
Building Class:
A-Class assets separate from obsolescent stock through smart building infrastructure and sustainability certification, while adaptive reuse addresses compliance-driven refurbishment demand.
- A-Class:Premium towers integrate building management systems with grid-responsive energy platforms. Corporate occupiers mandate wellness certification and flexible space configurations as lease preconditions.
- B-Class:Secondary-grade stock in transit-linked locations offers value-add repositioning potential. Melbourne's Docklands and Sydney's Barangaroo command sustained rental premiums through amenity-rich environments.
- C-Class:Peripheral locations face demand erosion as occupiers cluster in premium, transit-linked precincts.
- Adaptive Reuse:National Construction Code updates toward net-zero-ready standards are accelerating retrofit cycles and creating compliance-driven refurbishment demand across aging stock.
A-Class towers dominate institutional allocation. Adaptive Reuse is gaining share fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sydney-Melbourne office corridor commands institutional capital flows as technology sector expansion reshapes tenant demand across Australia's eastern seaboard.
New South Wales
Cloud computing and artificial intelligence firms are absorbing premium office space in Sydney CBD and Barangaroo precincts. The Australian Prudential Regulation Authority maintains lending standards that shape commercial property exposure limits for domestic banks. Parramatta's emerging commercial core is capturing decentralised office demand as transport infrastructure investment accelerates.
Victoria
Melbourne's Docklands and Southbank precincts attract technology tenants mandating NABERS Energy ratings above five stars. The National Construction Code updates mandate minimum energy performance thresholds that filter development feasibility across the state. Footscray and inner-west industrial zones are converting to mixed-use precincts as institutional capital seeks integrated income streams.
Queensland
E-commerce fulfillment networks are clustering distribution facilities along Brisbane's motorway corridors, tightening industrial vacancy to historic lows. State-based planning regime variations intersect with TGA building material certifications to determine project timelines. The Logan and Ipswich logistics corridor is capturing last-mile infrastructure investment as supply constraints elevate rental premiums.
Western Australia
Resources sector consolidation has suppressed Perth CBD office rents below replacement cost, positioning value-add repositioning strategies. The Western Australian Planning Commission shapes development approval timelines that extend project gestation periods. Fremantle's industrial fringe is attracting adaptive reuse projects as compliance-driven refurbishment demand accelerates across aging stock.
South Australia
Defence and advanced manufacturing investment is stabilising Adelaide's commercial property demand after prolonged public sector contraction. The South Australian Planning Commission administers state-based planning regimes that determine compliance costs. The Edinburgh Parks defence precinct is anchoring industrial absorption as sovereign capability programs expand manufacturing footprints.
Australia Commercial Real Estate Market Vendor Landscape
Global institutional capital competes with domestic superannuation fund champions across development risk layers and trophy asset ownership. The market structure concentrates around vertically integrated developers, diversified REITs, and specialised logistics operators. Three archetypes dominate: land bank controllers leveraging industrial scarcity, portfolio aggregators capturing liquidity premiums, and construction-led developers internalising delivery risk. Competitive intensity manifests through joint venture structuring for speculative pipelines and sustainability pre-certification to secure institutional commitment.
Among integrated Australian developers, Goodman Group, Scentre Group, and Stockland exemplify distinct strategic positions. Goodman Group represents the land bank controller archetype, leveraging industrial scarcity across mainland capitals. Scentre Group anchors the portfolio aggregator position through metropolitan retail dominance. Stockland occupies the diversified developer tier, competing across master-planned communities with integrated commercial precincts. Lendlease Corporation and Dexus sit within the construction-led and funds management vectors respectively, though their strategic differentiation narrows as capital deployment models converge on partnership structures.
| Leading Market Players |
|---|
| Goodman Group |
| Scentre Group |
| Stockland |
| Lendlease Corporation |
| GPT Group |
| Dexus |
| Charter Hall Group |
| Mirvac |
| Multiplex Constructions |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across development partnerships anchors supply positioning and pricing power for Australian commercial property, as joint venture structures concentrate land bank control among vertically integrated operators while the National Construction Code compliance costs filter development feasibility.
Pricing Analysis
Input-cost pass-through mechanics determine rental rate trajectories across Australian commercial property, with structural steel and concrete volatility compressing development margins on speculative office projects. Pricing stratifies across premium-grade A-Class towers, B-Class transit-linked repositioning candidates, and C-Class peripheral stock facing demand erosion. Cost compression in secondary office markets is intensifying because tenant flight-to-quality preferences concentrate absorption in NABERS 5-star certified assets. Corporate occupiers in Sydney and Melbourne CBDs demonstrate lowest price sensitivity, while small business tenants in peripheral locations face highest rent burden vulnerability.
Supply Chain Analysis
Single-source vulnerability sits with Chinese structural steel and engineered timber imports that feed Australian construction pipelines, exposing project timelines to tariff fluctuations and logistics chokepoints. Supply draws from China, South Korea, and domestic Australian manufacturing for core building materials including steel reinforcement, concrete admixtures, and glazing systems. Regulatory restriction risk emanates from TGA building material certification requirements that intersect with state-based planning regimes to extend approval timelines. Distribution runs through developer-led procurement consortia that aggregate volume commitments across joint venture partnerships, concentrating bargaining power with tier-one contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian commercial property offers margin expansion potential as NABERS certification premiums widen and compliance-driven refurbishment demand accelerates retrofit cycles, compressing capital expenditure recovery periods for landlords who pre-certify ahead of regulatory deadlines.
For Market Incumbents: Deploy sustainability pre-certification as the defensive lever against obsolescence risk, accelerating Green Star and NABERS frameworks to secure institutional capital commitment before net-zero-ready mandates tighten. Consolidate land bank positions in Brisbane's logistics corridor where e-commerce fulfillment networks have tightened industrial vacancy to historic lows, insulating against development approval timeline extensions that state-based planning variations impose on speculative pipelines. For New Entrants and Emerging Players: Channel partners in last-mile logistics specialization represent the most penetrable entry vector, targeting sub-5,000 square metre facilities within 15 kilometres of Sydney and Melbourne CBDs where urban consolidation constraints elevate rental premiums. White-space exists in Perth office submarket value-add repositioning, where resources sector consolidation has suppressed CBD rents below replacement cost. Build-to-rent residential convergence within mixed-use precincts offers integrated income stream differentiation with lower capital partner competition. For Investors and Strategic Acquirers: Roll-up economics work for industrial land bank controllers because supply constraints across mainland capitals create captive rental growth trajectories that institutional capital prioritizes for inflation-linked duration. Long-term viability centers on weighted average lease expiry profiles exceeding five years with tenant credit quality supporting debt-dependent development pipelines. Monitor interest rate transmission velocity as the inflection indicator for joint venture structure recalibration and operating cost pass-through lease term negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Structuring | Pairs capital partners with operating expertise on speculative pipelines while transferring development risk. |
| Sustainability Pre-Certification | Green Star and NABERS frameworks secure institutional commitment ahead of National Construction Code net-zero mandates. |
| Last-Mile Logistics Infiltration | Sub-5,000 square metre facilities within 15 kilometres of CBDs capture urban consolidation premium. |
| Adaptive Reuse Repositioning | Compliance-driven refurbishment demand accelerates retrofit cycles across aging B-Class and C-Class stock. |
| Build-to-Rent Convergence | Integrated mixed-use precincts combine commercial income with residential annuity streams for duration-matched capital. |
Methodological Framework
Bottom-up tenant absorption modeling reconciled against top-down development pipeline tracking forms the analytical core of this study, combining primary interviews with property fund managers, development directors, tenant representation brokers, and construction procurement leads with secondary validation from Australian Prudential Regulation Authority lending standard disclosures, National Construction Code regulatory filings, state planning department approval databases, and REIT portfolio reporting.
Historical trendline analysis of capital value movements and rental growth trajectories across Sydney, Melbourne, Brisbane, Perth, and Adelaide submarkets establishes baseline momentum patterns across the projection horizon. Segmentation dimensions modeled include property type, investment vehicle structure, lease format, and building class tier. CAGRs derive from lease expiry schedules, development completion timelines, and regulatory compliance deadline clustering. Forecast inputs incorporate technology sector footprint expansion rates and e-commerce fulfillment network facility requirements.
Revisions become necessary when interest rate transmission velocity exceeds modeled assumptions, construction material input volatility disrupts development feasibility, or state-based planning regime variations extend approval timelines beyond historical patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
South Africa Commercial Real Estate Market