
 Egypt Commercial Real Estate Market | 2026-2036
Egypt Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Commercial Real Estate Market Foresight
Project finance through long-term institutional leasing is narrowing the competitive field to developers with balance-sheet depth. Emaar Misr leverages its integrated master-planning model to control land parcels across the New Administrative Capital. Talaat Moustafa Group anchors its position through captive construction capacity and recurring revenue from leaseback arrangements. SODIC competes by specializing in lifestyle-oriented mixed-use compounds that command premium tenant retention.
Egypt commercial real estate encompasses income-producing properties—office towers, retail centers, industrial warehouses, and mixed-use complexes—designed for lease to corporate, government, and institutional tenants, typically engineered to seismic zone 2B standards and LEED-equivalent energy benchmarks. The sector generates returns through rental yield appreciation and capital value growth in urban expansion zones. Office and mixed-use property types currently lead transaction volume as multinationals relocate headquarters to government-designated business districts. Industrial segments sustain the fastest structural expansion, driven by localization requirements under Egypt's industrial development strategy. Retail exposure concentrates in luxury and mid-market tiers where foot traffic recovery and formal lease enforcement protect margin pools.
Egypt's General Authority for Investment and Free Zones governs foreign ownership thresholds and special economic zone incentives that direct capital toward designated development corridors. The country's central bank and financial regulatory authority shape leverage limits and mortgage liquidity facilities that determine developer access to construction finance. Egypt's urban planning mandates and building code enforcement through governorate-level authorities dictate permissible density, use mixing, and infrastructure contribution requirements. Stakeholders must monitor how currency hedging availability and repatriation rules interact with lease denomination practices to protect realized returns.
Market Dynamics
Government-mandated relocation of state institutions to the New Administrative Capital is compressing demand timelines and forcing developers to front-load infrastructure investment ahead of confirmed tenant commitments.
Growth Catalysts
- Special Economic Zone Incentives:Egypt's General Authority for Investment and Free Zones offers tax holidays and customs exemptions that attract warehousing and light manufacturing tenants to designated corridors.
- Digital Cadastral Modernization:Streamlined property registration through blockchain-linked title systems reduces transaction friction and accelerates institutional capital deployment.
- Localization Mandates:Industrial development strategy requirements for domestic production are expanding demand for grade-A logistics facilities in 10th of Ramadan and Borg El Arab zones.
Market Restraints
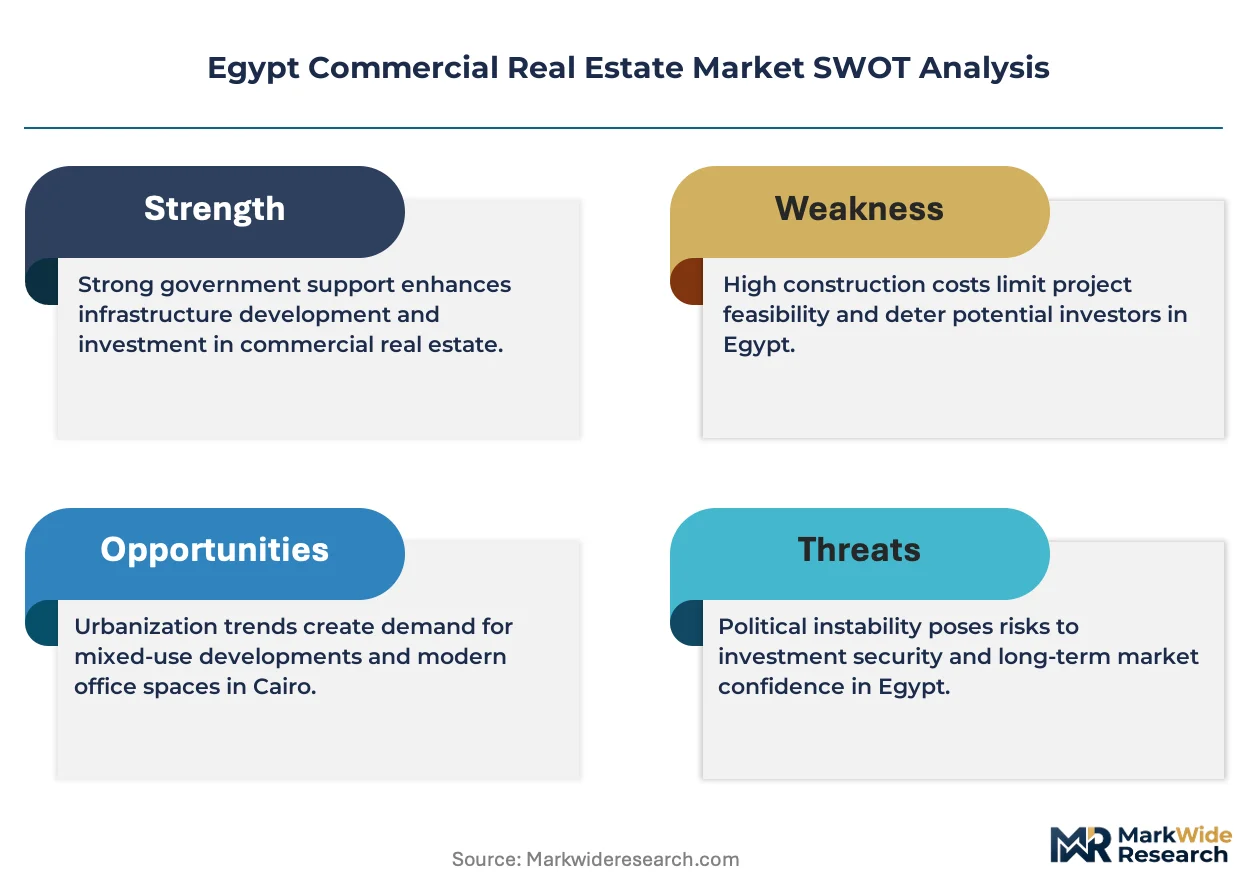
- Foreign Exchange Illiquidity:Limited availability of hedging instruments against Egyptian pound volatility constrains lease denomination in hard currency for international tenants.
- Construction Input Concentration:Steel and cement supply chains depend heavily on domestic producers subject to periodic export restrictions and price controls.
- Seismic Engineering Costs:Zone 2B structural requirements add 12-18% to base construction costs compared to standard commercial specifications.
Strategic Opportunities
- Secondary City Penetration:Alexandria's Borg El Arab corridor and Mansoura's industrial ring retain undersupplied logistics markets with limited competing stock.
- Mixed-Use Density Bonuses:Governorate-level urban planning mandates increasingly permit higher floor-area ratios for developments integrating residential, office, and retail functions.
- Green Building Certification:LEED-equivalent energy benchmarks unlock preferential financing terms through central bank liquidity facilities for sustainable construction.
Industry Challenges
- Skilled Project Management Scarcity:Complex mixed-use developments require coordination across residential, hospitality, and commercial workstreams where experienced local talent pools remain thin.
- Utility Connection Timelines:Electricity and water infrastructure contributions for new developments face 14-22 month approval cycles from governorate authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Commercial Real Estate Market |
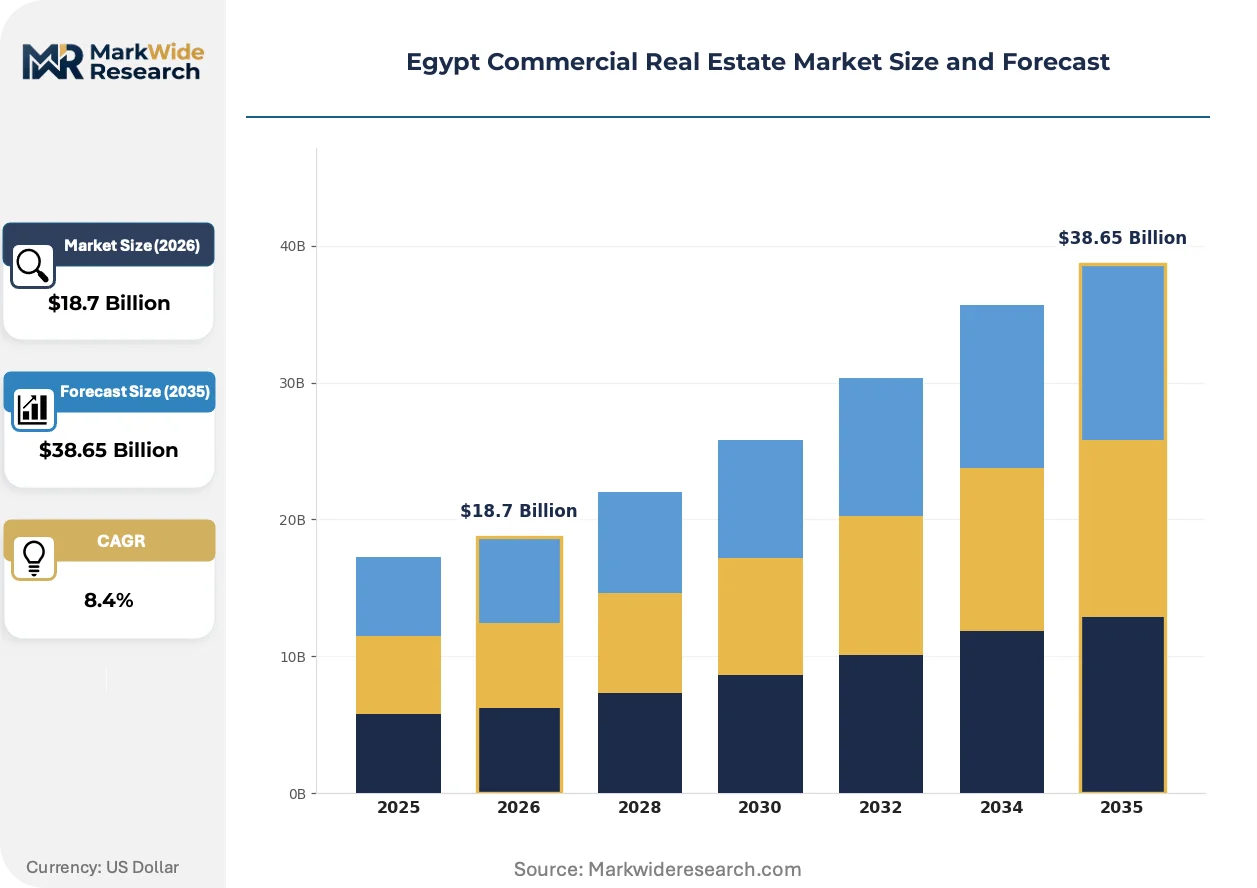
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use End User: Corporations, Investors, Developers, Government Investment Type: Equity, Debt, REITs, Joint Ventures Market Segment: Luxury, Mid-Market, Budget, Others |
| Companies Covered | Amer Group, Emaar Misr, Talaat Moustafa Group, Rock Developments, SODIC, Orascom Construction PLC, The Arab Contractors, Hassan Allam Holding, Palm Hills Developments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Commercial Real Estate Market Shifts & Advancements
Digital infrastructure integration and evolving tenant service expectations are redefining asset competitiveness beyond traditional location and specification metrics.
Smart building management platforms combining IoT sensors with predictive analytics are rendering obsolete manual facilities oversight in premium office stock. Multinational headquarters tenants now mandate real-time energy monitoring and automated climate control as baseline requirements. This compression of operational expectations is widening the rent gap between connected Class A assets and legacy buildings unable to support sensor retrofits.
Egypt's building code enforcement through governorate-level authorities now mandates LEED-equivalent energy benchmarks for all new commercial construction above 5,000 square meters. Developers must submit lifecycle carbon assessments alongside traditional structural documentation. The industrial warehouse segment faces the steepest compliance curve, as existing stock predates thermal envelope requirements.
Tenants increasingly unbundle lease agreements from traditional full-service gross structures, preferring net arrangements with transparent utility pass-throughs and separately metered common area charges. This shift transfers operational risk to occupiers while demanding more sophisticated landlord accounting systems. New Cairo and the New Administrative Capital show the fastest adoption, where institutional tenants possess internal facilities management capacity.
Egypt Commercial Real Estate Market Segmentation
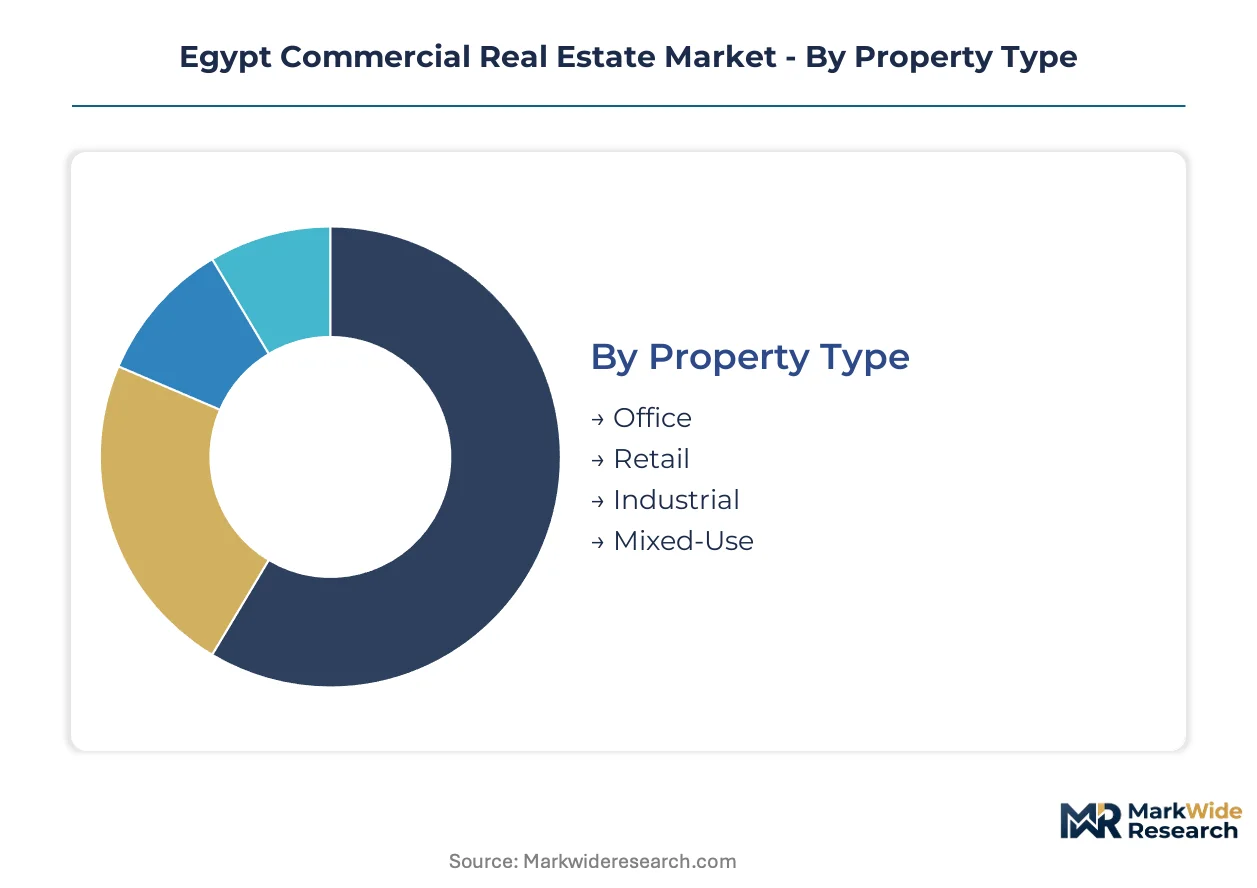
Property type, end user profile, investment vehicle, and market tier each command distinct operational models and capital structures in Egypt's commercial real estate sector. Developers align project specifications, lease structures, and financing arrangements against these dimensions to optimize risk-adjusted returns.
Property Type:
After-sales service intensity varies sharply across property types, with mixed-use developments requiring integrated facilities management spanning residential, retail, and office workstreams.
- Office:Class A towers in New Cairo and the New Administrative Capital incorporate smart building management platforms with IoT-enabled energy monitoring as baseline specifications. Multinational headquarters tenants concentrate demand here, driven by government-mandated relocation of state institutions that compresses absorption timelines.
- Mixed-Use:Developments combining retail, office, and residential functions command premium tenant retention through lifestyle-oriented amenities and captive demand pools. Density bonuses from governorate-level urban planning mandates enable higher floor-area ratios that improve project economics.
- Industrial:Grade-A logistics facilities in 10th of Ramadan and Borg El Arab zones serve localization requirements under Egypt's industrial development strategy.
- Retail:Luxury and mid-market tiers concentrate activity where formal lease enforcement and recovering foot traffic protect margin pools.
By volume, Mixed-Use leads transaction flow. By growth pace, Industrial is climbing the fastest.
End User:
Capital deployment scale and holding period horizons diverge materially across end user categories, shaping developer marketing strategies and lease structure preferences.
- Corporations:Multinational headquarters tenants demand net lease arrangements with transparent utility pass-throughs and separately metered common area charges, transferring operational risk from landlords. These occupiers possess internal facilities management capacity that accelerates adoption in New Cairo and the New Administrative Capital.
- Investors:Institutional capital targets income-producing assets with long-term leaseback arrangements that generate recurring revenue streams and portfolio diversification.
- Developers:Balance-sheet depth determines competitive positioning as project finance through long-term institutional leasing narrows the field to players with integrated master-planning capabilities.
- Government:State institution relocations to the New Administrative Capital front-load infrastructure investment requirements ahead of confirmed tenant commitments.
Corporations anchor current absorption. Government-driven demand is expanding most quickly.
Investment Type:
Risk-return profiles and liquidity characteristics vary substantially across capital structures, influencing sponsor alignment and exit pathway planning.
- Equity:Direct ownership stakes in development projects or stabilized assets offer full upside participation but require active asset management and currency hedging against Egyptian pound volatility.
- Joint Ventures:Partnership structures with local developers provide market access and regulatory navigation while sharing construction and leasing risk.
- Debt:Construction and term financing from banking institutions subject to central bank leverage limits and mortgage liquidity facility conditions.
- REITs:Securities offerings that pool institutional capital toward income-generating portfolios with periodic distribution requirements.
Joint Ventures dominate new project capitalization. Equity deployment is gaining share fastest.
Market Segment:
Specification tiers align tenant quality, construction cost premiums, and achievable rent levels against distinct capital allocation strategies.
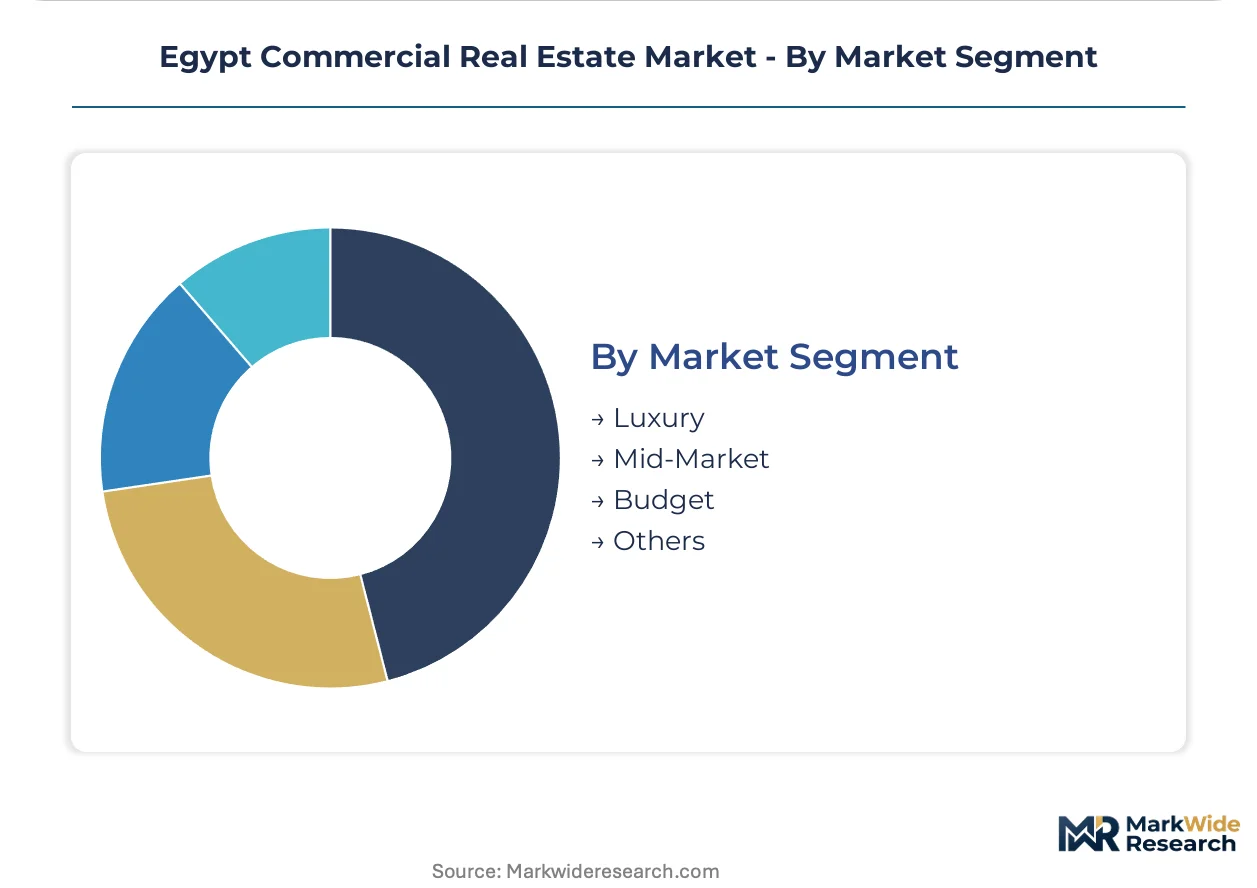
- Luxury:Premium office stock and retail centers in prime Cairo-Alexandria corridor locations incorporate LEED-equivalent energy benchmarks and seismic zone 2B structural standards that add 12-18% to base construction costs.
- Mid-Market:Functional specifications meeting governorate building code requirements without extensive amenity programming serve cost-conscious corporate tenants and domestic retailers.
- Budget:Entry-level industrial warehouses and secondary office stock predating thermal envelope requirements face steepest compliance curves as enforcement tightens.
- Others:Specialized assets including hospitality-integrated commercial and educational-adjacent retail serving niche demand pools.
Mid-Market commands greatest development activity. Luxury assets show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's commercial real estate sector exhibits pronounced regional concentration, with capital flows clustering around state-directed urban expansion corridors rather than organic market diffusion. The New Administrative Capital anchors public sector demand generation, while private development gravitates toward established Cairo-Alexandria infrastructure networks.
Cairo Governorate
Corporate headquarters absorption concentrates in New Cairo's Fifth Settlement and the nascent Central Business District, where multinational tenants negotiate net lease structures with transparent utility pass-throughs. The New Urban Communities Authority governs density bonuses and infrastructure contribution requirements that shape developer project economics. Smart building management platforms with IoT-enabled energy monitoring have become baseline specifications in Class A towers along the Cairo-Suez corridor.
Alexandria Governorate
Borg El Arab's industrial ring sustains undersupplied logistics markets serving localization mandates under Egypt's industrial development strategy. The General Authority for Investment and Free Zones administers special economic zone incentives that attract warehousing and light manufacturing tenants to this western corridor. Grade-A logistics facilities face limited competing stock, compressing vacancy rates and supporting rental yield premiums.
Giza Governorate
6th of October City and Sheikh Zayed districts host mixed-use developments that combine retail, office, and residential functions to capture captive demand pools. Governorate-level urban planning mandates permit higher floor-area ratios for integrated projects, improving developer returns. Seismic zone 2B structural requirements add construction cost premiums that filter development participation toward balance-sheet-deep players.
Qalyubia Governorate
10th of Ramadan City's industrial zones absorb manufacturing relocation from congested Cairo core areas, driven by central bank liquidity facilities for sustainable construction. The industrial warehouse segment faces steep compliance curves as thermal envelope requirements tighten enforcement. Domestic steel and cement supply chain dependencies subject projects to periodic export restrictions and price control volatility.
Egypt Commercial Real Estate Market Competitive Landscape
On the supply side, the industry is consolidating around developers with integrated master-planning capabilities and captive construction capacity. Project finance through long-term institutional leasing has narrowed the competitive field to players possessing balance-sheet depth for front-loaded infrastructure investment. Three strategic archetypes dominate: state-affiliated contractors leveraging public procurement relationships, privately held conglomerates with diversified revenue streams, and specialized lifestyle-oriented developers commanding premium tenant retention. Dominant competitive moves include portfolio diversification across property types and geographic expansion into secondary city corridors.
Among Egyptian developers with integrated capabilities, Emaar Misr, Talaat Moustafa Group, and SODIC occupy distinct positioning within the competitive structure. Emaar Misr exemplifies the master-planned community archetype through land parcel control across government-designated expansion zones. Talaat Moustafa Group anchors the vertically integrated model with recurring revenue from leaseback arrangements. SODIC represents the lifestyle-specialist tier, competing through mixed-use compounds that command retention premiums in New Cairo and Sheikh Zayed districts.
| Leading Market Players |
|---|
| Amer Group |
| Emaar Misr |
| Talaat Moustafa Group |
| Rock Developments |
| SODIC |
| Orascom Construction PLC |
| The Arab Contractors |
| Hassan Allam Holding |
| Palm Hills Developments |
| Others |
Supply & Pricing Matrix
The Cairo-Alexandria Desert Road corridor freight costs compress margin pools for developers sourcing steel and cement from domestic producers, forcing price differentiation between seismic-compliant Class A towers and legacy stock unable to absorb zone 2B engineering premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Egypt's commercial real estate sector. Premium Class A office towers in New Cairo command lease rate premiums through LEED-equivalent certification and smart building management platforms, while budget-tier industrial warehouses face steep compliance curves as thermal envelope requirements tighten. Pricing pressure stems from foreign exchange illiquidity constraining hard-currency lease denomination for international tenants. Government and institutional tenants exhibit lowest price sensitivity due to mandate-driven absorption timelines, whereas domestic retailers operate under acute cost consciousness.
Supply Chain Analysis
Export restrictions on construction-grade steel from Egyptian producers subject to periodic government price controls limit material availability for developers with front-loaded infrastructure commitments. Domestic cement and steel supply chains draw from producers concentrated in Qalyubia and Suez Governorates, creating geographic dependency for projects in the New Administrative Capital. Single-source vulnerability intensifies as state-affiliated contractors prioritize captive supply for public procurement. Distribution runs through governorate-level building material markets with 14-22 month utility connection approval cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's commercial real estate sector sits in early-cycle recovery, with government-mandated state institution relocations to the New Administrative Capital compressing demand timelines and forcing pre-commitment infrastructure investment.
For Market Incumbents: Pre-empt competitive encroachment by securing density bonus entitlements through mixed-use master-planning ahead of governorate urban planning mandate revisions. Consolidate land parcel control in Borg El Arab and 10th of Ramadan corridors before industrial localization requirements accelerate. Vertical integration into captive construction capacity insulates against steel and cement supply chain volatility.
For New Entrants and Emerging Players: Mansoura's industrial ring retains undersupplied logistics markets with limited competing grade-A warehouse stock. Secondary city penetration into Alexandria's western corridor offers white-space capture before special economic zone incentives mature. Joint venture structures with local developers provide regulatory navigation capacity without balance-sheet depth requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors income-producing assets with long-term leaseback arrangements generating recurring revenue streams. Assets with smart building management platforms and IoT-enabled energy monitoring demonstrate durable tenant retention through operational expectation compression. Watch for central bank liquidity facility adjustments as inflection indicators for sustainable construction financing availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Land Parcel Pre-Positioning | Secures entitled development rights in government-designated expansion corridors ahead of infrastructure deployment. |
| Joint Venture Structuring | Distributes construction and leasing risk while accessing local regulatory navigation expertise through partnership. |
| Smart Building Certification | Unlocks preferential central bank liquidity facility terms for sustainable construction above 5,000 square meters. |
| Secondary City Expansion | Captures undersupplied logistics demand in Borg El Arab and Mansoura industrial rings with limited competing stock. |
| Leaseback Arrangement Securitization | Generates recurring revenue streams from government and institutional tenants with mandate-driven absorption timelines. |
Research Methodology
Initial hypotheses were tested against primary input from development project directors, governorate urban planning officers, institutional leasing managers, and construction procurement leads and refined through secondary validation against General Authority for Investment and Free Zones filings, New Urban Communities Authority density entitlement records, central bank mortgage liquidity facility disclosures, and customs data on construction material imports. Bottom-up project pipeline tracking and top-down sector value triangulation anchored market sizing.
Demand-supply balance modeling across the projection horizon incorporated property type segmentation, end user corporate-investor-government-developer profiles, investment vehicle structures, and market tier specifications. CAGRs were derived from absorption timeline compression effects, infrastructure contribution requirement escalations, and lease structure evolution toward net arrangements with transparent utility pass-throughs. Forecast inputs included governorate-level building code enforcement trajectories and special economic zone incentive maturation curves.
Practitioners should monitor currency hedging instrument availability and repatriation rule adjustments for early signals of institutional capital deployment shifts. Forecasts reflect assumptions on state institution relocation schedules and seismic engineering cost trajectories. Material shifts in central bank leverage limits or governorate utility connection approval cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market