
 Global Sharps Containers Market | 2026-2036
Global Sharps Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sharps Containers Market Foresight
The EU Green Deal is realigning procurement criteria for single-use medical plastics across European healthcare systems. Becton, Dickinson and Company leverages its integrated manufacturing footprint to control resin sourcing for puncture-resistant polymer formulations. Cardinal Health anchors its position through direct distribution contracts with integrated delivery networks in North America. Daniels Health differentiates via reusable container servicing infrastructure that reduces landfill burden for hospital waste management departments.
Sharps containers are engineered containment vessels constructed from high-density polyethylene or polypropylene resins, designed with tamper-evident lids and needle-entry apertures to safely collect hypodermic needles, lancets, and scalpel blades until terminal treatment. Wall thickness typically exceeds 1.5 millimeters to resist penetration under 15 pounds of force, with color-coded labeling denoting biohazard classification per OSHA bloodborne pathogen standards. Plastic containers dominate procurement volumes due to cost efficiency and injection-mold scalability, while reusable containers command premium positioning among waste management firms seeking long-term service contracts. Hospital applications generate the largest absolute demand, though home healthcare represents the fastest-expanding application as subcutaneous injection therapies migrate to residential settings.
FDA 510(k) clearance requirements govern container design validation for US market entry, while REACH compliance restricts certain phthalate plasticizers in European-manufactured units. OSHA's bloodborne pathogen standard mandates workplace sharps disposal protocols that directly specify container performance characteristics. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life collection costs from healthcare facilities to original manufacturers.
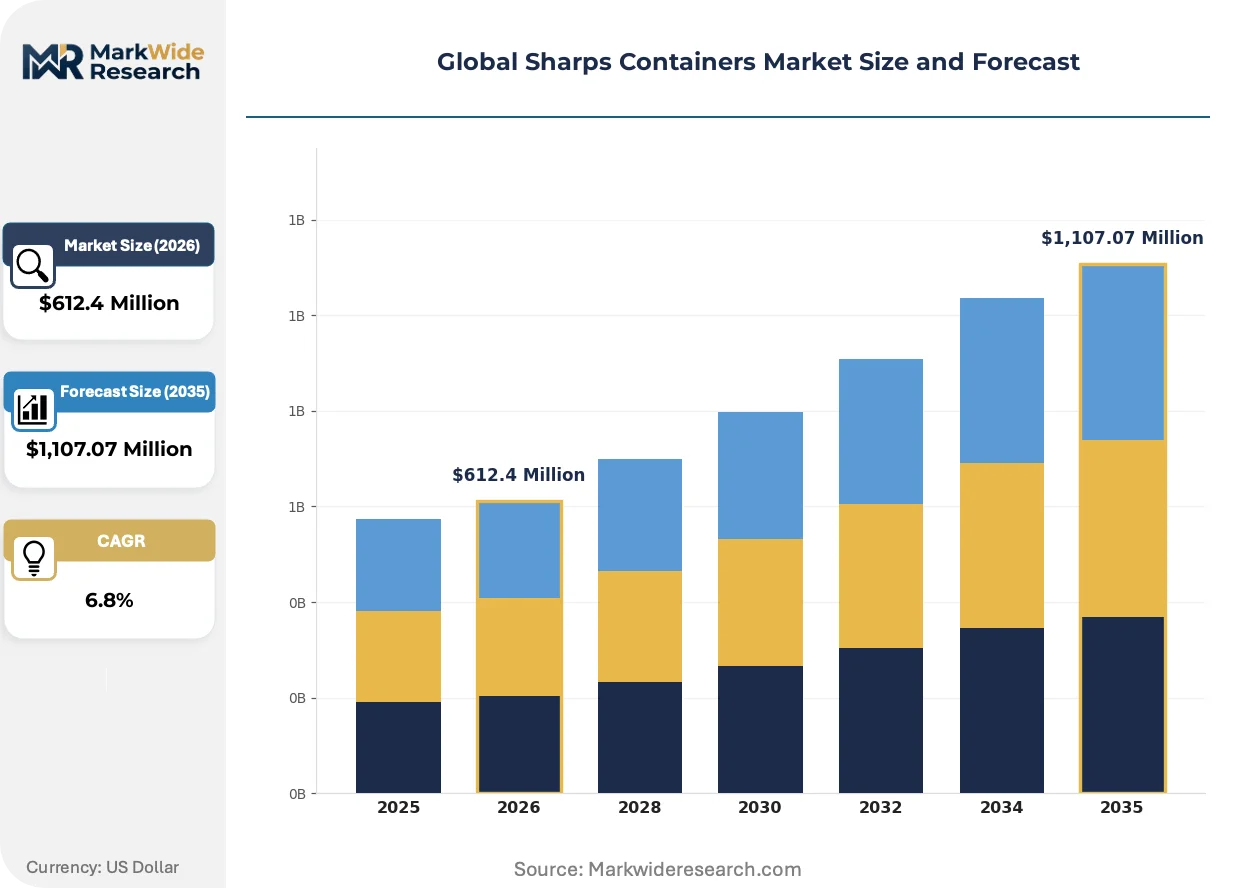
Market Dynamics
The sharps containers market is experiencing structural compression as EU Medical Device Regulation (MDR) compliance costs force consolidation among mid-tier manufacturers while home healthcare expansion creates divergent product specifications.
Growth Catalysts
- EU MDR Material Compliance Mandates:Tightened polymer traceability requirements are accelerating replacement cycles for non-compliant legacy inventory across German and French hospital networks.
- Home Healthcare Subcutaneous Injection Surge:Diabetes and biologic therapy administration in residential settings is generating incremental container demand with specialized portability specifications.
- REACH Phthalate Restrictions:Banned plasticizer categories are redirecting procurement toward medical-grade polypropylene formulations certified under updated ECHA substance regulations.
Market Restraints
- Resin Supply Concentration:High-density polyethylene feedstock dependence on Gulf Coast petrochemical complexes exposes manufacturers to hurricane-related production disruptions.
- Reusable Container Capital Intensity:Daniels Health-style servicing infrastructure requires fleet logistics investments that lock out smaller regional competitors.
- OSHA Compliance Verification Costs:Third-party puncture-resistance testing for 510(k) submissions adds fixed regulatory overhead disproportionately burdening low-volume producers.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Emerging EU national implementations of manufacturer-funded end-of-life collection create service-revenue streams beyond unit sales.
- Smart Container Integration:RFID-enabled fill-level monitoring is converging with hospital waste management software to enable dynamic logistics optimization.
- Asia-Pacific Ambulatory Surgical Center Expansion:Japan's METI-certified day-surgery facilities are adopting Western-standard containment protocols for infection control certification.
Industry Challenges
- Polymer Compounding Expertise Scarcity:Medical-grade puncture-resistant formulation development requires specialized rheology knowledge concentrated among aging technical workforces.
- Dual Certification Timeline Compression:Simultaneous FDA 510(k) and EU MDR technical documentation preparation strains regulatory affairs capacity at mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sharps Containers Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Metal Containers, Biodegradable Containers, Disposable Containers, Reusable Containers Application: Hospitals, Laboratories, Clinics, Veterinary Care, Home Healthcare End User: Medical Practitioners, Diagnostic Centers, Pharmaceutical Companies, Research Institutes, Waste Management Firms Capacity: 1 Liter, 2 Liters, 3 Liters, 5 Liters, 10 Liters |
| Companies Covered | Becton, Dickinson and Company, Cardinal Health, Stericycle, Sharps Compliance, Inc., Daniels Health, Thermo Fisher Scientific, Henry Schein, Inc., Bondtech Corporation, EnviroTain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sharps Containers Market Shifts & Advancements
Container engineering is pivoting toward circular material flows and digital traceability as regulatory frameworks harden around lifecycle accountability rather than point-of-sale compliance.
Antimicrobial polymer integration is converging with copper-ion additive technology to reduce surface pathogen viability in high-touch clinical environments. Outpatient dialysis centers in Spain and Italy are piloting these formulations for immunocompromised patient protocols. The structural consequence is compressing commoditized single-use segments toward premium-certified product tiers.
REACH SVHC candidate list expansion is forcing reformulation of colorant and stabilizer packages in European-manufactured containers. Compounders serving the medical device sector are accelerating substitution timelines for brominated flame retardants ahead of 2026 sunset dates. German procurement consortiums are now requiring full material disclosure documentation as a bid qualification threshold.
Hospital waste management departments are unbundling container supply from disposal service contracts to optimize total cost of ownership. Integrated delivery networks in Texas and Florida are negotiating direct manufacturer relationships that bypass traditional distributor markups. This pattern is most visible in US states with concentrated private health system ownership where procurement centralization authority rests with corporate supply chain officers rather than individual facility managers.
Global Sharps Containers Market Segmentation
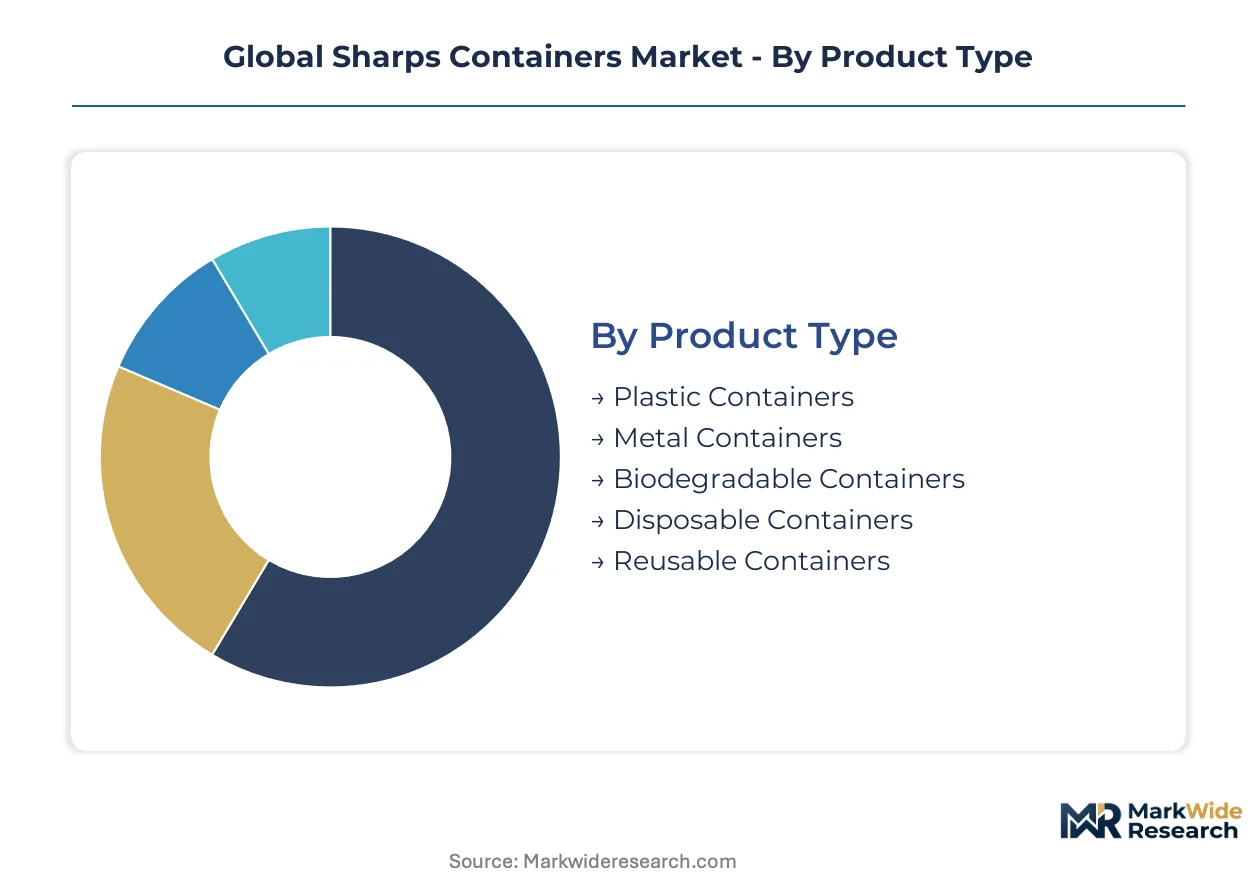
Sharps container procurement splits across material chemistry, clinical setting, waste handler type, and volume specification. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across manufacturer portfolios.
Product Type:
Capital intensity concentrates in reusable container servicing infrastructure and specialized polymer compounding equipment for medical-grade formulations.
- Plastic Containers:High-density polyethylene and polypropylene formulations dominate procurement volumes through injection-mold scalability. German hospital networks and US integrated delivery networks specify color-coded biohazard labeling per OSHA and EU MDR traceability mandates.
- Reusable Containers:Servicing logistics require fleet investments and sterilization infrastructure that lock out smaller competitors. Daniels Health-style closed-loop systems command premium positioning among waste management firms seeking landfill reduction.
- Metal Containers:Stainless steel variants serve high-temperature autoclave protocols in research settings.
- Biodegradable Containers:PLA-based formulations face REACH compliance hurdles for clinical waste streams.
- Disposable Containers:Single-use units absorb volume pressure from home healthcare expansion.
Most installed capacity flows through plastic containers. Expansion is steepest in reusable containers.
Application:
Clinical setting determines container specification complexity and regulatory scrutiny intensity.
- Hospitals:Centralized procurement mandates puncture-resistance certification under FDA 510(k) and EU MDR. Wall thickness exceeding 1.5 millimeters resists 15 pounds of penetration force in high-throughput surgical wards.
- Home Healthcare:Subcutaneous injection therapies for diabetes and biologics demand portable, tamper-evident designs. Residential settings in Germany and Florida drive specialized smaller-capacity specifications.
- Laboratories:Research protocols require dual biohazard and chemical compatibility labeling.
- Clinics:Outpatient surgical volumes elevate procurement standards in ambulatory settings.
- Veterinary Care:Animal health protocols adapt human-standard containment for zoonotic risk mitigation.
Hospital procurement absorbs the largest absolute volumes. Home healthcare is climbing the fastest.
End User:
Waste handler sophistication separates premium-certified tiers from commoditized supply.
- Waste Management Firms:Long-term service contracts favor reusable container infrastructure with integrated logistics. Extended producer responsibility frameworks in EU member states shift collection costs toward manufacturer-funded models.
- Medical Practitioners:Individual practice procurement concentrates in single-use plastic units with OSHA-mandated needle-entry apertures.
- Diagnostic Centers:High-test-volume facilities specify antimicrobial polymer integration for immunocompromised patient protocols.
- Pharmaceutical Companies:Manufacturing waste streams require specialized containment for active pharmaceutical ingredient handling.
- Research Institutes:Biosafety level protocols dictate metal or reinforced polymer specifications.
Most contract value concentrates with waste management firms. Medical practitioner demand is expanding most quickly.
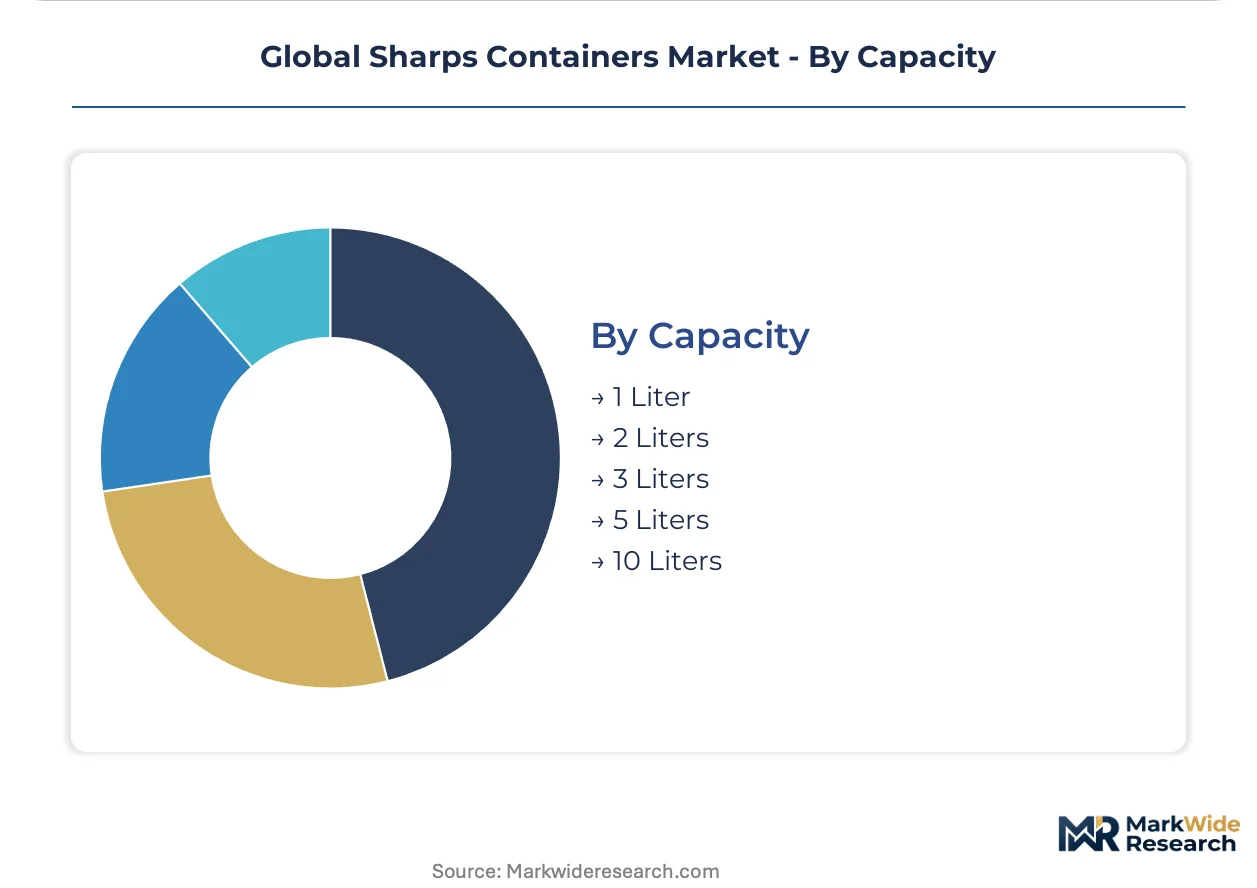
Capacity:
Volume specification aligns with waste generation cadence and space constraints across clinical environments.
- 1 Liter:Compact dimensions serve point-of-care injection stations and home healthcare portability requirements. German outpatient networks specify this tier for mobile nursing protocols.
- 10 Liters:High-volume units minimize exchange frequency in surgical suites and dialysis centers. Wall thickness and structural ribbing requirements elevate material costs disproportionately.
- 2 Liters:Intermediate sizing balances exchange logistics with storage efficiency.
- 3 Liters:Standard clinic workstation specification across EU procurement consortiums.
- 5 Liters:Mid-tier hospital ward deployment for moderate-throughput departments.
Most unit shipments flow through 1-liter specifications. 10-liter demand is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding expertise concentrates in the US Gulf Coast, Germany's Rhine-Ruhr corridor, and Japan's Kansai industrial belt, anchoring three distinct manufacturing ecosystems for medical-grade containment systems.
United States
Integrated delivery networks in Texas and Florida drive procurement centralization as corporate supply chain officers negotiate direct manufacturer relationships. FDA 510(k) clearance requirements govern container design validation for market entry, with OSHA's bloodborne pathogen standard mandating workplace disposal protocols. Houston-area petrochemical complexes supply high-density polyethylene feedstock, though hurricane exposure creates periodic resin disruption risks.
Germany
Outpatient surgical volumes and strict waste segregation protocols elevate procurement standards across hospital networks. EU Medical Device Regulation tightened polymer traceability requirements accelerate replacement cycles for non-compliant legacy inventory. The Rhine-Ruhr corridor hosts specialized compounders serving medical device manufacturers with REACH-compliant formulations.
Japan
METI-certified day-surgery facilities adopt Western-standard containment protocols for infection control certification. Subcutaneous injection therapies for diabetes and biologics generate residential container demand with specialized portability specifications. Osaka-based polymer processors supply puncture-resistant formulations to domestic device manufacturers.
China
Ambulatory surgical center expansion and home healthcare service growth create dual demand streams for containment systems. NMPA medical device registration requirements increasingly align with international standards for polymer traceability. Yangtze River Delta injection molders scale production for both domestic hospital procurement and export markets.
United Kingdom
Hospital waste management departments unbundle container supply from disposal service contracts to optimize total cost of ownership. NHS procurement frameworks emphasize extended producer responsibility for end-of-life collection costs. Midlands-based distributors serve integrated care systems with standardized containment specifications.
Global Sharps Containers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a structurally tiered vendor base. Integrated manufacturers with captive resin sourcing and injection-mold capacity anchor the premium tier, while regional distributors and private-label assemblers populate commoditized segments. Three archetypes dominate: vertically integrated polymer compounders, reusable container servicing operators with fleet logistics infrastructure, and distributor-anchored procurement consolidators. Competitive moves concentrate in direct contract negotiations with health system supply chain officers and M&A targeting regional waste service capabilities.
Within the integrated manufacturing tier, Becton, Dickinson and Company and Cardinal Health exemplify divergent strategic positioning. Becton, Dickinson and Company represents the polymer-compounding archetype with upstream control over resin formulation. Cardinal Health occupies a position as a distributor-anchored consolidator leveraging direct network contracts. Daniels Health sits within the reusable servicing archetype, its closed-loop infrastructure representing premium positioning among waste management firms seeking landfill reduction.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cardinal Health |
| Stericycle |
| Sharps Compliance, Inc. |
| Daniels Health |
| Thermo Fisher Scientific |
| Henry Schein, Inc. |
| Bondtech Corporation |
| EnviroTain |
| Others |
Supply & Pricing Matrix
EU MDR polymer traceability mandates are forcing hospital procurement officers to disqualify non-compliant legacy inventory, compelling manufacturers to absorb reformulation costs and compress margins on standard-grade containers while premium-certified tiers capture pricing power.
Pricing Analysis
Bundled container-plus-disposal service contracts command 15-25% premiums over unbundled unit sales in German hospital networks. Pricing stratifies across FDA 510(k)-certified premium tiers, REACH-compliant mid-tier formulations, and economy-grade private-label supply. Cost compression in standard plastic containers is intensifying because integrated delivery networks in Texas and Florida negotiate direct manufacturer relationships that bypass distributor markups. Medical practitioner segments show highest price sensitivity; waste management firms seeking landfill reduction demonstrate lowest sensitivity due to total-cost-of-ownership optimization.
Supply Chain Analysis
Freight costs for puncture-resistant polymer formulations escalate disproportionately when sourcing from Gulf Coast petrochemical complexes to inland US healthcare markets. Manufacturing concentrates in the United States, Germany, and China. Feedstock draws from high-density polyethylene resin production, medical-grade polypropylene compounding, and colorant stabilizer packages. Single-source vulnerability to hurricane-related production disruptions at Houston-area complexes threatens supply continuity. Distribution runs through integrated delivery network direct contracts, GPO procurement frameworks, and regional waste service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sharps containers market has entered late-cycle quality differentiation as EU Green Deal procurement criteria and FDA 510(k) clearance requirements elevate premium-certified specifications above commoditized supply.
For Market Incumbents: Acquire reusable container servicing fleets to defend against Daniels Health-style closed-loop competitors. Backward integration into medical-grade polypropylene compounding secures REACH-compliant formulation supply. Invest in RFID-enabled fill-level monitoring capabilities to capture hospital waste management software integration contracts. For New Entrants and Emerging Players: Home healthcare subcutaneous injection patients represent an underserved buyer archetype with specialized portability requirements unmet by hospital-centric designs. Target residential diabetes and biologic therapy markets in Germany and Florida with tamper-evident 1-liter specifications. Pursue direct-to-patient pharmacy partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with reusable servicing infrastructure operators holding fleet logistics capabilities in EU member states implementing extended producer responsibility frameworks. Five-to-ten-year viability hinges on landfill reduction mandates tightening across European healthcare systems. Monitor German procurement consortium bid qualification thresholds for full material disclosure documentation as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Certification | Accelerates replacement cycles for non-compliant legacy inventory across German and French hospital networks. |
| Reusable Container Fleet Expansion | Captures premium positioning among waste management firms seeking landfill reduction commitments. |
| Smart Container RFID Integration | Enables dynamic logistics optimization through hospital waste management software convergence. |
| Direct IDN Contract Negotiation | Bypasses distributor markups in Texas and Florida concentrated private health system markets. |
| Antimicrobial Polymer Development | Addresses immunocompromised patient protocols in Spanish and Italian outpatient dialysis centers. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineer consultations, GPO contracts manager discussions, and waste management operator briefings — were reconciled against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and OSHA compliance guidance. Secondary validation drew from customs trade data, petrochemical industry reports, and healthcare supply chain disclosures. Bottom-up container shipment estimates and top-down healthcare expenditure allocations were triangulated to anchor volume and value outputs.
Historical demand patterns were cross-referenced against panel input from supply chain officers and regulatory affairs leads across the projection horizon. Segmentation dimensions modeled include material chemistry, clinical setting, waste handler type, and capacity specification, with additional granularity on polymer formulation certification tiers. CAGRs were derived from trend extrapolation adjusted for regulatory compliance cost impacts and home healthcare expansion trajectories. Forecast inputs incorporated REACH SVHC candidate list expansion timelines and extended producer responsibility framework implementation schedules.
Underlying measurement precision varies by segment; hospital and home healthcare application data carry tighter precision than veterinary and research institute categories. Forecasts reflect assumptions about EU MDR enforcement consistency, resin supply stability, and home healthcare reimbursement policy. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Micro Vials Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Blood Processing Disposables Market