
 Global Nasal Aspirator Market | 2026-2036
Global Nasal Aspirator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasal Aspirator Market Foresight
The premium medical-grade specification tier is collapsing into mid-market positioning as manufacturers broaden accessibility. NoseFrida leverages its Scandinavian design heritage and direct-to-consumer channel control to sustain brand loyalty across European and North American markets. NeilMed Pharmaceuticals anchors its competitive stance through pharmacy distribution networks and ENT specialist endorsements. Pigeon Corporation dominates Asian retail shelves with pediatric-focused packaging and local manufacturing scale.
A nasal aspirator is a suction device engineered to clear mucus from nasal passages, typically operating at negative pressures between 50 and 150 mmHg depending on patient age and device classification, with materials requiring biocompatible silicone or medical-grade polymer construction to prevent airway trauma. Its primary commercial purpose spans infant respiratory hygiene, post-surgical ENT recovery, and homecare management of congestion in non-verbal patients. Electric aspirators are capturing the fastest growth trajectory as parents and pediatric clinics prioritize consistent suction control over manual bulb alternatives. The homecare application segment represents the deepest margin pool due to recurring consumable sales and subscription-style filter replacement models.
The FDA regulates nasal aspirators as Class I or II medical devices depending on powered versus manual operation, while CE marking under the EU MDR imposes biocompatibility and clinical evaluation requirements for European market access. Japan's PMDA maintains distinct pharmaceutical affairs standards that delay foreign product registration but reward JIS-compliant domestic manufacturers. China's NMPA has accelerated GB standard harmonization for infant care electronics, reshaping import timelines for battery-operated aspirators. Stakeholders must monitor evolving battery safety mandates and pediatric device-specific guidance documents across these three regulatory jurisdictions to anticipate compliance-driven product redesign cycles.
Market Dynamics
Pediatric clinics in the United States, Germany, and Japan are standardizing electric aspirator equipment, compressing procurement cycles and forcing manual bulb manufacturers into retail-only positioning.
Growth Catalysts
- EU MDR biocompatibility mandates:European clinical evaluation requirements for medical-grade polymers are elevating material specifications across export-bound production lines.
- Homecare consumable subscription models:Filter replacement programs are generating recurring revenue streams that deepen customer lifetime value in direct-to-consumer channels.
- Silicone airway construction:Biocompatible material adoption is reducing pediatric trauma incidents and expanding insurance reimbursement eligibility for premium device tiers.
Market Restraints
- Medical-grade polymer input volatility:Specialized silicone pricing fluctuations compress margin stability for manufacturers dependent on pharmaceutical-grade supply chains.
- PMDA registration timelines:Japan's pharmaceutical affairs standards create six-to-twelve month entry delays that advantage JIS-compliant domestic producers.
- Bulb aspirator substitution persistence:Low-cost manual alternatives retain price-sensitive volume in emerging retail segments despite performance inferiority.
Strategic Opportunities
- India pediatric clinic expansion:Underpenetrated metro hospital networks present first-mover positioning for electric aspirator distributors establishing service infrastructure.
- Battery safety mandate alignment:China's NMPA GB standard harmonization for infant electronics creates compliance-ready export pathways for certified manufacturers.
- ENT specialist endorsement channels:Pharmacy network partnerships anchored by physician recommendation protocols are displacing pure retail discovery in congestion management categories.
Industry Challenges
- Pediatric device-specific guidance navigation:FDA Class II powered device documentation requirements demand specialized regulatory affairs expertise that strains mid-cap engineering teams.
- Multi-jurisdiction certification parallelism:Simultaneous FDA, CE marking, and PMDA submission timelines create capital allocation pressure during product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasal Aspirator Market |
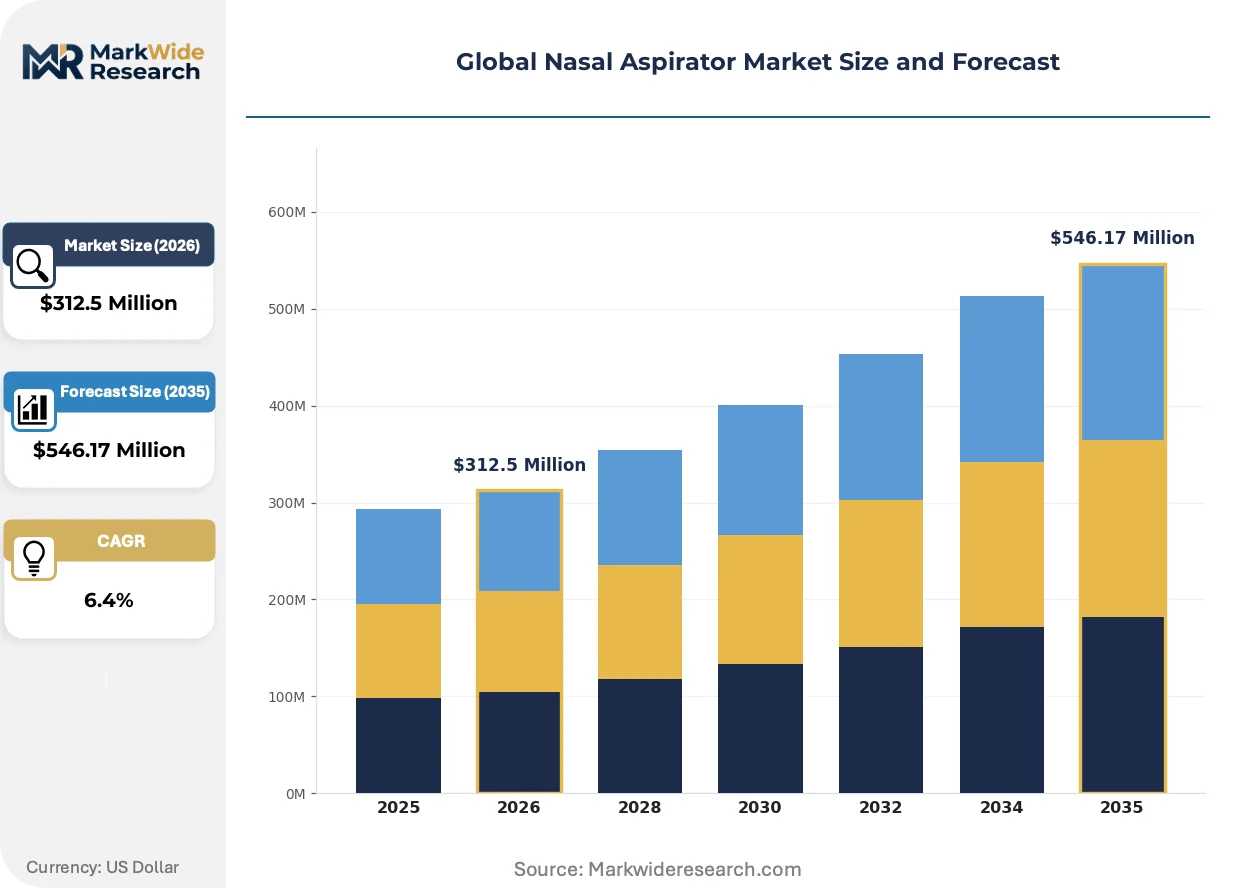
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
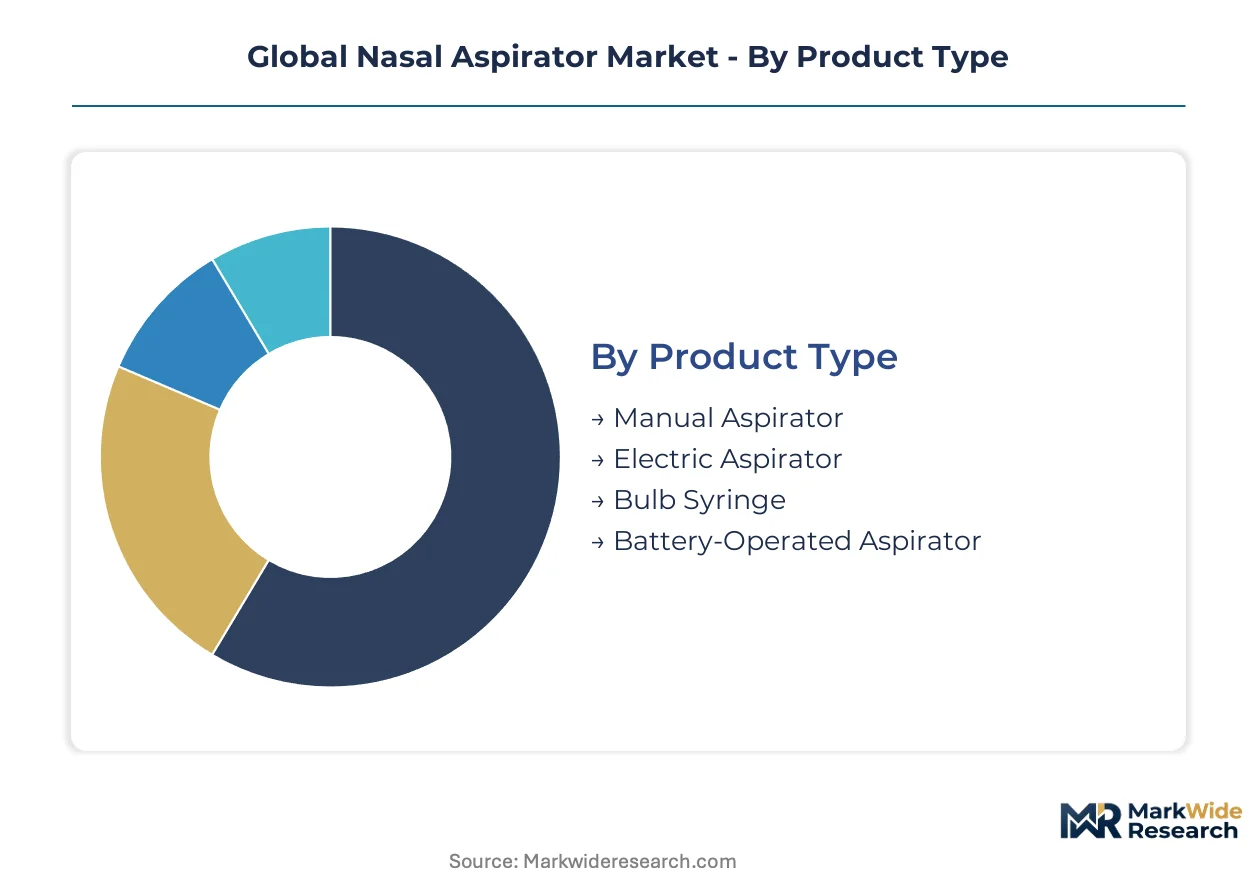
| Segmentation | Product Type: Manual Aspirator, Electric Aspirator, Bulb Syringe, Battery-Operated Aspirator Application: Infant Care, Pediatric Clinics, Homecare Use, Childcare Centers End User: Hospitals, ENT Specialists, Pediatricians, Home Users Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Specialty Stores |
| Companies Covered | NoseFrida, NeilMed Pharmaceuticals, AViTA Corporation, Pigeon Corporation, NUK, Graco, Béaba, B.Well Swiss AG, Rumble Tuff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasal Aspirator Market Shifts & Advancements
Consistent suction control architectures are displacing variable-pressure manual alternatives, while regulatory convergence around biocompatibility and battery safety is compressing design iteration cycles.
Micro-pump negative pressure systems are decomposing the traditional separation between clinical-grade precision and home-use convenience. Pediatric clinics in Germany and Japan are adopting these systems for standardized suction protocols. This convergence is decomposing the premium-mid-economy tier boundaries that previously segmented institutional and retail procurement.
CE marking under EU MDR is imposing clinical evaluation requirements that extend documentation obligations to previously exempt manual device categories. Manufacturers are responding by consolidating product lines around modular platforms that satisfy both powered and non-powered classification pathways. European distributors are prioritizing MDR-compliant inventory to preempt notified body backlog delays.
Direct-to-consumer discovery is displacing pharmacy-first purchase patterns among millennial parent demographics. Subscription-style filter replacement programs are capturing recurring engagement that retail transactions cannot replicate. This channel rotation is most visible in United States and Scandinavian markets where digital-native parenting communities concentrate.
Global Nasal Aspirator Market Segmentation
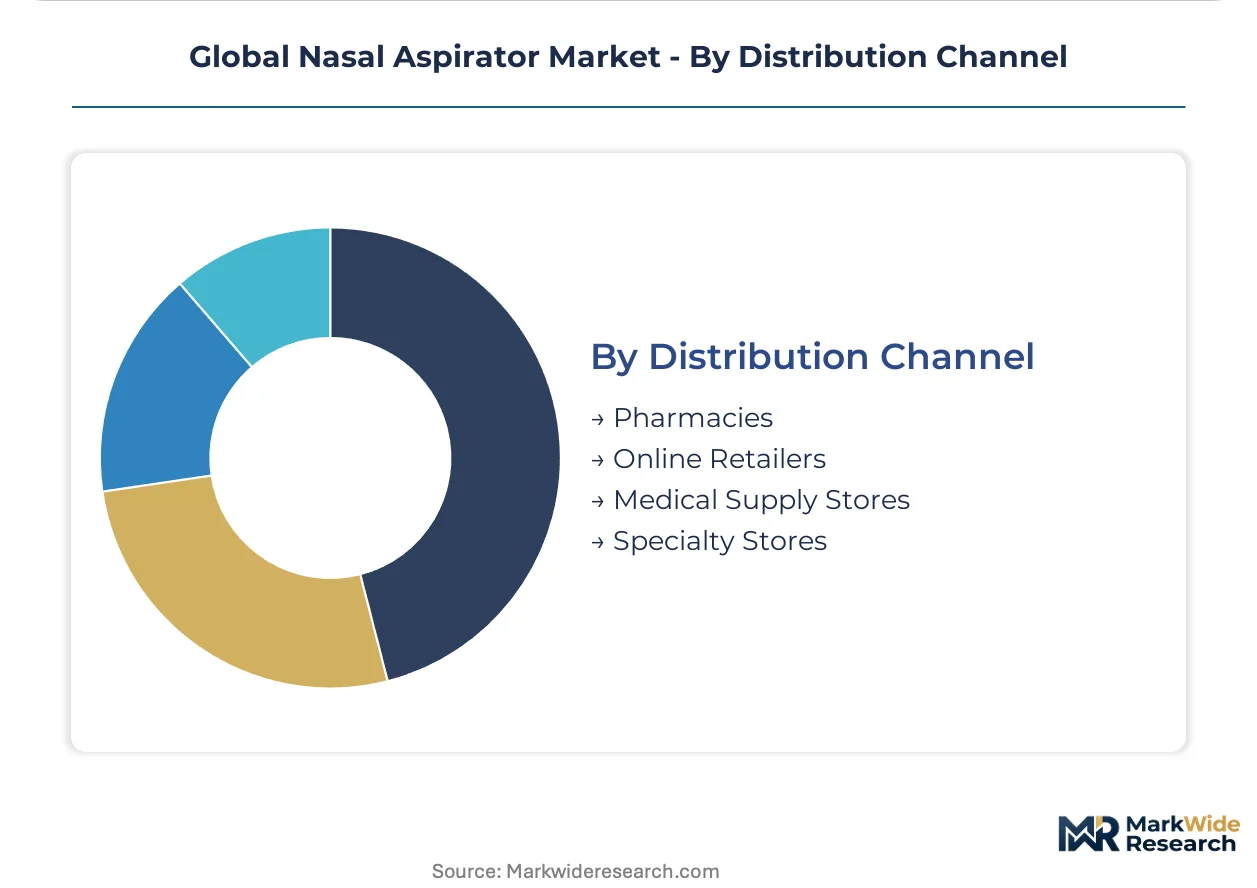
Channel economics reshape how each nasal aspirator category reaches its buyer. Pediatric clinics consolidate procurement through medical supply distributors, while millennial parents discover products through algorithm-driven online retail before pharmacy repurchase.
Product Type:
Pharmacy chains stock manual and bulb formats for impulse purchase, while electric variants flow through medical supply stores and direct-to-consumer platforms requiring education-heavy conversion funnels.
- Manual Aspirator:Hand-powered suction devices employing oral or bellows mechanisms generate negative pressure through physical effort. Demand concentrates in price-sensitive retail segments across India and Southeast Asia where healthcare access costs dominate purchase decisions. Bulb syringe substitution and low unit economics constrain margin expansion despite volume scale.
- Electric Aspirator:Motorized systems deliver consistent negative pressure between 50-150 mmHg with variable control interfaces. Pediatric clinics in Germany, Japan, and the United States standardize these for procedural reliability, compressing procurement cycles and forcing manual manufacturers into retail-only positioning. FDA Class II and EU MDR compliance requirements elevate material specifications and documentation burdens.
- Bulb Syringe:Single-piece rubber or silicone squeeze bulbs remain the default hospital discharge gift format. Low production costs sustain presence in emerging market maternity wards.
- Battery-Operated Aspirator:Portable electrics with rechargeable lithium-ion cells bridge home and clinic use cases. China's NMPA GB standard harmonization accelerates registration timelines for certified exporters.
Electric aspirators dominate installed base in clinical settings. Battery-operated variants are where expansion concentrates.
Application:
Margin profiles diverge sharply between institutional contracting and recurring consumer purchases, with consumable attachment models deepening lifetime value in homecare segments.
- Infant Care:Newborn respiratory hygiene applications demand biocompatible silicone construction and trauma-minimizing tip geometries. Direct-to-consumer discovery through parenting platforms in Scandinavia and North America displaces traditional pharmacy-first patterns, with subscription filter programs capturing recurring engagement.
- Pediatric Clinics:Standardized suction protocols in Germany and Japan drive electric aspirator procurement for ENT examination and congestion management. EU MDR clinical evaluation requirements extend documentation obligations to previously exempt manual categories, consolidating vendor relationships around MDR-compliant platforms.
- Homecare Use:Post-discharge congestion management by non-verbal patients spans infant through geriatric populations. Insurance reimbursement eligibility for premium device tiers expands with silicone airway construction adoption.
- Childcare Centers:Licensed facility requirements in multiple jurisdictions mandate medical-grade specifications for shared-use devices. Bulk procurement through medical supply distributors dominates this channel.
Pediatric clinics anchor institutional procurement volume. Homecare use is climbing the fastest as subscription models reshape purchase patterns.
End User:
Decision authority fragments across procurement committees, physician preference items, and direct consumer choice, each demanding distinct value demonstration and channel access.
- Hospitals:Maternity ward discharge protocols and NICU respiratory support drive bulk purchasing through group purchasing organizations. Standardization around electric systems for clinical reliability compresses manual device shelf space.
- ENT Specialists:Otolaryngology practices in the United States and Germany specify aspirator performance for post-surgical recovery protocols. Pharmacy network partnerships anchored by physician recommendation displace pure retail discovery.
- Pediatricians:Well-child visit recommendations influence parental purchase decisions across all product tiers. Clinic sample programs and branded educational materials shape brand preference before retail exposure.
- Home Users:Millennial parents research suction performance metrics through peer-reviewed parenting platforms before online purchase. Filter replacement subscription programs generate recurring revenue unavailable through transactional retail.
Home users represent the deepest addressable population. ENT specialists concentrate premium specification influence.
Distribution Channel:
Inventory ownership and customer acquisition cost structures determine which product tiers flow through which intermediaries, with digital-native channels capturing subscription economics unavailable to physical retail.
- Pharmacies:Community and chain pharmacies stock bulb syringes and manual aspirators for distress-driven purchase. NeilMed Pharmaceuticals anchors competitive positioning through this channel with specialist endorsement protocols.
- Online Retailers:Direct-to-consumer platforms enable discovery through algorithmic targeting of parenting demographics. NoseFrida leverages Scandinavian design heritage and channel control to sustain brand loyalty across European and North American markets.
- Medical Supply Stores:Institutional procurement and home medical equipment distribution concentrate electric aspirator sales with service infrastructure requirements. Pigeon Corporation dominates Asian retail shelves through local manufacturing scale and pediatric-focused packaging.
- Specialty Stores:Baby product boutiques and maternity-focused retailers curate aspirator assortments around design aesthetics and gift-appropriate packaging. Premium positioning supports margin capture despite lower inventory turns.
Pharmacies dominate transaction frequency. Online retailers are gaining share fastest through subscription attachment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electric aspirator systems to pediatric clinics across the United States and Japan, establishing a high-specification trade corridor that shapes procurement standards in both destination markets.
United States
FDA Class II powered device regulations elevate documentation burdens for electric aspirator entrants, compressing vendor pools around established compliance infrastructure. Pediatric clinic procurement standardization through group purchasing organizations concentrates volume among medical-grade suppliers. The Southeast region anchors domestic distribution networks serving maternity ward discharge protocols.
Germany
EU MDR clinical evaluation requirements for biocompatible polymers extend documentation obligations to manual device categories previously exempt. Pediatric ENT practices in Bavaria and North Rhine-Westphalia specify aspirator performance for post-surgical recovery protocols. Berlin-based notified bodies manage certification backlogs that reshape inventory prioritization across European distribution channels.
Japan
PMDA pharmaceutical affairs standards impose six-to-twelve month registration timelines that advantage JIS-compliant domestic manufacturers over foreign entrants. METI industrial policy supports pediatric device innovation clusters in the Kanto region. Tokyo-based procurement committees standardize electric aspirator specifications for clinic networks nationwide.
China
NMPA GB standard harmonization for infant care electronics accelerates registration timelines for battery-operated aspirators meeting certified safety benchmarks. Yangtze River Delta manufacturing clusters supply component assemblies to export-oriented finished goods producers. Shanghai distributors navigate dual carbon goals while scaling production of rechargeable lithium-ion powered systems.
India
CDSCO medical device rules increasingly align with international standards for powered suction devices, though manual bulb formats retain volume in price-sensitive segments. Metro hospital networks in Maharashtra and Karnataka present expansion opportunities for electric aspirator distributors establishing service infrastructure. BIS certification requirements shape import timelines for premium device tiers.
Global Nasal Aspirator Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities, creating tiered competitive dynamics where public company scale advantages confront private firm agility in navigating multi-jurisdiction certification cycles. The vendor base concentrates around three strategic archetypes: Scandinavian design-centric direct-to-consumer specialists, pharmaceutical-backed pharmacy channel anchors, and Asian manufacturing-scale retail distributors. Competitive moves center on M&A for regulatory expertise acquisition and geographic expansion through distributor partnership networks.
Within the design-centric direct-to-consumer tier, NoseFrida exemplifies channel control strategies that sustain brand loyalty across European and North American parenting communities. NeilMed Pharmaceuticals occupies a position representing pharmaceutical-backed distribution through specialist endorsement protocols. Pigeon Corporation anchors the Asian manufacturing-scale archetype with pediatric-focused retail presence. These three entities collectively illustrate how competitive positioning fragments across channel strategy rather than product specification alone.
| Leading Market Players |
|---|
| NoseFrida |
| NeilMed Pharmaceuticals |
| AViTA Corporation |
| Pigeon Corporation |
| NUK |
| Graco |
| Béaba |
| B.Well Swiss AG |
| Rumble Tuff |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for medical-grade silicone lock in supply access and price visibility for electric aspirator manufacturers serving pediatric clinics across Germany, Japan, and the United States. These contracts insulate premium tier producers from pharmaceutical-grade polymer spot market volatility while compressing margin flexibility for mid-market competitors dependent on shorter procurement cycles.
Pricing Analysis
Current-generation micro-pump electric aspirators command substantial premiums over prior-generation bulb syringes and basic manual devices. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA Class II certification status and biocompatible silicone construction grade. Cost compression in the manual bulb tier is intensifying because of low-cost Asian manufacturing scale and persistent substitution from emerging market maternity wards. Home users through direct-to-consumer channels exhibit lowest price sensitivity due to subscription filter replacement attachment, while institutional procurement committees in India and Southeast Asia drive hardest volume negotiations.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam and Shenzhen-Los Angeles trade lanes elevate inbound logistics costs for battery-operated aspirator assemblies sourced from Yangtze River Delta manufacturing clusters. Component concentration centers on China for lithium-ion cells and precision micro-pumps, Japan for medical-grade silicone formulations, and Germany for pneumatic control systems. Single-source vulnerability in pharmaceutical-grade polymer feedstock creates exposure to EU MDR biocompatibility mandate compliance delays. Distribution runs through medical supply distributors for institutional procurement and direct-to-consumer platforms for homecare subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story justified by pediatric clinic standardization of electric aspirator equipment across underpenetrated metro hospital networks in India and Southeast Asia.
For Market Incumbents: Consolidate regulatory affairs capabilities through targeted acquisition of CE marking and PMDA submission specialists to compress multi-jurisdiction certification parallelism timelines. Deepen backward integration into medical-grade silicone compounding to defend margin position against pharmaceutical-grade polymer input volatility. Channel control through exclusive distributor partnerships in Asian retail shelves remains essential to counter Pigeon Corporation's manufacturing-scale dominance.
For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-track for novel suction control architectures offers expedited pathway into United States pediatric clinic procurement. White-space opportunity concentrates in India's metro hospital networks where electric aspirator service infrastructure remains underdeveloped. ENT specialist endorsement protocols through pharmacy network partnerships provide highest-conversion go-to-market angle against pure retail discovery models.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors regulatory compliance infrastructure over raw manufacturing scale. Long-term viability across the analysis window hinges on capturing recurring consumable revenue streams through filter replacement subscription models. Acquisition target archetype: mid-cap electric aspirator specialists with existing FDA Class II clearance and direct-to-consumer channel control. Signal to watch: notified body backlog durations for EU MDR clinical evaluation submissions as inflection indicator for European market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements extend documentation obligations to manual device categories previously exempt. |
| Hospital System Partnership | Pediatric clinic procurement standardization through group purchasing organizations concentrates volume among medical-grade suppliers. |
| Software Companion Development | Connected aspirator platforms enable suction protocol logging for ENT specialist reimbursement documentation. |
| Reimbursement Strategy | Insurance eligibility for premium device tiers expands with biocompatible silicone airway construction adoption. |
| Geographic Manufacturing Footprint | JIS-compliant domestic production in Japan circumvents PMDA registration timelines that delay foreign entrants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body certification databases, and PMDA pharmaceutical affairs registration records. Pediatricians, hospital purchasing committee members, biomedical engineers specializing in respiratory devices, and GPO contracts managers provided structured input across the United States, Germany, and Japan. Secondary validation drew from hospital procurement databases, medical device trade customs records, and CMS Medicare durable medical equipment claims data. Bottom-up unit economics modeling triangulated against top-down market size reconciliation.
Segmentation dimensions modeled span product type architecture, application setting, end-user decision authority, and distribution channel structure across the projection horizon. Analytical framework incorporated electric aspirator adoption curves in pediatric clinics, manual bulb substitution persistence in emerging markets, and subscription filter replacement attachment rates in direct-to-consumer channels. CAGRs derived from regression analysis against historical procurement standardization timelines and regulatory compliance cycle durations.
Underlying assumptions cover continued EU MDR biocompatibility mandate enforcement, stable lithium-ion battery safety standard harmonization, and sustained pediatric clinic electric aspirator procurement consolidation, with deviation risk concentrated in PMDA registration timeline extensions and pharmaceutical-grade polymer supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Medical Instruments Disinfection Market