
 Hemostasis Products Market | 2026-2036
Hemostasis Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostasis Products Market Analysis
Collagen-based matrices is shifting toward oxidized regenerated cellulose platforms across the hemostasis products landscape, altering raw material sourcing and unit economics for manufacturers. Johnson & Johnson leverages its broad surgical portfolio to sustain dominance in topical hemostat distribution. Baxter International anchors its position through specialized concentration in fibrin sealant technology. CSL Behring differentiates via plasma-derived biologic hemostats with established cold-chain infrastructure.
Hemostasis products encompass devices, agents, and sealants engineered to arrest bleeding through mechanical obstruction, physiologic clot promotion, or tissue adhesion, typically incorporating collagen, cellulose, gelatin, or thrombin-active proteins in sterile formats for intraoperative deployment. Their primary purpose centers on reducing blood loss, minimizing transfusion requirements, and improving surgical field visibility across invasive procedures. Topical hemostats occupy the largest revenue pool given universal applicability across surgical disciplines, while biological agents represent the fastest-expanding segment driven by recombinant thrombin and fibrin concentrate adoption. Surgical sealants command premium positioning in cardiac and neurosurgical applications where precision sealing justifies higher procurement costs.
FDA premarket clearance requirements under 21 CFR 878.4490 shape absorbable hemostat development timelines and clinical evidence burdens for US market entrants. The EU Medical Device Regulation (MDR) and CE marking obligations enforce biocompatibility and post-market surveillance standards across European distribution channels. Japan's PMDA reviews hemostatic agents under pharmaceutical frameworks, creating distinct registration pathways versus device-classified alternatives. Stakeholders must monitor evolving reimbursement thresholds for biologic hemostats versus synthetic alternatives as payors recalibrate coverage based on comparative effectiveness data.
Market Dynamics
The transition from collagen-based matrices to oxidized regenerated cellulose platforms is restructuring raw material sourcing economics and compressing manufacturing margins across the hemostasis products supply base.
Growth Catalysts
- FDA 21 CFR 878.4490 Streamlining:The updated premarket notification pathway for absorbable hemostats is compressing product clearance timelines and reducing clinical evidence burdens for US market entrants.
- General Surgery Expansion:Tertiary hospitals are scaling advanced hemostatic solution adoption across expanding surgical departments, creating concentrated demand pull from high-volume procedural centers.
- Recombinant Thrombin Maturation:Biologically active protein engineering is displacing plasma-derived alternatives in cardiac and neurosurgical applications where clot precision commands premium positioning.
Market Restraints
- Cold-Chain Infrastructure Concentration:Plasma-derived biologic hemostats require specialized temperature-controlled distribution networks that concentrate supply risk in limited logistics corridors.
- EU MDR Compliance Burden:The Medical Device Regulation's enhanced biocompatibility and post-market surveillance standards are extending certification timelines and elevating documentation costs for European distribution.
- Synthetic Polymer Substitution:Gelatin and polyethylene glycol sealants are capturing price-sensitive procedural volumes in orthopedic and general surgical applications.
Strategic Opportunities
- Japan Pharmaceutical Pathway Differentiation:PMDA's classification of hemostatic agents under pharmaceutical frameworks creates distinct registration moats versus device-classified competitors.
- Fibrin Sealant Cardiac Specialization:Precision sealing requirements in open-heart and minimally invasive cardiac procedures justify premium procurement economics and long-term supply contracts.
- Blood Conservation Protocol Mandates:Hospital accreditation standards emphasizing transfusion reduction are embedding hemostasis products into perioperative care bundles.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel matrix compositions are extending development cycles and elevating preclinical expenditure.
- Reimbursement Recalibration Friction:Payor comparative effectiveness reviews of biologic versus synthetic hemostats are creating coverage uncertainty and procurement hesitation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostasis Products Market |
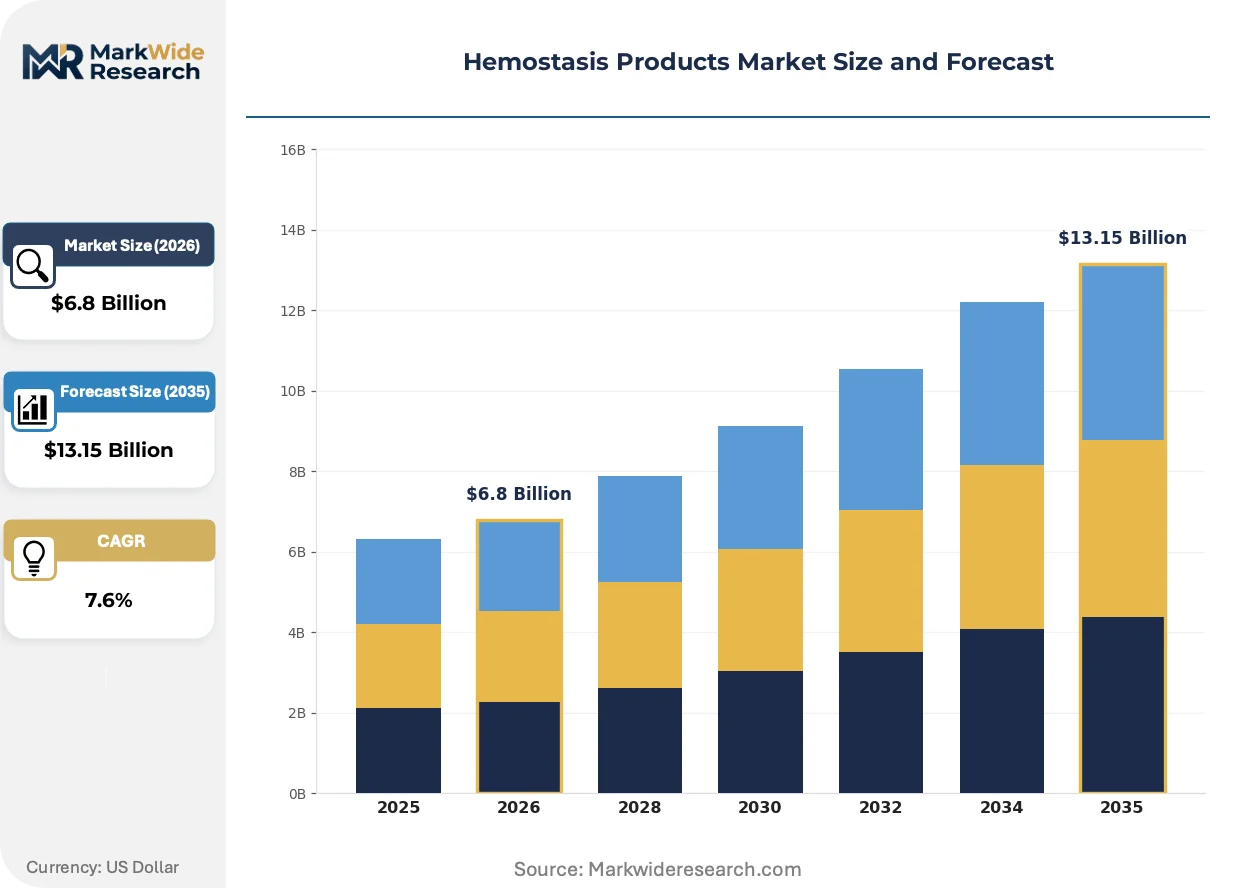
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Hemostats, Adhesive Agents, Biological Agents, Surgical Sealants Delivery Mode: Injectable, Sprays, Pads, Gels End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Emergency Services Application: Cardiac Surgery, Trauma Care, Neurosurgery, Orthopedic Surgery |
| Companies Covered | Johnson & Johnson, Baxter International, Medtronic plc, Pfizer, Abbott Laboratories, CSL Behring, Becton Dickinson (BD), Grifols, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostasis Products Market Emerging Trajectories
Convergence between mechanical obstruction platforms and physiologic clot promotion is dissolving traditional category boundaries and enabling multifunctional hemostatic deployment.
Oxidized regenerated cellulose matrices is unifying mechanical hemostasis with intrinsic clotting cascade activation in single-application formats. Cardiac surgery departments at tertiary medical centers are adopting these hybrid platforms at accelerated replacement rates for standalone collagen sponges. The technology is unifying previously separate product categories into consolidated procurement bundles that compress vendor management overhead.
Japan's PMDA maintains pharmaceutical classification for thrombin-active hemostats while permitting device pathways for mechanical alternatives, creating divergent evidence requirements across product categories. This regulatory bifurcation is segmenting development portfolios and concentrating biologic investments in manufacturers with established cold-chain capabilities. European distributors are responding by establishing separate regulatory affairs functions for pharmaceutical versus device-classified portfolios.
Hospital value analysis committees are consolidating hemostasis product selection authority from individual surgeons to centralized procurement functions. This concentration is displacing traditional distributor relationships with direct manufacturer contracts and volume-based pricing frameworks. The United States exhibits the most pronounced centralization, with integrated delivery networks standardizing hemostat formularies across multi-hospital systems.
Hemostasis Products Market Segmentation
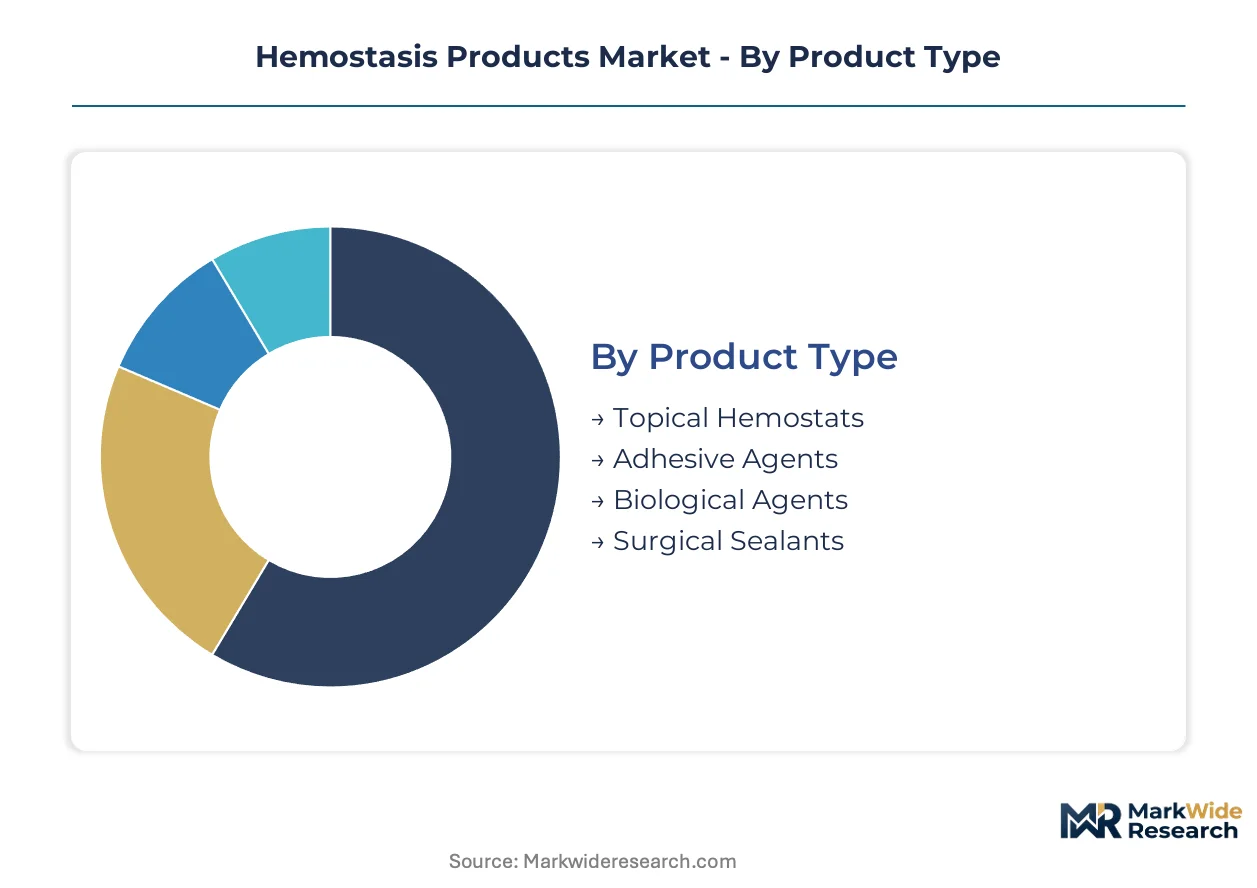
Hemostasis product manufacturers configure their supply chains around distinct technical specifications and end-use requirements. Each segmentation dimension reveals different pressure points for margin defense and volume capture.
Product Type:
Supply concentration for active ingredients varies sharply across product categories, with plasma-derived biologics tethered to limited cold-chain corridors while synthetic matrices source from distributed chemical processors.
- Topical Hemostats:Mechanical platforms incorporating oxidized regenerated cellulose, collagen, or gelatin matrices that activate through physical absorption and surface coagulation. Demand concentrates in United States tertiary hospitals where blood conservation protocols mandate universal availability across general surgery suites; procurement committees favor these for their shelf stability and broad applicability.
- Biological Agents:Thrombin-active proteins and fibrin concentrates derived from plasma or recombinant sources that accelerate physiologic clotting cascades. Cardiac and neurosurgical departments in Germany and Japan drive adoption where precision clot formation justifies premium positioning and cold-chain investment.
- Adhesive Agents:Synthetic polymer platforms including cyanoacrylate and polyethylene glycol formulations that bond tissue surfaces through chemical cross-linking. Orthopedic applications in price-sensitive markets favor these for rapid deployment and lower per-procedure cost.
- Surgical Sealants:Dual-component systems combining fibrinogen and thrombin for active sealing of suture lines and anastomoses. Cardiac surgery centers in Japan command the steepest procurement premiums for these applications.
Today's leader: Topical Hemostats. Tomorrow's challenger: Biological Agents.
Delivery Mode:
Manufacturing scale and regulatory pathway complexity diverge across delivery formats, with sterile fill-finish requirements for injectables contrasting against simpler conversion processes for pads.
- Injectable:Liquid formulations delivered via syringe for deep wound beds and laparoscopic ports, requiring aseptic processing and particulate control. Cardiac surgery departments in United States academic medical centers standardize these for internal bleeding control.
- Sprays:Aerosolized or pump-dispersed systems for broad surface coverage in open procedures. Trauma bays in German emergency departments favor these for rapid deployment over large wound areas.
- Pads:Pre-formed matrices in standardized dimensions for direct application to bleeding surfaces. General surgery volume in United States community hospitals anchors demand for these commoditized formats.
- Gels:Viscous formulations conforming to irregular tissue topography, particularly valued in neurosurgical applications where mechanical pressure must be minimized.
Injectable formats command the steepest expansion trajectory as minimally invasive procedural volume climbs.
End User:
Procurement authority concentration varies by facility type, with integrated delivery networks centralizing hemostat selection for hospitals while ambulatory centers retain surgeon-driven purchasing.
- Hospitals:Multi-specialty institutions with centralized value analysis committees and formulary standardization across surgical departments. United States integrated delivery networks and German hospital chains exhibit the most pronounced procurement consolidation.
- Ambulatory Surgical Centers:Focused facilities performing same-day procedures with cost-constrained supply budgets and limited storage infrastructure. Orthopedic-focused centers in Japan represent concentrated demand for synthetic hemostats.
- Specialty Clinics:Single-discipline practices including dental surgery and dermatology with modest volume but specific formulation requirements.
- Emergency Services:Pre-hospital and trauma bay applications prioritizing rapid deployment and minimal training burden. Military and civilian trauma systems in the United States drive development of field-stable formats.
Hospital procurement concentration is accelerating vendor consolidation, while ambulatory centers remain fragmented.
Application:
Clinical outcome requirements and reimbursement intensity create tiered demand profiles across surgical specialties, with cardiac and neurosurgery supporting premium positioning unavailable in general surgery.
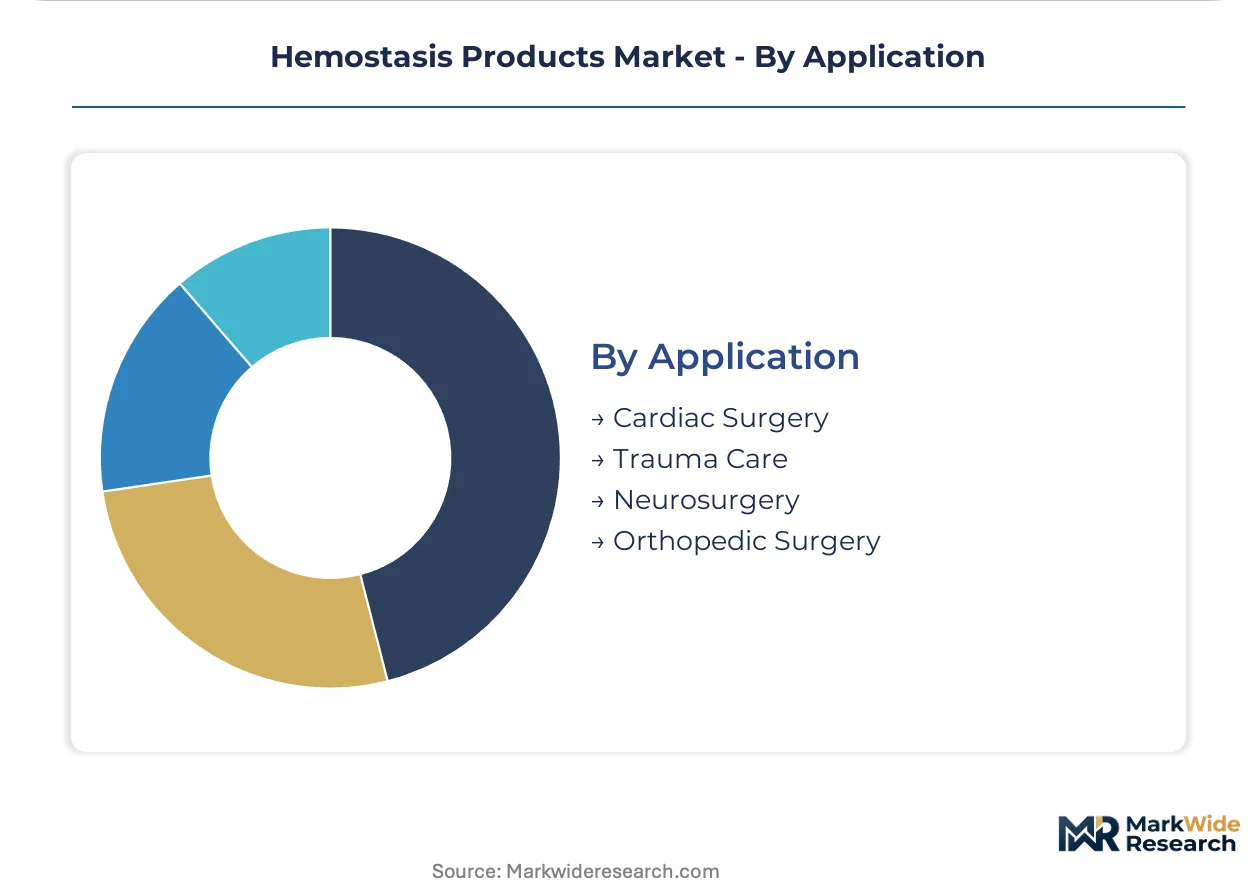
- Cardiac Surgery:Open-heart and minimally invasive procedures requiring precision hemostasis around anticoagulated patients and vascular anastomoses. Tertiary centers in Japan and Germany sustain premium pricing for fibrin sealants and recombinant thrombin.
- Neurosurgery:Cranial and spinal procedures where tissue adhesion must not transmit pressure to neural structures. Academic medical centers in the United States drive adoption of gelatin-thrombin combinations.
- Orthopedic Surgery:Joint replacement and trauma fixation with substantial blood loss potential but lower precision requirements. Volume concentrates in United States ambulatory surgery centers and German hospital orthopedics departments.
- Trauma Care:Emergency surgical control of hemorrhage in unstable patients, spanning pre-hospital through operative phases. Military medical research in the United States accelerates development of rapid-acting formats.
Cardiac Surgery sustains the highest margin pool. Orthopedic Surgery offers the largest addressable volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johnson & Johnson's surgical portfolio concentration in New Brunswick anchors North American hemostasis product distribution networks. Tertiary hospital systems in the United States, Germany, and Japan drive demand concentration through blood conservation protocol mandates and expanding cardiac surgery volumes.
United States
FDA's 21 CFR 878.4490 premarket notification pathway compresses absorbable hemostat clearance timelines for domestic manufacturers. Integrated delivery networks in the Southeast and Midwest standardize hemostat formularies across multi-hospital systems, displacing traditional distributor relationships with direct manufacturer contracts. Academic medical centers in Boston and Houston drive adoption of recombinant thrombin formulations.
Germany
EU MDR biocompatibility and post-market surveillance standards extend certification timelines for European distribution channels. Hospital chains in North Rhine-Westphalia and Bavaria concentrate procurement authority through centralized value analysis committees. Berlin-based regulatory affairs functions manage separate pharmaceutical versus device-classified portfolios under EMA guidance.
Japan
PMDA pharmaceutical classification for thrombin-active hemostats creates distinct registration moats versus device-classified competitors. Cardiac surgery departments in Tokyo and Osaka sustain premium procurement economics for fibrin sealants. Cold-chain infrastructure investments concentrate in Kanto and Kansai regions for plasma-derived biologic distribution.
United Kingdom
NHS blood conservation mandates embed hemostasis products into perioperative care bundles across England's hospital trusts. London and Manchester surgical hubs drive demand for oxidized regenerated cellulose matrices in general surgery applications. MHRA post-Brexit regulatory frameworks diverge from EU MDR compliance requirements.
India
CDSCO pharmaceutical regulation of active hemostatic agents creates tiered registration pathways for domestic and imported products. Maharashtra and Karnataka medical device clusters expand local manufacturing of gelatin-based mechanical hemostats. Delhi-NCR tertiary hospitals drive adoption of cost-constrained synthetic polymer sealants in orthopedic applications.
Hemostasis Products Market Vendor Landscape
Global majors compete with regional champions across regulatory pathway expertise and cold-chain infrastructure scale. The vendor base stratifies into three tiers: diversified surgical conglomerates with broad distribution networks, plasma fractionation specialists with captive biologic supply, and focused hemostat developers with matrix formulation IP. Strategic archetypes include full-spectrum surgical suppliers, biologic hemostat pure-plays, and synthetic sealant innovators. Competitive moves concentrate on M&A for regulatory asset accumulation and capacity expansion in aseptic fill-finish facilities.
Within the diversified surgical supplier tier, Johnson & Johnson and Baxter International anchor competitive positioning through distribution breadth and fibrin sealant specialization respectively. CSL Behring occupies the biologic hemostat pure-play position, leveraging plasma-derived protein expertise and established temperature-controlled logistics networks. These three entities exemplify how regulatory pathway mastery and supply chain configuration determine tier placement in hemostasis product markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| Medtronic plc |
| Pfizer |
| Abbott Laboratories |
| CSL Behring |
| Becton Dickinson (BD) |
| Grifols |
| Integra LifeSciences |
| Others |
Supply Flow & Price Mechanics
Family-owned gelatin processors in India and private-equity-rolled-up cellulose converters in Europe anchor mid-tier supply for mechanical hemostats, creating pricing discipline through consolidated sourcing pools that resist spot-market volatility. Their ownership structures prioritize long-term contract stability over quarterly margin extraction, compressing procurement leverage for hospital buyers while insulating premium-tier biologic suppliers from direct price competition.
Pricing Analysis
Input-cost pass-through from oxidized regenerated cellulose feedstock and plasma-derived thrombin concentrates shapes tiered pricing across product categories. Three-tier pricing structure across premium, standard, and economy levels separates recombinant thrombin formulations from collagen sponges and synthetic polymer sealants. Pricing pressure stems from EU MDR compliance costs elevating European certification expenses. Orthopedic surgery centers exhibit highest price sensitivity, while cardiac surgery departments tolerate premium positioning for precision sealing performance.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR 820 quality system certifications gate supplier qualification for sterile hemostat manufacturing, concentrating viable production in the United States, Germany, and Japan. Raw material dependencies center on bovine collagen, cotton-derived cellulose, and human plasma fractionation. Single-source vulnerability runs through limited plasma collection networks for biologic hemostats. Distribution runs through specialized medical-surgical distributors and direct hospital contracts for high-volume integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hemostasis products rests on cold-chain cost rationalization for biologics and premium-tier adoption of recombinant thrombin displacing plasma-derived alternatives.
For Market Incumbents: Deepen backward integration into plasma collection networks to secure biologic hemostat supply against cold-chain concentration risk. Expand aseptic fill-finish capacity in United States Southeast corridor to capture FDA 21 CFR 878.4490 streamlined clearance benefits. Fortify formulary lock-in through bundled procurement contracts with integrated delivery networks. For New Entrants and Emerging Players: Begin with oxidized regenerated cellulose matrix development for price-sensitive orthopedic applications in Indian and Southeast Asian markets. Target ambulatory surgical centers in Japan's Kansai region where device-classified pathways reduce regulatory burden. Pursue white-label manufacturing partnerships with established European distributors lacking sterile processing capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among synthetic sealant developers with matrix formulation IP but underdeveloped regulatory dossiers. Long-term viability centers on dual-pathway capability spanning pharmaceutical and device classification frameworks. Watch PMDA guidance harmonization signals as inflection indicator for Japan market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled logistics investments in Kanto and Kansai regions secure plasma-derived biologic distribution for cardiac surgery centers. |
| EU MDR Certification Pathway | Enhanced biocompatibility documentation accelerates CE marking timelines for oxidized regenerated cellulose platforms entering German hospital chains. |
| Recombinant Thrombin Pipeline | Biologically active protein engineering displaces plasma-derived alternatives in United States academic medical center cardiac departments. |
| Hospital System Partnership | Direct manufacturer contracts with Southeast integrated delivery networks displace traditional distributor relationships and standardize formularies. |
| Regulatory Asset Accumulation | M&A targeting specialized hemostat developers with established PMDA pharmaceutical registrations creates moats against device-classified competitors. |
Methodological Framework
Multiple input streams — surgical supply chain managers, hospital value analysis committee members, regulatory affairs directors at hemostat manufacturers, and plasma fractionation procurement leads — were reconciled against FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval records, and hospital GPO contract repositories. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue disclosures across the analysis window.
Historical shipment data cross-referenced against expert panel inputs on recombinant thrombin adoption curves and oxidized regenerated cellulose replacement rates. Segmentation modeling incorporated product type, delivery mode, end-user facility tier, and application specialty dimensions across the projection horizon. CAGRs derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules.
Several conditions sit outside the modeled scope, including unforeseen FDA guidance revisions, plasma supply disruptions from donor pool contraction, and radical synthetic polymer breakthroughs displacing biologic mechanisms. A model refresh is warranted upon material change in PMDA pharmaceutical-device classification boundary interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
South America Syringe Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Lab Trays Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Medical Bags Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Global Chromatography Syringes Market