
 Anesthesia Disposables Market | 2026-2036
Anesthesia Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Disposables Market Analysis
MDR is pivoting the cost-of-entry calculus for anesthesia disposables sold into European healthcare systems. Teleflex Incorporated leverages its vertically integrated manufacturing footprint to sustain margin resilience under stricter conformity assessment timelines. Ambu A/S anchors its competitive position through single-use endoscopy and anesthesia portfolios that sidestep reprocessing liability. Medtronic plc dominates electrosurgical and airway management adjacencies, extending its reach through bundled disposable contracts with IDNs.
Anesthesia disposables encompass single-patient-use devices—including breathing circuits, laryngeal masks, and intravenous sets—manufactured from medical-grade polymers, silicone, or PVC and sterilized via ethylene oxide or gamma irradiation to maintain aseptic delivery of inhalational or intravenous anesthetics. The product type dimension shows breathing circuits occupying the largest revenue pool due to per-procedure replacement mandates, while laryngeal masks represent the fastest-expanding category as supraglottic airway techniques displace endotracheal intubation in appropriate cases. By end user, hospitals command the dominant share of procurement volume, though surgical centers are capturing disproportionate growth as outpatient migration accelerates.
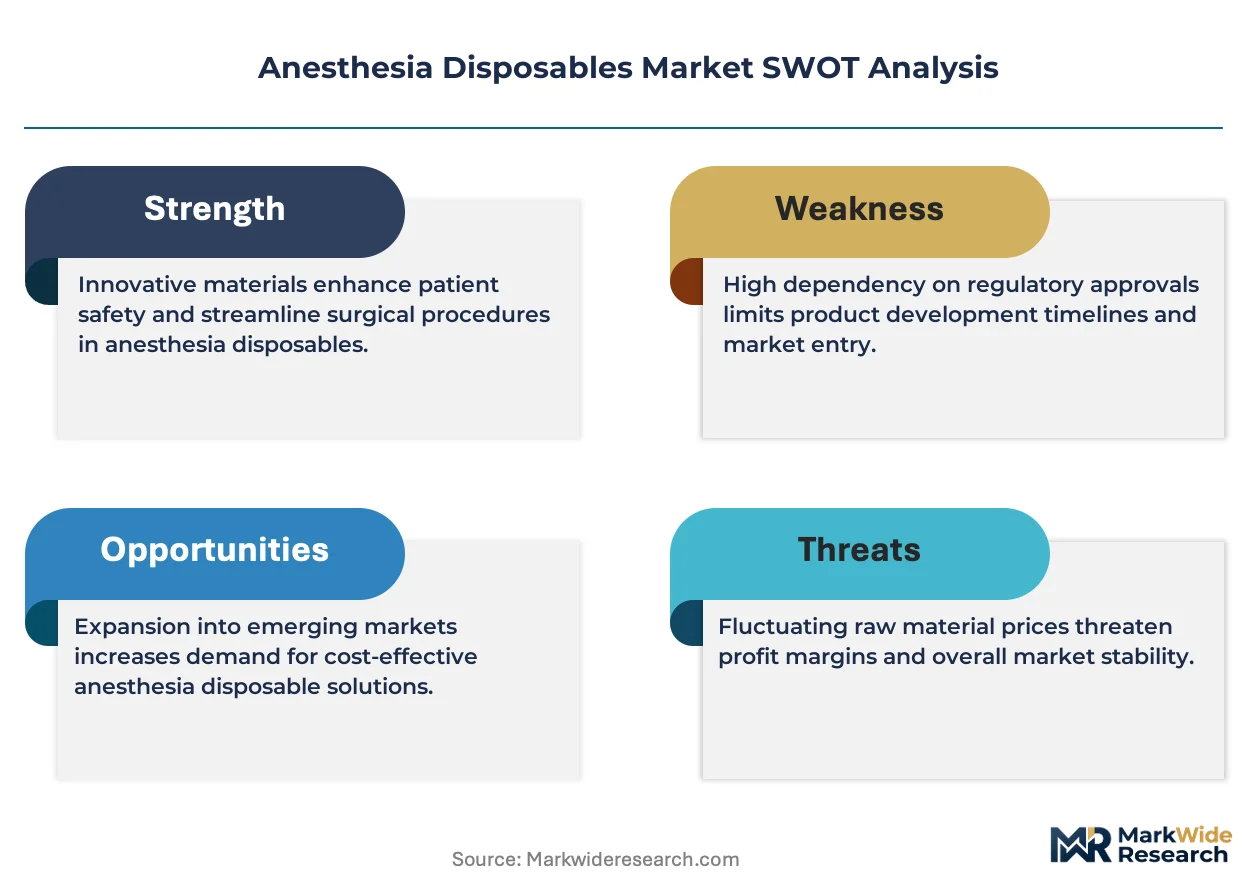
FDA 510(k) clearance pathways, the EU MDR's heightened clinical evidence requirements, and ISO 13485 quality management standards collectively shape product development timelines and market access trajectories for disposable anesthesia device manufacturers. These frameworks elevate barriers for non-compliant suppliers while rewarding firms with established regulatory infrastructure and post-market surveillance capabilities. Stakeholders must monitor how CMS reimbursement shifts for ambulatory surgery and evolving EPA sterilization emissions rules will reshape supplier cost structures and sourcing geography.
Market Dynamics
Single-use sterility mandates from the FDA and EU MDR are compressing reprocessing economics while forcing suppliers to absorb ethylene oxide sterilization cost volatility. This regulatory convergence with hospital consolidation into integrated delivery networks is restructuring procurement leverage and margin allocation across the value chain.
Growth Catalysts
- EU MDR clinical evidence requirements:Elevated conformity assessment timelines favor incumbent manufacturers with established quality management systems, accelerating supplier rationalization.
- Ambulatory surgical center expansion:CMS reimbursement shifts toward outpatient settings concentrate demand for compact, single-patient anesthesia circuits designed for rapid turnover.
- Silicone material substitution:Premium polymer adoption in laryngeal masks reduces allergic response rates and supports premium positioning in pediatric and high-risk patient segments.
Market Restraints
- Ethylene oxide sterilization capacity concentration:EPA emissions enforcement has shuttered multiple US contract sterilizers, creating supply bottlenecks for gamma-irradiation alternatives.
- PVC resin price volatility:Feedstock exposure to petrochemical markets compresses margin predictability for standard breathing circuit manufacturers.
- Reprocessing liability thresholds:Mal litigation risk in endotracheal tube reprocessing sustains artificial demand for single-use alternatives despite equivalent clinical performance.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives enable cost-competitive export positioning into Southeast Asian and Middle Eastern procurement networks.
- Closed-loop anesthesia delivery systems:Integration of scavenging technology with disposable circuits addresses occupational exposure regulations in European operating theaters.
- Direct-to-hospital e-procurement platforms:IDN centralized purchasing portals disintermediate traditional distributor markups for high-volume consumable categories.
Industry Challenges
- ISO 13485 auditor scarcity:Certification backlog delays market entry for emerging manufacturers targeting MDR compliance deadlines.
- Legacy ERP integration:Hospital supply chain systems require manual bridging to automate disposable consumption tracking and par-level replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Disposables Market |
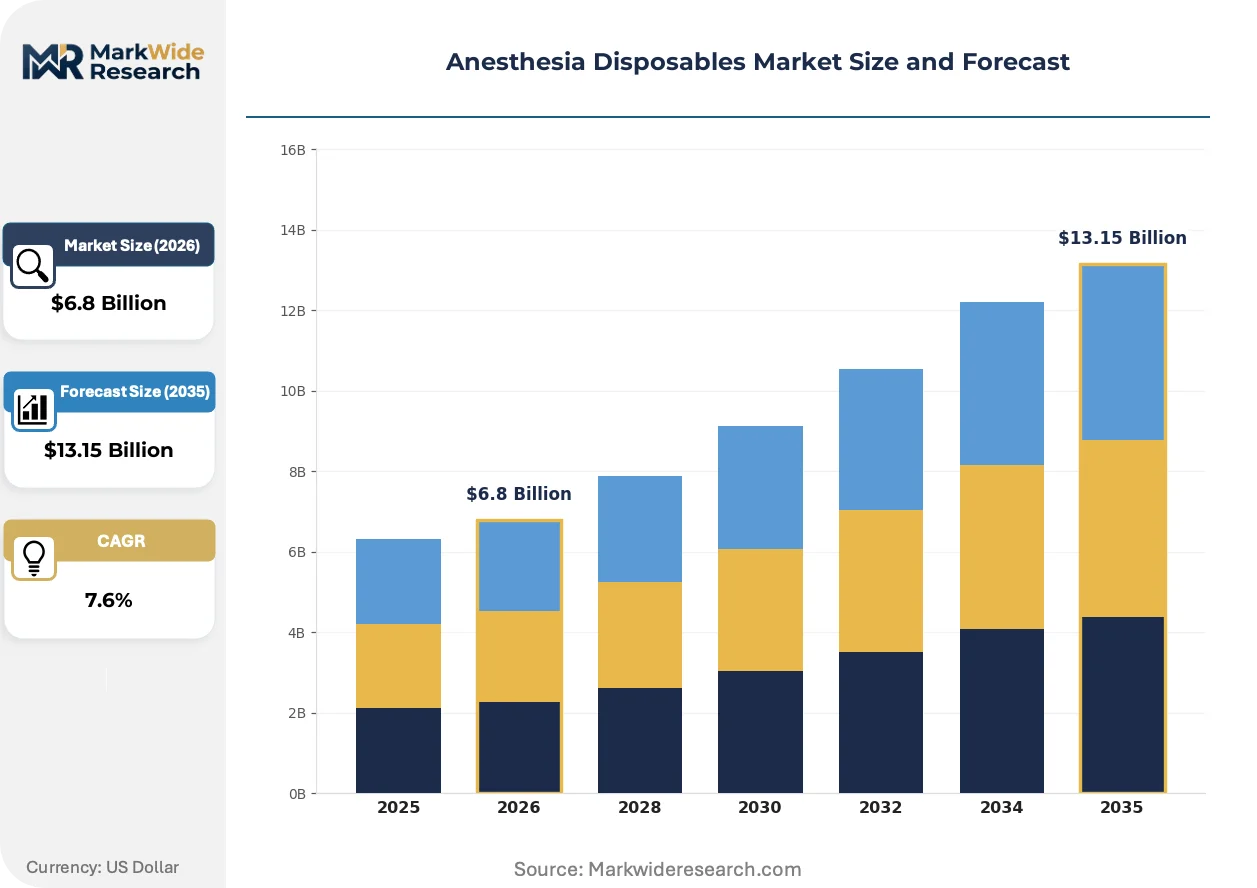
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breathing Circuits, Anesthesia Masks, Intravenous Sets, Laryngeal Masks End User: Hospitals, Surgical Centers, Specialty Clinics, Emergency Departments Delivery Mode: Single-Use, Reusable, Pre-Sterilized, Packaged Solutions Application: Surgery, Pain Management, Dental Procedures, Critical Care |
| Companies Covered | Teleflex Incorporated, Ambu A/S, Medtronic plc, Draegerwerk AG and Co. KGaA, Intersurgical Ltd., Becton, Dickinson and Company, Smiths Medical, Philips, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Disposables Market Emerging Trajectories
Material science convergence with digital traceability requirements is redefining how anesthesia disposables are specified, sourced, and monitored through their clinical lifecycle. Suppliers now compete on integrated data layers rather than unit cost alone.
Anti-microbial silver-ion integration into silicone laryngeal masks is unifying infection control and airway management functions into single-use platforms. Surgical centers in Germany and the Netherlands are standardizing these devices for outpatient ENT procedures. The technology is unifying what were previously separate capital equipment and disposable procurement decisions.
The EU MDR's Unique Device Identification mandates are forcing serialization infrastructure investments across European supply chains. Manufacturers must now maintain post-market surveillance databases linking specific lot numbers to adverse event reports. Breathing circuit suppliers serving the French and Italian markets face the steepest compliance cost escalation due to national notification system fragmentation.
Consolidated IDN contracting is compressing vendor rosters from twelve-plus suppliers to three or four per category. United States health systems now demand guaranteed fill rates and consignment inventory arrangements that transfer working capital burden upstream. This concentration is most visible in the Southeast and Midwest, where regional systems like HCA and CommonSpirit enforce standardized formularies across fifty-plus facilities.
Anesthesia Disposables Market Segmentation
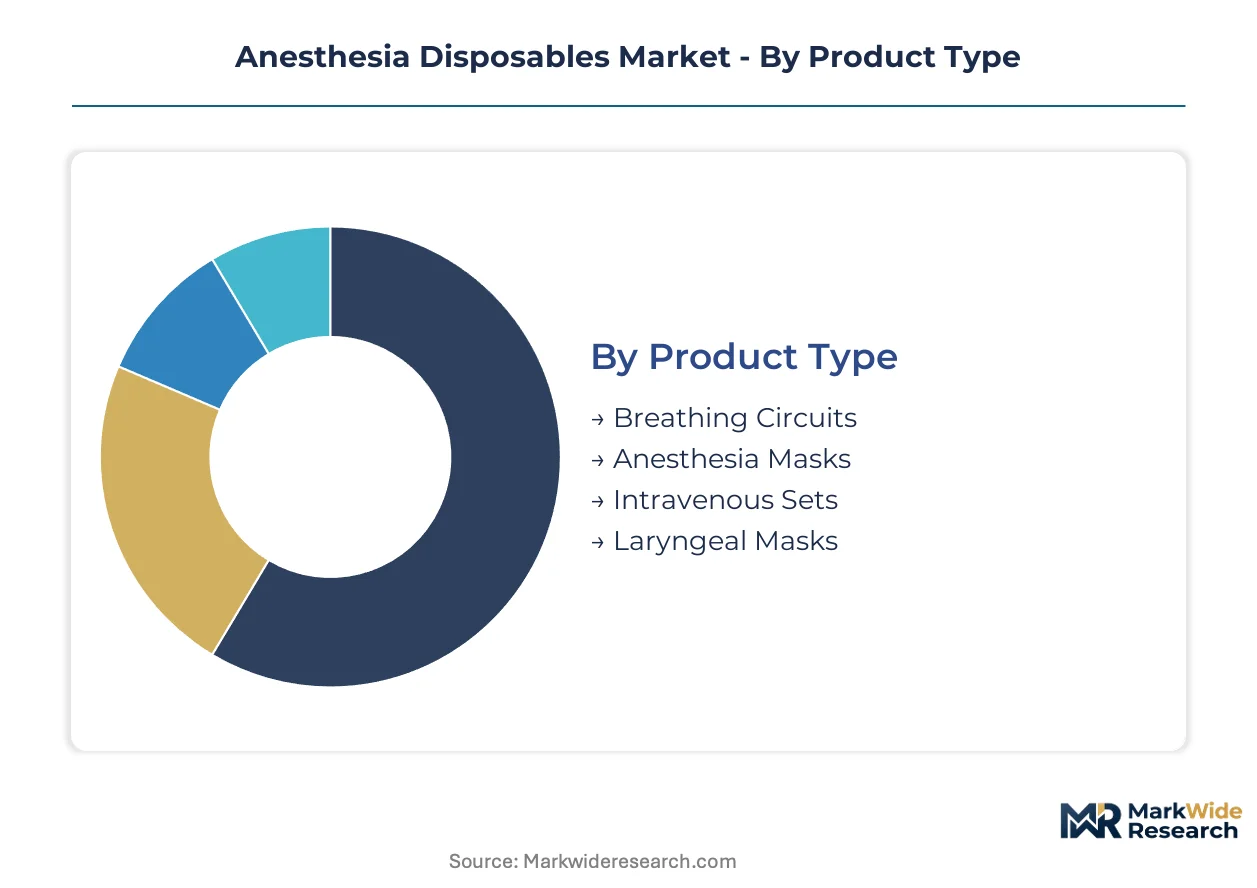
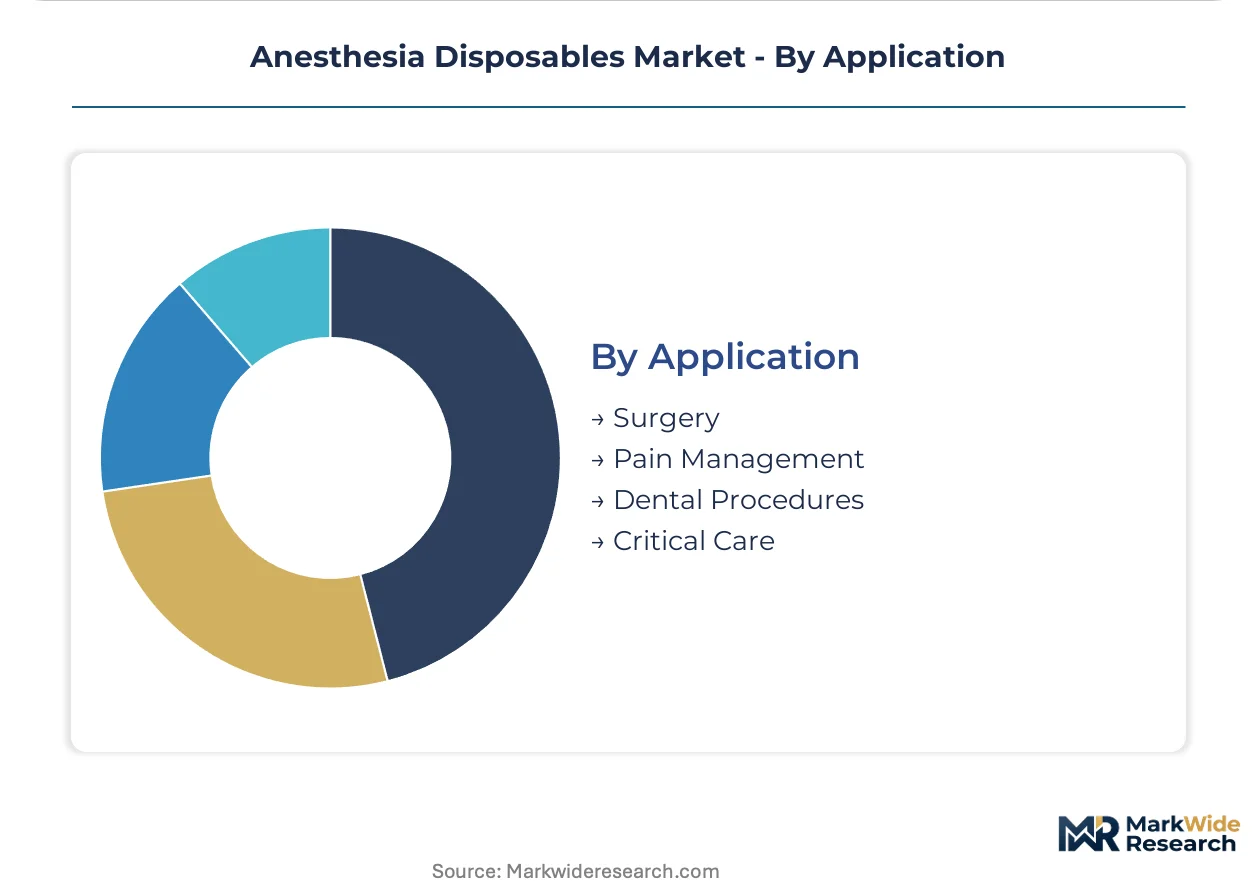
Anesthesia disposables segment along four functional dimensions that reshape procurement economics and supplier qualification requirements. Product type determines sterilization infrastructure needs, while end user concentration dictates contract structure and inventory terms.
Product Type:
Material composition and replacement frequency separate buyers into distinct cost tiers with varying margin sensitivity.
- Breathing Circuits:Medical-grade polymer tubing assemblies with bacterial filters and connectors, sterilized via ethylene oxide or gamma irradiation. Demand clusters in United States integrated delivery networks where per-procedure replacement mandates create predictable high-volume procurement.
- Laryngeal Masks:Silicone or PVC supraglottic airway devices with inflatable cuffs and gastric access ports. German and Dutch surgical centers are standardizing these for outpatient ENT procedures as supraglottic techniques displace endotracheal intubation in appropriate cases.
- Anesthesia Masks:Facial interface devices in standard and pediatric sizes, manufactured from transparent PVC or silicone.
- Intravenous Sets:Needle-free injection ports and drip chambers for anesthetic agent administration.
Breathing circuits lead volumes today; laryngeal masks are climbing the fastest.
End User:
Facility scale and case mix determine whether buyers prioritize unit economics or total cost of ownership.
- Hospitals:Multi-specialty institutions with captive sterilization departments and 24-hour anesthesia coverage. United States health systems like HCA and CommonSpirit enforce standardized formularies across fifty-plus facilities, consolidating vendor rosters to three or four per category.
- Surgical Centers:Ambulatory facilities requiring compact, single-patient circuits for rapid turnover. CMS reimbursement shifts toward outpatient settings are accelerating demand for pre-configured disposable kits.
- Specialty Clinics:Pain management and dental anesthesia providers with lower procedure volumes.
- Emergency Departments:Trauma and resuscitation settings requiring immediate airway access capabilities.
Hospitals dominate procurement volume; surgical centers show the steepest expansion trajectory.
Delivery Mode:
Sterility assurance level and packaging configuration drive differentiation between premium and standard tiers.
- Single-Use:Gamma-irradiated or ethylene-oxide-sterilized devices in individual peel-pouch packaging. FDA renewed emphasis on single-use sterility protocols is pivoting supplier qualification requirements toward lot-level traceability systems.
- Reusable:Autoclavable silicone devices requiring hospital reprocessing infrastructure. Mal litigation risk sustains artificial demand for single-use alternatives despite equivalent clinical performance.
- Pre-Sterilized:Bulk-sterilized components for kit assembly by third-party packagers.
- Packaged Solutions:Procedure-specific bundles combining circuits, masks, and IV sets.
Single-use commands the dominant share; packaged solutions are expanding most quickly as IDNs seek procurement simplification.
Application:
Clinical setting determines performance specifications and regulatory scrutiny intensity.
- Surgery:General, orthopedic, and cardiovascular procedures requiring controlled ventilation and anesthetic depth management. Anti-microbial silver-ion integration into silicone laryngeal masks is unifying infection control and airway management functions.
- Pain Management:Regional anesthesia and sedation procedures in outpatient settings.
- Dental Procedures:Conscious sedation and general anesthesia for oral surgery.
- Critical Care:Mechanical ventilation and sedation in intensive care units.
Surgery leads volumes today; pain management is gaining share fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anesthesiologist workforce density and surgical residency program concentration anchor procurement geography. Hospital consolidation into integrated delivery networks concentrates purchasing power in metropolitan medical corridors. Regulatory divergence between FDA sterility protocols and EU MDR clinical evidence requirements splits supplier qualification strategies.
United States
HCA and CommonSpirit Health systems enforce standardized anesthesia formularies across fifty-plus facilities each. FDA renewed emphasis on single-use sterility protocols pivots supplier qualification toward lot-level traceability systems. The Southeast and Midwest regional corridors concentrate ambulatory surgical center expansion as CMS reimbursement shifts accelerate outpatient migration.
Germany
Surgical centers in Bavaria and Baden-Württemberg standardize silicone laryngeal masks for outpatient ENT procedures. EU MDR Unique Device Identification mandates force serialization infrastructure investments linking lot numbers to adverse event databases. The Eindhoven-Düsseldorf medical technology cluster anchors breathing circuit manufacturing for Central European distribution.
India
Domestic manufacturing incentives under the PLI scheme enable cost-competitive export positioning into Southeast Asian procurement networks. CDSCO alignment with ISO 13485 quality management standards elevates barriers for non-compliant suppliers while rewarding established regulatory infrastructure. Gujarat and Maharashtra industrial corridors concentrate contract sterilization capacity serving regional disposable manufacturers.
Netherlands
Outpatient surgical volumes in the Randstad metropolitan zone drive demand for compact single-patient anesthesia circuits. EPA-equivalent emissions enforcement through national environmental regulators creates sterilization capacity bottlenecks favoring gamma-irradiation alternatives. Amsterdam and Rotterdam health systems pilot closed-loop anesthesia delivery systems integrating scavenging technology with disposable circuits.
Japan
PMDA quality management requirements sustain premium positioning for silicone material substitution in pediatric airway devices. METI industrial policy supports domestic polymer processing capabilities for medical-grade tubing production. The Kansai and Chubu regional manufacturing bases supply breathing circuit assemblies across East Asian hospital networks.
Anesthesia Disposables Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive anesthesia portfolios. Incumbent manufacturers leverage established FDA 510(k) clearance pathways and EU MDR conformity assessment capabilities to sustain procurement relationships with consolidated health systems. Three archetypes dominate: vertically integrated polymer processors, regulatory infrastructure specialists, and bundled disposable contract providers. Competitive moves concentrate on M&A for sterilization capacity access and strategic partnerships with integrated delivery networks for consignment inventory arrangements.
Among diversified medical technology conglomerates, Teleflex Incorporated, Medtronic plc, and Ambu A/S occupy positions reflecting distinct strategic anchors. Teleflex exemplifies the vertically integrated manufacturing archetype with polymer processing capabilities sustaining margin resilience. Medtronic represents the bundled disposable contract model extending reach through multi-product agreements with IDNs. Ambu sits within the single-use specialization tier, anchoring competitive positioning through portfolios that sidestep reprocessing liability. These three entities collectively illustrate how regulatory infrastructure scale and manufacturing integration separate procurement winners from commodity suppliers.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Ambu A/S |
| Medtronic plc |
| Draegerwerk AG and Co. KGaA |
| Intersurgical Ltd. |
| Becton, Dickinson and Company |
| Smiths Medical |
| Philips |
| Fisher & Paykel Healthcare |
| Others |
Supply Flow & Price Mechanics
EPA emissions enforcement gates both qualified sterilization supply and premium-tier pricing access for anesthesia disposable manufacturers. Contract sterilizer shutdowns concentrate ethylene oxide capacity among fewer providers, forcing suppliers to absorb cost volatility or migrate to gamma-irradiation alternatives that command price premiums.
Pricing Analysis
Bundled disposable contracts versus unbundled component sourcing splits procurement economics across integrated delivery networks. Three-tier pricing structure across premium silicone, standard PVC, and economy-grade polymer levels reflects material certification and sterilization method. Cost compression in standard breathing circuits intensifies as hospital GPOs consolidate vendor rosters. Surgical centers show highest price sensitivity due to CMS reimbursement constraints, while pediatric segments tolerate premium positioning for hypoallergenic silicone alternatives.
Supply Chain Analysis
Single-source vulnerability sits with ethylene oxide sterilization capacity concentrated in the United States, Germany, and India. Medical-grade PVC resin, silicone polymer, and gamma-irradiation feedstock anchor raw material dependencies. Regulatory restriction through EPA emissions enforcement creates supply bottlenecks for sterilization-dependent products. Distribution runs through integrated delivery network centralized purchasing portals that disintermediate traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anesthesia disposables constitute a late-cycle quality story as outpatient migration concentrates demand toward premium single-use specifications with embedded traceability.
For Market Incumbents: Acquire sterilization infrastructure assets to secure capacity access amid EPA emissions enforcement. Backward integration into medical-grade polymer processing defends margin position against PVC resin volatility. Consolidate vendor relationships with HCA and CommonSpirit through consignment inventory arrangements that transfer working capital burden downstream. For New Entrants and Emerging Players: Digital traceability platforms with lot-level serialization offer a technology-first wedge into EU MDR-compliant supply chains. Target India's PLI scheme for cost-competitive export positioning into Southeast Asian procurement networks. Lead with closed-loop anesthesia delivery systems integrating scavenging technology to capture Dutch and German outpatient surgical center demand. For Investors and Strategic Acquirers: Roll-up economics work for regional sterilization capacity consolidators because EPA emissions enforcement structurally reduces viable supplier count. Five-to-ten year viability hinges on regulatory infrastructure scale rather than unit cost alone. Monitor ISO 13485 auditor scarcity as inflection indicator for market entry barriers tightening further.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Capacity Acquisition | EPA enforcement has shuttered multiple US contract sterilizers, concentrating supply among fewer qualified providers. |
| EU MDR Conformity Investment | Serialization infrastructure linking lot numbers to adverse event databases is now mandatory for French and Italian market access. |
| Hospital System Partnership | IDN centralized purchasing portals at HCA and CommonSpirit enforce standardized formularies across fifty-plus facilities each. |
| Software Companion Development | Post-market surveillance databases for Unique Device Identification compliance differentiate procurement winners from commodity suppliers. |
| Reimbursement Strategy | CMS payment shifts toward ambulatory settings concentrate demand for compact single-patient circuits designed for rapid turnover. |
Methodological Framework
Bottom-up surgical procedure modeling reconciled against top-down sterilization capacity tracking forms the analytical core of this study. Primary interviews with anesthesiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR conformity databases, hospital procurement records, and CMS reimbursement data. Triangulation between demand-side procedure volumes and supply-side manufacturing capacity yields volume and value estimates.
Historical trendline analysis across installed base replacement cycles and ambulatory surgical center expansion patterns informs projection mechanics. Segmentation dimensions span product type, end user facility scale, delivery mode sterility assurance, and application setting. CAGR derivation rests on procedure volume elasticity to reimbursement shifts and material substitution rates for silicone versus PVC. Forecast inputs incorporate IDN consolidation trajectories and sterilization capacity utilization thresholds.
The model holds under stable EPA emissions enforcement and EU MDR implementation timelines; deviation in sterilization plant closures or auditor certification backlogs would shift capacity-constrained scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Wash Bottle Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Safety Needles Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Blood Processing Disposables Market