
 Europe Smart Hospital Market | 2026-2036
Europe Smart Hospital Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Hospital Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for connected medical devices, forcing vendors to recertify legacy platforms before commercial expansion. Siemens Healthineers leverages its in-house imaging portfolio to anchor integrated digital twin deployments across German university hospitals. Koninklijke Philips N.V. competes through its cloud-native patient monitoring architecture, while GE Healthcare differentiates via AI-embedded radiology workflows that reduce diagnostic turnaround times.
A smart hospital integrates IoT-enabled medical devices, cloud-based data platforms, and machine learning algorithms to automate clinical workflows, optimize resource allocation, and enable real-time patient surveillance across distributed care settings. The technical stack requires interoperability across HL7 FHIR standards, edge computing nodes with sub-50ms latency, and cybersecurity frameworks compliant with IEC 62304 software lifecycle protocols. Patient Monitoring Systems and Telemedicine Solutions represent the most active investment corridors, with hardware-software bundling capturing margin pools that standalone device sales cannot match. Data Management Software remains structurally fragmented, creating openings for platform plays that consolidate electronic health records across multi-site hospital networks.
The European Medicines Agency coordinates post-market surveillance of AI-enabled diagnostic tools, while the EU AI Act imposes risk-classification requirements on clinical decision-support algorithms that process patient data. GDPR and the NIS2 Directive enforce granular consent management and incident reporting standards that inflate compliance costs for cloud-dependent architectures. Stakeholders must weigh vendor consolidation against interoperability mandates as procurement committees rewrite technical specifications to favor open-architecture platforms over proprietary ecosystems.
Market Dynamics
CE marking recertification under the EU Medical Device Regulation is compressing vendor timelines and forcing hospital procurement committees to rewrite technical specifications around interoperability mandates.
Growth Catalysts
- EU AI Act risk-classification requirements:Clinical decision-support algorithms face new compliance pathways that favor established platform vendors with dedicated regulatory affairs teams.
- Cloud-native patient monitoring architectures:German university hospitals are consolidating distributed care settings through edge computing nodes with sub-50ms latency requirements.
- Diagnostic imaging integration:France's public hospital networks are bundling hardware-software contracts to capture margin pools unavailable through standalone device procurement.
Market Restraints
- GDPR granular consent management:Cloud-dependent architectures face inflated compliance costs from incident reporting standards under the NIS2 Directive.
- Legacy platform recertification:Vendors must redirect engineering resources toward MDR compliance rather than feature development.
- HL7 FHIR interoperability gaps:Proprietary hospital information systems resist standardized data exchange, fragmenting platform consolidation efforts.
Strategic Opportunities
- United Kingdom NHS digitization mandates:England's integrated care systems are accelerating procurement of connected care infrastructure with centralized funding mechanisms.
- AI-embedded radiology workflow convergence:Machine learning algorithms processing patient data create openings for vendors combining diagnostic imaging with real-time surveillance capabilities.
- Data Management Software fragmentation:Multi-site hospital networks in the Netherlands seek platform plays consolidating electronic health records across distributed campuses.
Industry Challenges
- IEC 62304 software lifecycle expertise:Vendors struggle to recruit engineers fluent in medical device cybersecurity frameworks compliant with European Medicines Agency post-market surveillance.
- Edge computing infrastructure capex:Real-time patient surveillance requires hospital capital allocation toward networking hardware rather than clinical equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Hospital Market |
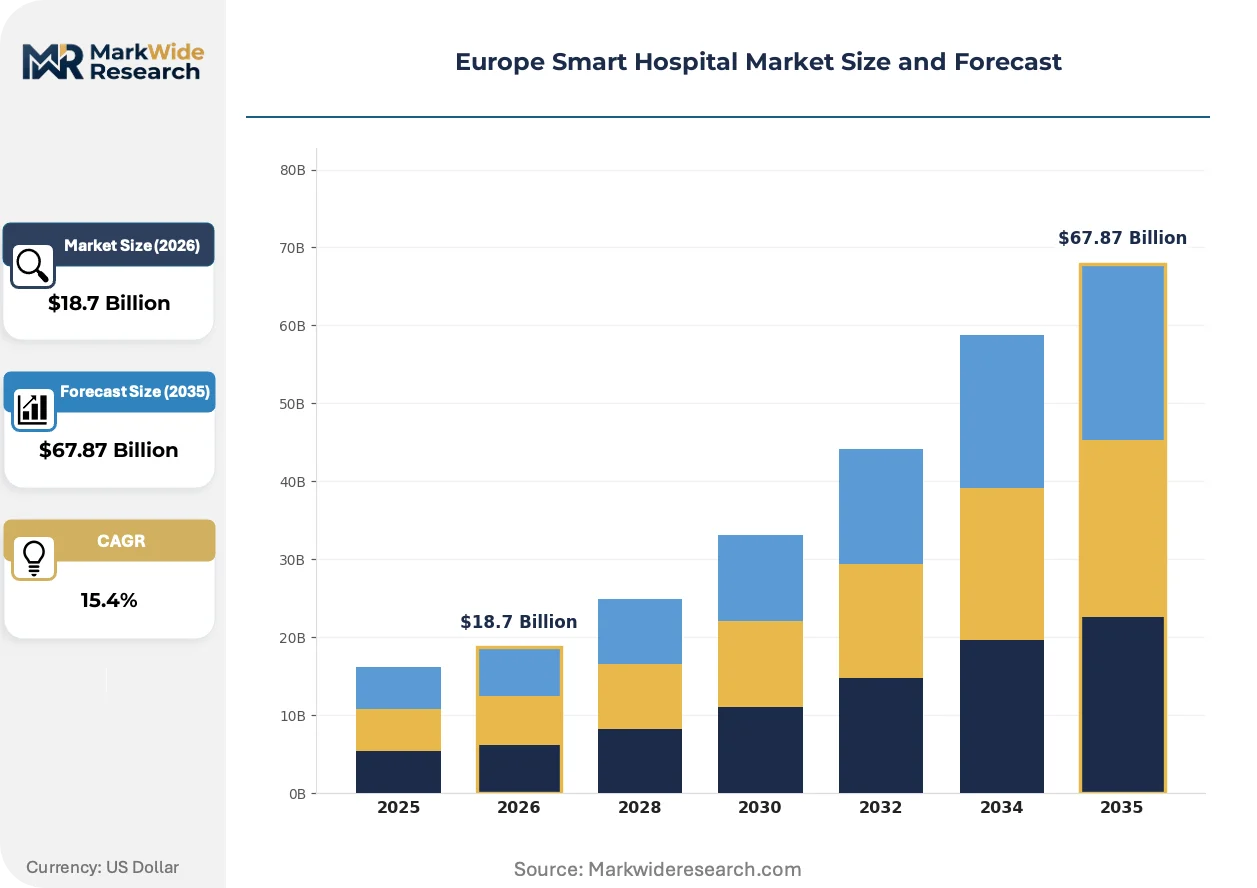
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Monitoring Systems, Telemedicine Solutions, Imaging Systems, Data Management Software End User: Public Hospitals, Private Hospitals, Specialty Clinics, Rehabilitation Centers Technology: IoT Devices, Cloud Computing, Artificial Intelligence, Machine Learning Application: Remote Patient Monitoring, Electronic Health Records, Workflow Automation, Telehealth Services |
| Companies Covered | Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Medtronic, Microsoft, Qualcomm Technologies, Inc., McKesson Corporation, SAP, Stanley Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Hospital Market Shifts & Advancements
Digital twin deployments are anchoring competitive differentiation as vendors race to integrate IoT-enabled medical devices with predictive maintenance capabilities across European hospital networks.
Digital twin technology is displacing reactive equipment maintenance schedules across German university hospitals. Siemens Healthineers anchors integrated deployments through its in-house imaging portfolio. Clinical engineering teams now prioritize predictive asset management over traditional break-fix service contracts.
The EU AI Act imposes risk-classification requirements on clinical decision-support algorithms processing patient data. High-risk AI systems face conformity assessment procedures before CE marking authorization. Radiology departments in France and Germany are restructuring procurement specifications to prioritize explainable AI architectures.
Hospital procurement committees now favor open-architecture platforms over proprietary ecosystems when rewriting technical specifications. Bundled hardware-software contracts capture margin pools that standalone device sales cannot match. This specification shift appears most visible in England's NHS integrated care systems and Dutch academic medical centers.
Europe Smart Hospital Market Segmentation
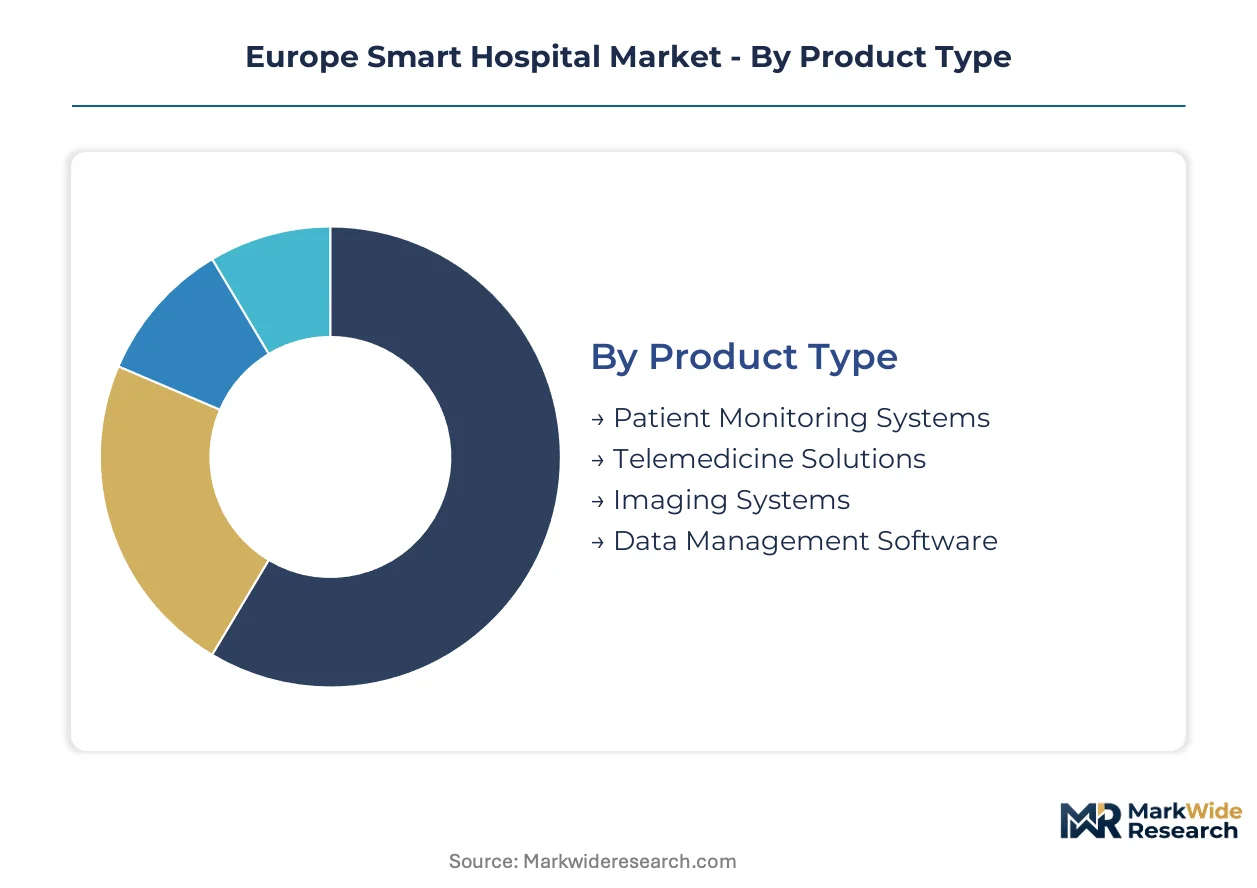
Smart hospital procurement committees evaluate technology investments through four intersecting lenses: clinical utility, regulatory pathway, integration complexity, and total cost of ownership. Segmentation clarity enables vendors to align product roadmaps with the specific procurement criteria dominating German university hospitals versus French public networks versus England's integrated care systems.
Product Type:
Hardware-software bundling captures margin pools that standalone device sales cannot match, with procurement committees favoring integrated platforms over point solutions.
- Patient Monitoring Systems:IoT-enabled bedside and wearable sensors stream real-time vital signs to centralized nursing stations. Demand concentrates in Germany's university hospital network, where edge computing nodes with sub-50ms latency requirements are mandatory for distributed care settings. CE marking recertification under MDR is compressing vendor timelines for wireless connectivity modules.
- Telemedicine Solutions:Cloud-native architectures enable synchronous video consultation and asynchronous store-and-forward diagnostics across multi-site hospital networks. French public hospitals are consolidating procurement through hardware-software contracts that standalone device vendors cannot fulfill. GDPR granular consent management inflates compliance costs for cloud-dependent deployments.
- Imaging Systems:Diagnostic imaging integration advances fastest in German university hospitals with digitization mandates.
- Data Management Software:Structurally fragmented electronic health record platforms create openings for consolidation plays across Dutch academic medical centers.
By volume, Patient Monitoring Systems leads. By growth pace, Telemedicine Solutions is climbing the fastest.
End User:
Capital allocation patterns diverge sharply between publicly funded networks with centralized procurement and privately held hospital groups with decentralized decision-making.
- Public Hospitals:Germany, France, and the United Kingdom are accelerating connected care infrastructure procurement through centralized funding mechanisms. England's NHS integrated care systems rewrite technical specifications to favor open-architecture platforms over proprietary ecosystems. MDR compliance requirements reshape vendor qualification timelines.
- Private Hospitals:Independent hospital groups prioritize diagnostic imaging integration and AI-embedded radiology workflows that reduce turnaround times. Margin capture through hardware-software bundling exceeds what standalone device procurement achieves.
- Specialty Clinics:Cardiology and oncology centers in the Netherlands seek platform plays consolidating electronic health records across distributed campuses.
- Rehabilitation Centers:Remote patient monitoring demand is expanding most quickly in post-acute settings managing chronic disease transitions.
Public Hospitals dominate procurement volume. Private Hospitals show the steepest expansion trajectory for AI-enabled diagnostic tools.
Technology:
Interoperability mandates under HL7 FHIR standards determine which technology layers hospital IT departments will greenlight for enterprise deployment.
- IoT Devices:Connected medical devices with predictive maintenance capabilities anchor digital twin deployments. Siemens Healthineers leverages its in-house imaging portfolio to anchor integrated deployments across German university hospitals. IEC 62304 software lifecycle expertise remains scarce among engineering teams.
- Cloud Computing:Cloud-native patient monitoring architectures enable real-time surveillance across distributed care settings. GDPR and the NIS2 Directive enforce granular consent management and incident reporting standards that inflate compliance costs.
- Artificial Intelligence:The EU AI Act imposes risk-classification requirements on clinical decision-support algorithms processing patient data. High-risk AI systems face conformity assessment procedures before CE marking authorization.
- Machine Learning:Radiology departments in France and Germany restructure procurement specifications to prioritize explainable AI architectures.
IoT Devices leads by installed base. Artificial Intelligence is gaining share fastest as procurement committees prioritize explainable diagnostic algorithms.
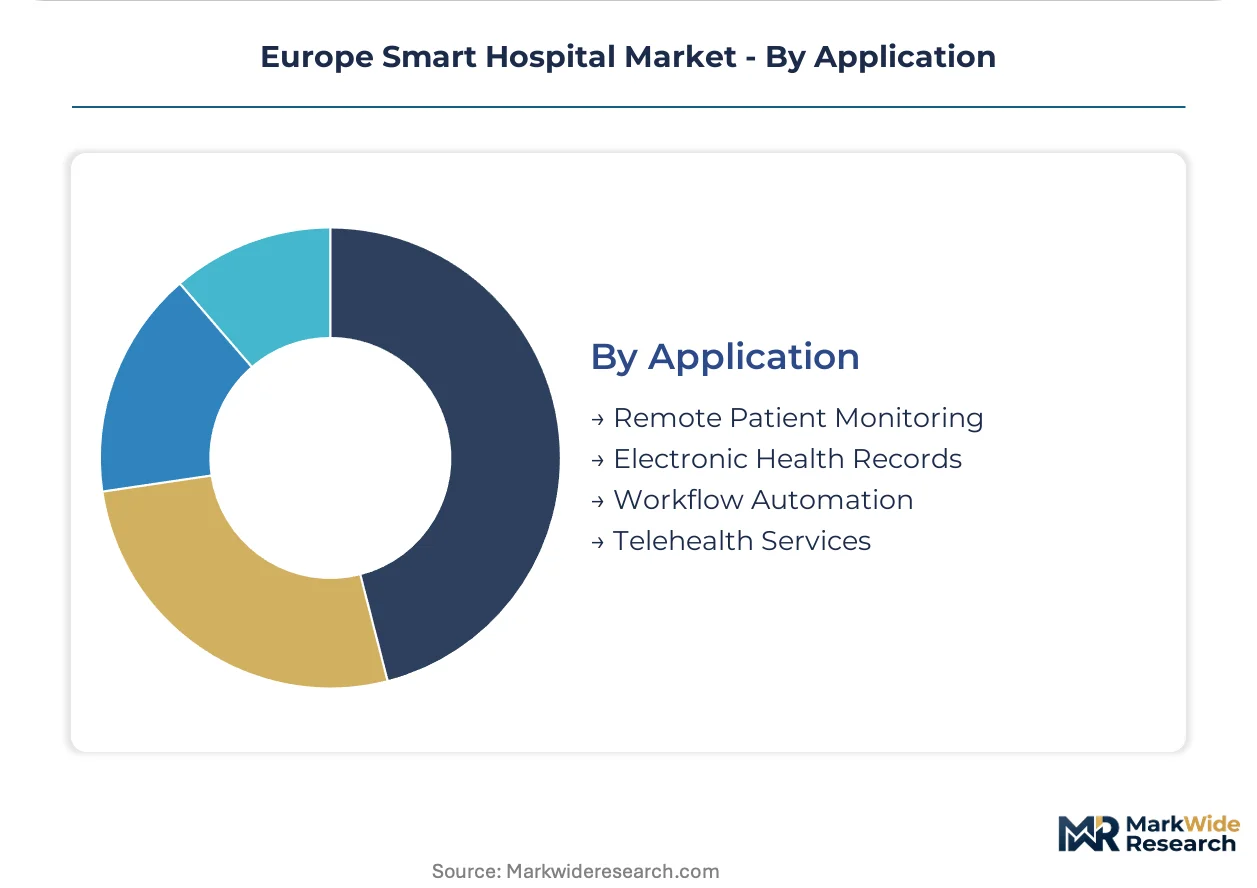
Application:
Workflow automation and remote surveillance applications command premium pricing when bundled with hardware infrastructure rather than sold as standalone software licenses.
- Remote Patient Monitoring:Real-time surveillance across distributed care settings requires hospital capital allocation toward networking hardware with sub-50ms latency. German university hospitals consolidate distributed settings through edge computing nodes. EU AI Act risk-classification requirements apply to algorithmic patient risk scoring.
- Electronic Health Records:Multi-site hospital networks in the Netherlands seek platform plays consolidating records across distributed campuses. Data Management Software fragmentation creates consolidation openings for vendors with interoperability expertise.
- Workflow Automation:Machine learning algorithms optimize resource allocation and automate clinical workflows in England's NHS integrated care systems.
- Telehealth Services:Cloud-dependent architectures face inflated compliance costs from GDPR granular consent management requirements.
Electronic Health Records leads by deployment volume. Remote Patient Monitoring is expanding most quickly as edge computing infrastructure capex shifts from clinical equipment to networking hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU digitization mandates and GDPR compliance requirements are reshaping procurement patterns across national hospital networks. CE marking recertification under the EU MDR compresses vendor timelines unevenly. Public funding mechanisms concentrate investment in university hospital systems with established digital infrastructure.
Germany
University hospital networks drive diagnostic imaging integration and edge computing deployment with sub-50ms latency requirements. The country's national pharmaceutical regulator coordinates post-market surveillance alongside EU AI Act risk-classification enforcement. Bavaria's academic medical centers anchor Siemens Healthineers digital twin deployments through predictive maintenance contracts.
France
Public hospital networks consolidate procurement through hardware-software bundling that standalone device vendors cannot fulfill. ANSM and CNIL enforce granular consent management standards that inflate compliance costs for cloud-dependent architectures. Parisian university hospitals restructure specifications to prioritize explainable AI architectures in radiology departments.
United Kingdom
NHS integrated care systems accelerate connected care infrastructure procurement through centralized funding mechanisms. England's digitization mandates rewrite technical specifications to favor open-architecture platforms over proprietary ecosystems. London's academic medical centers lead workflow automation deployments using machine learning algorithms for resource allocation.
Netherlands
Multi-site hospital networks seek platform plays consolidating electronic health records across distributed campuses. Data Management Software fragmentation creates openings for vendors with HL7 FHIR interoperability expertise. Eindhoven's health technology cluster concentrates telemedicine solution development for cross-border care coordination.
Italy
Regional health authorities negotiate consolidated procurement contracts for IoT-enabled patient monitoring systems. The country's national pharmaceutical regulator aligns CE marking timelines with EU MDR recertification requirements. Lombardy's hospital network advances cloud-native architectures despite GDPR-driven compliance cost inflation.
Europe Smart Hospital Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates with established imaging portfolios and emerging cloud-native specialists. Siemens Healthineers anchors integrated digital twin deployments through in-house imaging assets. Koninklijke Philips N.V. competes via cloud-native patient monitoring architectures. GE Healthcare differentiates through AI-embedded radiology workflows. Strategic moves concentrate on M&A for interoperability capabilities and portfolio diversification into software-centric revenue models.
Among diversified European health technology conglomerates, Siemens Healthineers and Koninklijke Philips N.V. occupy positions exemplifying the hardware-software bundling archetype that procurement committees increasingly favor. GE Healthcare represents the AI-embedded workflow specialization vector. These three entities anchor competitive dynamics as hospital networks rewrite specifications around open-architecture mandates and explainable AI requirements under EU regulatory frameworks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Microsoft |
| Qualcomm Technologies, Inc. |
| McKesson Corporation |
| SAP |
| Stanley Healthcare |
| Others |
Supply & Pricing Matrix
Ninety-day component lead times for edge computing nodes and wireless connectivity modules concentrate procurement leverage with German and Dutch systems integrators, compressing margin pools for standalone device vendors unable to bundle hardware-software contracts. This inventory compression forces pricing power toward platform players with captive certification pipelines under EU MDR and GDPR compliance frameworks.
Pricing Analysis
Certification level (CE marking under EU MDR versus legacy MDD grandfathering) creates the primary spread between premium platform vendors and economy-tier standalone suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects bundled after-sales service commitments and predictive maintenance contract duration. Cost compression in the economy tier intensifies as hospital procurement committees consolidate vendor panels around open-architecture mandates. Public hospital networks in Germany and France exhibit lowest price sensitivity due to centralized digitization funding, while Italian regional health authorities face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of semiconductor components for IoT-enabled medical devices contrasts with just-in-time preferences for cloud computing infrastructure, reflecting divergent obsolescence risk profiles across hardware generations. Manufacturing concentration centers on Germany, the Netherlands, and Taiwan for edge computing nodes, sensor arrays, and wireless connectivity modules. Component sourcing draws from specialized foundries in South Korea and Japan for medical-grade semiconductors. Single-source vulnerability persists for IEC 62304-compliant firmware development expertise. Distribution runs through hospital procurement consortiums and group purchasing organizations with centralized technical specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering teams fluent in medical device cybersecurity frameworks and HL7 FHIR interoperability standards remain acutely scarce, constraining vendor expansion velocity and inflating talent acquisition costs across European hospital networks.
For Market Incumbents: Consolidate interoperability capabilities through targeted acquisition of HL7 FHIR specialist firms and IEC 62304 software lifecycle consultancies. Lock in multi-year predictive maintenance contracts with Bavarian and Parisian university hospitals before CE marking recertification deadlines compress competitive windows. Vertical integration into edge computing hardware assembly mitigates semiconductor lead-time exposure. For New Entrants and Emerging Players: Differentiate on explainable AI architectures for radiology decision-support, targeting procurement specification rewrites in French and German hospitals restructuring around EU AI Act risk-classification requirements. White-space concentration sits in Dutch multi-site hospital networks seeking electronic health record consolidation across distributed campuses. Go-to-market through NHS integrated care system framework agreements bypasses fragmented private hospital sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a platform-consolidation play because hardware-software bundling captures margin pools unavailable to standalone device vendors, with procurement committee preferences hardening around open-architecture mandates. Target acquisition profiles emphasize cloud-native patient monitoring specialists with established GDPR compliance infrastructure and existing German university hospital deployments. Watch for inflection when ANSM and BfArM publish harmonized post-market surveillance guidance for AI-enabled diagnostic tools.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification compresses vendor timelines and reshapes competitive positioning across German procurement panels. |
| Hospital System Partnership | Framework agreements with NHS integrated care systems accelerate cloud-native architecture deployment at scale. |
| Software Companion Development | AI-embedded radiology workflows reduce diagnostic turnaround times for French public hospital networks. |
| Backward Integration | In-house edge computing node production mitigates semiconductor lead-time volatility for patient monitoring systems. |
| Reimbursement Strategy | Alignment with national digitization mandates unlocks centralized funding mechanisms in England and Germany. |
Research Methodology
The analysis maps patient monitoring systems, telemedicine solutions, diagnostic imaging platforms, and data management software segments, each validated through hospital procurement committees, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists. Primary interviews with clinicians and health technology procurement officers combined with secondary validation against EMA post-market surveillance databases, hospital procurement registries, and EU MDR notified body filings. Bottom-up installation base enumeration and top-down expenditure flow analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across hardware-software bundling penetration, cloud-native architecture adoption curves, and AI-enabled diagnostic tool deployment rates. Segmentation modeling incorporated product type, end-user capital allocation patterns, technology interoperability layers, and application workflow automation intensity. CAGRs derived from regression analysis of historical procurement cycle timing and digitization mandate implementation schedules, with edge computing infrastructure capex and GDPR compliance cost inflation as industry-specific forecast inputs.
Material uncertainties — regulatory timeline delays for EU AI Act conformity assessment procedures, MDR notified body capacity constraints, and semiconductor supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding procurement committee specification continuity and centralized funding mechanism stability. Revision becomes warranted when CE marking recertification backlog durations or edge computing component lead times cross thresholds that alter hospital capital allocation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Telepharmacy Market