
 Global Nitinol Medical Devices Market | 2026-2036
Global Nitinol Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitinol Medical Devices Market Intelligence
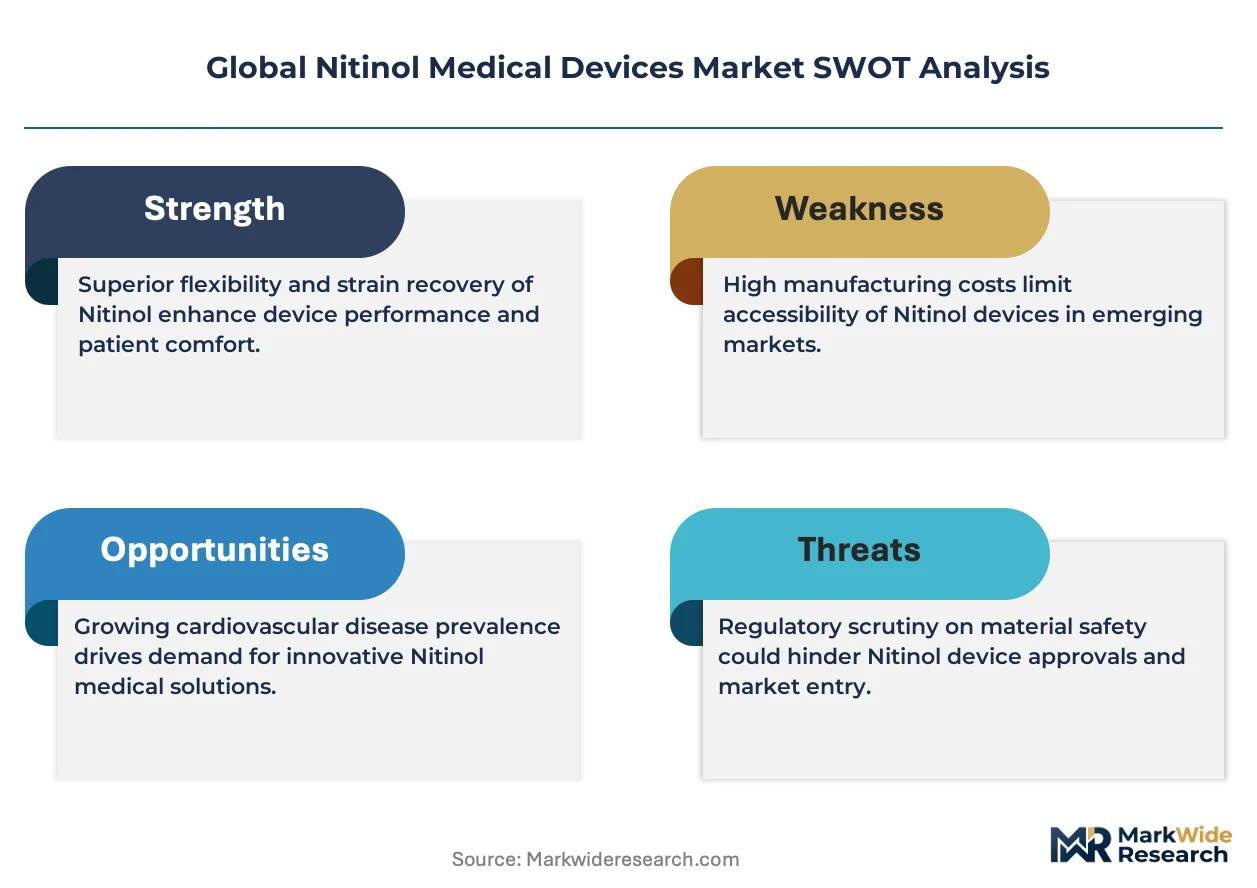
The increasing preference for minimally invasive procedures in cardiology and vascular surgery is realigning the end-use application mix for nitinol devices. Medtronic plc leverages its extensive distribution network and broad product portfolio to maintain a significant market presence. Boston Scientific Corporation specializes in cardiovascular applications, particularly with its advanced stent and catheter systems. Terumo Corporation differentiates through its leadership in guidewire technology and precision manufacturing capabilities.
Nitinol medical devices are instruments and implants fabricated from a nickel-titanium alloy renowned for its unique properties of superelasticity and thermal shape memory. This material allows devices like stents and guidewires to be navigated through complex anatomies in a compressed state and then deploy to their functional shape upon reaching the target site. Stents and guidewires represent the largest product segments, driven by high-volume procedures in cardiology. Within applications, vascular surgery and orthopedics are showing significant expansion, benefiting from nitinol's biocompatibility and mechanical resilience for implants and fixation devices.
Market access is strictly governed by regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Union's Medical Device Regulation (MDR). These frameworks, alongside ISO 10993 for biocompatibility, mandate rigorous testing for material composition, fatigue resistance, and clinical efficacy, influencing product design and development timelines. Future competitive advantage will depend on mastering thermal treatment processes to precisely control the alloy's phase transformation temperatures for increasingly miniaturized and complex device applications.
Market Dynamics
The central structural force in the nitinol medical device market is the intense technological push towards miniaturization. This is driven by advanced thermal treatment processes that allow for precise control over the alloy's shape memory and superelastic properties in increasingly smaller and more complex device designs.
Growth Catalysts
- Expanding Clinical Applications:The use of nitinol is expanding beyond cardiology into orthopedic and spinal surgery for fixation devices and corrective implants, leveraging the material's unique combination of flexibility and strength.
- Advanced Manufacturing:Additive manufacturing of nitinol alloys enables the creation of highly complex, patient-specific implants with porous structures that promote better bone integration, a significant advantage over traditionally manufactured components.
- Demographic Pressures:Aging populations in developed nations such as Japan and Germany are increasing the incidence of cardiovascular and degenerative bone diseases, directly fueling procedural volumes for nitinol-based stents, guidewires, and orthopedic implants.
Market Restraints
- Raw Material Cost Volatility:The market is exposed to price fluctuations in high-purity nickel and titanium, the primary constituents of nitinol. These supply-side shocks can compress manufacturer margins and impact final device pricing.
- Processing Complexity:Achieving consistent and precise shape memory properties requires sophisticated thermomechanical processing, which represents a significant technical barrier and limits the number of qualified material suppliers.
- Regulatory Scrutiny:Rigorous testing and validation protocols mandated by the EU's Medical Device Regulation (MDR) and the U.S. FDA, particularly for long-term implantable devices, result in extended and costly product development cycles.
Strategic Opportunities
- Neurovascular Intervention:There is a significant opportunity in developing next-generation nitinol-based devices, such as flow diverters and clot retrievers, to address the growing clinical need for effective ischemic stroke treatments.
- Emerging Market Penetration:Healthcare systems in Brazil and India represent substantial growth areas, as improving infrastructure and rising disposable incomes increase access to advanced minimally invasive procedures.
- Smart Device Integration:The convergence of nitinol with micro-sensor technology offers a pathway to create smart implants capable of monitoring physiological conditions or device integrity in real-time, providing valuable clinical data.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of materials scientists and engineers with deep expertise in nitinol metallurgy and device fabrication constrains research and development capacity across the industry.
- Fatigue Life Standardization:The lack of a universally accepted standard for testing and predicting the fatigue life of nitinol devices creates inconsistencies in regulatory submissions and complicates device-to-device comparisons for clinicians.
- Intellectual Property Density:A crowded and complex patent landscape surrounding nitinol processing techniques and device designs increases litigation risk and can create barriers for new entrants attempting to innovate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitinol Medical Devices Market |
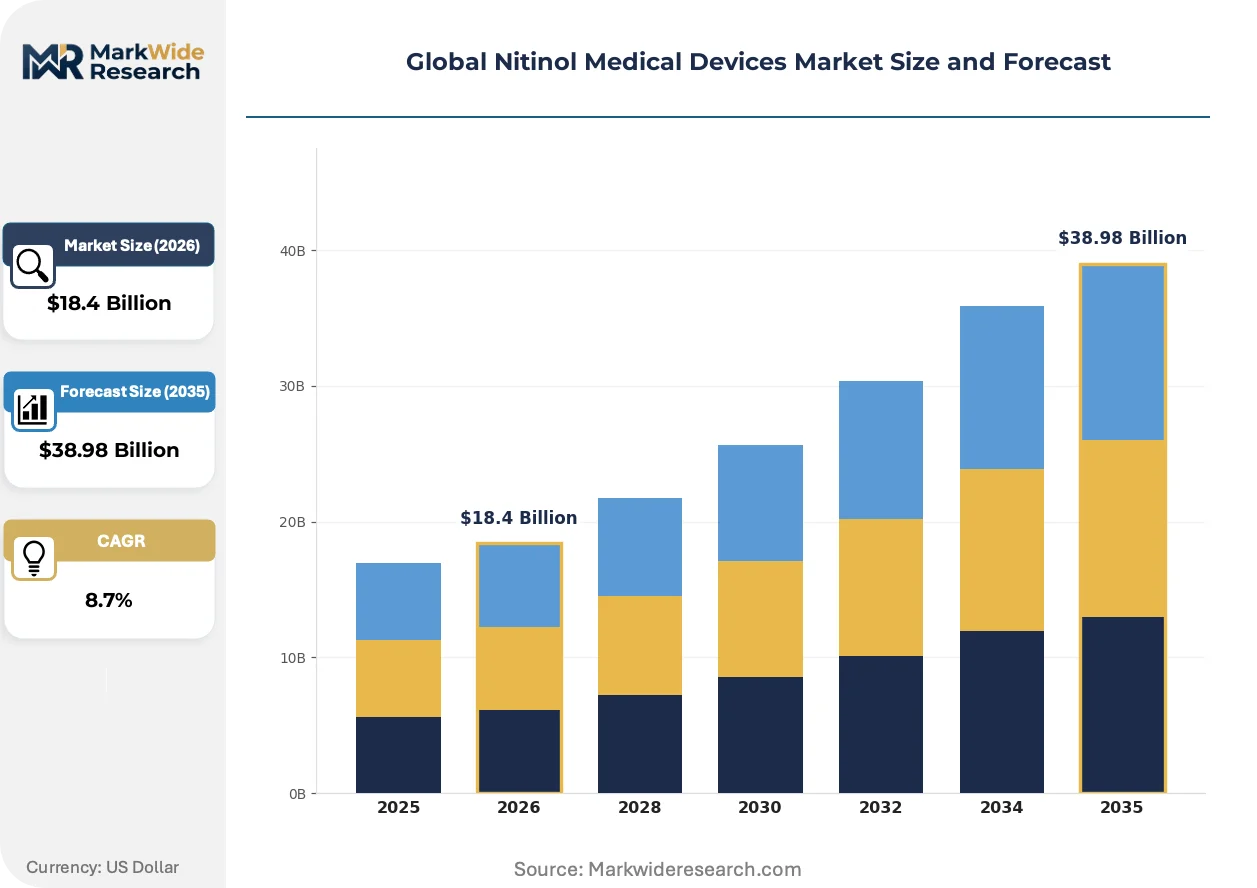
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guidewires, Stents, Orthodontic Archwires, Surgical Instruments, Catheters Application: Cardiology, Urology, Neurology, Orthopedics, Vascular Surgery End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Specialty Clinics Technology: Shape Memory Alloy, Superelasticity, Memory Effect, Thermal Treatment, Cold Working |
| Companies Covered | Terumo Corporation, W. L. Gore & Associates, Medtronic plc, Zimmer Biomet Holdings, Becton, Dickinson and Company, Boston Scientific Corporation, Cook Medical, Arthrex, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitinol Medical Devices Market Strategic Shifts & Innovations
The market is reshaping around the transition from standardized, high-volume components to customized, patient-specific solutions. This evolution is enabled by the convergence of advanced material processing with digital design and diagnostic imaging technologies, allowing for unprecedented device personalization.
Additive manufacturing, specifically selective laser melting of nitinol, permits the fabrication of implants with intricate geometries tailored to individual patient anatomy. Orthopedic and maxillofacial surgical specialties are early adopters, using the technology for custom fixation plates and lattice structures that promote osseointegration. This capability is decentralizing production away from large-scale foundries toward specialized, on-demand manufacturing centers.
The updated ISO 10993 framework for biocompatibility evaluation now mandates more rigorous assessment of leachable and extractable materials from medical devices. This regulatory shift directly impacts nitinol products due to concerns over long-term nickel ion release. The cardiovascular stent segment is most affected, compelling manufacturers to invest in advanced surface passivation and barrier coating technologies to ensure compliance.
A notable behavioral change is emerging as hospital purchasing departments shift toward value-based procurement for high-cost nitinol devices like transcatheter heart valves. This model prioritizes total cost of care and clinical outcomes over simple unit price, altering supplier negotiations. This demand-side shift is most visible in large, integrated health networks in the United States and Germany, where economic and clinical evidence are paramount.
Global Nitinol Medical Devices Market Segmentation
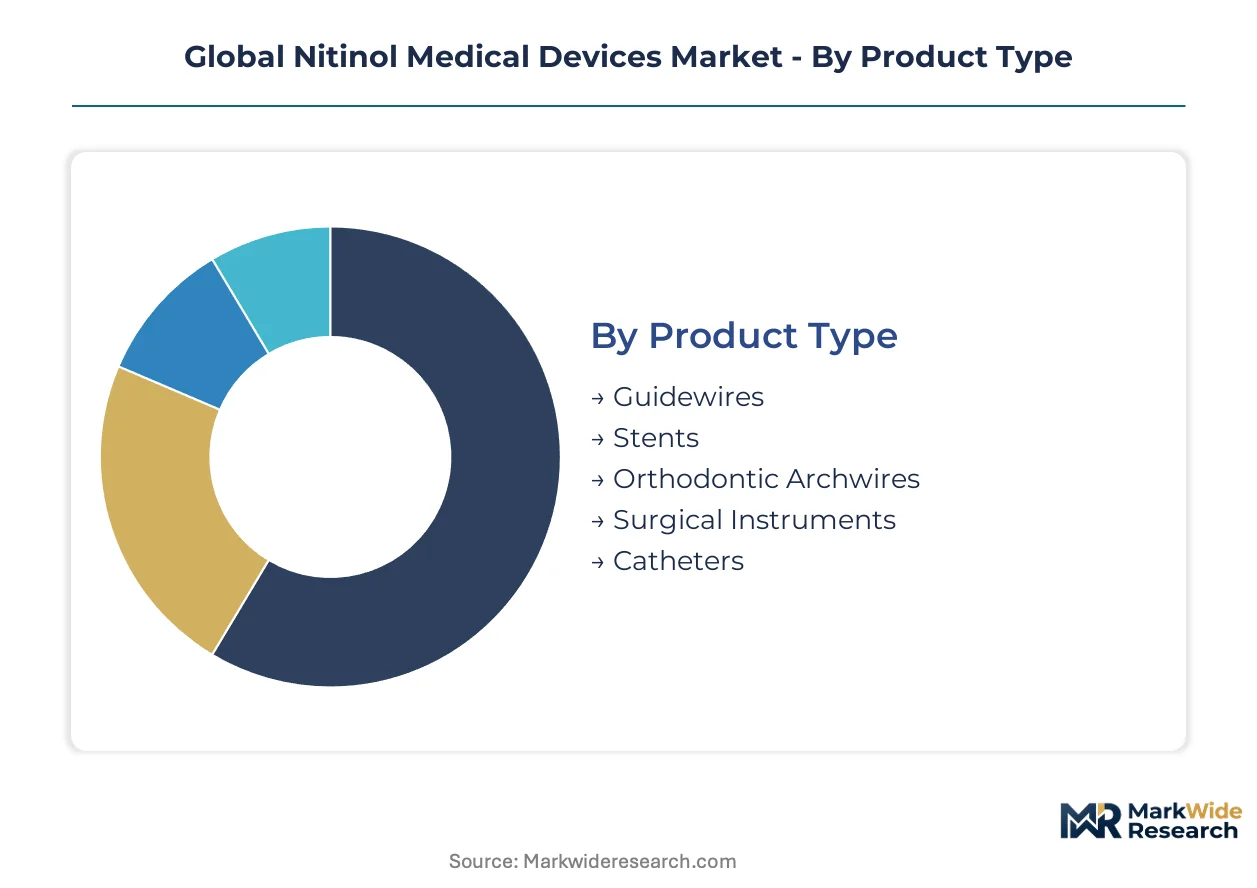
Understanding the varied needs of medical professionals and patient populations drives product development in the nitinol medical devices market. Segmentation analysis clarifies how different device types, applications, end-users, and manufacturing technologies contribute to market dynamics. This breakdown helps identify areas of concentrated demand and emerging growth opportunities across the healthcare ecosystem.
Product Type:
The selection of nitinol medical devices by clinicians is primarily driven by the specific anatomical requirements and procedural complexity of patient interventions. Device properties like flexibility, kink resistance, and biocompatibility are paramount in therapeutic choices.
- Guidewires:These devices, often made with a nitinol core, provide steerability and torque response for navigating tortuous vasculature during minimally invasive procedures. Demand is concentrated in interventional cardiology and neurology, where precise navigation reduces procedural complications.
- Stents:Self-expanding nitinol stents are critical for maintaining vessel patency, deploying compressed and expanding to their functional shape at the target site. High-volume cardiovascular procedures in Germany and Japan drive stent demand due to aging populations and advanced healthcare infrastructure.
- Orthodontic Archwires:Nitinol archwires apply consistent, gentle forces for tooth movement, valued for their shape memory and superelastic properties.
- Surgical Instruments:These include specialized forceps and graspers leveraging nitinol's flexibility for access in confined surgical spaces.
- Catheters:Nitinol-reinforced catheters enhance pushability and kink resistance, essential for delivering therapies and diagnostics in various medical fields.
Stents lead on scale due to their widespread use in cardiovascular interventions; guidewires lead on momentum with expanding applications in complex neurovascular procedures.
Application:
The volume of procedures requiring nitinol devices significantly shapes the market distribution across various medical applications. High-incidence chronic conditions directly correlate with increased demand in specific therapeutic areas.
- Cardiology:This segment encompasses devices for heart-related conditions, including coronary and peripheral artery disease, leveraging nitinol for stents, guidewires, and structural heart implants. Demand is substantial in the United States, driven by high rates of cardiovascular disease and advanced treatment access.
- Vascular Surgery:Nitinol devices here address peripheral artery disease, aneurysms, and venous disorders, utilizing stents, grafts, and filters for minimally invasive interventions. Expansion in Brazil is notable, as healthcare infrastructure improves and access to advanced surgical techniques increases.
- Urology:Nitinol stents and stone retrieval devices are employed for renal and urinary tract conditions, benefiting from the material's flexibility.
- Neurology:This application focuses on neurovascular devices like clot retrievers and flow diverters for stroke treatment, a strategic opportunity.
- Orthopedics:Nitinol is used in bone fixation devices, spinal implants, and joint reconstruction due to its strength and biocompatibility.
Cardiology maintains the largest share of nitinol device consumption, while neurovascular intervention represents the fastest-growing trajectory for new product development.
End User:
The operational capabilities and patient care models of various healthcare facilities dictate the type and volume of nitinol devices procured. Specialized infrastructure and surgical expertise influence purchasing patterns.
- Hospitals:These institutions represent the primary end-users for complex nitinol procedures, including advanced cardiovascular and orthopedic surgeries requiring extensive post-operative care. Procurement decisions in hospitals are often influenced by value-based purchasing models in the United States and Germany.
- Ambulatory Surgical Centers:ASCs are increasingly performing less complex, minimally invasive procedures, driving demand for cost-effective and efficient nitinol devices like peripheral stents and guidewires. Their growth is pronounced in India, where outpatient surgery volumes are rising.
- Diagnostic Centers:These centers primarily utilize nitinol components within advanced imaging catheters for diagnostic purposes.
- Specialty Clinics:Orthodontic and vascular clinics use nitinol archwires and smaller vascular devices for focused patient treatments.
Hospitals remain the foundational market for nitinol devices, but ambulatory surgical centers are gaining significant ground through expanded outpatient capabilities.
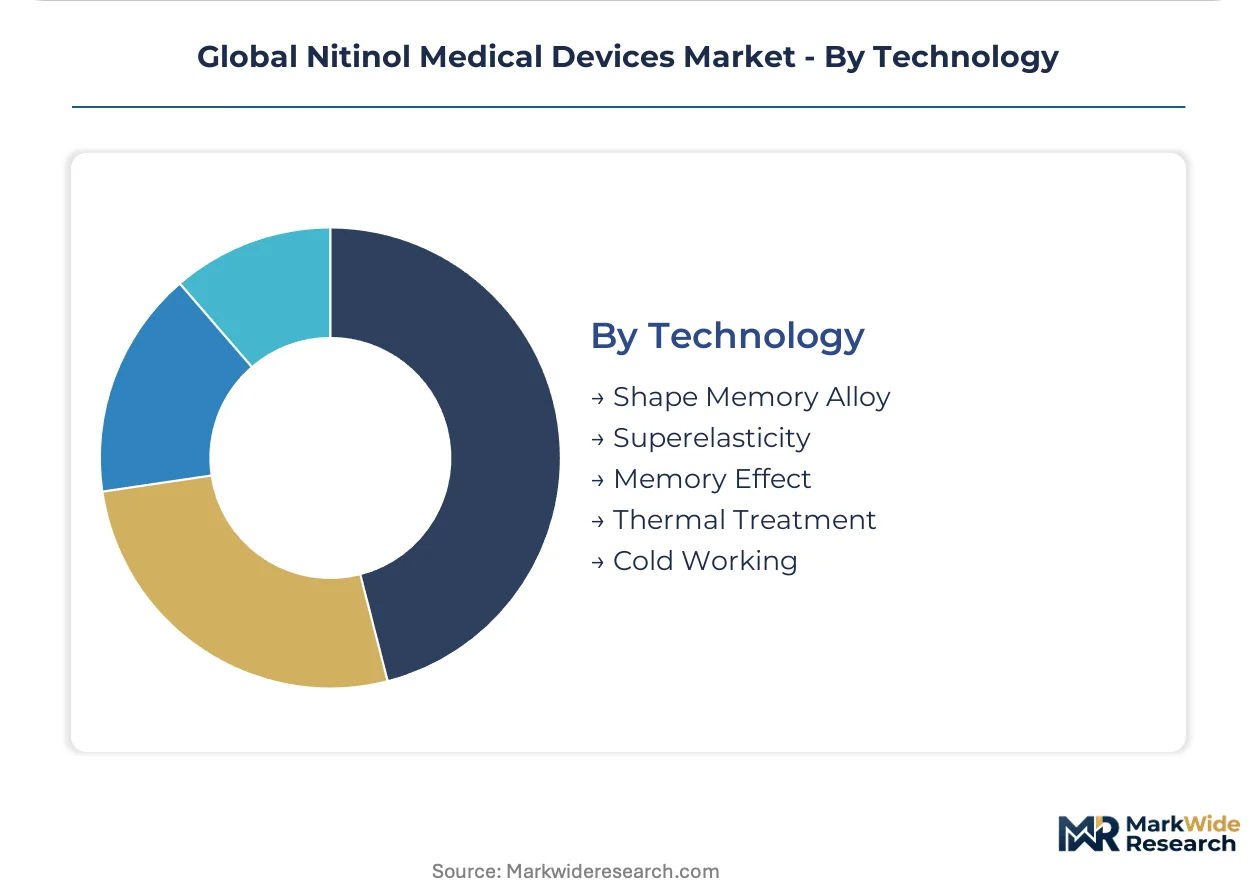
Technology:
The inherent properties and processing methods of nitinol alloys define the technological segmentation, influencing device performance and manufacturing complexity. Material science advancements directly impact device design envelopes.
- Superelasticity:This property allows nitinol devices to undergo significant deformation and return to their original shape, critical for deployable stents and guidewires. Its application is foundational for devices used in complex anatomies, particularly in neurovascular interventions.
- Thermal Treatment:Precise thermal processing controls nitinol's phase transformation temperatures, enabling tailored superelasticity and shape memory for specific device applications. Mastering this technology is crucial for miniaturized and complex device designs, providing a competitive advantage.
- Shape Memory Alloy:Nitinol's ability to "remember" a pre-set shape upon heating is leveraged in certain fixation devices and surgical tools.
- Memory Effect:The memory effect, a subset of shape memory, finds use in self-actuating components and temperature-activated medical implants.
- Cold Working:This mechanical process enhances nitinol's strength and fatigue resistance, vital for durable, long-term implantable devices.
Superelasticity is the most widely utilized technological characteristic, while advanced thermal treatment processes are central to future innovation and miniaturization efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-driven arbitrage influences the geographic distribution of nitinol medical device manufacturing, as producers seek regions with favorable compliance costs and streamlined market access. This dynamic shapes investment patterns, particularly for advanced thermal treatment processes and additive manufacturing capabilities. Demand concentration remains highest in developed economies with established healthcare infrastructures.
Germany
An aging population and a sophisticated healthcare system drive sustained demand for nitinol stents and orthopedic implants in Germany. The European Union's Medical Device Regulation (MDR) mandates stringent testing, influencing product design and development timelines for devices sold here. Munich and Stuttgart serve as significant hubs for medical technology innovation and manufacturing.
United States
High rates of cardiovascular disease and advanced treatment access fuel demand for nitinol-based guidewires and stents across the United States. The U.S. Food and Drug Administration (FDA) sets rigorous standards for device approval, impacting the clinical trial burden for new products. Medical device clusters in Minneapolis and Boston concentrate significant research and development efforts.
Japan
Demographic pressures from a rapidly aging population increase procedural volumes for nitinol-based cardiovascular and orthopedic implants in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals, emphasizing long-term safety and efficacy for implantable devices. Tokyo and Osaka remain key centers for advanced medical device R&D and precision manufacturing.
China
Expanding healthcare infrastructure and rising disposable incomes are increasing access to advanced minimally invasive procedures, driving nitinol device consumption in China. The National Medical Products Administration (NMPA) regulates device market entry, with a growing focus on local manufacturing capabilities. The Yangtze River Delta region is emerging as a critical hub for medical device production and innovation.
India
Improving healthcare infrastructure and growing outpatient surgery volumes contribute to rising demand for cost-effective nitinol devices, especially peripheral stents and guidewires, in India. The Central Drugs Standard Control Organization (CDSCO) manages device approvals, with recent initiatives to streamline the regulatory pathway. Bengaluru and Hyderabad are developing into significant centers for med-tech development and manufacturing.
Global Nitinol Medical Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a notable shift toward strategic partnerships for technology co-development. The market structure exhibits a tiered consolidation, where a few large multinational corporations hold significant market share alongside numerous specialized component suppliers. Dominant competitive moves include portfolio diversification and geographic expansion into emerging markets.
Medtronic plc, a multinational medical technology company, exemplifies the large, diversified player offering a broad product portfolio across multiple therapeutic areas. Boston Scientific Corporation occupies a position as a leading innovator in cardiovascular applications, particularly with advanced stent and catheter systems. Terumo Corporation, with its strong Japanese heritage, represents a specialist excelling in guidewire technology and precision manufacturing capabilities.
| Leading Market Players |
|---|
| Terumo Corporation |
| W. L. Gore & Associates |
| Medtronic plc |
| Zimmer Biomet Holdings |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Cook Medical |
| Arthrex |
| Abbott Laboratories |
Cost & Logistics Intelligence
Vertical integration into nitinol processing anchors material supply and allows manufacturers to control critical intellectual property, influencing device pricing power. This integration mitigates raw material cost volatility, enhancing market stability for key players.
Pricing Analysis
Distributor margins reflect the value-based procurement models favored by large hospitals, influencing final device costs. Pricing stratifies across premium, standard, and economy tiers, driven by FDA/MDR certification levels and the degree of device customization for patient-specific implants. Pricing softness affects high-volume, standardized segments due to purchasing groups prioritizing total cost of care. Ambulatory surgical centers exhibit higher price sensitivity compared to hospitals, which often prioritize clinical outcomes for complex procedures.
Supply Chain Analysis
China's growing focus on local manufacturing capabilities reshapes sourcing patterns, particularly for cost-effective nitinol components. Geographic supply concentrates in Germany and Japan for precision manufacturing, alongside China for emerging local production. The supply chain draws heavily from high-purity nickel and titanium, creating vulnerability to commodity price volatility. Single-source vulnerability for specialized nitinol alloys represents a structural risk. Distribution runs through direct sales channels to hospitals and specialized distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-driven arbitrage creates distinct market opportunities, as stringent EU MDR requirements contrast with potentially streamlined pathways in emerging markets like India.
For Market Incumbents: To counter increasing regulatory scrutiny and market fragmentation, invest in advanced surface passivation technologies to mitigate nickel ion release concerns. Form strategic partnerships for co-development of next-generation nitinol alloys and thermal treatment processes. Prioritize certification investment for new device designs to ensure compliance with evolving global standards like ISO 10993. Focus R&D efforts on miniaturized device applications to maintain a competitive edge.
For New Entrants and Emerging Players: Enter via niche, high-value applications such as neurovascular intervention, which presents a significant clinical need for effective stroke treatments. Target patient-specific orthopedic implants, leveraging additive manufacturing capabilities to create customized solutions. Focus go-to-market strategies on emerging markets like India, where improving healthcare infrastructure supports demand for cost-effective, advanced minimally invasive devices. Develop specialized expertise in thermal treatment processes to control alloy properties.
For Investors and Strategic Acquirers: Roll-up economics work for specialized component suppliers because the intellectual property landscape is fragmented and specialized manufacturing expertise is critical. Sustained demand for minimally invasive procedures over the next decade supports long-term viability. Target firms mastering advanced thermal treatment processes or additive manufacturing for nitinol, as these capabilities drive future innovation. Consolidation of specialized nitinol processing firms represents a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA/MDR Compliance Acceleration | Ensures market access and reduces development timelines for new nitinol devices in regulated markets. |
| Additive Manufacturing Investment | Enables production of complex, patient-specific nitinol implants for orthopedic and maxillofacial surgery. |
| Neurovascular Device Development | Addresses critical clinical needs for ischemic stroke treatment with advanced nitinol flow diverters and clot retrievers. |
| Emerging Market Expansion | Captures demand in Brazil and India driven by improving healthcare infrastructure and rising procedural volumes. |
| Surface Passivation Technology | Mitigates nickel ion release concerns, ensuring biocompatibility for long-term implantable nitinol devices. |
Research Approach
Bottom-up cardiology and vascular surgery end-use modeling reconciled against top-down nitinol alloy supplier tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and material scientists provided qualitative insights. Secondary validation drew from FDA filings, EU MDR guidelines, ISO 10993 standards, and medical device company annual reports.
Historical trendline analysis informed the analytical framework used to project market trajectories over the projection horizon. Segmentation dimensions modeled include product type, application, end-user, material properties, and regional market dynamics. Compound annual growth rates were derived through regression analysis of historical data and projected growth catalysts. Forecast inputs incorporated minimally invasive procedure volumes and aging population demographics.
The model holds under current regulatory frameworks and stable raw material supply; deviation in major shifts in regulatory policy or significant raw material price shocks would shift market forecasts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Umbilical Vessel Catheters Market