
 Global Burn Ointment Market | 2026-2036
Global Burn Ointment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Burn Ointment Market Foresight
The EU Green Deal's chemical sustainability criteria is decoupling procurement preferences from traditional silver sulfadiazine formulations across European hospital networks. Johnson & Johnson leverages its sterile manufacturing infrastructure to sustain supply contracts with tier-one burn centers across North America. Smith & Nephew PLC anchors its competitive position through specialized hydrofiber matrix technologies that integrate antimicrobial delivery with moisture retention.
Burn ointment comprises topical pharmaceutical preparations formulated with active agents such as silver sulfadiazine, bacitracin, or lidocaine in hydrophilic bases designed to prevent infection, manage pain, and promote re-epithelialization of damaged dermal tissue. These formulations serve critical therapeutic functions across first-degree through third-degree thermal and chemical injuries in both acute emergency settings and extended rehabilitation protocols. Silver sulfadiazine dominates current volume flows due to established clinical protocols and broad-spectrum antimicrobial coverage, while lidocaine-containing analgesic ointments represent the fastest-expanding margin pool as outpatient burn management protocols expand. Application segmentation reveals second-degree burns as the primary addressable category given treatment complexity and recurrence rates that sustain recurring prescription patterns.
The FDA maintains stringent premarket requirements for topical burn therapeutics through its Center for Drug Evaluation and Research, while the EMA's Medical Device Regulation increasingly governs advanced dressing-ointment combination products entering European markets. India's CDSCO has accelerated product registration timelines for burn care formulations under its emergency use pathways, reshaping market access dynamics for multinational manufacturers. Stakeholders must monitor evolving antimicrobial stewardship mandates that threaten to delist legacy silver-based formulations from hospital formularies without demonstrated resistance mitigation strategies.
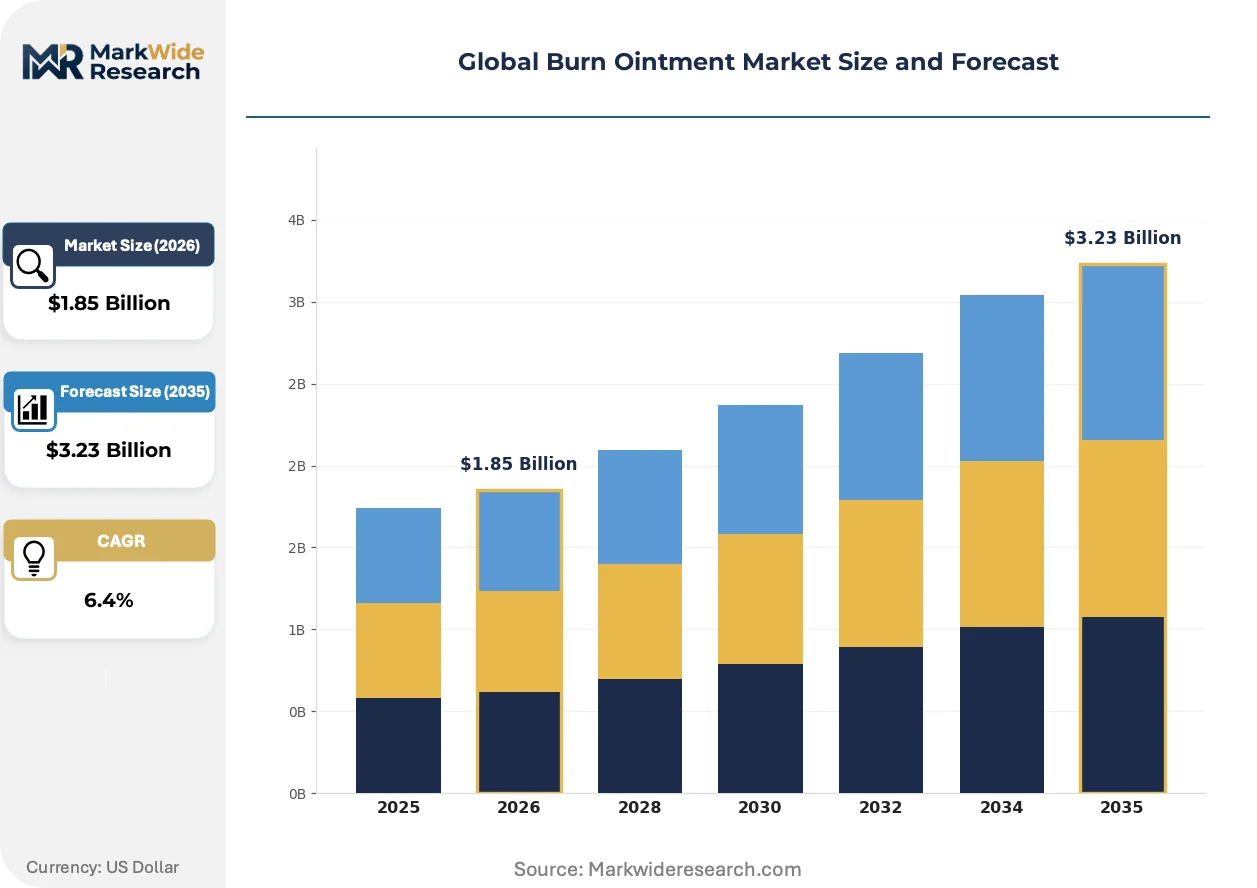
Market Dynamics
Antimicrobial stewardship mandates across major hospital networks are forcing manufacturers to reformulate silver-based products ahead of anticipated formulary exclusions, compressing R&D timelines while elevating regulatory compliance costs.
Growth Catalysts
- Emerging Economy Hospital Expansion:Government health programs in India and Brazil are broadening procurement of specialized wound care products through centralized tender mechanisms.
- EU Green Deal Chemical Criteria:The EU Green Deal's sustainability framework is decoupling European hospital procurement from legacy silver sulfadiazine formulations, creating openings for bio-based alternatives.
- Outpatient Burn Management Protocols:Lidocaine-containing analgesic ointments are capturing expanded prescription volumes as ambulatory care models displace extended hospitalization for second-degree injuries.
Market Restraints
- Silver Price Volatility:Fluctuations in silver commodity markets directly compress margins on sulfadiazine-based formulations that dominate current volume flows.
- FDA Safety Review Uncertainty:The FDA's ongoing antimicrobial safety profile review creates regulatory friction that delays new product launches and freezes formulary decisions at tier-one burn centers.
- Hydrocolloid Dressing Substitution:Advanced wound dressing technologies with integrated antimicrobial layers threaten to displace traditional ointment-only treatment regimens in managed care settings.
Strategic Opportunities
- India CDSCO Emergency Pathways:Accelerated product registration timelines for burn care formulations under India's emergency use mechanisms reduce market entry barriers for reformulated topical agents.
- Hydrofiber-Antimicrobial Convergence:Smith & Nephew PLC's matrix technology demonstrates how moisture retention platforms can integrate antimicrobial delivery, pointing toward combination product white space.
- Direct Hospital Contracting:Bypassing wholesale distribution through sterile manufacturing infrastructure investments enables supply security commitments with tier-one burn centers.
Industry Challenges
- Reformulation Talent Scarcity:Shortages of pharmaceutical formulation scientists with dual expertise in antimicrobial efficacy and biocompatibility testing extend development timelines.
- MDR Certification Complexity:The EMA's Medical Device Regulation imposes extended conformity assessment timelines for dressing-ointment combination products entering European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Burn Ointment Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Sulfadiazine, Bacitracin, Lidocaine, Mafenide Acetate, Benzalkonium Chloride Application: First-degree Burns, Second-degree Burns, Third-degree Burns, Chemical Burns, Thermal Burns End User: Burn Centers, Emergency Clinics, Dermatology Clinics, Rehabilitation Facilities, Outpatient Services Packaging Type: Tubes, Jars, Sachets, Pump Bottles, Single-dose Packs |
| Companies Covered | Johnson & Johnson, Smith & Nephew PLC, ConvaTec Group PLC, Pfizer Inc., GlaxoSmithKline PLC, Perrigo Company PLC, Sun Pharmaceutical Industries Ltd, 3M, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Burn Ointment Market Shifts & Advancements
Reformulation investments are accelerating as manufacturers anticipate formulary exclusions, while convergence between pharmaceutical ointments and advanced wound dressings is collapsing traditional category boundaries.
Hydrogel-based delivery systems are integrating bioactive peptides and plant-derived antimicrobial compounds to replace silver sulfadiazine in European hospital networks. Burn centers in Germany and France are piloting these formulations under antimicrobial stewardship protocols. This technology is integrating pain management and infection control into single-application protocols that reduce nursing intervention frequency.
The EU Green Deal's chemical sustainability criteria is reshaping procurement specifications across European hospital networks, explicitly prioritizing formulations with demonstrated biodegradability profiles. Manufacturers must now submit environmental fate data alongside clinical efficacy documentation. Second-degree burn treatments face the most immediate compliance pressure given their high prescription volumes and recurring purchase patterns.
Hospital procurement departments are consolidating vendor lists and demanding supply security guarantees through multi-year sterile manufacturing commitments. Tier-one burn centers in the United States and United Kingdom are replacing spot purchasing with integrated supply contracts that bundle ointment formulations with advanced dressing technologies. This concentration is most visible in North American academic medical centers where formulary committees now prioritize manufacturers with captive sterile production capabilities.
Global Burn Ointment Market Segmentation
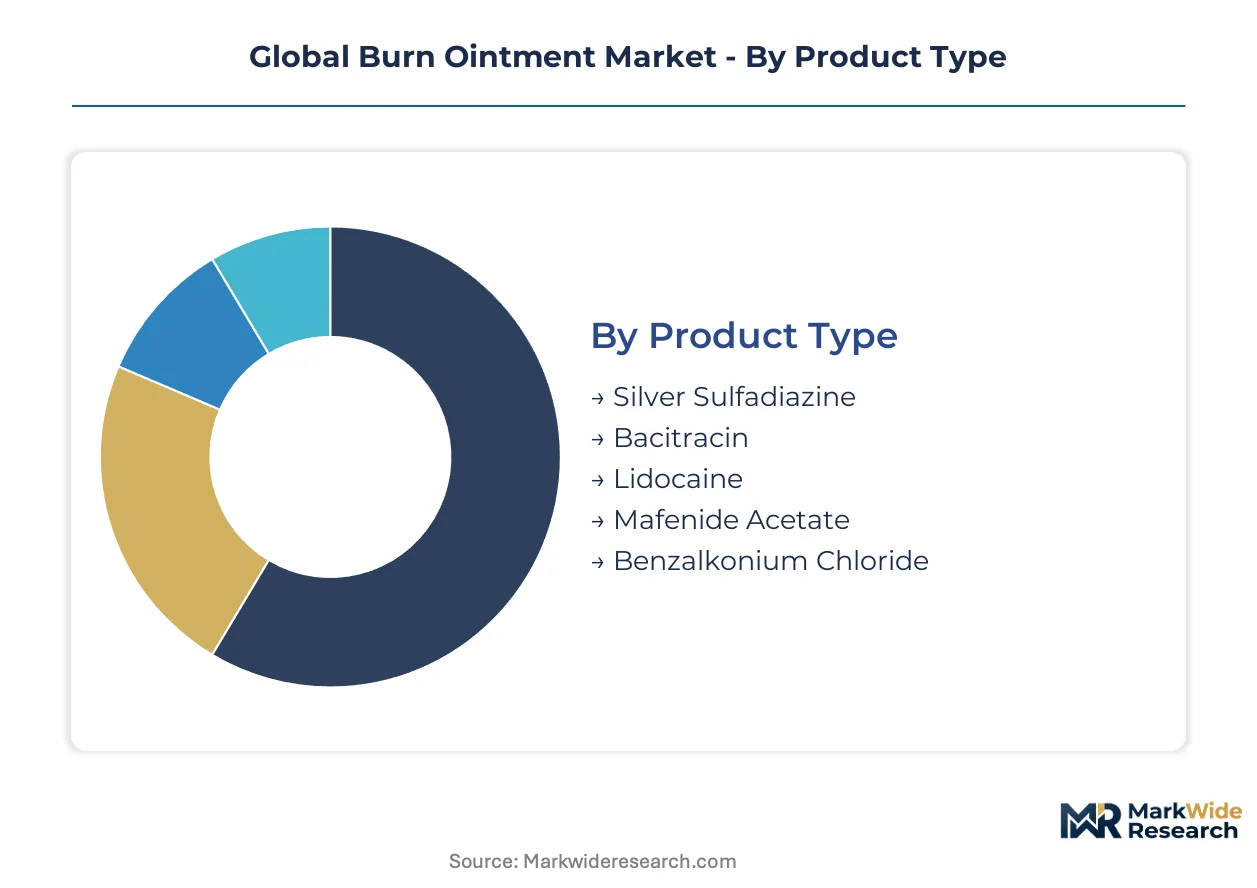
Segmentation in the burn ointment market reveals how regulatory pathways, procurement specifications, and clinical protocols fragment demand across distinct formulation categories. Manufacturers must align R&D investments with the certification burden and volume concentration of each segment to optimize commercial returns.
Product Type:
FDA premarket approval requirements under CDER guidance vary sharply across antimicrobial classes, with silver-based formulations facing heightened scrutiny while analgesic compounds navigate abbreviated pathways. EMA's MDR framework imposes additional conformity assessments on combination products incorporating active pharmaceutical ingredients with dressing materials.
- Silver Sulfadiazine:Broad-spectrum antimicrobial cream formulated with 1% silver sulfadiazine in a water-miscible base remains the clinical standard for infection prophylaxis in partial-thickness injuries. Demand concentrates in Indian government hospital tenders and Brazilian SUS procurement channels where established protocols resist formulary disruption despite stewardship pressures.
- Lidocaine:Topical anesthetic ointments containing 2-5% lidocaine hydrochloride deliver rapid pain modulation for superficial burns without systemic absorption concerns. Outpatient services in Germany and France are expanding prescriptions as ambulatory protocols displace inpatient observation for second-degree thermal injuries.
- Bacitracin:Polypeptide antibiotic ointment targeting gram-positive organisms in minor first-degree injuries.
- Mafenide Acetate:Sulfonamide-class antimicrobial reserved for deep burns where eschar penetration is required.
- Benzalkonium Chloride:Cationic surfactant antiseptic employed in low-cost formulations for emerging economy mass distribution.
Leading the category by volume: Silver Sulfadiazine. Growing fastest: Lidocaine.
Application:
Clinical outcome requirements and reimbursement tiers stratify procurement budgets across burn severity classifications, with third-degree cases commanding premium pricing while first-degree applications face commoditization pressure from over-the-counter alternatives.
- Second-degree Burns:Partial-thickness injuries involving epidermis and superficial dermis generate recurring prescription volumes through extended healing timelines and infection risk windows. Burn centers in São Paulo and Mumbai are standardizing protocol-driven ointment selection to reduce nursing intervention frequency.
- First-degree Burns:Superficial epidermal injuries represent high-volume, low-margin retail pharmacy sales with minimal regulatory barriers.
- Third-degree Burns:Full-thickness tissue destruction requires surgical intervention alongside topical adjuncts, limiting addressable ointment volume.
- Chemical Burns:Acid and alkali exposures demand neutralization protocols with specialized decontamination ointments in industrial settings.
- Thermal Burns:Flame and scald injuries constitute the foundational indication for standard antimicrobial formulations.
Dominating procurement expenditure: Second-degree Burns. Expanding most quickly: Outpatient-managed First-degree protocols.
End User:
Sterile manufacturing certification requirements and supply chain reliability standards diverge between acute care institutions and ambulatory settings, with burn centers demanding multi-year contractual guarantees unavailable to smaller dermatology practices.
- Burn Centers:Specialized tertiary care facilities with dedicated wound care teams and formulary committees that prioritize evidence-based antimicrobial selection. Tier-one centers in Boston, London, and Singapore are consolidating vendor lists around manufacturers with captive sterile production infrastructure.
- Emergency Clinics:Acute intake facilities requiring rapid-deployment single-dose packaging for trauma stabilization.
- Dermatology Clinics:Outpatient specialty practices managing minor burns alongside chronic wound portfolios.
- Rehabilitation Facilities:Post-acute care settings focused on scar management and functional recovery rather than acute infection control.
- Outpatient Services:Ambulatory care networks capturing shifted volume from hospitalization reduction initiatives.
Commanding premium pricing: Burn Centers. Volume expansion steepest: Outpatient Services.
Packaging Type:
Unit economics and contamination risk profiles shape format selection, with multi-dose containers favored in institutional settings while travel and field applications drive single-unit demand.
- Tubes:Collapsible aluminum or laminated plastic containers dominate hospital formularies for controlled dispensing and shelf stability.
- Jars:Wide-mouth containers serving high-volume institutional procurement with bulk pricing structures.
- Sachets:Unit-dose foil pouches eliminating cross-contamination risk in emergency field deployment.
- Pump Bottles:Airless dispensing systems preserving formulation integrity for hydrocolloid suspensions.
- Single-dose Packs:Pre-measured applications standardizing nursing protocol compliance in burn center workflows.
Institutional procurement standard: Tubes. Format innovation concentrated: Single-dose Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors procurement concentration in Latin America through centralized Brazilian SUS tenders that standardize silver sulfadiazine protocols across public burn centers.
United States
Boston's tier-one burn centers consolidate vendor lists around manufacturers with captive sterile production infrastructure. FDA antimicrobial safety reviews under CDER guidance create regulatory friction that freezes formulary decisions at academic medical centers. New York Metro emergency departments pilot single-dose packaging protocols to reduce nursing intervention frequency.
Germany
Burn centers in Berlin and Hamburg pilot hydrogel-based bioactive peptide formulations under EU Green Deal chemical sustainability mandates. EMA's Medical Device Regulation imposes extended conformity assessments on dressing-ointment combination products. Bavarian hospital networks explicitly prioritize biodegradability documentation alongside clinical efficacy in procurement specifications.
India
Government health programs in Maharashtra and Gujarat broaden access to specialized wound care through centralized tender mechanisms. CDSCO emergency use pathways accelerate product registration timelines for reformulated topical agents. Mumbai's public hospital networks standardize protocol-driven ointment selection to reduce infection rates in second-degree thermal injuries.
Brazil
São Paulo's SUS procurement channels sustain volume flows for silver sulfadiazine despite antimicrobial stewardship pressures emerging in private networks. ANVISA registration requirements for topical pharmaceuticals maintain barriers against rapid generic substitution. Rio de Janeiro's burn rehabilitation facilities expand outpatient prescription volumes for lidocaine-containing analgesic protocols.
United Kingdom
London's academic medical centers replace spot purchasing with integrated supply contracts bundling ointment formulations with advanced dressing technologies. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for hydrofiber-antimicrobial convergence products. Manchester's specialized wound care teams prioritize evidence-based antimicrobial selection through dedicated formulary committees.
Global Burn Ointment Market Competitive Landscape
The competitive structure tilts toward diversified healthcare conglomerates with established sterile manufacturing footprints. Consolidation pressure concentrates procurement influence among tier-one burn centers demanding multi-year supply security guarantees. Three archetypes dominate: integrated pharmaceutical-hygiene conglomerates, specialized wound care pure-plays, and generic pharmaceutical manufacturers with topical formulation capabilities. Capacity expansion into hydrofiber matrix technologies and backward integration into active pharmaceutical ingredient production represent the dominant competitive vectors reshaping supply relationships.
Among diversified healthcare conglomerates, Johnson & Johnson and 3M occupy positions anchored by sterile infrastructure investments that secure tier-one burn center contracts. Smith & Nephew PLC exemplifies the specialized wound care archetype through matrix technology platforms that integrate antimicrobial delivery with moisture retention. Sun Pharmaceutical Industries Ltd represents the emerging economy generic manufacturer archetype leveraging India's CDSCO accelerated pathways to capture government tender volumes.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Smith & Nephew PLC |
| ConvaTec Group PLC |
| Pfizer Inc. |
| GlaxoSmithKline PLC |
| Perrigo Company PLC |
| Sun Pharmaceutical Industries Ltd |
| 3M |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Tier-one burn centers in Boston, London, and Singapore concentrate procurement influence through multi-year sterile manufacturing commitments, anchoring contract-based pricing that bundles ointment formulations with advanced dressing technologies. This buyer concentration elevates supply security guarantees over unit cost minimization in vendor selection criteria.
Pricing Analysis
Outcome-linked pricing anchors procurement negotiations as hospitals prioritize infection rate reduction and nursing intervention frequency over per-tube cost. Three-tier pricing structure across premium hydrofiber-matrix formulations, standard silver sulfadiazine creams, and economy bacitracin ointments reflects certification grade and sterile manufacturing infrastructure. Pricing pressure stems from silver commodity volatility compressing margins on sulfadiazine-based volume leaders. Government tender channels in India and Brazil exhibit highest price sensitivity, while North American academic medical centers prioritize supply reliability.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Brazil's ANVISA localization requirements are reshaping active pharmaceutical ingredient sourcing for multinational manufacturers. Supply concentrates in India for generic formulation production, the United States for sterile finished goods, and China for silver compound raw materials. Formulation scientists with dual antimicrobial-biocompatibility expertise represent a critical bottleneck extending development timelines. Single-source vulnerability in silver sulfadiazine precursor supply creates exposure to commodity price swings. Distribution runs through government tender mechanisms in emerging economies and GPO contracts in North American hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The burn ointment market is becoming a vertical-integration race as manufacturers pursue captive sterile production infrastructure to secure tier-one burn center contracts. Control over hydrofiber matrix technology and antimicrobial formulation capabilities represents the decisive upstream lever.
For Market Incumbents: Extend sterile manufacturing footprints through dedicated facility investments in Maharashtra and São Paulo to anchor government tender participation. Lock in multi-year supply security commitments with Boston and London academic medical centers before formulary consolidation accelerates. Prioritize hydrofiber-antimicrobial convergence R&D to defend against hydrocolloid dressing substitution threats. For New Entrants and Emerging Players: CDSCO emergency use pathways in India open a window for bioactive peptide formulations targeting EU Green Deal compliance gaps in European hospital networks. Target outpatient services in Germany and France with lidocaine-containing analgesic protocols as ambulatory care models displace inpatient observation. Pursue direct hospital contracting bypassing wholesale distribution through sterile infrastructure partnerships. For Investors and Strategic Acquirers: The window for entry favors specialized wound care pure-plays with matrix technology platforms over diversified healthcare conglomerates. Target mid-cap manufacturers with demonstrated CDSCO registration success and captive hydrofiber production capabilities. Watch FDA antimicrobial safety review outcomes as the inflection signal for silver sulfadiazine formulary exclusions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive silver sulfadiazine supply mitigates commodity volatility exposure for tier-one manufacturers. |
| Hydrofiber Matrix Technology Licensing | Smith & Nephew's moisture retention platforms demonstrate antimicrobial delivery integration potential. |
| CDSCO Emergency Pathway Registration | Accelerated timelines in India reshape market access dynamics for reformulated topical agents. |
| Sterile Manufacturing Certification Investment | FDA and EMA compliance enables multi-year supply contracts with academic medical centers. |
| EU Green Deal Compliance Repositioning | Bio-based formulation portfolios capture procurement preference shifts in German hospital networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving hospital procurement managers, formulary committee directors, pharmaceutical R&D leads, and burn center clinicians. FDA 510(k) submissions, EMA MDR conformity assessments, CDSCO registration databases, and Brazilian ANVISA filings provided regulatory pathway documentation. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from sterile manufacturing capacity assessments.
Segment-level granularity modeled product type, application severity, end-user institution class, and regional regulatory cluster across the projection horizon. CAGRs derived from infection protocol adoption curves, outpatient care shift rates, and government tender volume trajectories. Hydrocolloid dressing substitution rates and antimicrobial stewardship mandate implementation timelines served as critical forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for hydrogel-based bioactive peptide formulations would alter the outlook if European hospital networks accelerate silver sulfadiazine exclusions. Silver commodity price trajectories and FDA safety review conclusions represent additional forecast revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market