
 Global Medical Protective Equipment Market | 2026-2036
Global Medical Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Protective Equipment Market Foresight
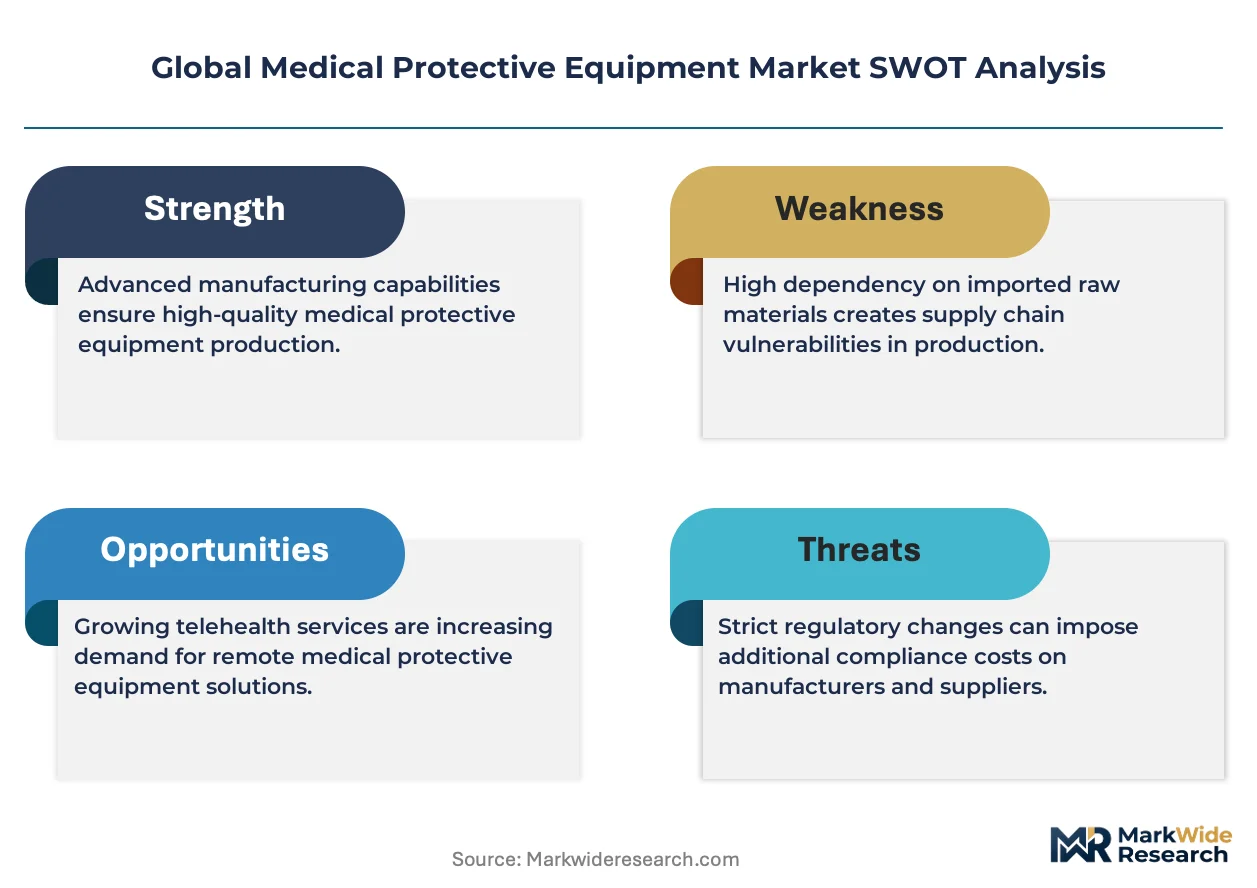
ISO 13485 certification is bifurcating the competitive landscape into qualified medical-grade suppliers and commoditized industrial entrants. 3M Company leverages its integrated filtration technology platform to sustain premium positioning across respirator categories. Ansell Limited anchors its market presence through specialized glove manufacturing scale in Southeast Asian production clusters. DuPont de Nemours, Inc. differentiates via advanced nonwoven fabric technologies that command preference in high-risk surgical environments.
Medical protective equipment encompasses barrier garments, respiratory devices, hand protection, and facial coverage engineered to specified AAMI liquid-borne pathogen resistance levels or NIOSH filtration efficiency thresholds, primarily manufactured through meltblown polypropylene extrusion, spunbond lamination, or nitrile latex dipping processes to prevent occupational exposure to infectious agents. Gloves and respirators occupy the largest revenue pools due to recurring consumption volumes, while protective gowns compete on AAMI-level certification tiers that segment margin structures across standard and high-barrier applications. Pharmaceutical Manufacturing as an application dimension is gaining structural weight as aseptic processing regulations tighten containment requirements for sterile drug production environments.
FDA 510(k) clearance pathways and the EU MDR's reinforced notified body oversight are elevating compliance costs and extending time-to-market for new entrants, effectively consolidating procurement relationships around established certificate holders. NIOSH certification for N95 respirators and OSHA bloodborne pathogen standards in the United States, alongside China's NMPA medical device registration requirements, create multi-jurisdictional qualification burdens that favor suppliers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving pandemic treaty negotiations and national stockpile replenishment cycles to anticipate demand surges that disrupt baseline forecasting models.
Market Dynamics
ISO 13485 certification requirements are bifurcating the competitive landscape into qualified medical-grade suppliers and commoditized industrial entrants, forcing procurement consolidation around established certificate holders.
Growth Catalysts
- EU MDR conformity assessment:Stricter notified body oversight for Class I medical devices elevates entry barriers and consolidates procurement relationships around established suppliers with dedicated regulatory affairs infrastructure.
- Aseptic pharmaceutical processing:Tightened containment regulations for sterile drug production environments expand addressable demand beyond traditional healthcare into pharmaceutical manufacturing facilities.
- National stockpile replenishment:Strategic reserve expansion in the United States, Germany, and China generates non-cyclical procurement volumes that buffer baseline demand forecasting models.
Market Restraints
- Nitrile latex input volatility:Petrochemical feedstock price swings and concentrated Malaysian-Thai rubber production clusters expose glove manufacturers to margin compression without pricing power.
- FDA 510(k) timeline extension:Elevated compliance documentation requirements and reviewer backlogs stretch time-to-market for novel barrier garment designs beyond eighteen months.
- Reusable surgical textile substitution:Advanced laundering technologies and life-cycle cost pressures in budget-constrained hospital systems threaten single-use gown volumes in standard-risk procedures.
Strategic Opportunities
- India's CDSCO medical device registration:Underdeveloped domestic manufacturing capacity and expanding hospital infrastructure create first-mover positioning for ISO-certified foreign suppliers.
- Wearable sensor integration:Convergence of biometric monitoring fabrics with AAMI-level barrier materials enables real-time exposure detection in high-risk surgical environments.
- Direct-to-health system e-procurement:Bypassing traditional distributor markups through GPO-integrated digital platforms captures margin and locks in multi-year supply agreements.
Industry Challenges
- NIOSH certification queue congestion:Respirator testing laboratory capacity constraints create twelve-to-eighteen-month approval backlogs that strand finished goods inventory.
- Meltblown polypropylene equipment scarcity:Specialized extrusion line engineering talent and long-lead machinery orders throttle capacity expansion for high-filtration media producers.
- Legacy ERP integration friction:Hospital procurement systems' rigid contract management modules resist real-time inventory visibility tools that would enable vendor-managed replenishment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Protective Equipment Market |
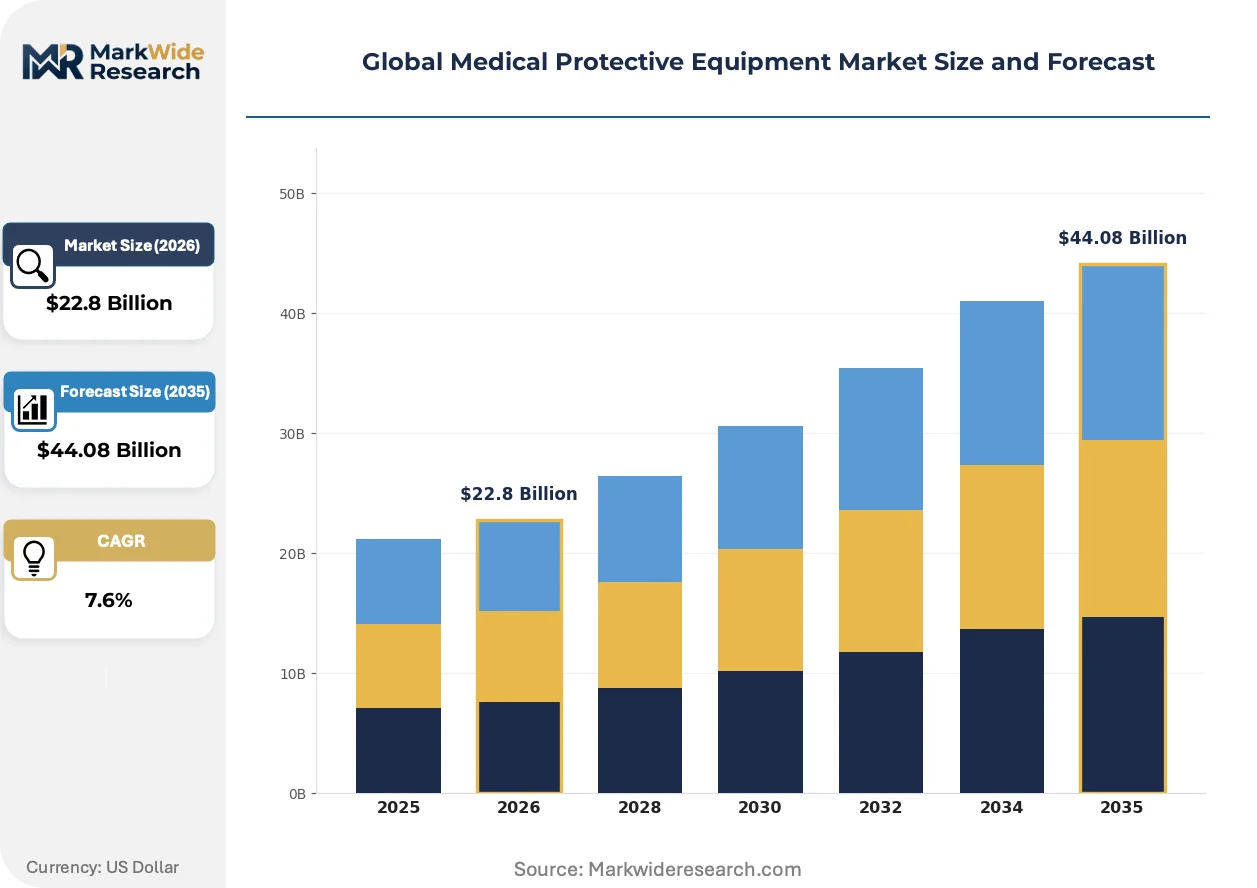
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
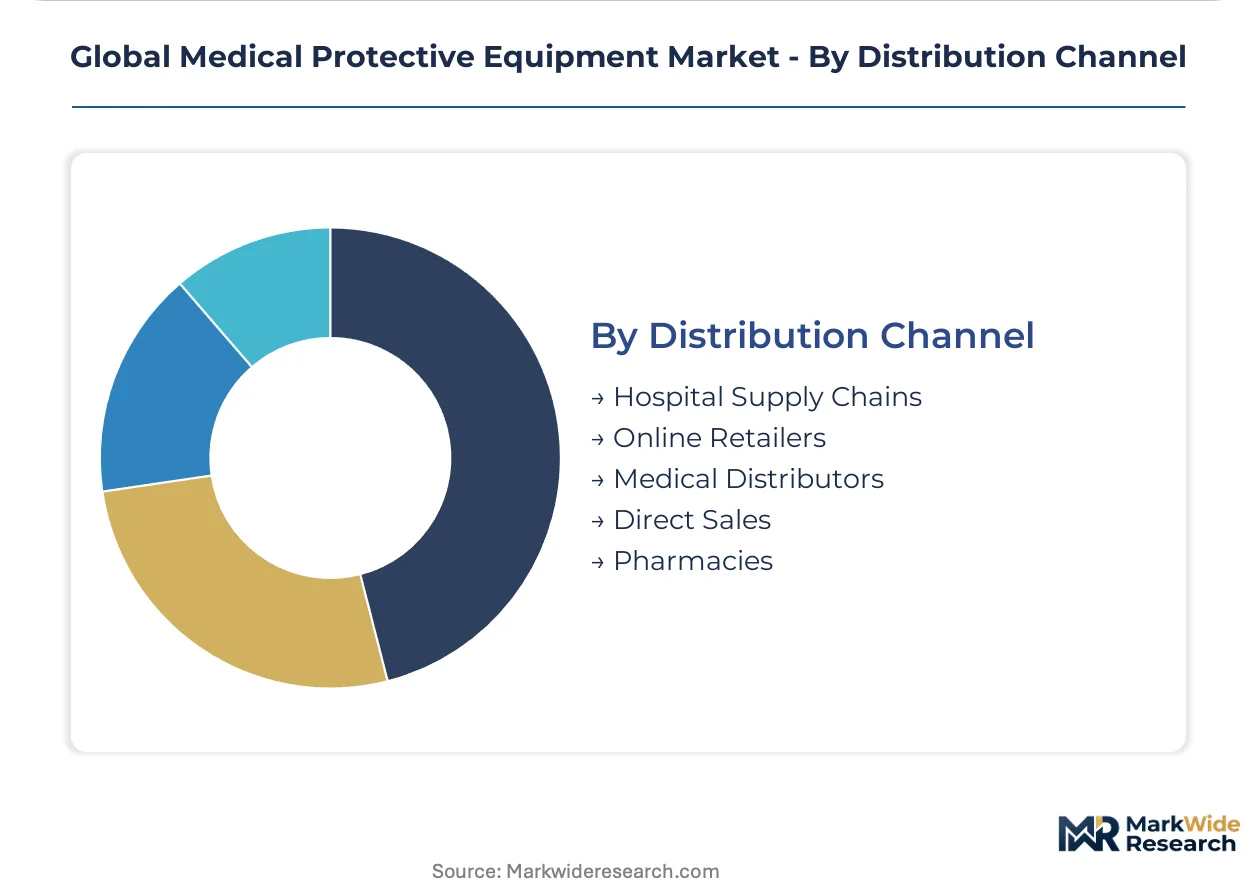
| Segmentation | Product Type: Surgical Masks, Respirators, Protective Gowns, Face Shields, Gloves Application: Infection Control, Emergency Response, Laboratory Work, Public Health, Pharmaceutical Manufacturing End User: Hospitals, Diagnostic Laboratories, Clinics, Pharmaceutical Companies, Emergency Medical Services Distribution Channel: Hospital Supply Chains, Online Retailers, Medical Distributors, Direct Sales, Pharmacies |
| Companies Covered | 3M Company, Ansell Limited, Top Glove Corporation Bhd, DuPont de Nemours, Inc., Kimberly-Clark Corporation, Honeywell International Inc., MSA Safety Inc., Alpha ProTech, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Protective Equipment Market Shifts & Advancements
Advanced material platforms and regulatory digitization are compressing product development cycles while reshaping how protective equipment performance is verified and procured across healthcare systems.
Electrospun nanofiber membranes are supplanting conventional meltblown polypropylene in next-generation respirator media, delivering sub-micron filtration efficiency at reduced breathing resistance. Intensive care units and surgical suites in tertiary hospitals are piloting these materials for extended-wear applications. This substitution is supplanting established supply relationships as performance specifications rewrite procurement evaluation criteria.
The EU MDR's Unique Device Identification mandate and enhanced post-market surveillance requirements impose traceability infrastructure investments across the value chain. Manufacturers must deploy serialized production tracking and adverse event reporting systems that interface with EUDAMED. High-barrier surgical gown suppliers face disproportionate compliance burdens as Class I device reclassification triggers notified body involvement previously exempted.
Hospital systems are consolidating purchasing decisions through centralized supply chain offices that negotiate enterprise-wide contracts replacing department-level autonomy. This concentration transfers price negotiation leverage from individual clinicians to procurement executives with formal total-cost-of-ownership frameworks. The United States exhibits the most pronounced shift as integrated delivery networks absorb independent facilities and standardize formulary decisions across multistate footprints.
Global Medical Protective Equipment Market Segmentation
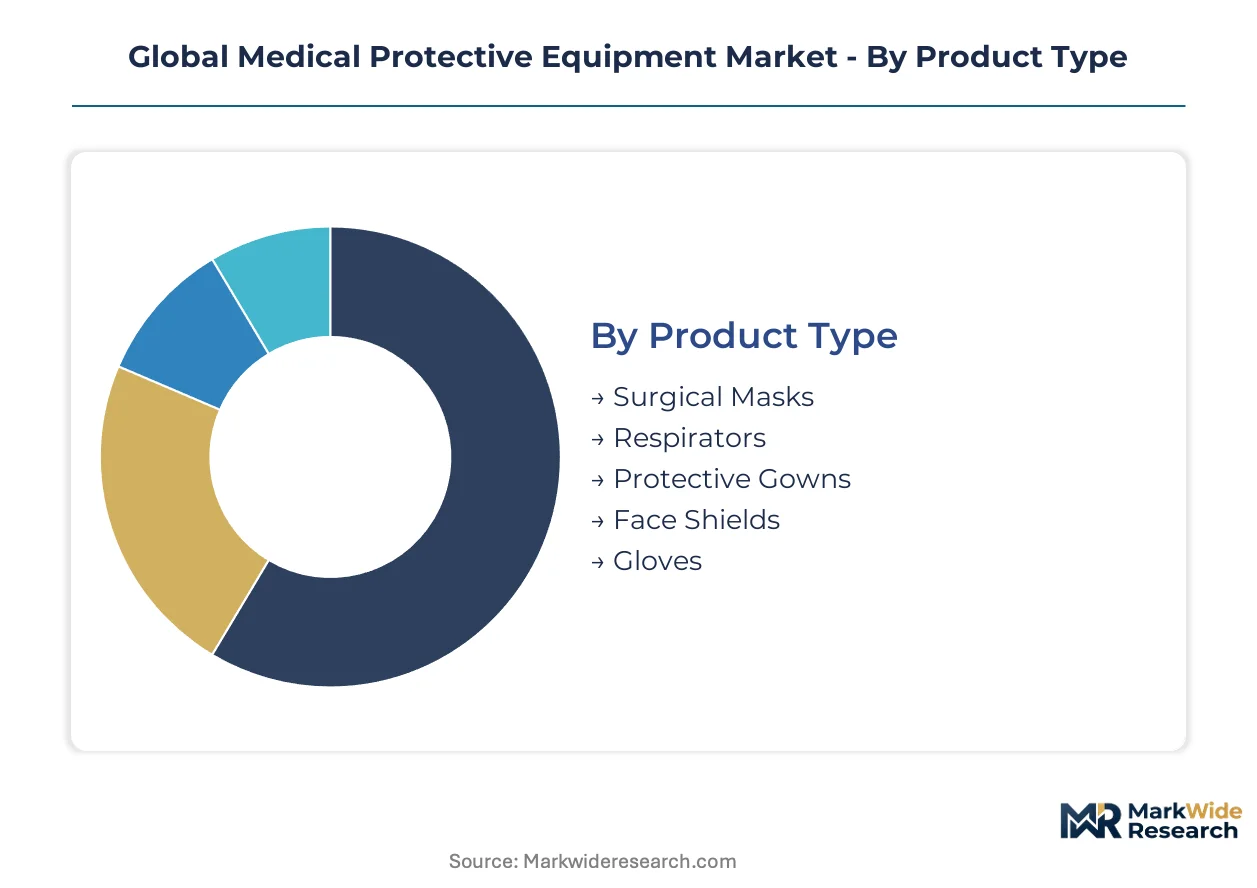
Medical protective equipment procurement flows through highly stratified channels where product specifications, regulatory certification tiers, and end-user risk profiles determine route-to-market economics. Segmentation reveals how ISO 13485-qualified manufacturers capture premium hospital contracts while commoditized suppliers compete through distributor networks for lower-specification applications.
Product Type:
Hospital supply chains and medical distributors dominate volume flows for high-barrier products requiring certificate-of-analysis documentation, while online retailers and pharmacies capture standardized consumables with lower regulatory documentation burdens.
- Gloves:Nitrile and latex formulations manufactured through dipping processes dominate recurring consumption volumes in surgical and examination applications. Demand concentrates in tertiary hospital systems across the United States, Germany, and China as these markets enforce OSHA bloodborne pathogen standards and mandate higher puncture-resistance specifications for frontline workers.
- Respirators:NIOSH-certified N95 and equivalent FFP2/FFP3 devices engineered through meltblown polypropylene filtration media command premium positioning in high-risk aerosol-generating procedures. Procurement clusters around national stockpile replenishment cycles in the United States, Germany, and China, where strategic reserve mandates buffer baseline demand forecasting.
- Protective Gowns:AAMI-level certified barrier garments compete on liquid-borne pathogen resistance tiers from Level 1 to Level 4.
- Surgical Masks:ASTM F2100-rated filtration devices serve standard precaution protocols in routine clinical encounters.
- Face Shields:Polycarbonate or PET splash protection supplements respiratory devices in droplet precaution scenarios.
By volume, gloves lead procurement flows across all channels. By growth pace, respirators are climbing the fastest as pandemic preparedness mandates permanently elevate strategic reserve requirements.
Application:
Cost tier stratification separates capital-intensive containment infrastructure from consumable-driven recurring demand, with pharmaceutical manufacturing and emergency response commanding premium pricing against standardized infection control protocols.
- Infection Control:Standard precaution and transmission-based protocols in acute care settings drive baseline consumption of gloves, masks, and gowns through hospital supply chain contracts. Demand concentrates in integrated delivery networks across the United States as these systems consolidate formulary decisions and standardize barrier-performance specifications across multistate footprints.
- Pharmaceutical Manufacturing:Aseptic processing regulations for sterile drug production impose ISO 14644 cleanroom-compatible garment requirements and continuous monitoring protocols. Facilities in Germany and the United States lead adoption as FDA and EMA tighten containment validation standards for biologics and injectable therapies.
- Emergency Response:Mobile medical units and disaster relief operations require rapid-deployment protective kits with extended-wear capabilities.
- Laboratory Work:Biosafety level-rated containment protocols drive specialized glove and respiratory selection for pathogen handling.
- Public Health:Community vaccination campaigns and screening programs generate surge demand for standardized masks and face shields.
By volume, infection control absorbs the majority of unit flows. By margin expansion, pharmaceutical manufacturing is gaining share fastest as regulatory complexity erects barriers to commoditized supply.
End User:
Customer type determines contract structure, with hospitals negotiating multi-year enterprise agreements while smaller clinical settings purchase through distributor tier pricing.
- Hospitals:Tertiary and community acute care facilities anchor procurement volumes through centralized supply chain offices replacing department-level autonomy. The United States exhibits the most pronounced concentration as integrated delivery networks absorb independent facilities and deploy total-cost-of-ownership frameworks for barrier garment selection.
- Pharmaceutical Companies:Sterile manufacturing operations require validated supply chains with serialized production tracking and adverse event reporting systems interfacing with FDA and EUDAMED databases.
- Diagnostic Laboratories:High-throughput testing facilities consume specialized respiratory and hand protection for biological specimen handling.
- Clinics:Outpatient and ambulatory settings purchase through group purchasing organization contracts or medical distributor networks.
- Emergency Medical Services:Pre-hospital care providers require ruggedized, rapid-don protective equipment for field deployment.
By absolute spend, hospitals dominate procurement value. By contract sophistication, pharmaceutical companies are advancing fastest as EU MDR traceability mandates force infrastructure investment.
Distribution Channel:
Supply concentration in specialized extrusion and dipping equipment creates channel power asymmetries, with direct sales capturing strategic accounts and medical distributors serving fragmented clinical demand.
- Hospital Supply Chains:Integrated delivery network procurement offices negotiate enterprise-wide contracts with ISO 13485-certified manufacturers, bypassing traditional distributor markups. The United States leads this structural shift as multistate health systems consolidate purchasing decisions through centralized supply chain offices.
- Medical Distributors:Regional and national distributors maintain inventory positions for mid-tier hospitals and independent clinics requiring rapid fulfillment without certificate-of-analysis complexity.
- Direct Sales:Large pharmaceutical manufacturers and national laboratory networks establish direct supplier relationships for validated cleanroom garment programs.
- Online Retailers:E-procurement platforms capture standardized mask and glove demand from smaller clinical settings and non-acute care providers.
- Pharmacies:Community and retail pharmacy chains serve individual healthcare workers and small practice consumable replenishment.
By transaction volume, medical distributors process the most individual orders. By contract value migration, hospital supply chains are consolidating fastest as integrated delivery networks absorb purchasing autonomy from individual facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strategic national stockpile mandates and tightened infection control protocols are reshaping procurement patterns across major healthcare markets. Government reserve replenishment cycles and regulatory harmonization initiatives are creating divergent competitive access conditions.
United States
Integrated delivery networks consolidate purchasing through centralized supply chain offices replacing department-level autonomy. OSHA bloodborne pathogen standards and FDA 510(k) clearance pathways elevate compliance burdens for barrier garment entrants. Boston and Minneapolis medical technology clusters host specialized filtration media engineering capabilities serving NIOSH certification requirements.
Germany
EU MDR conformity assessment and Unique Device Identification mandates force traceability infrastructure investments across the value chain. EMA tightened containment validation standards for sterile drug production expand pharmaceutical manufacturing demand. Baden-Württemberg and North Rhine-Westphalia industrial regions concentrate advanced nonwoven fabric production for high-barrier surgical applications.
China
NMPA medical device registration requirements and strategic national stockpile expansion generate non-cyclical procurement volumes. Dual carbon goals and domestic manufacturing capacity investments reshape supplier qualification criteria. Yangtze River Delta production clusters dominate meltblown polypropylene extrusion capacity for respirator media supply.
India
CDSCO medical device registration framework and expanding hospital infrastructure create positioning opportunities for ISO-certified foreign suppliers. PLI scheme incentives attract domestic manufacturing investment for glove and mask production. Maharashtra and Gujarat pharmaceutical manufacturing corridors drive cleanroom-compatible garment demand for aseptic processing operations.
Global Medical Protective Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with integrated material science platforms alongside specialized protective equipment pure-plays. Market structure exhibits tiered consolidation with premium positions held by certificate-rich incumbents and price-competitive pressure from industrial entrants seeking medical-grade qualification. Two strategic archetypes dominate: integrated material technology platforms leveraging backward control over filtration media supply, and specialized manufacturers scaling through Southeast Asian production clusters. Competitive moves center on regulatory certificate accumulation and direct-to-health system e-procurement platform development.
Within the diversified industrial tier, 3M Company and DuPont de Nemours, Inc. exemplify material science platform strategies. Ansell Limited anchors the specialized manufacturing archetype through production scale concentration. These three occupy positions reflecting divergent paths to competitive positioning—integrated technology control versus geographic manufacturing optimization.
| Leading Market Players |
|---|
| 3M Company |
| Ansell Limited |
| Top Glove Corporation Bhd |
| DuPont de Nemours, Inc. |
| Kimberly-Clark Corporation |
| Honeywell International Inc. |
| MSA Safety Inc. |
| Alpha ProTech |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates simultaneously determine supplier qualification tiers and price differentiation bandwidth, with certificate holders commanding AAMI-level premiums while uncertified industrial entrants compete on spot-market nitrile glove pricing. This regulatory filter compresses margin structures at the commodity end while insulating premium positions for NIOSH-certified respirator manufacturers with dedicated regulatory affairs infrastructure.
Pricing Analysis
Cost-plus contracts with nitrile latex indexation dominate glove procurement, tying hospital system payments to Malaysian-Thai petrochemical feedstock benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates AAMI Level 4 surgical gowns from Level 1 examination gloves, with certification grade and volume scale as primary differentiation levers. Pricing pressure stems from reusable surgical textile substitution in budget-constrained US hospital systems. Integrated delivery networks exhibit lowest price sensitivity due to total-cost-of-ownership frameworks, while independent clinics purchasing through distributor tier pricing show highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites nitrile latex feedstock security for Southeast Asian glove manufacturers concentrated in Malaysia and Thailand. Meltblown polypropylene capacity clusters in China's Yangtze River Delta and Germany's Baden-Württemberg region, drawing from petrochemical feedstocks and specialized extrusion engineering talent. Single-source vulnerability concentrates in Malaysian-Thai rubber production clusters exposed to climate and labor disruptions. Distribution runs through hospital supply chains for integrated delivery networks and medical distributors for fragmented clinical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical protective equipment market sits in early-cycle expansion as pandemic treaty negotiations and national stockpile replenishment mandates permanently elevate baseline consumption above pre-crisis levels.
For Market Incumbents: Consolidate procurement relationships through GPO-integrated e-procurement platforms that bypass distributor markups and lock in multi-year supply agreements. Deepen backward integration into meltblown polypropylene filtration media to defend against electrospun nanofiber substitution threatening established respirator specifications. Prioritize EU MDR traceability infrastructure investments to capture pharmaceutical manufacturing demand as EMA containment validation standards tighten.
For New Entrants and Emerging Players: Anchor in India's CDSCO registration framework where underdeveloped domestic manufacturing capacity and expanding hospital infrastructure create first-mover positioning for ISO-certified foreign suppliers. Target pharmaceutical manufacturing cleanroom garment programs where regulatory complexity erects barriers to commoditized supply. Pursue direct sales relationships with large laboratory networks as an entry vector bypassing entrenched hospital supply chain incumbency.
For Investors and Strategic Acquirers: EU MDR's Unique Device Identification mandate reshapes the acquisition landscape toward certificate-rich manufacturers with serialized production tracking already deployed. Five-to-ten year viability favors specialized protective equipment pure-plays with dedicated regulatory affairs infrastructure over diversified industrial conglomerates seeking medical-grade qualification. Watch NIOSH certification queue congestion as an inflection signal—laboratory capacity constraints that strand finished goods inventory create distressed acquisition opportunities for well-capitalized buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Certificate holders capture premium hospital contracts as FDA and EU MDR elevate entry barriers. |
| NIOSH Certification Fast-Track | Respirator manufacturers bypass twelve-to-eighteen-month approval backlogs that strand competitor inventory. |
| Direct-to-Health System E-Procurement | Digital platforms capture margin and lock in multi-year agreements with integrated delivery networks. |
| Electrospun Nanofiber R&D Partnership | Next-generation filtration media supplants meltblown polypropylene in tertiary hospital pilot programs. |
| India CDSCO Registration First-Mover | ISO-certified foreign suppliers capture positioning in underdeveloped domestic manufacturing capacity. |
Research Methodology
A standing panel of hospital procurement directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body submissions, NIOSH respirator approval databases, and hospital procurement transaction records. This study combines primary interviews with industry stakeholders and secondary data triangulation through bottom-up volume modeling and top-down market sizing reconciliation.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation dimensions spanning product type, application, end user, and distribution channel. CAGRs derive from regression analysis of historical procurement patterns and scenario-weighted demand drivers including national stockpile replenishment cycles and aseptic pharmaceutical processing expansion. Industry-specific forecast inputs incorporate meltblown polypropylene capacity utilization rates and nitrile latex feedstock price indices.
Material uncertainties — pandemic treaty negotiation outcomes, NIOSH laboratory capacity expansion, and Malaysian-Thai rubber production disruptions — sit outside the modeled envelope. Forecasts reflect assumptions documented in the segmentation and regional frameworks. Practitioners should keep alternative scenarios live as EU MDR implementation timelines and US strategic national stockpile mandate revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Surgical Gowns Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Global Enema Bags Market