
 Medical Gas Market | 2026-2036
Medical Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Gas Market Intelligence
The medical gas supply chain is rebalancing between premium-grade hospital pipeline systems and commodity cylinder fill operations for smaller clinics. Air Liquide leverages its integrated production and distribution network across Western Europe to sustain high-purity output for surgical theaters. Linde anchors North American hospital pipeline contracts through long-term service agreements, while Taiyo Nippon Sanso Corporation competes aggressively in East Asian bulk liquid supply with specialized cryogenic logistics.
Medical gases comprise purified atmospheric and synthetic gases manufactured to pharmacopeial standards exceeding 99.5% purity, delivered via cryogenic distillation or pressure swing adsorption for therapeutic administration. Oxygen dominates product type revenue due to irreplaceable roles in respiratory therapy and emergency resuscitation, while nitrous oxide retains stable anesthesia demand despite environmental scrutiny over greenhouse gas potency. Pipeline systems capture the highest capital commitment among delivery modes as hospitals prioritize uninterrupted flow for intensive care units, though home care cylinders represent the fastest expansion vector as post-acute discharge protocols lengthen.
The US FDA enforces Current Good Manufacturing Practice for medical gas fillers, while the European MDR mandates Unique Device Identification for delivery equipment, collectively elevating compliance costs for cross-border suppliers. Japan's PMDA imposes additional lot-release testing that slows market entry but reinforces quality differentiation among established incumbents. Stakeholders must monitor how carbon accounting frameworks reshape helium sourcing decisions and whether home care reimbursement expansions materially shift delivery mode mix away from institutional pipelines.
Market Dynamics
The medical gas market is rebalancing around home care oxygen delivery as hospital discharge protocols compress length-of-stay metrics and push therapeutic administration into residential settings. This structural shift compresses traditional bulk-liquid pipeline economics while elevating portable cylinder and concentrator logistics.
Growth Catalysts
- Chronic respiratory disease management programs:Government-funded COPD initiatives in the United States, Germany, and Japan are institutionalizing long-term oxygen therapy as standard post-acute care, expanding addressable patient populations beyond acute episodes.
- European MDR Unique Device Identification mandate:Traceability requirements for delivery equipment are forcing supplier consolidation toward qualified manufacturers with documented quality systems, inadvertently advantaging scaled incumbents with compliance infrastructure.
- Cryogenic distillation efficiency gains:Advanced air separation units are lowering unit production costs for high-purity oxygen, enabling margin expansion at price points accessible to smaller clinic customers previously served by premium hospital pipeline contracts.
Market Restraints
- Helium supply concentration:The United States' Bureau of Land Management federal helium reserve depletion and Qatar's blockade-vulnerable export infrastructure create single-source dependency risks for MRI cooling applications and specialized respiratory mixtures.
- European F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are tightening nitrous oxide production emissions standards, elevating compliance capital requirements for anesthesia gas manufacturers without alternative synthesis pathways.
- Home care reimbursement compression:Medicare's competitive bidding program and analogous European health technology assessment frameworks are squeezing cylinder rental margins below sustainable thresholds for independent distributors.
Strategic Opportunities
- India's hospital infrastructure expansion:The country's PLI scheme for medical devices and greenfield specialty hospital construction in tier-2 cities creates first-mover advantage for bulk liquid supply contracts before incumbent networks solidify.
- Remote patient monitoring convergence:Integration of pulse oximetry telemetry with automated oxygen concentrator adjustment is rewriting home care service models toward subscription-based remote therapeutic management.
- Japan's PMDA lot-release testing reciprocity negotiations:Bilateral mutual recognition agreements under discussion would accelerate market entry for pre-qualified European and North American suppliers with established pharmacopeial documentation.
Industry Challenges
- Cryogenic logistics technician scarcity:Specialized handling certification for liquid oxygen transport and storage equipment is concentrating qualified labor pools around major metropolitan distribution hubs, constraining rural service expansion.
- Legacy hospital pipeline integration:Retrofitting aging copper infrastructure for compatibility with digital flow monitoring and automated alarm systems requires capital coordination with facilities management teams unaccustomed to medical gas vendor partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Gas Market |
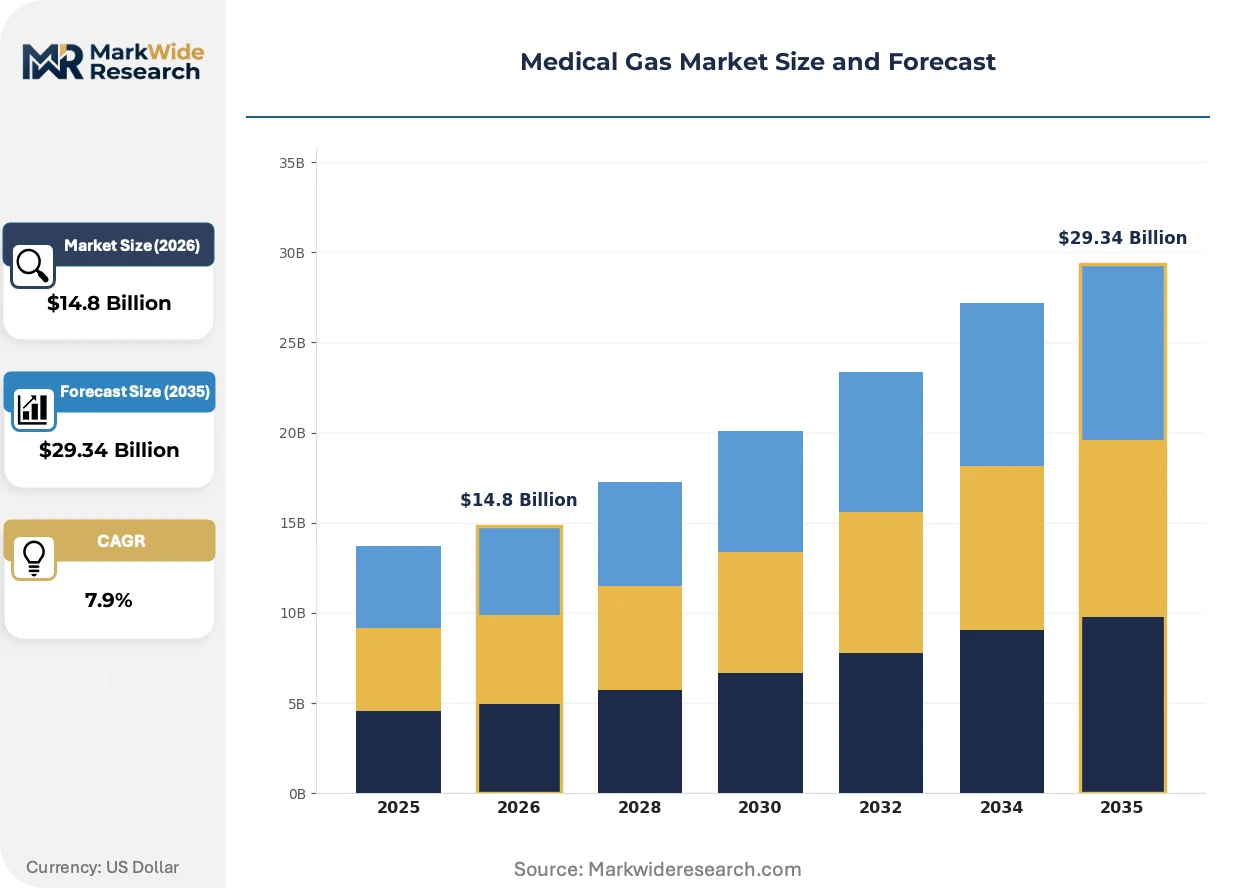
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrous Oxide, Nitrogen, Helium Delivery Mode: Cylinders, Pipeline Systems, Bulk Systems, Liquid Storage End User: Hospitals, Clinics, Home Care, Emergency Services Application: Respiratory Therapy, Anesthesia, Surgery, Diagnostics |
| Companies Covered | Atlas Copco Group, Messer Group, Air Liquide, GCE Group, Airgas, Linde, Taiyo Nippon Sanso Corporation, Allied Healthcare Products, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Gas Market Strategic Shifts & Innovations
Digitalization of gas flow monitoring and predictive maintenance algorithms are compressing service response times while regulatory carbon-accounting frameworks are reshaping sourcing decisions for high-global-warming-potential anesthesia gases.
Pressure swing adsorption portable oxygen concentrators are rewriting access economics for ambulatory patients requiring continuous flow. Home care agencies across the United States are deploying these units to reduce cylinder exchange logistics costs. The technology is compressing traditional liquid oxygen delivery market share in post-acute segments previously dominated by scheduled tank refills.
The European Union's F-Gas Regulation is accelerating nitrous oxide abatement technology deployment across anesthesia gas production facilities. Manufacturers are investing in catalytic destruction systems and alternative synthesis routes to maintain product availability under tightening emissions quotas. Surgical theaters in Germany and France are most affected, with hospital procurement teams now requiring supplier carbon footprint documentation alongside purity certificates.
Consolidated purchasing by multi-hospital health systems is disintermediating traditional independent gas distributors in North American metropolitan markets. Integrated delivery networks in Texas and California are negotiating direct pipeline service agreements with production-scale suppliers, bypassing regional cylinder fill operations. This concentration is visible most acutely in Sun Belt states where private equity-backed hospital rollups have compressed vendor counts to three or fewer per metro area.
Medical Gas Market Segmentation
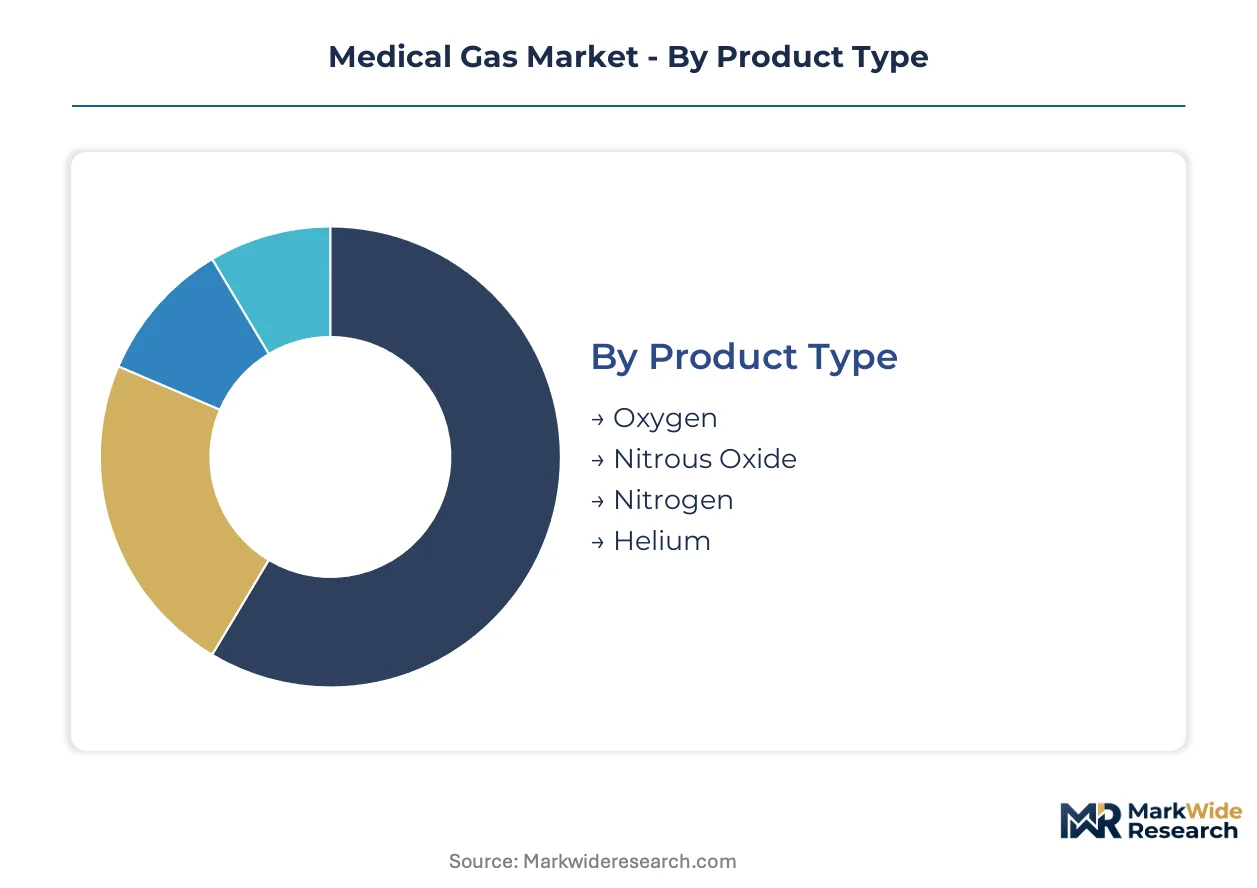
Medical gas segmentation reveals divergent compliance obligations across product categories. Purity thresholds, delivery infrastructure, and end-use applications each impose distinct certification pathways that reshape supplier economics and competitive positioning.
Product Type:
Oxygen, nitrous oxide, and helium each trigger separate pharmacopeial certification tracks under FDA Current Good Manufacturing Practice and European Pharmacopoeia monographs, while nitrogen crosses into both medical and industrial regulatory spheres.
- Oxygen:Purified to exceed 99.5% concentration through cryogenic distillation or pressure swing adsorption. Hospital intensive care units in the United States, Germany, and Japan consume the majority of therapeutic-grade volumes as chronic respiratory disease management programs institutionalize long-term therapy protocols.
- Nitrous Oxide:Synthesized via thermal decomposition of ammonium nitrate with stringent residual impurity controls. Surgical theaters in France and Germany now require supplier carbon footprint documentation alongside purity certificates under tightening EU F-Gas Regulation emissions quotas.
- Nitrogen:Medical-grade specification demands particulate and moisture removal beyond industrial grades. Compressed into cylinders for surgical instrument purging and cryogenic preservation applications.
- Helium:Sourced from concentrated natural gas reserves with Bureau of Land Management allocation dependencies in the United States. MRI cooling applications and specialized respiratory mixtures face single-source supply risks from Qatar's export infrastructure.
Leading the category by volume: Oxygen. Growing fastest: Helium for diagnostic imaging applications.
Delivery Mode:
Capital intensity and service frequency diverge sharply across delivery infrastructure, with pipeline systems demanding decade-long contracting horizons while portable modalities enable rapid market entry.
- Cylinders:Portable aluminum or steel vessels for ambulatory and emergency deployment. Home care agencies across the United States are substituting scheduled tank refills with pressure swing adsorption concentrators to compress logistics costs.
- Pipeline Systems:Copper infrastructure delivering uninterrupted flow to intensive care units and surgical theaters. Retrofitting aging installations for digital flow monitoring requires capital coordination with hospital facilities management teams.
- Bulk Systems:On-site cryogenic storage with vaporization for high-consumption institutional customers. Concentrates procurement power among multi-hospital health systems negotiating direct production-scale supplier agreements.
- Liquid Storage:Dewar vessels maintaining minus 183 degrees Celsius for oxygen and minus 196 degrees Celsius for nitrogen. Specialized handling certification scarcity concentrates qualified technician pools around major metropolitan distribution hubs.
Dominating capital deployment: Pipeline Systems. Expanding most quickly: Cylinders for post-acute residential therapy.
End User:
Procurement sophistication and reimbursement frameworks create tiered customer segments with diverging price sensitivity and technical specification requirements.
- Hospitals:Integrated delivery networks in Texas and California negotiate direct pipeline service agreements, bypassing regional distributors. Consolidated purchasing has compressed vendor counts to three or fewer per metropolitan area in Sun Belt states.
- Clinics:Smaller outpatient facilities served by cylinder fill operations rather than bulk liquid contracts. Advanced air separation unit efficiency gains are enabling margin expansion at price points previously inaccessible to this segment.
- Home Care:Post-acute discharge protocols are pushing therapeutic administration into residential settings. Medicare's competitive bidding program and European health technology assessment frameworks are squeezing cylinder rental margins below sustainable thresholds for independent distributors.
- Emergency Services:Ambulance and first-responder fleets requiring portable high-pressure cylinders with rapid exchange logistics. Demand concentrates in jurisdictions with expanded emergency medical services infrastructure.
Generating highest revenue concentration: Hospitals. Climbing the fastest: Home Care as length-of-stay metrics compress.
Application:
Clinical use cases impose distinct purity, flow rate, and monitoring specifications that segment supplier capabilities and certification portfolios.
- Respiratory Therapy:Continuous and intermittent oxygen administration for chronic obstructive pulmonary disease and acute respiratory failure. Government-funded COPD initiatives in the United States, Germany, and Japan are expanding addressable patient populations.
- Anesthesia:Nitrous oxide and volatile agent delivery with precise mixture control. Catalytic destruction systems and alternative synthesis routes are receiving capital investment to maintain availability under tightening emissions quotas.
- Surgery:Insufflation and instrument purging requiring medical-grade nitrogen and carbon dioxide compatibility. Operating room integration demands uninterrupted supply with automated alarm redundancy.
- Diagnostics:MRI cooling and chromatography carrier gases employing helium and specialized mixtures. Lot-release testing under Japan's PMDA slows market entry but reinforces quality differentiation among established incumbents.
Commanding largest volume share: Respiratory Therapy. Steepest expansion trajectory: Diagnostics as imaging infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American medical gas production through its Gulf Coast industrial corridor, where cryogenic distillation facilities supply hospital pipeline networks across Texas and neighboring states. This concentration shapes continental supply patterns and pricing benchmarks.
United States
Medicare's competitive bidding program for home oxygen equipment is compressing distributor margins while expanding patient access in post-acute settings. The FDA enforces Current Good Manufacturing Practice for medical gas fillers, elevating documentation burdens for cross-border suppliers. Texas and California health systems negotiate direct pipeline agreements, bypassing regional cylinder distributors in Sun Belt metropolitan markets.
Germany
Surgical theaters in Bavaria and North Rhine-Westphalia now require supplier carbon footprint documentation alongside purity certificates under tightening EU F-Gas Regulation emissions quotas. The European MDR mandates Unique Device Identification for delivery equipment, advantaging scaled incumbents with established compliance infrastructure. Industrial clusters around Munich and Frankfurt concentrate advanced air separation unit deployment for high-purity oxygen production.
Japan
Chronic respiratory disease management programs in Kanto and Kansai regions are institutionalizing long-term oxygen therapy as standard post-acute care. The PMDA imposes additional lot-release testing that slows market entry but reinforces quality differentiation among established suppliers. Tokyo and Osaka metropolitan areas concentrate MRI infrastructure driving helium demand for diagnostic cooling applications.
India
The PLI scheme for medical devices and greenfield specialty hospital construction in tier-2 cities creates first-mover advantage for bulk liquid supply contracts. CDSCO pharmacopeial standards govern medical gas purity thresholds for therapeutic administration. Maharashtra and Gujarat industrial corridors attract cryogenic logistics investments to serve emerging hospital infrastructure in Pune and Ahmedabad clusters.
France
Catalytic destruction systems for nitrous oxide abatement are receiving capital investment in production facilities serving Paris and Lyon surgical markets. ANSM oversight reinforces pharmacopeial documentation requirements alongside European MDR harmonization. The Île-de-France region concentrates hospital procurement power through consolidated purchasing by multi-hospital health systems.
Medical Gas Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification infrastructure and cryogenic logistics capabilities. The market exhibits tiered concentration with three to five production-scale suppliers anchoring hospital pipeline contracts in major metropolitan zones, while independent cylinder fill operations serve fragmented clinic and home care segments. Strategic archetypes include integrated industrial gas conglomerates with captive air separation capacity, specialized medical gas distributors with regional logistics networks, and equipment manufacturers bundling delivery systems with gas supply contracts. Competitive moves center on long-term service agreements locking hospital infrastructure and geographic expansion into underpenetrated tier-2 cities before incumbent networks solidify.
Within the integrated conglomerate tier, Air Liquide and Linde occupy positions defined by continental production and distribution scale, with the former leveraging Western European network density and the latter anchoring North American hospital contracts through multi-year service agreements. Taiyo Nippon Sanso Corporation represents the East Asian specialist archetype, competing in bulk liquid supply with cryogenic logistics capabilities. These three entities exemplify how regulatory compliance infrastructure and capital-intensive air separation assets create defensive positioning against commodity-margin entrants.
| Leading Market Players |
|---|
| Atlas Copco Group |
| Messer Group |
| Air Liquide |
| GCE Group |
| Airgas |
| Linde |
| Taiyo Nippon Sanso Corporation |
| Allied Healthcare Products |
| Air Products and Chemicals |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between pharmacopeial pipeline contracts and commodity cylinder fills splits pricing power across distinct supply configurations. Hospital systems in Texas and California pay throughput premiums for uninterrupted ICU flow guarantees, while Medicare competitive bidding compresses home care cylinder margins below sustainable thresholds for independent distributors.
Pricing Analysis
Uptime guarantees anchor value-based pricing for intensive care pipeline contracts, with multi-hospital networks negotiating decade-long service agreements that bundle flow assurance with predictive maintenance. Price differentiation separates FDA-validated bulk liquid supply from non-pharmacopeial industrial grades, with carbon footprint documentation under EU F-Gas Regulation emerging as a secondary premium driver. Cost compression in home care cylinders intensifies because Medicare reimbursement caps outpace logistics inflation, making independent distributors most price-sensitive while integrated conglomerates with captive air separation capacity absorb margin erosion.
Supply Chain Analysis
Cryogenic logistics costs concentrate qualified technician pools around Houston, Munich, and Tokyo metropolitan hubs, elevating last-mile delivery premiums for rural hospital and home care deployments. Production gravity centers on the United States, Germany, and Qatar for helium, with air separation units in Western Europe and East Asia feeding oxygen and nitrogen demand. Supply chain vulnerability rests on Qatar's blockade-exposed helium export infrastructure and the Bureau of Land Management reserve depletion. Distribution runs through direct pipeline service agreements for tier-one hospitals and regional cylinder fill networks for fragmented clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable incumbents as European MDR traceability mandates and FDA Current Good Manufacturing Practice documentation burdens force weaker regional distributors toward exit or acquisition.
For Market Incumbents: Lock in hospital pipeline contracts through multi-year service agreements bundling predictive maintenance with flow monitoring upgrades before greenfield specialty hospital construction in India's tier-2 cities allows competitor network pre-emption. Deepen backward integration into cryogenic logistics certification programs to offset technician scarcity constraining rural expansion, and invest in catalytic destruction systems for nitrous oxide abatement ahead of tightening EU F-Gas Regulation phase-down schedules. For New Entrants and Emerging Players: Enter via remote patient monitoring convergence opportunities where pulse oximetry telemetry integration with automated oxygen concentrator adjustment enables subscription-based therapeutic management models outside incumbent cylinder logistics footprints. Target India's PLI scheme beneficiary hospitals in Pune and Ahmedabad clusters before Air Liquide and Linde bulk liquid networks solidify, and pursue equipment-manufacturer partnerships bundling delivery systems with gas supply contracts to bypass direct production-scale competition. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated industrial gas conglomerates seeking regional cylinder fill network density to complete hospital-to-home care coverage maps, and in specialized medical gas distributors with established European MDR compliance infrastructure. Long-term viability favors targets with captive air separation capacity and documented pharmacopeial certification portfolios. Watch Japan's PMDA lot-release testing reciprocity negotiations as the inflection signal accelerating market entry for pre-qualified European and North American suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Air Separation Capacity | Captive oxygen production insulates margin pressure from industrial gas spot market volatility. |
| Hospital System Partnership | Direct pipeline agreements with Texas and California IDNs bypass regional distributor disintermediation. |
| Reimbursement Strategy | Medicare competitive bidding program navigation determines home care cylinder rental sustainability. |
| CE Marking Pathway | European MDR Unique Device Identification compliance advantages scaled incumbents with quality systems. |
| Software Companion Development | Remote patient monitoring integration rewrites home care economics toward subscription-based models. |
Research Approach
Trade databases, pharmacopeial regulatory filings, and hospital procurement contract registries formed the secondary backbone, cross-referenced against primary interviews with cryogenic logistics technicians, biomedical engineers at integrated delivery networks, GPO contracts managers, and FDA regulatory affairs specialists. Bottom-up patient population modeling for chronic respiratory disease management programs combined with top-down air separation capacity utilization analysis across Western Europe and North America.
Historical trendline analysis of bulk liquid contract pricing and cylinder exchange frequency informed the projection framework, with segmentation across product type, delivery mode, end user, and application dimensions modeled throughout the forecast period. CAGRs derived from cryogenic distillation efficiency gain trajectories and home care reimbursement expansion scenarios, with helium supply concentration risks and F-Gas Regulation compliance capital requirements as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Qatar export disruption or accelerated Bureau of Land Management helium reserve depletion scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Transfusion Bottles Market