
 X-Ray Aprons Market | 2026-2036
X-Ray Aprons Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Aprons Market Analytics
Software-defined lead-equivalence monitoring is expanding how apron vendors monetize patient safety. Infab Corporation leverages proprietary composite formulations to sustain premium positioning in radiation oncology suites. Burlington Medical anchors North American hospital procurement through direct sales relationships with integrated delivery networks. Amray Radiation Protection competes on custom tailoring workflows that reduce fit-related exposure gaps in fluoroscopy labs.
X-ray aprons are personal protective garments engineered with lead, lead-composite, or non-lead attenuating layers—typically 0.25 mm to 0.5 mm lead-equivalence—to shield torso and reproductive organs from scattered ionizing radiation during diagnostic and interventional procedures. Their primary purpose is to reduce cumulative occupational exposure for clinicians performing extended fluoroscopy, CT-guided interventions, and image-guided surgery. Non-lead aprons now command accelerating preference as orthopedic surgical teams seek lighter-weight alternatives for marathon procedures exceeding three hours. Lead aprons retain entrenched demand across budget-constrained dental practices where disposal logistics and upfront cost sensitivity dominate procurement calculus. Custom aprons extract margin premiums from bariatric and pediatric specialists requiring anatomically contoured shielding profiles unavailable in standard sizing matrices.
The FDA enforces lead-equivalence labeling under 21 CFR 1020.32, while the IEC 61331-1 standard governs attenuation performance testing for CE-marked products entering European clinical settings. OSHA's ionizing radiation standard (29 CFR 1910.1096) mandates employer-supplied protective equipment, directly institutionalizing replacement cycles and compliance-driven purchasing. Stakeholders must monitor evolving state-level restrictions on lead content in medical textiles, as California's Proposition 65 litigation trajectory signals potential material formulation disruptions that would cascade through manufacturing specifications and inventory planning.
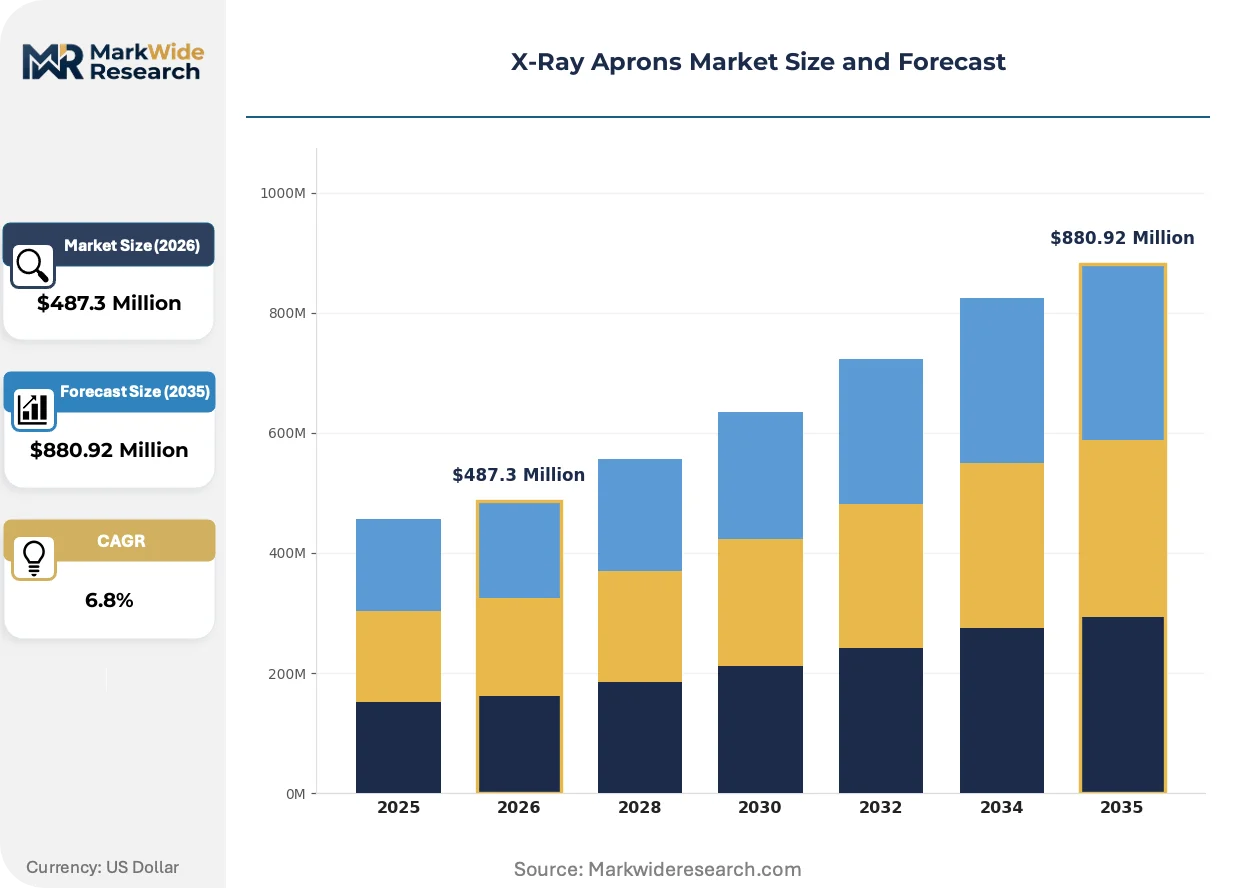
Market Dynamics
Material formulation pressure from the FDA's updated lead-equivalence testing protocols is forcing manufacturers to rebuild composite supply chains while tier-2 hospital expansions in India and Southeast Asian dental clinic procurement simultaneously pull demand in divergent price-performance directions.
Growth Catalysts
- OSHA 29 CFR 1910.1096 Mandates:Employer-supplied protective equipment requirements institutionalize replacement cycles across US healthcare systems. Compliance-driven purchasing sustains baseline volume regardless of discretionary budget pressures.
- Non-Lead Composite Adoption:Orthopedic surgical teams performing procedures exceeding three hours drive preference for lighter-weight attenuating materials. Marathon operative durations make ergonomic weight reduction a clinical necessity rather than preference.
- India Tier-2 Hospital Corridor:Government-backed infrastructure expansion in secondary cities generates concentrated procurement demand for standard and custom apron configurations. Radiology department commissioning timelines accelerate equipment bundling decisions.
Market Restraints
- Lead Price Volatility:Raw material input costs for traditional lead-core aprons fluctuate with commodity metal markets. Budget-constrained dental practices face margin compression when hedging strategies fail.
- California Proposition 65 Litigation Risk:State-level restrictions on lead content in medical textiles create formulation uncertainty. Manufacturers face stranded inventory if California restrictions cascade to other jurisdictions.
- Disposal Logistics Burden:Lead-containing aprons require specialized hazardous waste handling at end-of-life. Small practice buyers absorb premium disposal costs that non-lead alternatives avoid entirely.
Strategic Opportunities
- Software-Defined Monitoring Integration:Embedded sensors enabling real-time lead-equivalence verification create recurring revenue streams. Apron vendors monetize patient safety through subscription diagnostics rather than one-time hardware sales.
- Bariatric and Pediatric Custom Segments:Anatomically contoured shielding profiles unavailable in standard sizing matrices command margin premiums. Specialists require tailored attenuation geometries that generic manufacturers cannot fulfill.
- Integrated Delivery Network Direct Contracts:Bypassing distributor markups through hospital system procurement centralization captures margin. Volume commitments from IDNs stabilize production planning against fragmented clinic demand.
Industry Challenges
- IEC 61331-1 Testing Timeline Compression:CE-marked product validation requires extended attenuation performance verification. European market entry delays revenue recognition for reformulated composite submissions.
- Fit-Related Exposure Gap Mitigation:Custom tailoring workflows must eliminate measurement error in fluoroscopy labs. Poorly fitted aprons create liability exposure that standard sizing matrices cannot address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Aprons Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Aprons, Non-Lead Aprons, Disposable Aprons, Custom Aprons Application: Dental Procedures, Radiology, Orthopedics, Veterinary Use End User: Hospitals, Clinics, Diagnostic Centers, Research Labs Distribution Channel: Online Stores, Medical Supply Stores, Direct Sales, Wholesalers |
| Companies Covered | AADCO Medical, Inc., AliMed Inc., Amray Radiation Protection, Bar-Ray, Burlington Medical, Infab Corporation, Barrier Technologies, BLOXR Solutions, Shielding International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Aprons Market Evolving Landscape
Active material substitution and embedded sensor integration are restructuring how radiation protection equipment delivers value, while procurement centralization concentrates buying power among fewer decision-makers.
Non-lead attenuating layers combining bismuth, tungsten, and antimony compounds are overtaking traditional lead-core construction in premium surgical applications. Orthopedic teams performing extended image-guided procedures adopt these composites at accelerating rates despite 40-60% price premiums. The technology is compressing the addressable market for conventional lead aprons to budget-sensitive dental and veterinary segments.
REACH regulation scrutiny of heavy metal content in medical textiles is tightening material disclosure requirements for CE-marked products entering European clinical settings. Manufacturers must document full chemical composition across supply tiers or risk market withdrawal. Custom apron specialists with captive composite formulation capabilities absorb compliance costs more efficiently than distributors sourcing from opaque Asian foundries.
Hospital procurement committees now unbundle after-sales service from hardware acquisition, forcing apron vendors to compete on discrete maintenance contract terms. Distributor relationships that historically bundled calibration, repair, and replacement are fragmenting into separate competitive events. This behavioral shift is most visible in North American integrated delivery networks where capital equipment committees separate PPE purchasing from biomedical engineering service agreements.
X-Ray Aprons Market Segmentation
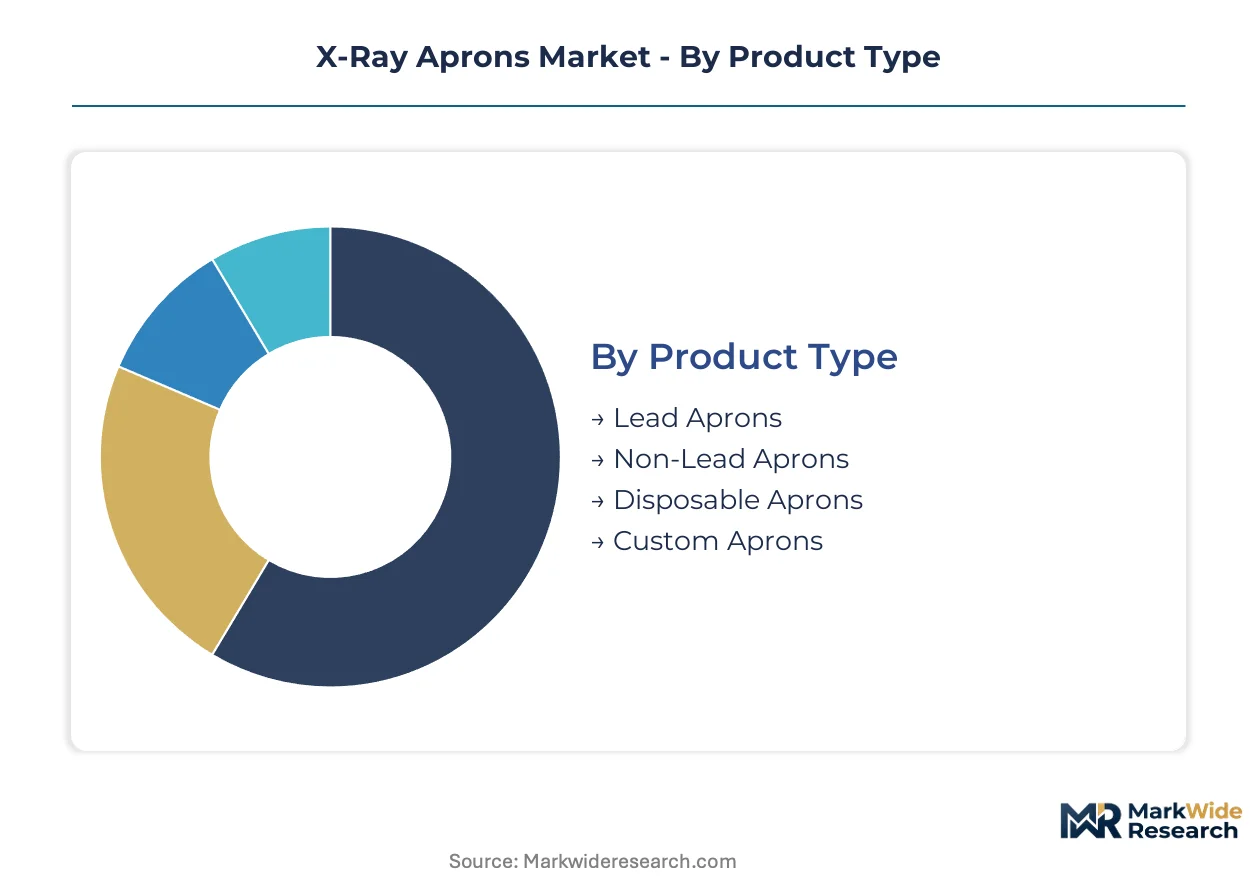
X-ray apron procurement splits across technical specifications, clinical settings, and procurement pathways. Each dimension carries distinct certification burdens and margin profiles that reshape vendor positioning.
Product Type:
FDA 21 CFR 1020.32 governs lead-equivalence labeling for lead-core and lead-composite constructions, while non-lead alternatives face attenuation verification under IEC 61331-1 for CE-marked distribution.
- Lead Aprons:Traditional lead-vinyl or lead-rubber laminates deliver 0.25-0.5 mm lead-equivalence through proven attenuation physics. Budget-constrained dental practices in India's tier-2 cities sustain procurement volume despite ergonomic limitations in marathon procedures.
- Non-Lead Aprons:Bismuth-tungsten-antimony composites achieve equivalent shielding at 30-40% reduced weight. Orthopedic surgical teams performing three-hour-plus image-guided procedures drive accelerating preference despite 40-60% price premiums over lead-core alternatives.
- Disposable Aprons:Single-use attenuating barriers serve emergency departments and isolation protocols where cross-contamination control overrides durability requirements.
- Custom Aprons:Anatomically contoured shielding profiles address bariatric and pediatric specialists requiring sizing matrices unavailable in standard configurations.
Lead Aprons sits at the top of the volume ranking, with Non-Lead Aprons climbing the fastest.
Application:
Procedure duration and radiation scatter intensity determine apron specification tiers, with fluoroscopy-heavy disciplines commanding premium attenuating materials.
- Dental Procedures:Intraoral and panoramic imaging generate intermittent low-dose exposure. Southeast Asian dental clinic procurement concentrates here, with cost sensitivity favoring standard lead-core construction over ergonomic upgrades.
- Radiology:CT-guided interventions and interventional radiology suites require sustained torso shielding during extended fluoroscopy runs. OSHA 29 CFR 1910.1096 mandates institutionalize replacement cycles across US hospital systems.
- Orthopedics:Image-guided spinal and trauma procedures demand lightweight composites for surgeon mobility during lengthy operative durations.
- Veterinary Use:Diagnostic imaging for large animals applies human-equivalent shielding standards with modified sizing for veterinary technician positioning.
Radiology captures the largest revenue pool, while Orthopedics expands most quickly as surgical volume shifts toward minimally invasive techniques.
End User:
Capital equipment bundling decisions and procurement centralization intensity vary sharply across facility types, reshaping vendor channel strategy.
- Hospitals:Integrated delivery networks in North America unbundle PPE purchasing from biomedical engineering service contracts, forcing discrete competitive events for apron hardware.
- Clinics:Fragmented independent practice demand concentrates through distributor relationships that historically bundled calibration and replacement logistics.
- Diagnostic Centers:High-throughput imaging facilities prioritize rapid turnaround on custom sizing and fit verification to minimize clinician downtime.
- Research Labs:Preclinical imaging and radiation biology applications require specialized attenuation geometries for non-standard experimental protocols.
Hospitals dominate absolute procurement value, with Diagnostic Centers gaining share fastest as outpatient imaging volume migrates from inpatient settings.
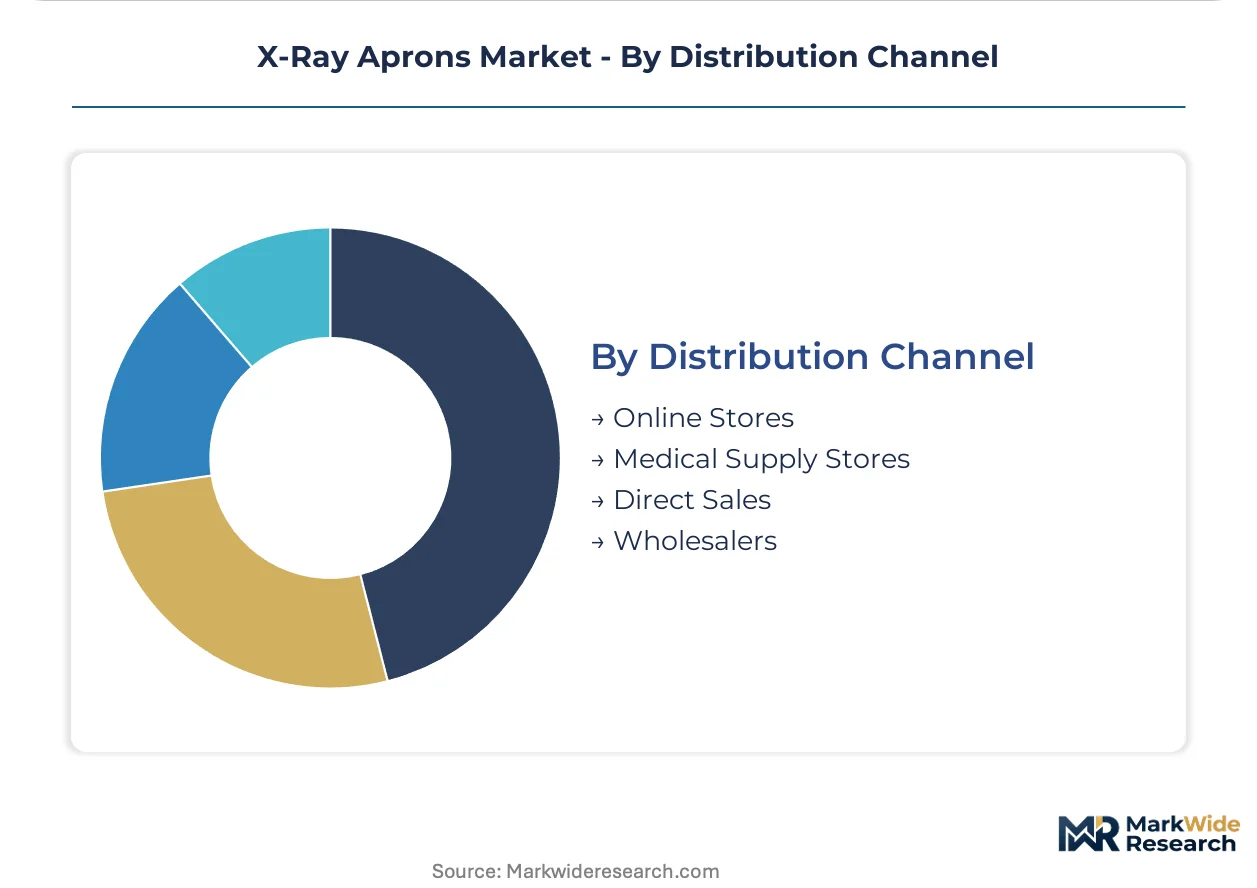
Distribution Channel:
Channel selection directly determines margin capture and customer relationship depth, with direct contracts displacing traditional distributor intermediation.
- Online Stores:E-commerce platforms serve small-practice replacement purchasing with standardized sizing and rapid fulfillment, though fit verification remains a post-purchase friction point.
- Medical Supply Stores:Regional distributors maintain inventory proximity for emergency replacement cycles, absorbing working capital costs that manufacturers avoid.
- Direct Sales:Hospital system procurement centralization enables margin capture through volume commitments and multi-year service agreements bypassing distributor markups.
- Wholesalers:Aggregated demand from fragmented clinic networks stabilizes production planning for manufacturers facing lumpy hospital commissioning timelines.
Direct Sales commands the highest value per transaction, with Online Stores expanding fastest as procurement digitization penetrates smaller practice segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains stricter OSHA enforcement than Germany, yet India's hospital commissioning velocity outpaces both in absolute apron procurement volume.
United States
Integrated delivery networks in Texas and Florida centralize PPE purchasing through capital equipment committees. OSHA 29 CFR 1910.1096 mandates institutionalize replacement cycles across hospital systems. The Greater Boston medical cluster drives demand for custom apron configurations in academic radiation oncology suites.
Germany
REACH regulation scrutiny tightens material disclosure requirements for CE-marked aprons entering European clinical settings. The ECHA documentation burden favors manufacturers with captive composite formulation capabilities. Bavaria's medical technology corridor concentrates precision fabrication capacity for attenuating textiles.
India
Government-backed infrastructure expansion in tier-2 cities generates concentrated procurement demand for standard and custom apron configurations. CDSCO registration requirements govern domestic manufacturing quality standards. The Maharashtra-Gujarat hospital commissioning corridor accelerates radiology department equipment bundling decisions.
China
NMPA medical device registration drives lead-equivalence verification protocols for domestically manufactured aprons. Dual carbon goals pressure manufacturers toward lighter-weight non-lead composite formulations. The Yangtze River Delta medical device cluster scales production for both domestic consumption and export markets.
Japan
PMDA quality management system requirements extend attenuation performance testing timelines for market entry. METI industrial policy supports domestic manufacturing of radiation protection equipment. The Kanto region's imaging equipment ecosystem generates co-located demand for specialized apron configurations.
X-Ray Aprons Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier vendors capturing margin through direct hospital relationships while commodity producers serve fragmented dental clinic demand. The vendor base organizes into three functional tiers: integrated radiation protection conglomerates with captive material science capabilities, regional fabricators specializing in custom tailoring workflows, and distributor-dependent assemblers sourcing opaque Asian supply chains. Dominant competitive moves include backward integration into composite formulation to escape commodity pricing pressure, and multi-year service contract bundling to displace distributor intermediation in North American IDN procurement.
Within the branded specialist tier, Infab Corporation and Burlington Medical exemplify divergent channel strategies—one leveraging proprietary material positioning in radiation oncology, the other anchoring hospital procurement through direct sales relationships. Amray Radiation Protection occupies a position in the custom fabrication segment, where fit-verification workflows address fluoroscopy lab liability exposure that standard sizing matrices cannot mitigate. These three entities collectively represent the strategic archetypes reshaping competitive positioning: material science differentiation, procurement centralization capture, and anatomical customization specialization.
| Leading Market Players |
|---|
| AADCO Medical, Inc. |
| AliMed Inc. |
| Amray Radiation Protection |
| Bar-Ray |
| Burlington Medical |
| Infab Corporation |
| Barrier Technologies |
| BLOXR Solutions |
| Shielding International |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in North America concentrate procurement authority through centralized capital equipment committees, forcing apron vendors into multi-year service contract negotiations that bundle hardware with discrete maintenance pricing. This buyer concentration shifts pricing power toward volume-commitment structures and away from spot-market transactions.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical device cluster are reshaping price floors for standard lead-core aprons sold into Southeast Asian dental markets. Three-tier pricing structure across premium non-lead composites, standard lead-composite hybrids, and economy lead-core constructions stratifies by certification grade and ergonomic weight class. Cost compression in the economy tier is intensifying because Indian tier-2 hospital procurement favors lowest-unit-cost sourcing over lifecycle value. Budget-constrained dental practices in India's secondary cities exhibit highest price sensitivity, while academic radiation oncology suites in the Greater Boston cluster accept 40-60% premiums for custom-contoured shielding profiles.
Supply Chain Analysis
Single-source vulnerability sits with bismuth and tungsten compound suppliers concentrated in China and Vietnam, where non-lead attenuating layer production draws from rare earth processing corridors. Raw material dependencies include lead ingots for traditional aprons, bismuth-tungsten-antimony composites for lightweight alternatives, and medical-grade vinyl laminates for barrier construction. Tariff exposure on Chinese-sourced attenuating compounds threatens margin stability for manufacturers without captive formulation capabilities. Distribution runs through regional medical supply distributors in fragmented clinic segments, while direct sales teams serve consolidated hospital procurement committees in North American IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's tier-2 hospital expansion corridor offers manufacturing cost arbitrage against REACH-regulated European production, with CDSCO registration requirements creating a regulatory moat for early movers establishing domestic formulation capabilities.
For Market Incumbents: Lock in backward integration into bismuth-tungsten composite formulation to escape commodity pricing pressure from Chinese rare earth suppliers. Defend against emerging non-lead specialists by securing multi-year IDN service contracts that bundle real-time lead-equivalence monitoring subscriptions with hardware replacement cycles. Prioritize certification investment in IEC 61331-1 testing infrastructure to compress European market entry timelines for reformulated products. For New Entrants and Emerging Players: OSHA 29 CFR 1910.1096 in the United States opens a window for compliance-driven replacement cycle capture through direct sales relationships with hospital systems seeking to unbundle PPE from biomedical engineering contracts. Target India's Maharashtra-Gujarat hospital commissioning corridor with standard apron configurations priced below European import landed costs. Pursue a go-to-market angle anchored to rapid custom sizing turnaround for bariatric and pediatric specialists underserved by generic manufacturers. For Investors and Strategic Acquirers: Radiation protection conglomerates with captive material science capabilities are the most active acquirer in this space, consolidating regional fabricators to capture custom tailoring workflows. Long-term viability hinges on software-defined monitoring integration transforming hardware vendors into recurring-revenue platform operators. Watch for California Proposition 65 litigation cascades as an inflection signal that would strand lead-core inventory and accelerate non-lead composite substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Formulation | Captive bismuth-tungsten supply chains insulate margin from Chinese rare earth price volatility. |
| Software-Defined Monitoring Integration | FDA 21 CFR 1020.32 compliance verification enables subscription diagnostics revenue streams. |
| CE Marking Pathway Acceleration | IEC 61331-1 pre-validation compresses European revenue recognition delays for non-lead submissions. |
| Hospital System Partnership | IDN direct contracts bypass distributor markups and stabilize production planning against lumpy demand. |
| Custom Sizing Workflow Investment | Anatomically contoured shielding profiles command margin premiums from bariatric and pediatric specialists. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with radiation protection equipment procurement managers, biomedical engineering directors, GPO contracts specialists, and custom apron fabrication technicians with secondary validation against FDA 510(k) filings, CDSCO registration databases, hospital procurement records, and REACH compliance documentation. Bottom-up apron shipment tracking across product type and end-user segments triangulated against top-down healthcare capital equipment spending analysis.
Comparable historical reference periods anchored the projection horizon, with CAGRs derived from segmented demand modeling across lead-core, lead-composite, and non-lead product tiers, procedure volume growth in fluoroscopy and image-guided surgery, and hospital infrastructure expansion patterns in India's tier-2 cities. Industry-specific inputs included OSHA replacement cycle mandates, lead price commodity curves, and REACH material disclosure timeline assumptions.
Revisions become necessary when California Proposition 65 litigation expands to other jurisdictions, when bismuth-tungsten supply disruptions materialize in Chinese processing corridors, or when FDA lead-equivalence testing protocols undergo further amendment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
NPWT Canisters Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Ostomy Care Market