
 Blood Glucose Test Strip Packaging Market | 2026-2036
Blood Glucose Test Strip Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Glucose Test Strip Packaging Market Analysis
Direct-to-pharmacy distribution is reshaping how blood glucose test strip packaging reaches end users, bypassing traditional wholesale layers in major markets. Sanner GmbH leverages its European manufacturing footprint to sustain just-in-time supply contracts with retail pharmacy chains. Amcor competes through multi-layer barrier film technology that extends shelf life in humid climates. Airnov Healthcare Packaging specializes in integrated desiccant systems that control moisture ingress during transit and storage.
Blood glucose test strip packaging refers to engineered primary and secondary enclosures that protect diagnostic reagent strips from moisture, light, and oxidation, typically incorporating aluminum-laminate barriers, silica gel canisters, or molecular sieve inserts to maintain strip enzymatic stability over 18-24 months. Blister packs dominate unit volume due to their unit-dose convenience and compliance-tracking benefits for home care users, while pouch formats capture growth in emerging markets where cost minimization overrides premium features. Plastic and polyethylene materials anchor the material mix, though aluminum barrier layers command margin pools where regulatory scrutiny of moisture vapor transmission rates intensifies.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements shape barrier-performance testing protocols, compelling packaging converters to validate moisture vapor transmission rates below specified thresholds. ISO 11607 standards for sterile barrier systems influence primary packaging design even for non-sterile strips, as manufacturers anticipate regulatory convergence. Stakeholders must monitor evolving EPA guidance on pharmaceutical packaging recyclability and position material choices ahead of anticipated extended producer responsibility mandates.
Market Dynamics
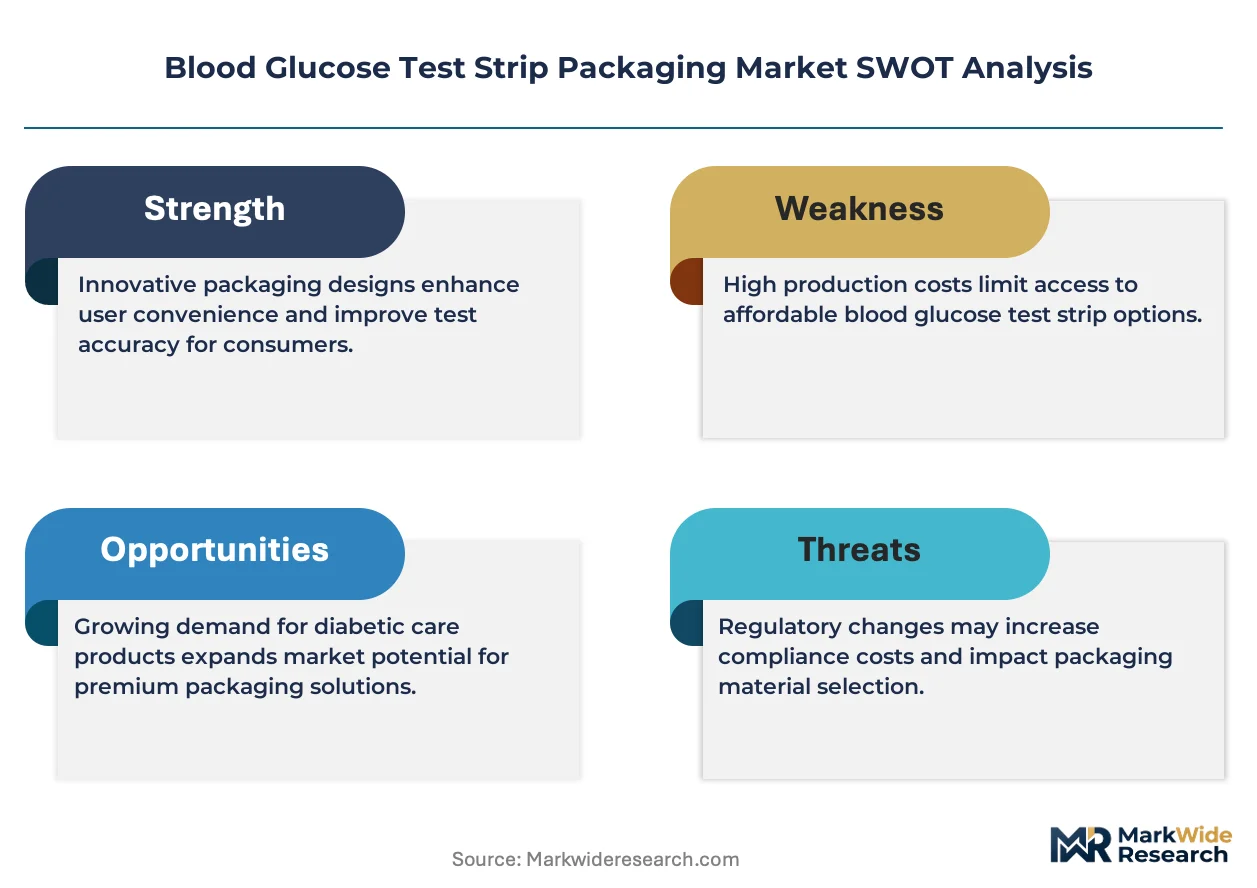
Moisture-barrier validation requirements under FDA 21 CFR Part 820 and EU MDR are forcing packaging converters to redesign material stacks and testing protocols, compressing development cycles while elevating capital intensity for compliant production lines.
Growth Catalysts
- Home care self-monitoring expansion:Diabetes management outside clinical settings drives unit-dose blister demand as patients prioritize portability and compliance tracking in daily routines.
- EU MDR technical documentation mandates:Stricter sterile barrier system standards for diagnostic devices elevate specification requirements for aluminum-laminate primary enclosures.
- Silica gel canister integration:Embedded desiccant systems are migrating from separate inserts to co-laminated film layers, reducing assembly steps and moisture ingress risk during distribution.
Market Restraints
- Aluminum price volatility:Primary barrier metal cost swings compress converter margins and complicate long-term supply contracts with diabetes device manufacturers.
- European converter concentration:Moisture-barrier film production clusters in Germany and Switzerland, creating single-source vulnerability for just-in-time pharmacy contracts.
- Polyethylene recycling friction:Multi-layer laminates resist mechanical separation, exposing brands to anticipated extended producer responsibility penalties under evolving EPA guidance.
Strategic Opportunities
- India pharmacy retail modernization:Organized chain expansion in Mumbai and Delhi creates demand for shelf-ready secondary packaging with humidity indicators and tamper evidence.
- Continuous glucose monitor hybrid formats:Packaging for calibration strip refills in integrated systems opens premium positioning above commodity test strip pouches.
- ISO 11607 sterile barrier convergence:Anticipated regulatory alignment between diabetes diagnostics and implantable devices rewards early adopters of pharmaceutical-grade validation protocols.
Industry Challenges
- Moisture vapor transmission rate certification timelines:ASTM F1249 testing protocols require 90-day validation cycles that delay new product introductions and freeze formulation changes.
- Legacy pouch-to-blister line conversion:Emerging market manufacturers face capital barriers retooling from low-cost pouch formats to compliance-driven unit-dose configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Glucose Test Strip Packaging Market |
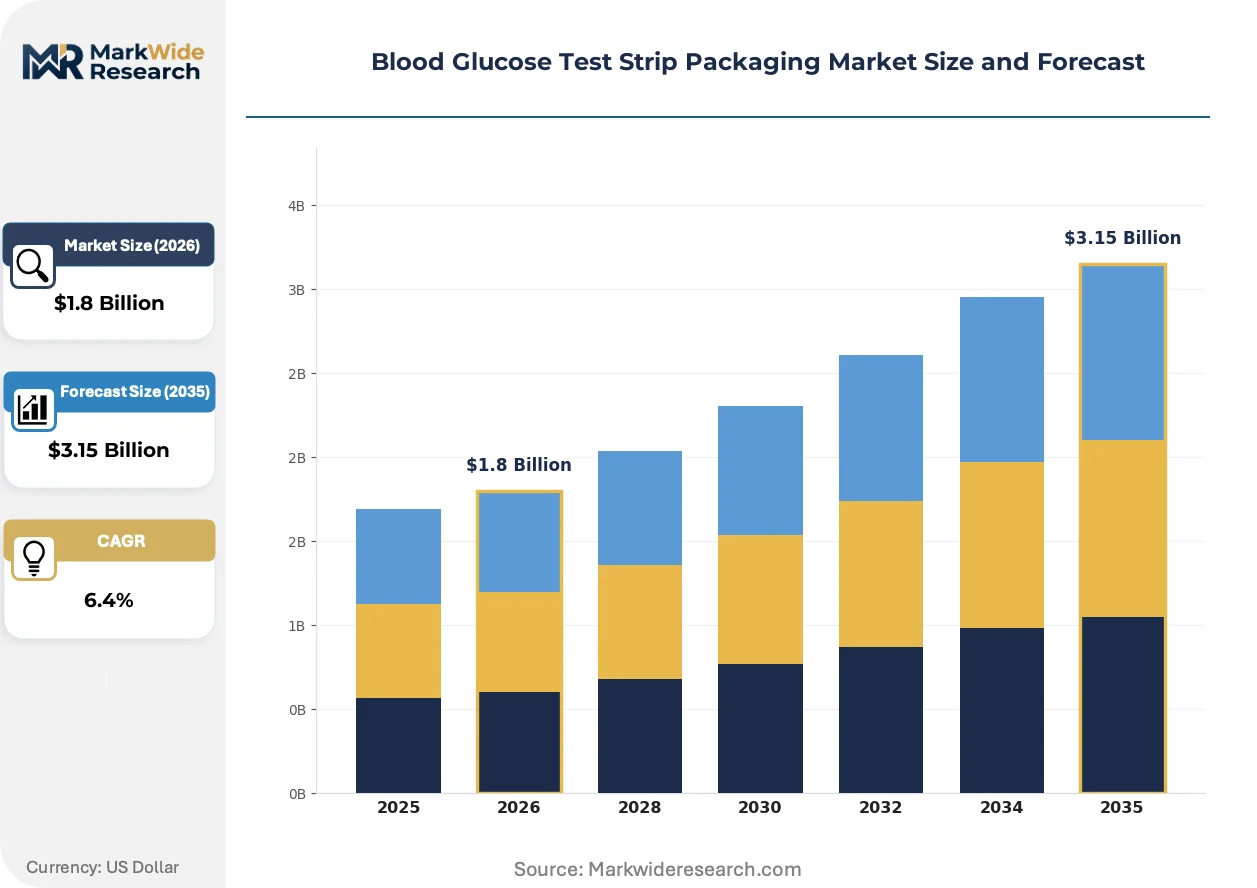
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Bottles, Pouches, Vials Material Type: Plastic, Polyethylene, Aluminum, Paperboard End User: Home Care, Hospitals, Clinics, Laboratories Distribution Channel: Online, Retail Stores, Pharmacies, Direct Sales |
| Companies Covered | Shijiazhuang Xinfuda Medical Packaging, Wisesorbent Technology, Sanner GmbH, HMD, Multisorb, Aptar CSP Technologies, IMPAK Corporation, Amcor, Airnov Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Glucose Test Strip Packaging Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine barrier performance benchmarks, with converters racing to validate next-generation laminates before extended producer responsibility mandates take effect.
Multi-layer coextruded barrier films are migrating from conventional aluminum-oxide coatings to silicon-oxide and aluminum-nitride nanolayers that maintain moisture vapor transmission below 0.1 g/m²/day while enabling near-infrared sortability for recycling streams. European diabetes device manufacturers are piloting these structures for 24-month shelf life claims in humid climates. The shift is compressing demand for legacy metallized polyester configurations and rewiring converter R&D priorities toward thin-film deposition expertise.
EU MDR Annex I general safety and performance requirements now mandate documented evidence of sterile barrier integrity across the claimed shelf life, compelling packaging engineers to implement accelerated aging protocols that exceed prior industry norms. German notified bodies are enforcing stricter interpretation of these clauses for class IIa diagnostic accessories. Converters serving Roche and Sanofi supply chains are responding by integrating redundant seal verification and real-time humidity logging into production workflows.
Direct-to-pharmacy distribution models are displacing traditional wholesale intermediaries in United States and German markets, with retail chains demanding vendor-managed inventory and point-of-sale data sharing. This pattern concentrates purchasing power among CVS Health, Walgreens Boots Alliance, and McKesson procurement teams, who now specify packaging formats optimized for automated dispensing robots rather than manual shelf stocking. The operational shift is most visible in California and Texas, where centralized distribution centers service hundreds of retail locations with uniform carton dimensions and RFID-enabled case labeling.
Blood Glucose Test Strip Packaging Market Segmentation
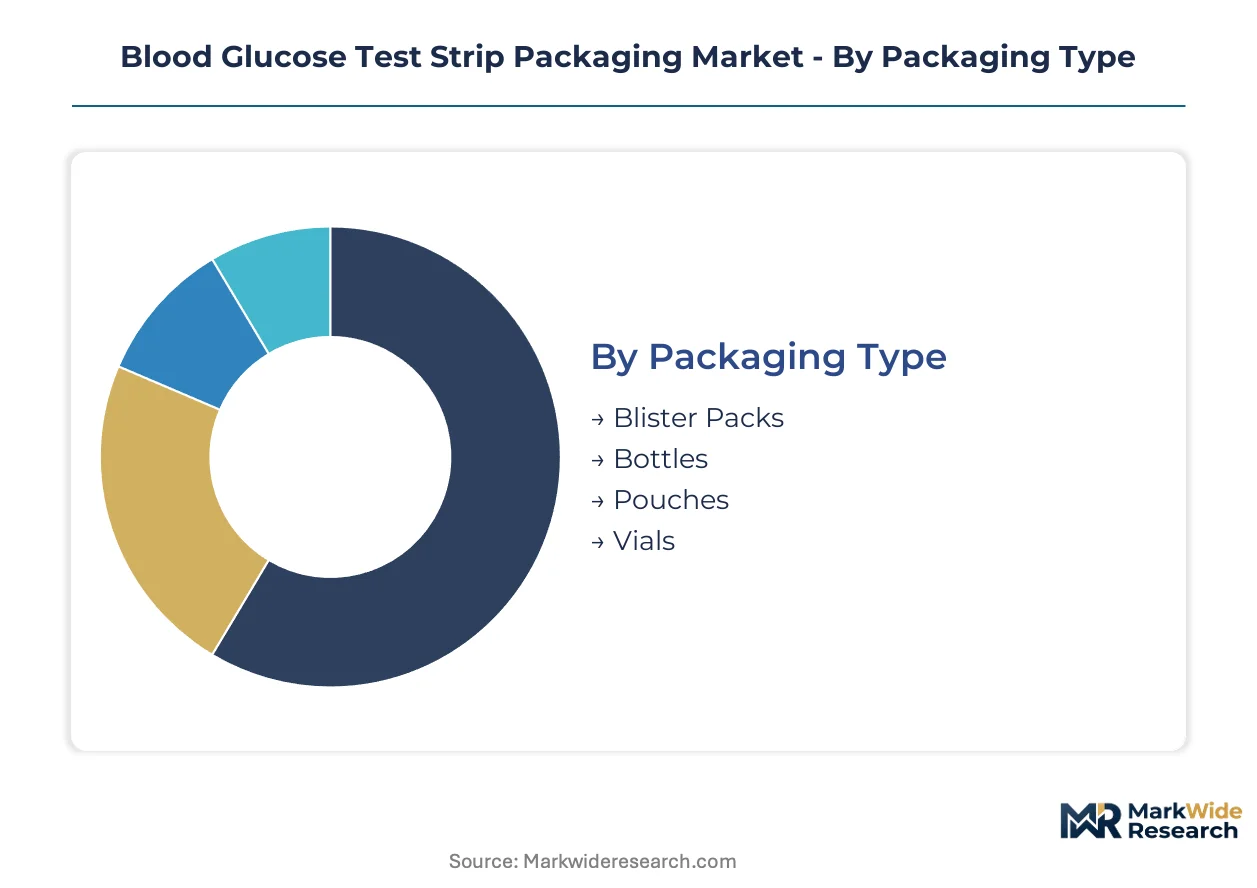
Packaging format selection in blood glucose test strips hinges on moisture protection requirements, patient handling ergonomics, and supply chain automation compatibility. Material stack composition and distribution channel configuration further determine unit economics and regulatory compliance pathways across patient self-monitoring and clinical settings.
Packaging Type:
Volume concentration and patient interaction patterns dictate format selection, with unit-dose convenience competing against bulk efficiency in different care settings.
- Blister Packs:Aluminum-laminate cavities with foil lidding dominate home care dispensing through pharmacy retail chains. CVS Health and Walgreens Boots Alliance procurement specifications now mandate automated dispensing robot compatibility, compressing dimensional tolerances and driving RFID-enabled case labeling adoption in California and Texas distribution centers.
- Pouches:Flexible multi-layer laminates capture emerging market volume where cost minimization overrides premium barrier features. Indian organized pharmacy chains in Mumbai and Delhi are demanding shelf-ready secondary formats with humidity indicators and tamper evidence as retail modernization accelerates.
- Bottles:HDPE containers with desiccant canisters serve high-volume institutional contracts requiring bulk strip storage and rapid access protocols.
- Vials:Glass or polymer cylindrical enclosures address specialized calibration strip refills in continuous glucose monitor hybrid systems.
Blister packs hold installed capacity. Pouches are rotating up the share rankings.
Material Type:
Barrier performance specifications and recyclability pressures are rewiring converter sourcing priorities across metal, polymer, and fiber-based substrates.
- Aluminum:Metallized barrier layers and aluminum-oxide coatings anchor moisture vapor transmission specifications below 0.1 g/m²/day for 24-month shelf life claims. Price volatility in primary metal markets compresses converter margins and complicates long-term supply contracts with Roche and Sanofi supply chains.
- Plastic:Multi-layer coextruded films with silicon-oxide nanolayers are displacing legacy metallized polyester configurations as European diabetes device manufacturers pilot near-infrared sortable structures for anticipated EPA extended producer responsibility mandates.
- Polyethylene:Sealant layers and structural substrates face mechanical separation friction in recycling streams, exposing brands to regulatory penalties under evolving pharmaceutical packaging recyclability guidance.
- Paperboard:Secondary carton stock supports shelf-ready retail presentation and automated case packing in direct-to-pharmacy distribution models.
Plastic is gaining share fastest. Aluminum retains margin concentration.
End User:
Care setting determines packaging complexity, with self-monitoring patients driving portability requirements and clinical environments prioritizing inventory efficiency.
- Home Care:Patients managing diabetes outside clinical settings demand unit-dose blister convenience with compliance tracking features. FDA 21 CFR Part 820 quality system regulations and portability requirements shape primary enclosure design for daily routine integration.
- Hospitals:Centralized pharmacy operations and automated dispensing systems specify uniform carton dimensions and high-volume bottle formats with rapid access protocols.
- Clinics:Point-of-care testing environments balance strip protection with immediate availability, favoring compact pouch configurations.
- Laboratories:Reference testing facilities require extended stability claims and documented sterile barrier integrity under EU MDR Annex I general safety and performance requirements.
Home care commands volume leadership. Hospitals are climbing the fastest.
Distribution Channel:
Channel structure determines packaging format specifications, with retail concentration and e-commerce growth rewiring secondary enclosure requirements.
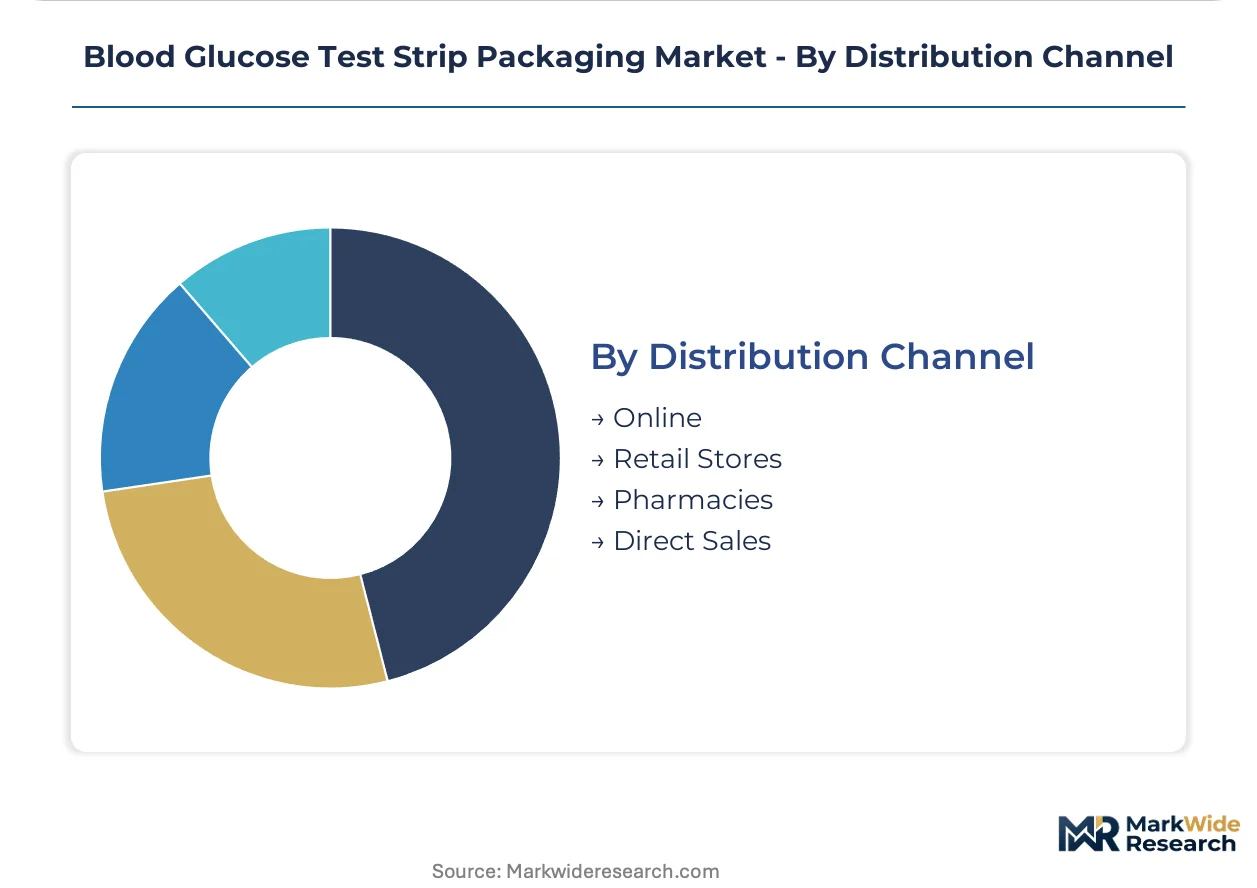
- Retail Stores:Shelf-ready cartons with humidity indicators and tamper evidence address organized pharmacy chain expansion in India and automated stocking requirements in German retail networks.
- Pharmacies:Direct-to-pharmacy distribution models displace wholesale intermediaries in United States and German markets, with vendor-managed inventory contracts specifying point-of-sale data sharing and RFID-enabled case labeling.
- Online:E-commerce fulfillment demands enhanced transit protection against moisture ingress and temperature excursion, driving embedded desiccant system integration in secondary packaging.
- Direct Sales:Institutional contracts with diabetes device manufacturers bypass retail layers, enabling customized batch sizing and private label configurations.
Pharmacies hold channel dominance. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations anchor the United States as the dominant geography for blood glucose test strip packaging demand, with reimbursement access and diabetes prevalence driving volume concentration across multiple continents.
United States
Home care self-monitoring and pharmacy retail concentration shape demand patterns. FDA 21 CFR Part 820 quality system regulations mandate moisture-barrier validation protocols. California and Texas distribution centers deploy automated dispensing robots with RFID-enabled case labeling for CVS Health and Walgreens Boots Alliance procurement networks.
Germany
Converter manufacturing clusters and EU MDR implementation create specification intensity. EU MDR Annex I general safety and performance requirements enforce sterile barrier documentation standards. Stuttgart and Frankfurt regions host moisture-barrier film production facilities serving Roche and Sanofi supply chains with just-in-time contracts.
China
Domestic diabetes device manufacturing expansion and organized pharmacy retail modernization accelerate format adoption. NMPA technical documentation requirements align with international barrier performance benchmarks. Shanghai and Shenzhen industrial zones concentrate pouch and blister packaging capacity for regional diabetes diagnostic producers.
India
Pharmacy chain consolidation and cost-sensitive bulk procurement reshape secondary packaging specifications. CDSCO import registration requirements influence material validation protocols for foreign suppliers. Mumbai and Delhi organized retail expansion demands shelf-ready cartons with humidity indicators and tamper evidence features.
Switzerland
Precision converter expertise and pharmaceutical-grade validation protocols anchor premium positioning. Swissmedic technical documentation standards exceed baseline EU requirements for diagnostic device accessories. Basel and Zurich regions concentrate specialized desiccant system integration and multi-layer laminate R&D capabilities.
Blood Glucose Test Strip Packaging Market Vendor Landscape
Specialized healthcare packaging converters and diversified materials conglomerates split the market across moisture-barrier technology tiers. The vendor base concentrates in European industrial clusters with secondary capacity expansion in Asia-Pacific manufacturing zones. Three strategic archetypes dominate: integrated desiccant system specialists, multi-layer barrier film developers, and pharmaceutical-grade validation service providers. Competitive moves center on co-laminated film layer R&D partnerships and direct-to-pharmacy distribution contract consolidation.
Within the integrated desiccant tier, Airnov Healthcare Packaging and Multisorb exemplify embedded moisture control system development. Among European-based converters, Sanner GmbH occupies a position serving just-in-time pharmacy supply chains. Amcor anchors the diversified materials archetype with multi-layer barrier film technology spanning pharmaceutical and diagnostic applications.
| Leading Market Players |
|---|
| Shijiazhuang Xinfuda Medical Packaging |
| Wisesorbent Technology |
| Sanner GmbH |
| HMD |
| Multisorb |
| Aptar CSP Technologies |
| IMPAK Corporation |
| Amcor |
| Airnov Healthcare Packaging |
| Others |
Supply Flow & Price Mechanics
Rotterdam-to-Hamburg container freight corridors transmit aluminum price volatility directly into converter margin structures, concentrating pricing power among German and Swiss moisture-barrier film specialists while forcing downstream tiering between FDA-validated premium configurations and standard pouch formats.
Pricing Analysis
Configured-to-order blister packs with embedded desiccant systems and redundant seal verification command substantial premiums over standard pouch formats. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 820 certification grade, volume scale, and geographic delivery cost. Cost compression in economy pouch tiers is intensifying because Indian and Chinese domestic manufacturers scale capacity. Hospital GPO contracts demonstrate lowest price sensitivity; emerging market pharmacy chains exhibit highest.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic planning for aluminum-laminate substrate sourcing. Production gravity centers on Germany, Switzerland, and China, with converter R&D capabilities tethered to Basel, Stuttgart, and Shenzhen industrial zones. Raw material dependencies rest on metallized polyester films, silicon-oxide deposition equipment, and pharmaceutical-grade desiccant canisters. Single-source vulnerability concentrates in German moisture-barrier film production clusters. Distribution runs through direct-to-pharmacy vendor-managed inventory contracts with CVS Health, Walgreens Boots Alliance, and McKesson procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blood glucose test strip packaging enters a cyclical recovery phase as diabetes prevalence curves and home care self-monitoring penetration rebound from pandemic-era care setting disruptions.
For Market Incumbents: Pre-empt silicone-oxide nanolayer patent filings before EPA extended producer responsibility mandates crystallize competitive advantage. Integrate redundant seal verification and real-time humidity logging into production workflows to defend against Swissmedic and German notified body enforcement of EU MDR Annex I sterile barrier documentation standards. Backward integration into desiccant canister manufacturing secures margin protection against aluminum price volatility. For New Entrants and Emerging Players: Mid-market pharmacy retail chains in Mumbai and Delhi represent the most penetrable entry point as organized retail modernization accelerates shelf-ready secondary packaging demand. Continuous glucose monitor calibration strip refill formats offer premium positioning above commodity test strip pouches with lower regulatory validation barriers. Partner with regional diabetes device manufacturers on co-development contracts rather than competing for Roche and Sanofi supply chain slots directly. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates seeking to monetize non-core healthcare packaging divisions with stranded FDA validation capabilities. Five-to-ten year viability hinges on converter positioning ahead of ISO 11607 sterile barrier convergence between diabetes diagnostics and implantable devices. Monitor NMPA technical documentation alignment with international barrier performance benchmarks as inflection indicator for China domestic manufacturing expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Oxide Nanolayer R&D Partnership | European diabetes device manufacturers pilot near-infrared sortable structures for 24-month shelf life claims in humid climates. |
| FDA 21 CFR Part 820 Validation Investment | Converters secure moisture vapor transmission rate certification below 0.1 g/m²/day for premium tier positioning. |
| Direct-to-Pharmacy Distribution Contract | Vendor-managed inventory with CVS Health and Walgreens Boots Alliance concentrates purchasing power and specification authority. |
| Embedded Desiccant System Integration | Co-laminated film layers reduce assembly steps and moisture ingress risk during e-commerce fulfillment transit. |
| EU MDR Annex I Compliance Pathway | German notified bodies enforce stricter sterile barrier documentation standards for class IIa diagnostic accessories. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with packaging converters, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records. Bottom-up triangulation against aluminum price indices and moisture vapor transmission rate testing protocols anchored volume estimates. Top-down cross-checks applied diabetes prevalence curves and reimbursement access patterns across United States, Germany, and China.
Forecast inputs considered packaging format adoption rates, material stack migration timelines, and regulatory convergence scenarios across the projection horizon. Segmentation dimensions modeled include packaging type, material composition, end-user care setting, and distribution channel configuration. CAGRs derived from fitted growth curves incorporating home care self-monitoring expansion, pharmacy retail concentration, and emerging market format upgrading. Industry-specific inputs encompassed ASTM F1249 testing protocol certification timelines and EU MDR implementation pace.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity prices, freight corridor costs, or diabetes device manufacturer capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and sterile barrier standard convergence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Global Needles Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Global Biohazard Bag Market