
 Asia-Pacific Medical Clothing Market | 2026-2036
Asia-Pacific Medical Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Clothing Market Insights
Aftermarket sterilization service revenue is rewriting margin expectations for reusable gown programs across the region. Cardinal Health leverages its logistics infrastructure to control distribution into tier-two Chinese hospitals. Molnlycke Health Care AB specializes in advanced barrier fabrics that sustain premium positioning in Japanese surgical suites. Ansell Limited anchors its regional presence through localized manufacturing in Malaysia that competes on turnaround speed against imported alternatives.
Asia-Pacific medical clothing encompasses garments engineered for healthcare environments, typically constructed from woven cotton, synthetic polyester blends, or spunbond-meltblown-spunbond non-woven layers with specified bacterial filtration efficiency and fluid resistance measured in millimeters of hydrostatic head pressure, designed primarily to reduce cross-contamination between patients and clinical staff. Disposable functionality commands the dominant revenue share as hospitals prioritize single-use protocols in operating theaters, though reusable cotton-polyester blends retain traction in administrative and outpatient settings where sterilization infrastructure supports circular workflows. Non-woven material categories are capturing accelerated growth in Southeast Asian markets where domestic spunmelt capacity is displacing woven alternatives in standard precaution applications.
Japan's PMDA and China's NMPA enforce divergent biocompatibility testing protocols that fragment product registration pathways for multinational suppliers, while Australia's TGA alignment with ISO 16603 blood penetration standards creates a secondary compliance tier for export-oriented manufacturers. India's CDSCO medical device rules are extending registration requirements to cover surgical gowns previously classified as non-regulated commodities, forcing domestic producers toward certified cleanroom production. Stakeholders must monitor how Japan's METI push for sustainable healthcare procurement will reshape material specifications before committing to long-term capacity investments.
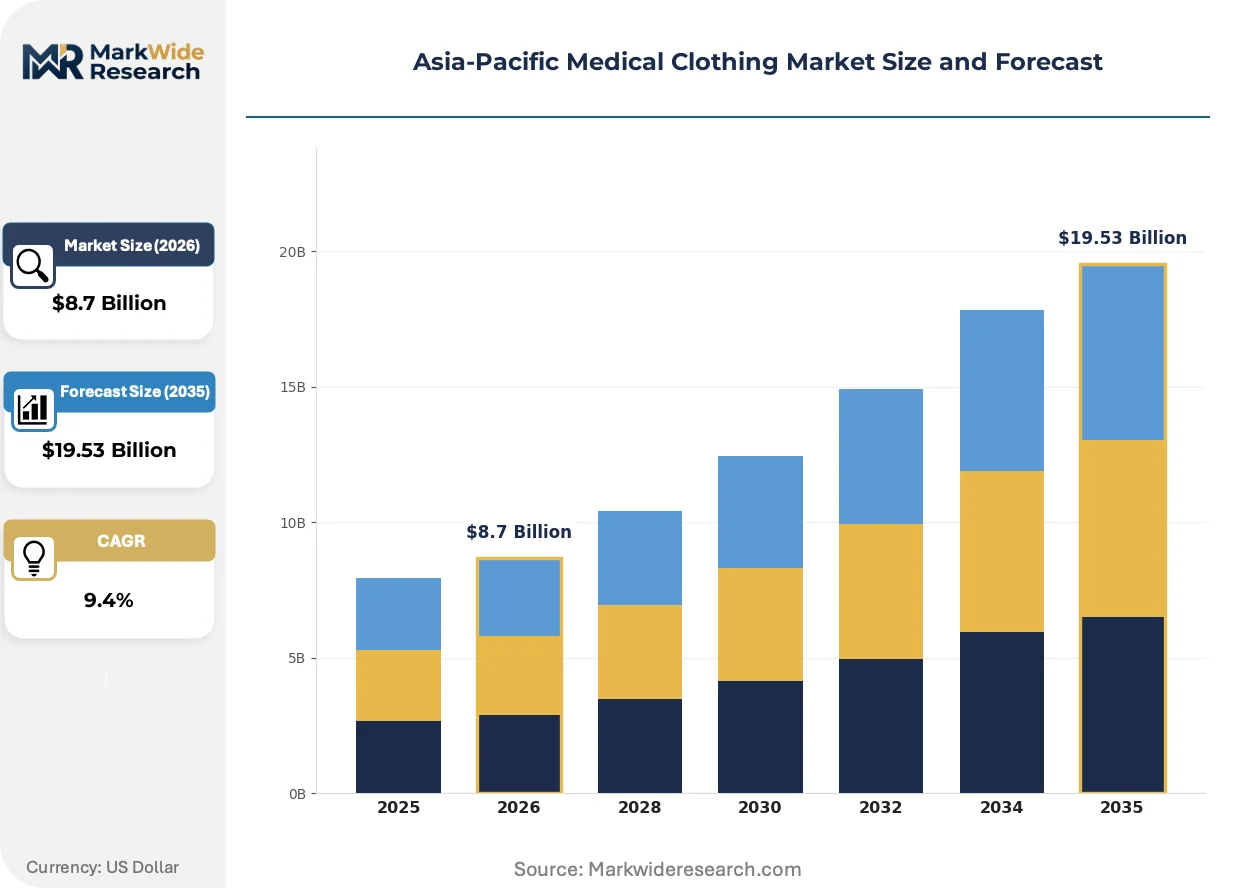
Market Dynamics
Centralized hospital procurement in China's eastern provinces is consolidating purchasing power and compressing supplier margins, while India's BIS certification mandates force domestic manufacturers toward certified cleanroom investments that reshape competitive positioning.
Growth Catalysts
- Surgical gown standardization:China's NMPA is tightening biocompatibility testing protocols for barrier fabrics used in tertiary care networks, accelerating product upgrades across domestic manufacturing.
- Spunmelt capacity expansion:Southeast Asian non-woven production clusters are displacing woven cotton-polyester blends in standard precaution applications through localized material supply.
- Japan's METI sustainability procurement:The ministry's push for circular healthcare materials is creating specification pull for reusable gown programs with aftermarket sterilization service integration.
Market Restraints
- Polypropylene feedstock volatility:Synthetic non-woven producers face margin pressure from petrochemical input cost swings that destabilize pricing for spunbond-meltblown-spunbond laminates.
- Regulatory pathway fragmentation:Divergent PMDA and NMPA biocompatibility testing requirements force multinational suppliers to maintain parallel registration workflows, elevating compliance overhead.
- Reusable gown substitution ceiling:Single-use protocol entrenchment in Japanese and Australian surgical suites limits addressable market expansion for circular workflow solutions despite sterilization infrastructure availability.
Strategic Opportunities
- India's CDSCO registration extension:The reclassification of surgical gowns as regulated medical devices creates first-mover advantage for certified cleanroom producers serving previously unregulated domestic supply.
- Aftermarket sterilization service bundling:Revenue pooling across gown lifecycle management offers margin recovery mechanisms for reusable program operators in Australia's TGA-aligned ISO 16603 markets.
- Malaysian manufacturing localization:Regional production hubs can compress turnaround speed against imported alternatives by leveraging proximity to Southeast Asian hospital clusters.
Industry Challenges
- Barrier fabric engineering talent scarcity:Specialized polymer scientists capable of optimizing bacterial filtration efficiency and hydrostatic head pressure specifications remain concentrated in Japan and South Korea.
- Dual registration timeline compression:Simultaneous PMDA and NMPA pathway navigation demands extended certification cycles that delay product commercialization in premium surgical segments.
- Legacy sterilization infrastructure retrofit costs:Hospital investment in steam and low-temperature hydrogen peroxide systems for reusable gown workflows requires capital allocation competing with disposable protocol preferences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Clothing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrubs, Lab Coats, Gowns, Surgical Caps Material: Cotton, Polyester, Blends, Non-woven Functionality: Disposable, Reusable, Sterile, Non-sterile End User: Hospitals, Clinics, Nursing Homes, Emergency Services |
| Companies Covered | Medline Industries, Cardinal Health, Ansell Limited, Kimberly-Clark Corporation, Owens & Minor, 3M, Top Glove Corporation Bhd, Molnlycke Health Care AB, Superior Group of Companies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Clothing Market Trends and Innovations
Material science convergence with regulatory specification tightening is collapsing traditional product lifecycles and compressing the window between certification and obsolescence across Asia-Pacific medical clothing.
Spunbond-meltblown-spunbond non-woven laminates with tuned bacterial filtration efficiency are collapsing the performance gap between synthetic disposables and woven reusables in standard precaution settings. Chinese provincial hospital clusters are adopting these materials at accelerated pace as centralized procurement specifications harden. The technology is collapsing historical material segmentation that previously reserved non-wovens for operating theaters and cotton-polyester for outpatient workflows.
Japan's METI sustainable healthcare procurement guidelines are mandating lifecycle carbon accounting for medical textiles that elevates reusable gown programs in public hospital tenders. The policy compresses disposable protocol preference in administrative settings where sterilization infrastructure already exists. Australian TGA alignment with ISO 16603 blood penetration standards creates a secondary compliance tier that advantages regional manufacturers over distant suppliers facing extended certification cycles.
Aftermarket sterilization service unbundling is separating gown supply from decontamination workflow management in large Australian and Japanese health networks. Third-party service providers are capturing margin pools that previously accrued to integrated hospital supply departments. This pattern concentrates most visibly in Japan's metropolitan hospital clusters where METI procurement guidelines explicitly preference circular economy service models over single-use volume contracts.
Asia-Pacific Medical Clothing Market Segmentation
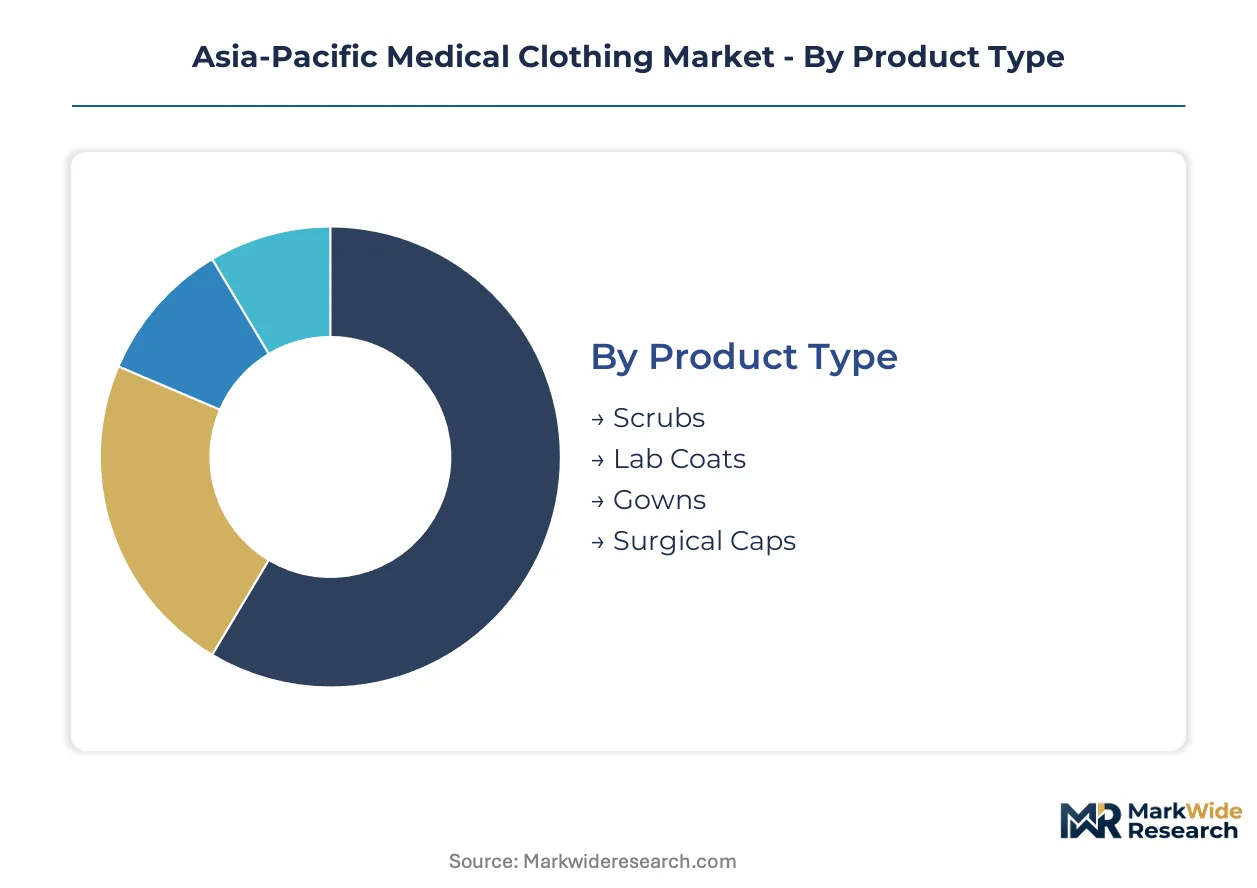
Segmentation in Asia-Pacific medical clothing reveals distinct procurement cycles across product categories, with high-turnover disposables in surgical suites contrasting against extended-use administrative garments. Material specifications and sterilization protocols create divergent margin profiles that reshape supplier strategies across hospital tiers.
Product Type:
Gowns rotate through inventory fastest in tertiary care networks, while lab coats persist longest in outpatient settings where contamination exposure remains minimal.
- Gowns:Spunbond-meltblown-spunbond laminates with specified hydrostatic head pressure dominate barrier specifications in Chinese provincial hospital clusters. NMPA biocompatibility tightening accelerates product upgrades as centralized procurement hardens technical requirements.
- Scrubs:Cotton-polyester blends retain preference in India's administrative and outpatient workflows where sterilization infrastructure supports circular protocols. BIS certification mandates force domestic manufacturers toward certified cleanroom production that elevates unit economics.
- Lab Coats:Woven cotton or polyester constructions serve diagnostic and research environments across Australian TGA-aligned facilities.
- Surgical Caps:Non-woven spunmelt materials displace woven alternatives in Japanese surgical suites prioritizing single-use protocols.
Gowns anchor the volume base while scrubs gain share at the steepest rate as India's CDSCO registration extension reclassifies previously unregulated supply.
Material:
Cost tiers separate premium barrier fabrics from economy woven alternatives, with mid-tier blends capturing outpatient standard precaution applications.
- Non-woven:Spunbond-meltblown-spunbond laminates with tuned bacterial filtration efficiency collapse performance gaps against woven reusables. Southeast Asian spunmelt capacity expansion displaces imported alternatives in regional hospital procurement.
- Blends:Cotton-polyester combinations balance comfort with sterilization durability in Australia's ISO 16603-aligned reusable programs. Aftermarket sterilization service bundling recovers margin pools for circular workflow operators.
- Cotton:Natural fiber constructions persist in India's cost-sensitive primary care settings.
- Polyester:Synthetic woven alternatives serve administrative environments where fluid resistance requirements remain minimal.
Non-woven materials command premium positioning while blends expand most quickly through sterilization service integration.
Functionality:
Volume concentration favors disposables in surgical segments, with reusable protocols concentrated where capital infrastructure already exists.
- Disposable:Single-use protocols dominate Japanese and Australian surgical suites where infection control standards prioritize elimination of cross-contamination risk. METI sustainable procurement guidelines create specification tension against circular economy preferences.
- Reusable:Circular workflows concentrate in administrative settings with existing steam or low-temperature hydrogen peroxide sterilization systems. Japan's metropolitan hospital clusters explicitly preference service-based models over volume contracts.
- Sterile:Pre-sterilized packaging serves emergency services and operating theaters requiring immediate deployment capability.
- Non-sterile:Standard precaution applications in outpatient and administrative settings reduce per-unit procurement costs.
Disposable functionality anchors the volume base while reusable programs climb the fastest through aftermarket service unbundling.
End User:
Customer scale determines contract structure, with consolidated hospital networks extracting pricing leverage against fragmented clinic procurement.
- Hospitals:Centralized purchasing in China's eastern province clusters compresses supplier margins while hardening technical specifications. Tertiary care networks upgrade infection control protocols that accelerate surgical gown standardization.
- Clinics:Fragmented procurement across India's diagnostic centers creates distribution complexity that favors logistics-integrated suppliers. CDSCO registration requirements extend compliance burdens to previously unregulated channels.
- Nursing Homes:Long-term care facilities in Japan prioritize comfort specifications for extended wear durations.
- Emergency Services:Rapid deployment requirements favor pre-sterilized disposable configurations.
Hospitals anchor the volume base while clinics gain share at the steepest rate as regulatory registration reshapes competitive access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern province hospitals favor centralized bulk purchasing of synthetic disposables, while India's diagnostic networks still fragment procurement across woven-cotton administrative garments. Japan's metropolitan clusters explicitly preference circular service models over single-use volume contracts.
China
Provincial hospital clusters in Jiangsu and Zhejiang consolidate surgical gown procurement through unified tender platforms that harden spunbond-meltblown-spunbond specifications. NMPA biocompatibility testing protocols now mandate upgraded barrier fabric documentation for tertiary care network suppliers. Yangtze River Delta manufacturing bases absorb domestic spunmelt capacity expansion that displaces imported non-woven alternatives.
India
Diagnostic center networks across Maharashtra and Gujarat fragment procurement across thousands of independent facilities that favor cotton-polyester blends for cost containment. CDSCO medical device rules now extend registration requirements to surgical gowns previously exempt from cleanroom certification. Karnataka's Bengaluru-Tumkur corridor attracts domestic manufacturers retrofitting toward BIS-certified production lines.
Japan
Metropolitan hospital clusters in Tokyo and Osaka explicitly preference reusable gown programs with bundled aftermarket sterilization services under METI sustainable procurement guidelines. PMDA biocompatibility protocols diverge from regional standards, forcing parallel registration workflows for multinational suppliers. Kansai region health networks pilot circular economy service contracts that separate garment supply from decontamination management.
Australia
Tertiary care networks in New South Wales and Victoria align procurement with TGA-adopted ISO 16603 blood penetration standards that advantage regional manufacturers over distant competitors. Pre-sterilized disposable configurations dominate emergency services and operating theater applications. Queensland's hospital clusters increasingly bundle reusable program management with third-party sterilization providers.
South Korea
Specialized polymer scientists concentrated in Seoul Capital Area and Busan-Ulsan industrial zones anchor barrier fabric engineering capability for premium surgical applications. MFDS medical device regulations enforce biocompatibility documentation that elevates technical entry barriers for imported alternatives. Daegu-Gyeongbuk textile manufacturing bases pivot toward medical-grade non-woven production for regional hospital supply.
Asia-Pacific Medical Clothing Market Competitive Landscape
Capability concentration sits with specialized barrier fabric engineers; scale advantage sits with diversified health supply conglomerates. The vendor base organizes around three archetypes: multinational distributors controlling logistics infrastructure into tier-two hospital networks, regional manufacturers competing on turnaround speed through localized production, and material science specialists commanding premium positioning in surgical suites. Dominant competitive moves include strategic partnerships with aftermarket sterilization service providers and geographic expansion through Malaysian manufacturing localization.
Among Asia-Pacific headquartered suppliers, Ansell Limited and Top Glove Corporation Bhd occupy positions within the regional manufacturing tier, while Molnlycke Health Care AB exemplifies the material science specialist archetype. These three entities represent contrasting strategic postures: Malaysian production proximity versus Swedish advanced barrier fabric development versus Australian-turned-Asian supply chain integration. Cardinal Health and Kimberly-Clark Corporation sit within the multinational distributor tier, leveraging existing health supply logistics networks rather than manufacturing specialization.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| Ansell Limited |
| Kimberly-Clark Corporation |
| Owens & Minor |
| 3M |
| Top Glove Corporation Bhd |
| Molnlycke Health Care AB |
| Superior Group of Companies |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta spunmelt manufacturing clusters dictate downstream pricing power through captive polypropylene feedstock access and integrated non-woven lamination capacity. Hospital procurement consolidation in Jiangsu and Zhejiang provinces compresses supplier margins while elevating technical specification requirements for barrier fabrics.
Pricing Analysis
Long-term offtake contracts dominate procurement between Chinese provincial hospital clusters and domestic spunmelt producers, insulating volume buyers from polypropylene feedstock volatility. Pricing stratifies across premium, standard, and economy tiers based on bacterial filtration efficiency certification and hydrostatic head pressure performance. Cost compression in standard precaution segments intensifies as Southeast Asian capacity expansion floods regional spot markets. Diagnostic clinics in India exhibit highest price sensitivity, while Japanese tertiary care networks prioritize barrier performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta non-woven producers, Malaysian glove and garment specialists, and South Korean barrier fabric engineers. Raw material dependencies center on polypropylene resin, medical-grade cotton fiber, and spunmelt production equipment. Single-source vulnerability concentrates in specialized polymer scientist talent pools anchored in Seoul Capital Area and Busan-Ulsan industrial zones. Distribution runs through diversified health supply conglomerates controlling logistics infrastructure into tier-two hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket sterilization service bundling expands faster than garment hardware supply, transforming capital equipment transactions into recurring revenue relationships across Asia-Pacific health networks.
For Market Incumbents: Pre-empt margin erosion from centralized Chinese procurement by integrating backward into polypropylene fiber production and securing exclusive sterilization service contracts in Australian TGA-aligned markets. Anchor capacity in Malaysian manufacturing corridors to compress turnaround speed against distant competitors. For New Entrants and Emerging Players: Pursue India's CDSCO-registered cleanroom production segment, where regulatory reclassification creates first-mover access to previously unregulated domestic supply. Target Maharashtra and Gujarat diagnostic center networks with cotton-polyester blend offerings supported by BIS certification investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material science specialists with proprietary barrier fabric IP over commodity garment assemblers. Five-to-ten year viability hinges on sterilization infrastructure integration rather than disposable volume scale. Monitor METI procurement guideline enforcement as circular economy mandate inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Sterilization Service Integration | Captures recurring revenue pools from Japanese METI-mandated circular procurement. |
| Malaysian Manufacturing Localization | Compresses logistics lead times against imported alternatives in Southeast Asian hospital clusters. |
| CDSCO Cleanroom Certification Investment | Unlocks first-mover positioning in India's newly regulated surgical gown supply channel. |
| Barrier Fabric R&D Partnership | Accesses Seoul Capital Area polymer scientist talent for NMPA-compliant product development. |
| Provincial Hospital System Partnership | Secures volume offtake from China's eastern province centralized procurement platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts administrators, and non-woven manufacturing plant directors. Secondary validation drew from NMPA registration filings, CDSCO medical device notifications, hospital procurement database extracts, and customs trade records for polypropylene fiber imports. Bottom-up volume estimates triangulated against top-down spending allocation models across the analysis window.
Calibration anchored on historical procurement volume patterns and regulatory pathway timelines without year-specific assumptions. Segmentation modeling spanned product type, material construction, functionality tier, and end-user facility scale. CAGRs derived from slope analysis of normalized procurement expenditure curves. Forecast inputs incorporated spunmelt capacity expansion pipelines and sterilization infrastructure deployment rates.
Macroeconomic conditions sit as an overlay; deviation in polypropylene feedstock pricing or hospital capital expenditure cycles would shift the trajectory. Cross-checking against regional hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Microcarrier Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Surgical Glue Market