
 Global Needles Market | 2026-2036
Global Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Needles Market Outlook
Hospital procurement is rotating toward ambulatory and home care channels as chronic disease management shifts outside traditional facilities. Becton, Dickinson and Company leverages its safety-engineered portfolio to dominate institutional contracts across North America and Europe. Terumo Corporation anchors its position through precision manufacturing of stainless steel hypodermic needles for diabetes and dialysis applications. B. Braun Melsungen AG differentiates via vertical control over sterilization and packaging workflows that serve clinic networks in Germany and Japan.
Needles are hollow metallic instruments, typically fabricated from 304-grade stainless steel tubing with beveled tips ground to angles between 12 and 30 degrees, designed to penetrate tissue or vessel walls for fluid delivery or extraction. Safety needle mechanisms incorporate retractable sheaths or hinged shields that activate upon withdrawal to prevent sharps injuries in clinical and non-clinical settings. Stainless steel formulations lead product type demand due to tensile strength and corrosion resistance, while safety needles represent the fastest-expanding category as OSHA and EU MDR compliance deadlines tighten. Home care end users command rising margin pools as direct-to-patient distribution models reduce intermediary costs.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern needle safety features, biocompatibility testing, and sterilization validation before market authorization. ISO 7864 standards specify dimensions, performance, and testing methods for sterile hypodermic needles used in human medicine. Stakeholders must monitor evolving FDA guidance on sharps injury prevention and EU EUDAMED registration timelines to align R&D pipelines with compliance windows.
Market Dynamics
The transition from institutional to decentralized care delivery is restructuring procurement volumes across the needles industry, with safety-engineered designs becoming non-negotiable entry requirements in regulated markets.
Growth Catalysts
- EU MDR safety mandates:The Medical Device Regulation's sharps injury prevention requirements are forcing hospital systems across Germany, France, and Italy to replace conventional needle portfolios with retractable and shielded alternatives.
- Home dialysis expansion:Patients managing end-stage renal disease outside clinical settings are consuming higher volumes of sterile hypodermic needles for vascular access, driving recurring purchase patterns.
- 304-grade stainless steel tubing supply:Precision manufacturing clusters in Japan and Germany have stabilized raw material flows, enabling consistent production of corrosion-resistant bevel geometries.
Market Restraints
- Nickel price volatility:Stainless steel formulations depend on nickel alloying elements, and commodity swings compress margin predictability for needle manufacturers.
- Single-source sterilization capacity:Gamma irradiation and ethylene oxide sterilization services concentrate among contract providers in the United States and Belgium, creating supply bottlenecks.
- Reusable needle alternatives:Certain veterinary and industrial applications are experimenting with autoclavable metal needles, threatening disposable volumes in non-regulated segments.
Strategic Opportunities
- India's domestic manufacturing scale-up:Production-Linked Incentive schemes for medical devices are attracting greenfield needle manufacturing investments to serve South Asian and African export markets.
- Biologic drug self-administration:Prefilled syringe and autoinjector formats for rheumatoid arthritis and multiple sclerosis therapies require specialized needle lengths and gauges.
- OSHA Bloodborne Pathogens Standard updates:Anticipated enforcement tightening in US healthcare settings will accelerate replacement cycles for non-compliant needle inventory.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, delaying FDA 510(k) submissions.
- Legacy ERP integration:Needle manufacturers implementing EU EUDAMED traceability requirements must reconcile batch records with decades-old inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Needles Market |
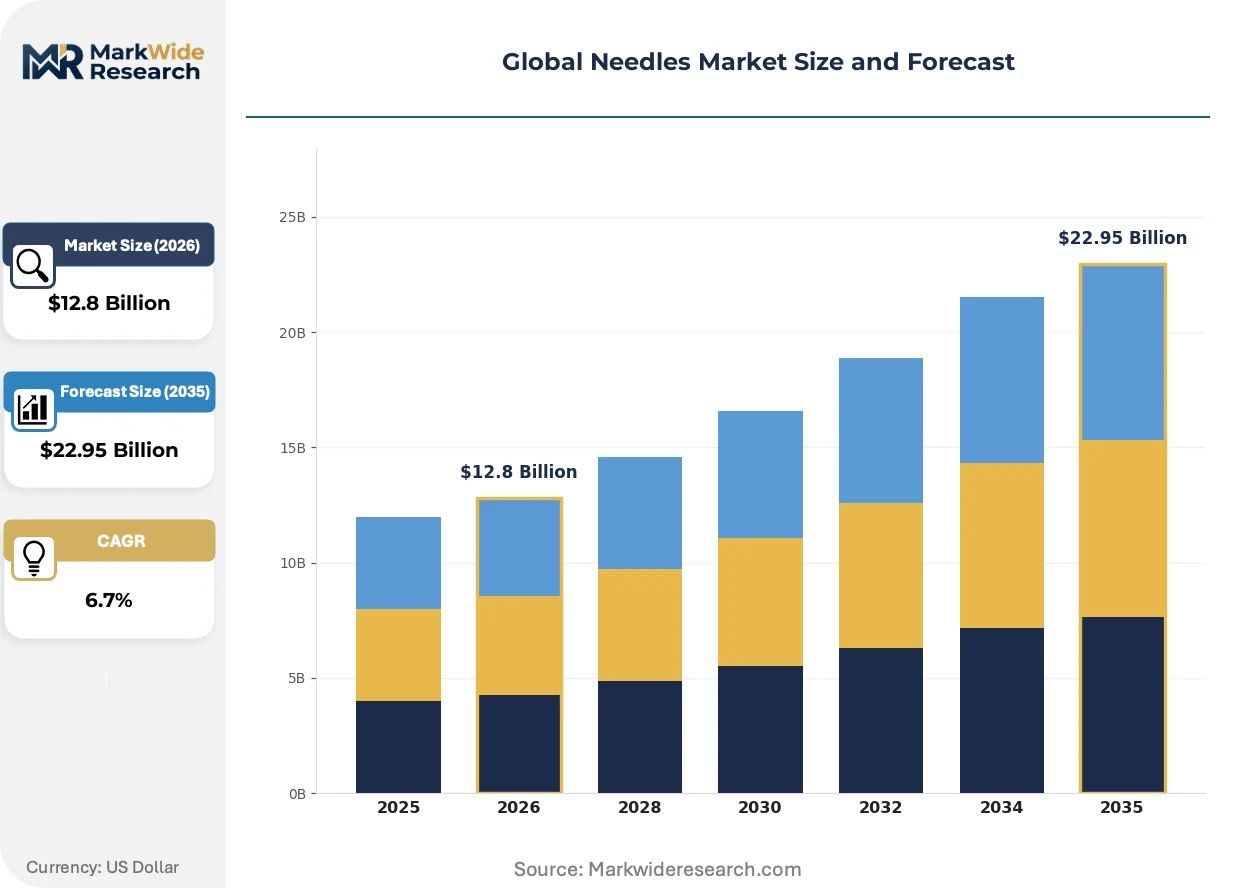
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypodermic Needles, Syringe Needles, IV Catheters, Safety Needles End User: Hospitals, Clinics, Home Care, Laboratories Material: Stainless Steel, Plastic, Silicone, Coated Packaging Type: Bulk, Individual Packs, Tray Packs, Kits |
| Companies Covered | Becton, Dickinson and Company, Medtronic, B. Braun Melsungen AG, Terumo Corporation, Stryker, Boston Scientific Corporation, Nipro Corporation, Smiths Medical, Novo Nordisk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Needles Market Strategic Shifts
Active needle tip geometries and connected delivery systems are converging to reduce tissue trauma and enable dose verification, reshaping R&D priorities across the supply base.
Silicone-free lubrication coatings are displacing traditional dimethicone-based surface treatments in diabetes and immunotherapy applications. Pediatric and geriatric patient populations with silicone sensitivities are driving preference shifts. This displacement is compressing market share for conventional lubricated needles in European and North American hospital formulary decisions.
REACH Annex XVII restrictions on nickel release are compelling manufacturers to certify 316L stainless steel alternatives for extended-wear applications. The European Chemicals Agency's substance evaluation process is extending compliance timelines. Dermal and subcutaneous needle segments serving allergy immunotherapy are absorbing the bulk of reformulation costs.
Direct-to-patient subscription models for chronic disease supplies are bypassing traditional distributor networks. Diabetes management platforms in the United States and United Kingdom are bundling needles with glucose monitoring consumables. This channel compression is most visible in insulin-dependent populations seeking cost predictability.
Global Needles Market Segmentation
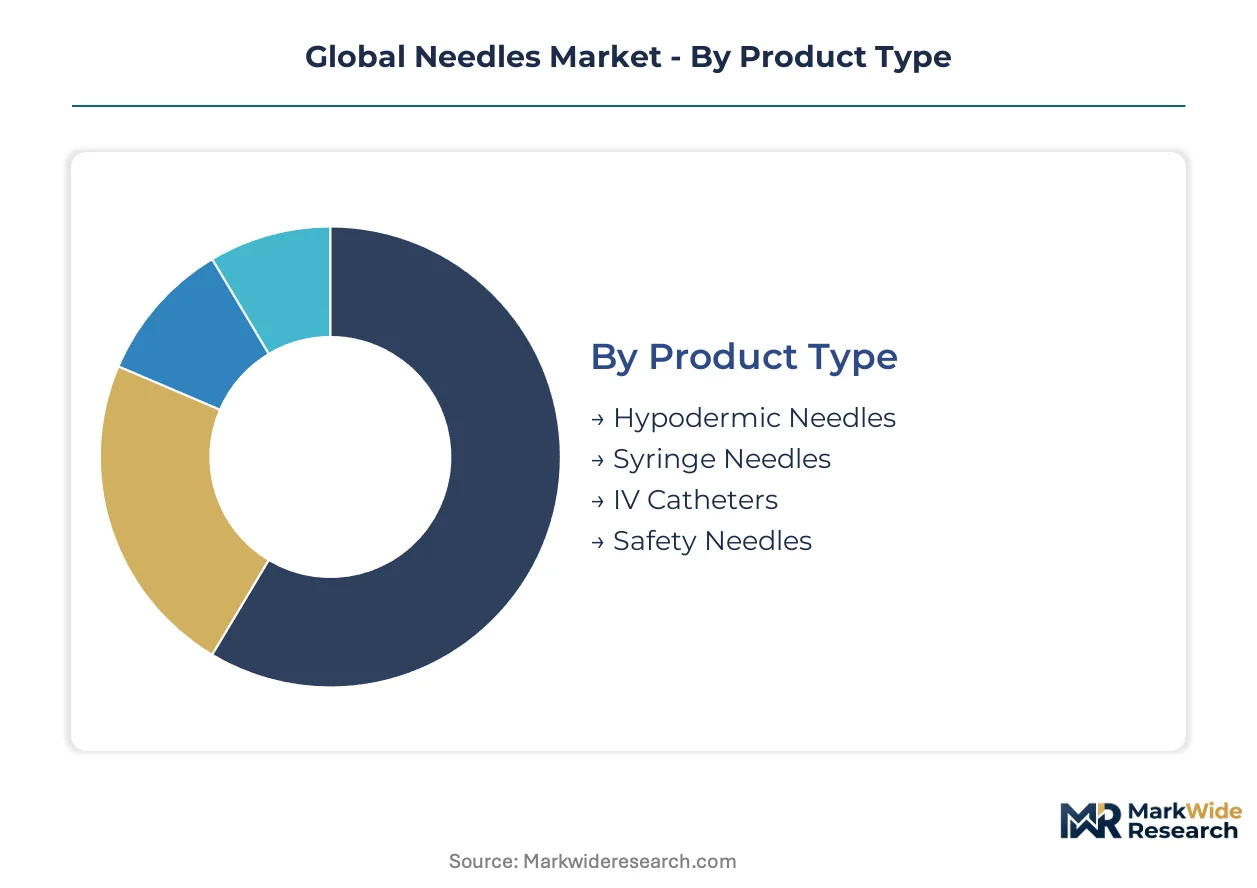
Needle manufacturers must align product portfolios with divergent regulatory pathways, as FDA 510(k) clearance timelines and EU MDR technical documentation requirements vary sharply across safety-engineered versus conventional designs. Segmentation strategy determines which R&D investments access institutional procurement contracts versus home care direct-to-patient channels.
Product Type:
FDA sharps injury prevention guidance and EU MDR Annex I general safety requirements create divergent compliance burdens across conventional and safety-engineered formats, reshaping manufacturer resource allocation.
- Hypodermic Needles:Hollow 304-grade stainless steel tubing with beveled tips ground to 12-30 degree angles dominates diabetes management and vaccination protocols. Demand concentrates in Indian and Chinese domestic manufacturing clusters as healthcare access expansion drives volume procurement.
- Safety Needles:Retractable sheaths and hinged shields activate upon withdrawal to prevent occupational sharps injuries. German and Italian hospital systems are replacing entire conventional inventories ahead of EU MDR enforcement deadlines, accelerating category expansion.
- Syringe Needles:Precision-manufactured attachments for fluid delivery systems serve prefillable syringe formats in biologic drug administration.
- IV Catheters:Vascular access devices with integrated needle introducers support infusion therapy in acute care settings.
Established volume favors hypodermic configurations; emerging adoption favors safety-engineered alternatives.
End User:
Procurement authority and reimbursement pathways split sharply between centralized hospital formulary committees and decentralized patient-directed purchasing.
- Hospitals:Institutional procurement committees governed by OSHA Bloodborne Pathogens Standard compliance mandates dominate North American safety needle contracting. Bulk purchasing agreements with Becton, Dickinson and Company and Terumo Corporation lock in multi-year supply relationships.
- Home Care:Direct-to-patient distribution models for diabetes and dialysis supplies bypass traditional distributor markups. United Kingdom and United States diabetes management platforms bundle needles with glucose monitoring consumables, compressing channel costs.
- Clinics:Outpatient facilities balance cost sensitivity with regulatory compliance across vaccination and blood draw protocols.
- Laboratories:Diagnostic testing workflows consume sterile needles for specimen collection and reagent handling.
Contract concentration anchors hospital procurement; margin expansion concentrates in home care subscription models.
Material:
REACH Annex XVII nickel release restrictions and ISO 10993 biocompatibility testing requirements are forcing reformulation across European dermal and subcutaneous applications.
- Stainless Steel:304-grade formulations provide tensile strength and corrosion resistance for standard hypodermic applications. 316L alternatives are gaining formulation share in European allergy immunotherapy segments as ECHA substance evaluations extend compliance timelines.
- Coated:Silicone-free lubrication treatments displace dimethicone-based surfaces in pediatric and geriatric populations with chemical sensitivities. North American and European hospital formularies are excluding conventional lubricated needles from preferred vendor lists.
- Plastic:Polymer-based hubs and handles reduce unit weight in high-volume disposable applications.
- Silicone:Traditional dimethicone lubrication faces formulation restrictions in extended-wear and sensitive-population devices.
Cost efficiency favors uncoated stainless configurations; clinical differentiation favors advanced surface treatments.
Packaging Type:
Sterilization validation requirements and EU EUDAMED traceability mandates are restructuring batch record systems across unit-of-use versus bulk distribution formats.
- Individual Packs:Single-unit sterile barriers with lot-specific labeling support home care and travel-based chronic disease management. United States direct-to-patient subscription services specify individual pack formats for compliance with postal shipping regulations.
- Kits:Bundled configurations pairing needles with syringes, alcohol swabs, and disposal containers serve dialysis and insulin-dependent populations. Japanese precision manufacturing clusters specialize in kit assembly workflows with integrated gamma irradiation validation.
- Bulk:Multi-unit containers serve high-throughput hospital central supply operations with automated dispensing systems.
- Tray Packs:Intermediate quantities support clinic and outpatient surgical center replenishment cycles.
Operational efficiency favors bulk hospital delivery; patient convenience and regulatory traceability favor individual and kit formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export safety-engineered needles to Italian and French hospital systems ahead of EU MDR enforcement deadlines. This trade corridor channels sterilized 304-grade stainless steel tubing through contract sterilization hubs in Belgium before final distribution.
United States
OSHA Bloodborne Pathogens Standard compliance mandates drive institutional procurement of retractable and shielded needle formats across hospital networks. FDA 510(k) clearance pathways govern safety feature validation before market authorization. Manufacturing clusters in Massachusetts and North Carolina specialize in gamma-irradiated individual pack formats for home dialysis patients.
Germany
EU MDR sharps injury prevention requirements are forcing hospital systems in Bavaria and North Rhine-Westphalia to replace conventional needle inventories. BfArM post-market surveillance obligations extend technical documentation burdens for domestic manufacturers. The Tuttlingen surgical instrument cluster anchors precision grinding operations for bevel geometries serving export markets.
China
NMPA medical device registration reforms are accelerating domestic production scale-up for hypodermic and safety needle categories. Healthcare access expansion in tier-two and tier-three cities drives volume procurement from Jiangsu and Zhejiang manufacturing bases. The Yangtze River Delta concentrates 304-grade stainless steel tubing fabrication for Asian and African export markets.
India
CDSCO medical device rules and Production-Linked Incentive schemes attract greenfield needle manufacturing investments to serve South Asian demand. Government hospital procurement under Ayushman Bharat generates bulk purchasing volumes for conventional hypodermic formats. The Gujarat and Maharashtra industrial corridors host sterilization-validated assembly operations for domestic and African export markets.
Japan
PMDA quality management system requirements enforce stringent batch traceability for stainless steel needle exports to European and North American buyers. Aging population demographics expand home care consumption of precision-manufactured diabetes and dialysis needles. The Kanagawa and Osaka precision manufacturing clusters specialize in kit assembly workflows with integrated gamma irradiation validation.
Global Needles Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with captive sterilization capacity and safety-engineered patent portfolios. Market structure concentrates procurement influence among three to four institutional contract holders in North America and Western Europe. Strategic archetypes include vertically integrated stainless steel processors, safety mechanism specialists, and diabetes-focused disposable manufacturers. Dominant competitive moves encompass backward integration into 304-grade tubing supply and geographic expansion through distributor acquisitions in Indian and Southeast Asian markets.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Terumo Corporation occupy positions exemplifying safety-engineered portfolio dominance and precision manufacturing specialization respectively. B. Braun Melsungen AG represents the vertically integrated archetype with in-house control over sterilization workflows. These three anchors demonstrate how regulatory compliance capabilities and raw material sourcing advantages stratify competitive positioning across institutional and home care channels.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Medtronic |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Stryker |
| Boston Scientific Corporation |
| Nipro Corporation |
| Smiths Medical |
| Novo Nordisk A/S |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers and EU MDR technical documentation requirements gate both supplier qualification and price stratification across safety-engineered and conventional needle portfolios. Manufacturers holding active FDA submissions and notified body certifications command premium positioning in hospital procurement contracts, while uncertified competitors face exclusion from institutional formulary committees in the United States and Germany.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates retractable safety needles from conventional hypodermic formats and unbranded commodity alternatives. Premium tiers capture ISO 13485-certified manufacturers with integrated gamma sterilization capacity serving German and Japanese hospital systems. Cost compression in standard hypodermic segments intensifies because Indian and Chinese domestic producers scale 304-grade stainless steel tubing fabrication. Home care direct-to-patient channels exhibit highest price sensitivity; institutional GPO contracts anchored by OSHA compliance mandates show lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital procurement in Germany and the United States ahead of EU MDR enforcement windows, while just-in-time replenishment governs home care subscription models in the United Kingdom. Raw material supply concentrates in Japan, Germany, and China for precision 304-grade stainless steel tubing with certified bevel geometries. Nickel alloying elements and gamma irradiation sterilization services in Belgium and the United States represent critical dependencies. Single-source sterilization capacity creates structural vulnerability. Distribution runs through hospital GPO networks, direct-to-patient platforms, and clinic distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
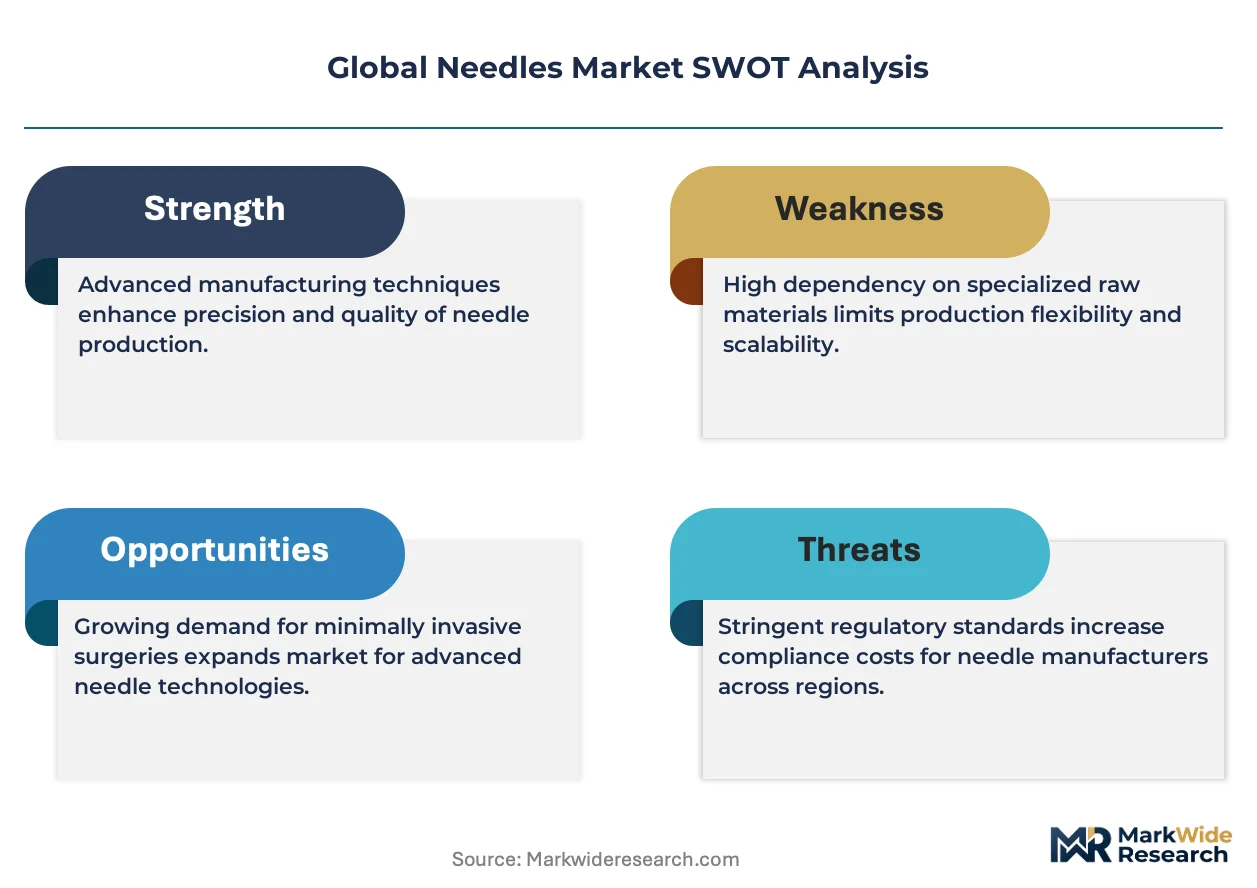
This market sits in early-cycle expansion as home dialysis and biologic self-administration penetrate patient populations previously managed in institutional settings. Safety-engineered device mandates across multiple regulatory jurisdictions accelerate replacement demand for conventional needle inventories.
For Market Incumbents: Secure backward integration into 304-grade stainless steel tubing supply to insulate margin structures from nickel commodity volatility. Expand captive gamma sterilization capacity in Belgium or the United States to reduce single-source dependency. Lock multi-year GPO contracts ahead of anticipated OSHA Bloodborne Pathogens Standard enforcement tightening.
For New Entrants and Emerging Players: Differentiate on silicone-free lubrication coatings for pediatric and geriatric sensitivity populations in European hospital formularies. Target India's Production-Linked Incentive corridors for greenfield manufacturing scale-up serving African export markets. Pursue direct-to-patient subscription bundling with glucose monitoring platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across safety-engineered needle segments due to EU MDR technical documentation and biocompatibility testing requirements. Long-term viability favors vertically integrated manufacturers with in-house sterilization workflows and notified body relationships. Watch EUDAMED traceability implementation timelines as the signal for compliance-cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body certifications unlock German and French hospital procurement contracts ahead of enforcement deadlines. |
| Backward Integration into 304-Grade Tubing | Captive stainless steel supply reduces nickel price exposure and stabilizes bevel geometry quality. |
| Silicone-Free Coating Development | Pediatric and geriatric formularies in the United States and Europe exclude conventional dimethicone-lubricated alternatives. |
| Direct-to-Patient Platform Partnership | Diabetes management bundling in the United Kingdom compresses distributor markups and locks recurring revenue. |
| Gamma Sterilization Capacity Expansion | In-house irradiation validation reduces dependency on Belgium and United States contract sterilization bottlenecks. |
Study Parameters
Operator-level perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and sterilization validation directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU EUDAMED registration databases, CDSCO medical device rules, and NMPA reform documentation. Customs records from Indian and Chinese export authorities and ISO certification registries provided trade flow triangulation. Bottom-up demand modeling across end-user segments reconciled with top-down market sizing from manufacturer capacity disclosures.
Sensitivity analysis tested forecast robustness across nickel price scenarios, EU MDR implementation delays, and OSHA enforcement intensities. Segmentation dimensions modeled include product type, end-user channel, material grade, and packaging format across the analysis window. CAGRs derived from volume trajectory analysis incorporating healthcare access expansion in India and China, home dialysis penetration rates, and biologic drug self-administration adoption curves. Sterilization capacity constraints and regulatory compliance timelines served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained nickel supply stability, EU MDR enforcement adherence, or home care reimbursement expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory timelines and raw material availability. Revision becomes warranted when safety needle compliance thresholds or sterilization capacity utilization crosses critical supply-demand imbalance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Medical Bags Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Hemostasis Products Market