
 US Depyrogenated Sterile Empty Vials Market | 2026-2036
US Depyrogenated Sterile Empty Vials Market Size, Share, and Industry Trends Forecast 2026-2036
US Depyrogenated Sterile Empty Vials Market Insights
Pharmaceutical-grade depyrogenation with endotoxin limits below 0.25 EU/mL is rotating the US market toward higher-specification vial tiers. Thermo Fisher Scientific leverages integrated bioproduction workflows to sustain dominance in sterile containment. Gerresheimer anchors North American supply through specialized borosilicate glass operations. SCHOTT competes via advanced forming technologies that reduce particulate generation.
Depyrogenated sterile empty vials are containers rendered free of pyrogenic substances through validated dry-heat or rinsing processes, typically manufactured from Type I borosilicate glass or cyclic olefin polymers to meet USP <661> physicochemical standards. Their primary purpose is to provide pre-sterilized, endotoxin-controlled primary packaging for parenteral drug products, eliminating in-house depyrogenation steps for drug manufacturers. Glass vials occupy the mature volume core of the market while plastic vials represent the fastest-expanding segment driven by biologic compatibility and breakage reduction needs. End-user concentration among contract manufacturing organizations creates margin pools for suppliers offering integrated certification packages spanning FDA-approved and GMP-compliant documentation.
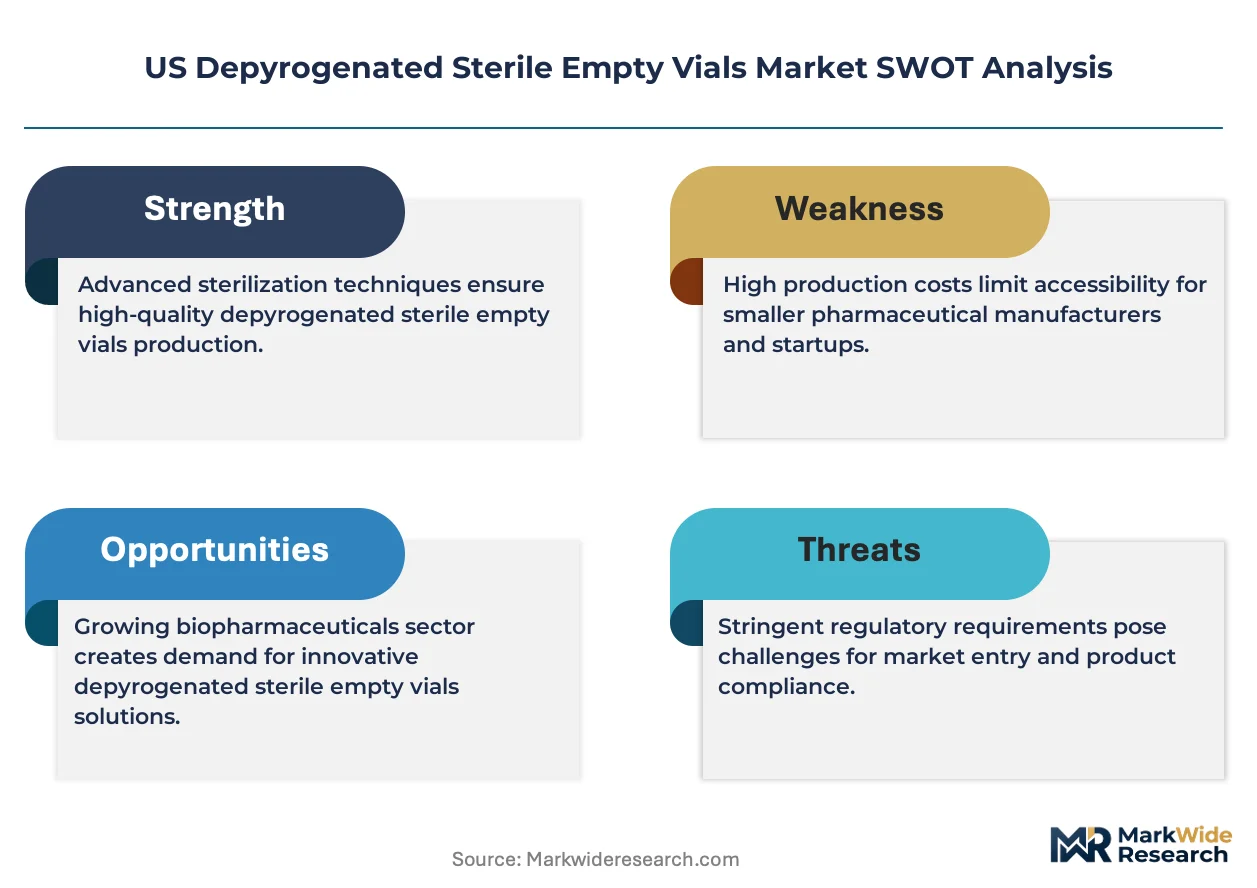
FDA Current Good Manufacturing Practice regulations, USP <85> bacterial endotoxins testing, and ISO 15378 primary packaging materials standards collectively mandate documented pyrogen control and batch-release traceability for vial suppliers. These frameworks shape demand by disqualifying uncertified entrants and rewarding manufacturers with validated sterilization cycles and complete quality documentation. Stakeholders must monitor evolving FDA guidance on container closure integrity as the agency tightens expectations for ready-to-use packaging systems in sterile drug applications.
Market Dynamics
Biologics manufacturing expansion is compressing fill-finish timelines and forcing drug sponsors toward pre-validated, ready-to-use container formats that bypass in-house depyrogenation entirely.
Growth Catalysts
- FDA sterility assurance guidelines:Tightened endotoxin thresholds below 0.25 EU/mL are disqualifying uncertified vial suppliers and consolidating procurement among validated manufacturers with complete batch documentation.
- Contract manufacturing organizations:CDMO capacity expansion across Massachusetts and New Jersey is creating concentrated demand pools for suppliers offering integrated certification packages spanning GMP compliance and container closure integrity validation.
- Cyclic olefin polymer adoption:Breakage-resistant plastic vials are penetrating biologic fill-finish lines where protein aggregation and glass delamination risks previously constrained format selection.
Market Restraints
- Type I borosilicate glass supply concentration:Specialized tubular glass sourcing depends on a limited set of European and North American forming operations, exposing buyers to geographic supply disruption.
- Dry-heat depyrogenation energy intensity:Validated endotoxin elimination cycles require sustained 250°C temperatures, embedding natural gas and electricity cost volatility directly into finished vial pricing.
- ISO 15378 compliance friction:Primary packaging materials certification demands extensive documentation of pyrogen control and traceability systems that extend supplier qualification timelines.
Strategic Opportunities
- Southeast pharmaceutical corridor:North Carolina and Georgia biomanufacturing clusters remain underpenetrated by ready-to-use vial suppliers with local sterilization and distribution infrastructure.
- Cell and gene therapy applications:Personalized medicine manufacturing requires small-batch, flexible-format containment systems that diverge from traditional large-volume parenteral packaging specifications.
- Container closure integrity testing convergence:Integration of laser-based headspace analysis with automated visual inspection systems is opening service-layer revenue for vial suppliers bundling hardware with consumable supply contracts.
Industry Challenges
- Depyrogenation validation expertise scarcity:Qualified personnel capable of executing FDA-recognized dry-heat cycle development and endotoxin challenge studies command premium compensation in tight labor markets.
- Legacy fill-finish equipment retrofit:Existing aseptic processing lines designed for bulk unprocessed vials require mechanical and software modifications to handle nested ready-to-use formats without compromising sterility assurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Depyrogenated Sterile Empty Vials Market |
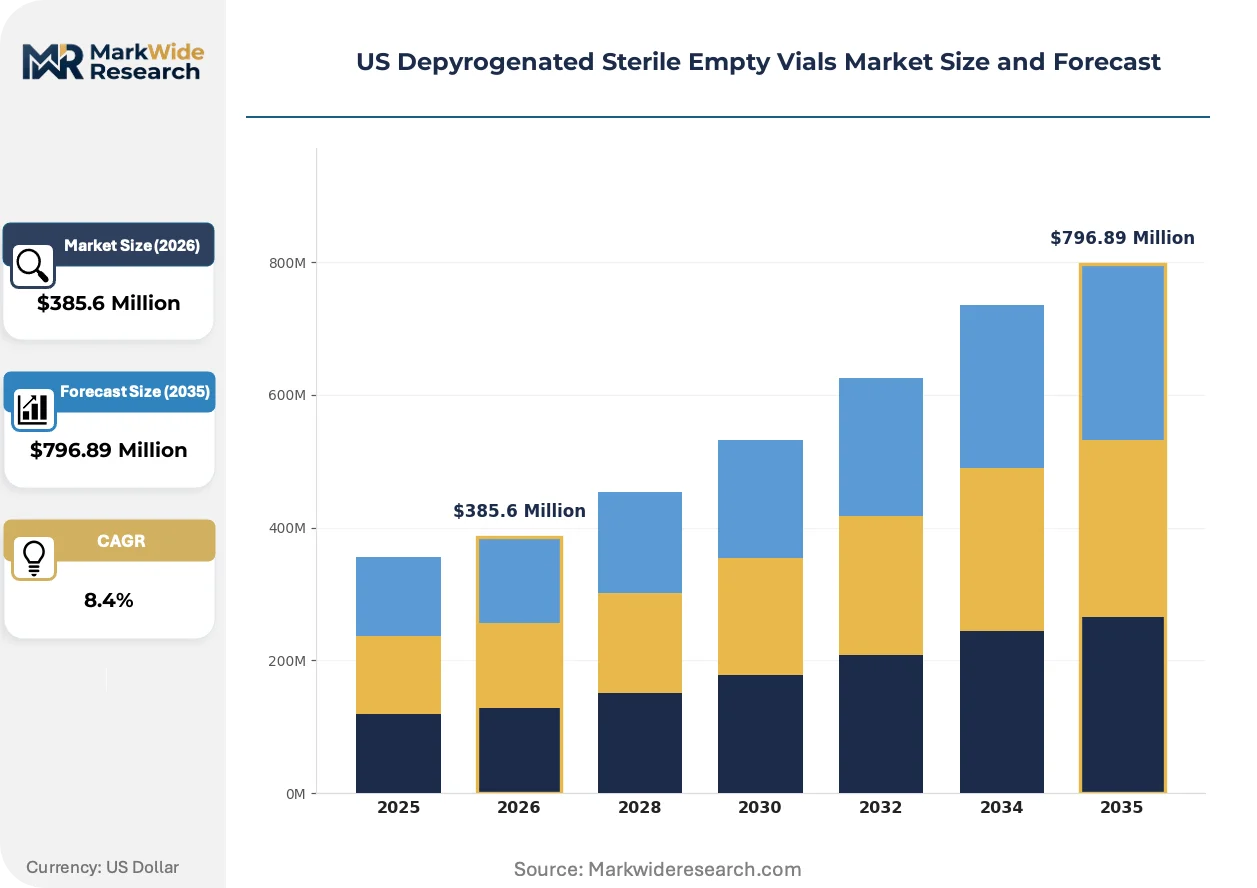
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Biodegradable Vials, Multi-Dose Vials Capacity: 1 mL, 5 mL, 10 mL, 20 mL End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Contract Manufacturing Organizations Certification: ISO, FDA Approved, CE Mark, GMP Compliant |
| Companies Covered | Thermo Fisher Scientific, Gerresheimer, SCHOTT, Stevanato Group, Corning, DWK Life Sciences, SGD Pharma, Nipro PharmaPackaging, APG Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Depyrogenated Sterile Empty Vials Market Trends and Innovations
Pre-sterilized container formats are compressing traditional supply chains and forcing vial manufacturers to embed quality documentation and logistics services directly into product offerings.
Ready-to-use nested vial configurations are fragmenting established procurement patterns. Biologic drug sponsors are adopting pre-sterilized, pre-capped formats that eliminate glass washing and depyrogenation stations from fill-finish suites. Contract manufacturers in New Jersey and Massachusetts are leading this transition, reducing facility footprint and utility loads while compressing batch release timelines. The technology is fragmenting competitive positioning by rewarding suppliers with validated sterilization partnerships and complete regulatory documentation packages over commodity glass converters.
FDA guidance on container closure integrity is tightening performance expectations for sterile drug applications. The agency's evolving position on probabilistic versus deterministic testing methods is forcing vial suppliers to invest in laser headspace analysis and high-voltage leak detection capabilities. Parenteral drug manufacturers are responding by specifying certified container closure integrity data with every vial lot, shifting supplier selection criteria toward integrated testing service providers.
Single-use format preference is consolidating procurement authority among CDMO quality departments. Biopharmaceutical sponsors are outsourcing fill-finish operations and delegating primary packaging selection to contract partners with established supplier qualification systems. This behavior is compressing the vial vendor base to manufacturers with documented FDA inspection histories and complete endotoxin control protocols. The pattern is most visible in the Northeast pharmaceutical corridor where CDMO concentration drives specification convergence toward ready-to-use formats with integrated certification.
US Depyrogenated Sterile Empty Vials Market Segmentation
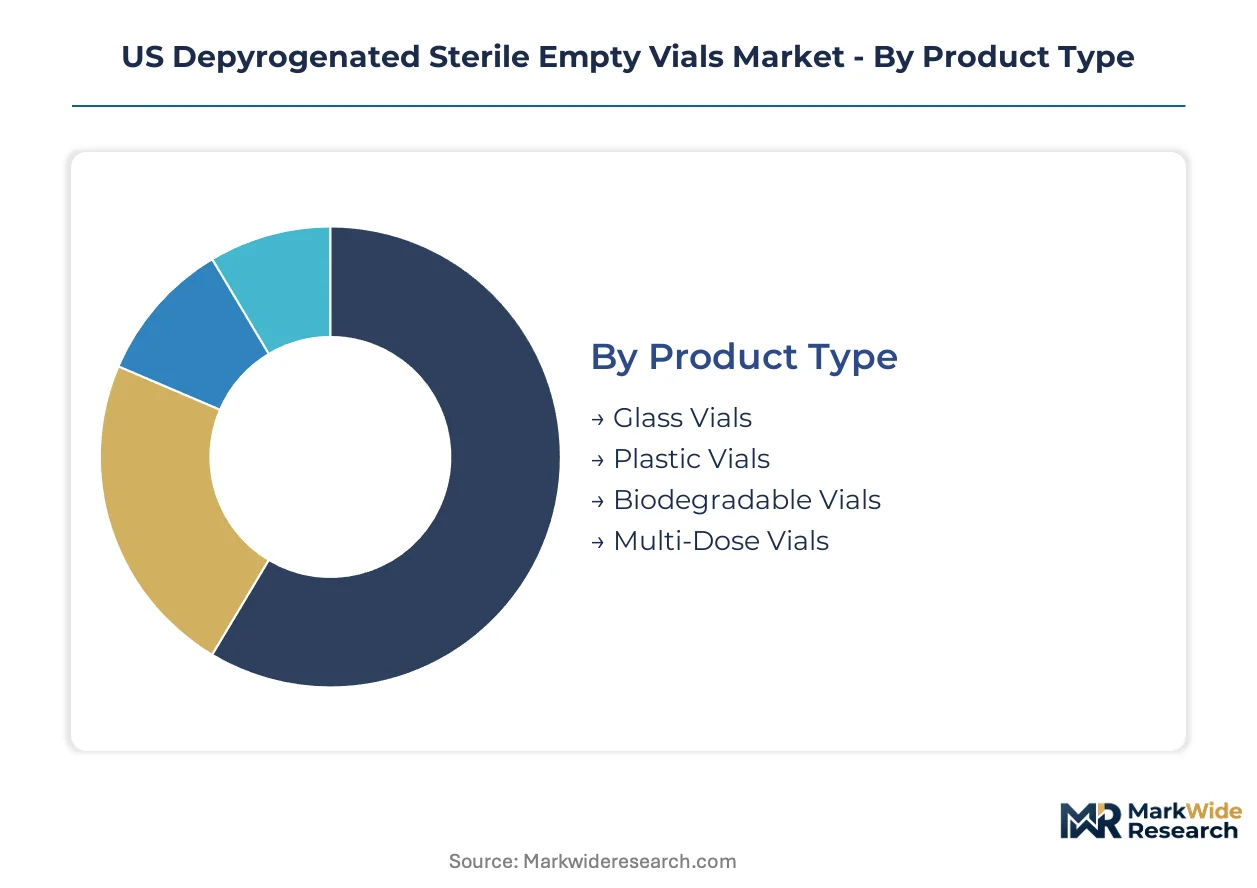
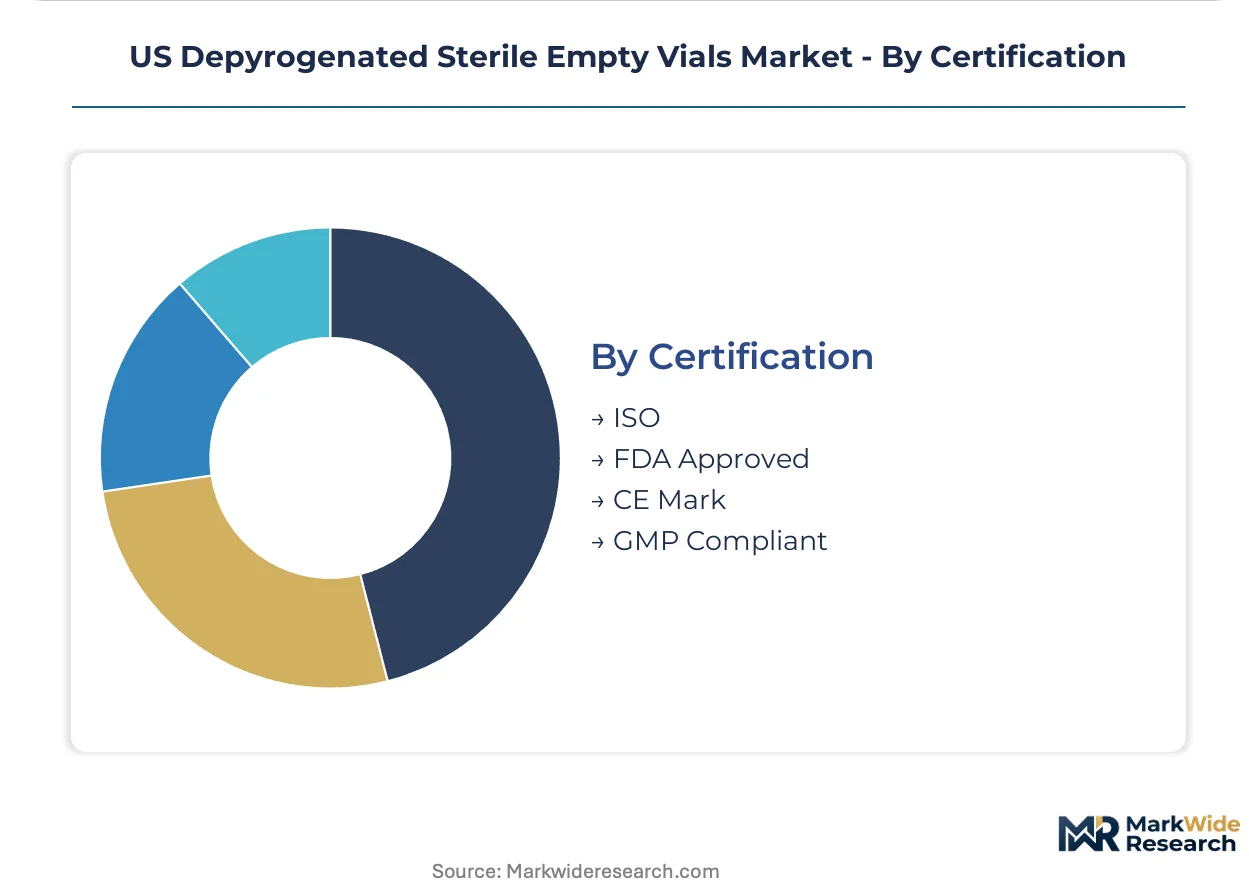
Segmentation in the US depyrogenated sterile empty vials market reveals how procurement authority concentrates among specific end-users and how certification tiers create pricing stratification. Understanding these divisions exposes where suppliers can defend margin position and where format innovation disrupts established supply relationships.
Product Type:
Margin pools concentrate in formats that eliminate downstream processing steps for fill-finish operators.
- Glass Vials:Type I borosilicate glass dominates parenteral applications requiring USP <660> chemical durability and thermal shock resistance. Massachusetts and New Jersey pharmaceutical corridors source heavily from validated tubular glass operations with complete endotoxin documentation.
- Plastic Vials:Cyclic olefin polymers and copolymers address biologic compatibility concerns where protein aggregation and glass delamination risks previously constrained format selection. CDMOs in the Northeast are adopting these for monoclonal antibody fill-finish lines.
- Biodegradable Vials:Emerging polylactic acid and starch-based alternatives target sustainability mandates from ESG-focused sponsors.
- Multi-Dose Vials:Larger-format containers with antimicrobial preservatives serve vaccine and insulin applications requiring repeated access.
The dominant share belongs to Glass Vials, while Plastic Vials is closing the gap fastest.
Capacity:
Volume concentration tracks biologic dosing trends and the shift toward personalized medicine manufacturing.
- 1 mL:Precision dosing formats for potent biologics and pediatric applications. Massachusetts cell therapy manufacturers specify these for small-batch autologous treatments.
- 5 mL:Standard fill volumes for monoclonal antibodies and vaccine presentations. New Jersey CDMOs procure nested ready-to-use configurations at this scale.
- 10 mL:Intermediate volumes for multi-dose antibiotic and hormone therapies.
- 20 mL:Large-format containment for diluents, contrast media, and bulk API storage.
Procurement weight sits heaviest with 5 mL, though 1 mL is climbing the fastest on cell therapy demand.
End User:
Customer type determines specification complexity and the value placed on integrated certification packages.
- Pharmaceutical Companies:Large sponsors with in-house fill-finish capabilities maintain dual-source strategies for glass vials while qualifying plastic alternatives for biologic portfolios.
- Biotechnology Firms:Development-stage companies prioritize ready-to-use formats that accelerate IND timelines and reduce capital expenditure on depyrogenation equipment.
- Research Laboratories:Academic and government facilities procure smaller lots with basic sterility assurance rather than full GMP documentation.
- Contract Manufacturing Organizations:CDMOs in Massachusetts and New Jersey consolidate procurement authority, specifying nested pre-sterilized formats with complete batch records and container closure integrity data.
Contract Manufacturing Organizations command the dominant procurement volume, while Biotechnology Firms are expanding their share fastest on outsourcing trends.
Certification:
Compliance tier functions as the primary price differentiator and supplier qualification gate.
- ISO:ISO 15378 primary packaging materials certification establishes baseline quality management for pyrogen control and traceability systems.
- FDA Approved:Suppliers with documented FDA inspection histories and drug master file references command premium positioning for commercial drug applications.
- CE Mark:European conformity marking relevant for US manufacturers exporting to EU markets or operating under mutual recognition agreements.
- GMP Compliant:Current Good Manufacturing Practice alignment with 21 CFR Part 210/211 requirements for sterile drug product contact materials.
FDA Approved certification holds the dominant procurement preference, while GMP Compliant is gaining ground fastest as CDMOs tighten supplier qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tubular glass forming operations cluster in the Northeast and mid-Atlantic states, with validated sterilization partnerships concentrating procurement authority among Massachusetts and New Jersey drug manufacturers. FDA inspection histories and complete batch documentation requirements reward geographic proximity between vial suppliers and fill-finish operators.
Northeast Corridor
Massachusetts biotech clusters and New Jersey pharmaceutical corridors drive concentrated demand for nested ready-to-use formats with complete endotoxin documentation. FDA sterility assurance guidelines and USP standards mandate documented pyrogen control. Cambridge and Princeton-area CDMOs specify pre-validated configurations that eliminate in-house depyrogenation equipment.
Mid-Atlantic Region
Pennsylvania and Maryland pharmaceutical manufacturing expansion creates demand pools for suppliers with local sterilization infrastructure. Current Good Manufacturing Practice regulations enforce batch-release traceability. Philadelphia and Baltimore-area contract manufacturers consolidate procurement among validated vendors with documented FDA inspection histories.
Southeast Pharmaceutical Corridor
North Carolina and Georgia biomanufacturing clusters remain underpenetrated by ready-to-use vial suppliers with regional distribution networks. State economic development incentives attract cell therapy and vaccine production. Research Triangle Park and Atlanta-area facilities represent expansion targets for sterilization-capable suppliers.
Pacific Coast
California and Washington biopharma development-stage companies prioritize ready-to-use formats accelerating IND timelines. State environmental regulations embed energy cost volatility into dry-heat depyrogenation economics. South San Francisco and Seattle-area biotechnology firms outsource fill-finish operations to CDMOs with established supplier qualification systems.
Midwest Manufacturing Belt
Illinois and Ohio pharmaceutical packaging distributors serve regional generic drug manufacturers with GMP-compliant documentation requirements. Midwest logistics networks support just-in-time delivery to fill-finish operations. Chicago and Cleveland-area facilities source from validated suppliers with complete quality management systems.
US Depyrogenated Sterile Empty Vials Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated bioproduction workflow specialists commanding premium positioning while commodity glass converters compete on volume scale. The vendor base stratifies across three tiers: multinational conglomerates with complete regulatory documentation packages, specialized primary packaging manufacturers with validated sterilization partnerships, and regional distributors serving research laboratories with basic sterility assurance. Consolidation pressures favor suppliers bundling container closure integrity testing services with consumable supply contracts.
Among diversified laboratory and bioproduction conglomerates, Thermo Fisher Scientific exemplifies the integrated workflow archetype through captive supply chain control over sterilization validation and quality documentation. Gerresheimer and SCHOTT occupy positions within the specialized glass forming tier, with German corporate structures signaling advanced forming technology capabilities and borosilicate glass processing expertise. These three entities anchor competitive dynamics by representing distinct strategic postures: full-service integration, materials specialization, and precision manufacturing technology respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Gerresheimer |
| SCHOTT |
| Stevanato Group |
| Corning |
| DWK Life Sciences |
| SGD Pharma |
| Nipro PharmaPackaging |
| APG Pharma |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between CDMOs and validated sterilization partners lock in supply access and price visibility across multi-year contract windows, insulating Northeast pharmaceutical corridors from spot-market volatility in Type I borosilicate glass feedstock.
Pricing Analysis
FDA 21 CFR Part 211 dictates the pricing tier structure across the US depyrogenated sterile empty vials market, separating FDA Approved certification holders from GMP Compliant and ISO baseline suppliers. Three-tier pricing stratification across premium, standard, and economy levels reflects endotoxin documentation completeness and batch traceability depth. Cost compression in standard-tier glass vials is intensifying because European forming operations pass through natural gas price volatility from dry-heat depyrogenation cycles. CDMO procurement departments show lowest price sensitivity given qualification timeline costs, while research laboratories exhibit highest sensitivity and accept basic sterility assurance without GMP documentation.
Supply Chain Analysis
Just-in-time inventory strategies dominate Northeast CDMO operations, with nested ready-to-use formats delivered directly to fill-finish suites on scheduled replenishment cycles rather than strategic stockpiling. Supply concentrates in Germany, the United States, and Japan for specialized tubular glass forming, with secondary polymer resin sourcing from South Korea and Singapore for cyclic olefin vial production. Raw material dependencies include high-purity silica sand, boron oxide, and pharmaceutical-grade cyclic olefin polymer resin. Single-source vulnerability in validated sterilization partnerships represents the dominant structural risk. Distribution runs through direct supplier-CDMO relationships with limited distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container closure integrity testing services represent a recurring-revenue layer expanding faster than consumable vial supply, converting hardware-adjacent validation into multi-year service contracts with Northeast pharmaceutical manufacturers.
For Market Incumbents: Shield market position by embedding laser headspace analysis capabilities into consumable supply contracts and deepening backward integration into captive sterilization validation partnerships. The threat of integrated bioproduction workflow competitors bundling complete documentation packages demands certification investment in FDA drug master file references. Capacity addition in North Carolina addresses geographic concentration risk in the Northeast corridor. For New Entrants and Emerging Players: Differentiate on Southeast pharmaceutical corridor penetration where local sterilization infrastructure remains underdeveloped relative to Massachusetts and New Jersey demand density. The most penetrable segment sits with Georgia and North Carolina cell therapy manufacturers requiring small-batch flexible-format containment systems diverging from traditional large-volume parenteral specifications. A go-to-market angle bundling container closure integrity hardware with consumable supply contracts bypasses established supplier qualification barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized primary packaging manufacturers with validated sterilization partnerships over commodity glass converters. Long-term viability across the five-to-ten year window rests on service-layer revenue attachment rates and regulatory documentation completeness rather than volume scale alone. The signal to watch as inflection indicator is FDA guidance evolution on deterministic versus probabilistic container closure integrity testing methods.| Strategic Initiative | Industry Significance |
|---|---|
| Container Closure Integrity Testing Integration | Laser headspace analysis bundling with vial supply contracts creates recurring revenue at CDMOs. |
| Southeast Sterilization Infrastructure Buildout | Regional depyrogenation capacity in North Carolina reduces logistics costs for Atlanta-area biomanufacturers. |
| FDA Drug Master File Investment | Documented inspection histories accelerate supplier qualification timelines for commercial drug applications. |
| Cell Therapy Format Development | Small-batch flexible containment systems address autologous treatment manufacturing requirements in Massachusetts clusters. |
| Backward Integration into Tubular Glass Forming | Captive borosilicate processing insulates against European supply disruption and energy cost volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fill-finish engineering directors, CDMO procurement leads, regulatory affairs specialists, and sterile packaging quality managers. Secondary validation drew from FDA 483 inspection observations, USP monograph revisions, ISO 15378 certification registries, and pharmaceutical trade customs data. Bottom-up triangulation across end-user consumption patterns converged with top-down supply-side capacity assessments.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation dimensions spanning product type, capacity tier, end-user category, and certification level alongside regional regulatory cluster intensity. CAGRs were derived from regression analysis against biologics manufacturing capacity expansion indicators and CDMO outsourcing penetration rates. Forecast inputs included dry-heat depyrogenation energy cost trajectories and FDA sterility assurance guideline revision timelines.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline investment and stable FDA regulatory frameworks would require recalibration. Forecasts reflect documented assumptions regarding CDMO consolidation patterns and endotoxin testing standard stability. Revision becomes warranted when container closure integrity testing method guidance crosses thresholds toward mandatory deterministic protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market