
 Horizontal Shaft Impact Crusher Market | 2026-2036
Horizontal Shaft Impact Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Shaft Impact Crusher Market Analysis
Aggregate production is decoupling from pure mining exposure as construction and recycling end users expand their share of horizontal shaft impact crusher procurement. McCloskey International leverages its portable product specialization to anchor North American rental channel dominance. Sandvik competes through aftermarket service density and premium wear part programs. Eagle Crusher sustains its position in asphalt recycling applications through domestic manufacturing scale.
A horizontal shaft impact crusher employs a rotating rotor with rigid blow bars that strike feed material against adjustable breaker plates, typically processing feed sizes up to 800 mm and reducing them to cubical products between 5 mm and 40 mm for concrete and road base specifications. Mobile units lead volume shipments due to quarry operators prioritizing fleet flexibility over fixed installations, while electric technology segments capture margin pools as grid-connected sites replace diesel-hydraulic systems to meet scope emissions targets.
EPA Tier 4 Final engine standards and EU Stage V emissions frameworks compel diesel technology segments toward aftertreatment integration or full electrification retrofits. OSHA machine guarding standards and ISO 21873 mobile crusher safety specifications shape product design cycles and aftermarket compliance spending. Stakeholders must monitor how carbon border adjustment mechanisms and emerging state-level quarry permitting restrictions reshape total cost of ownership calculations for fleet replacement decisions.
Market Dynamics
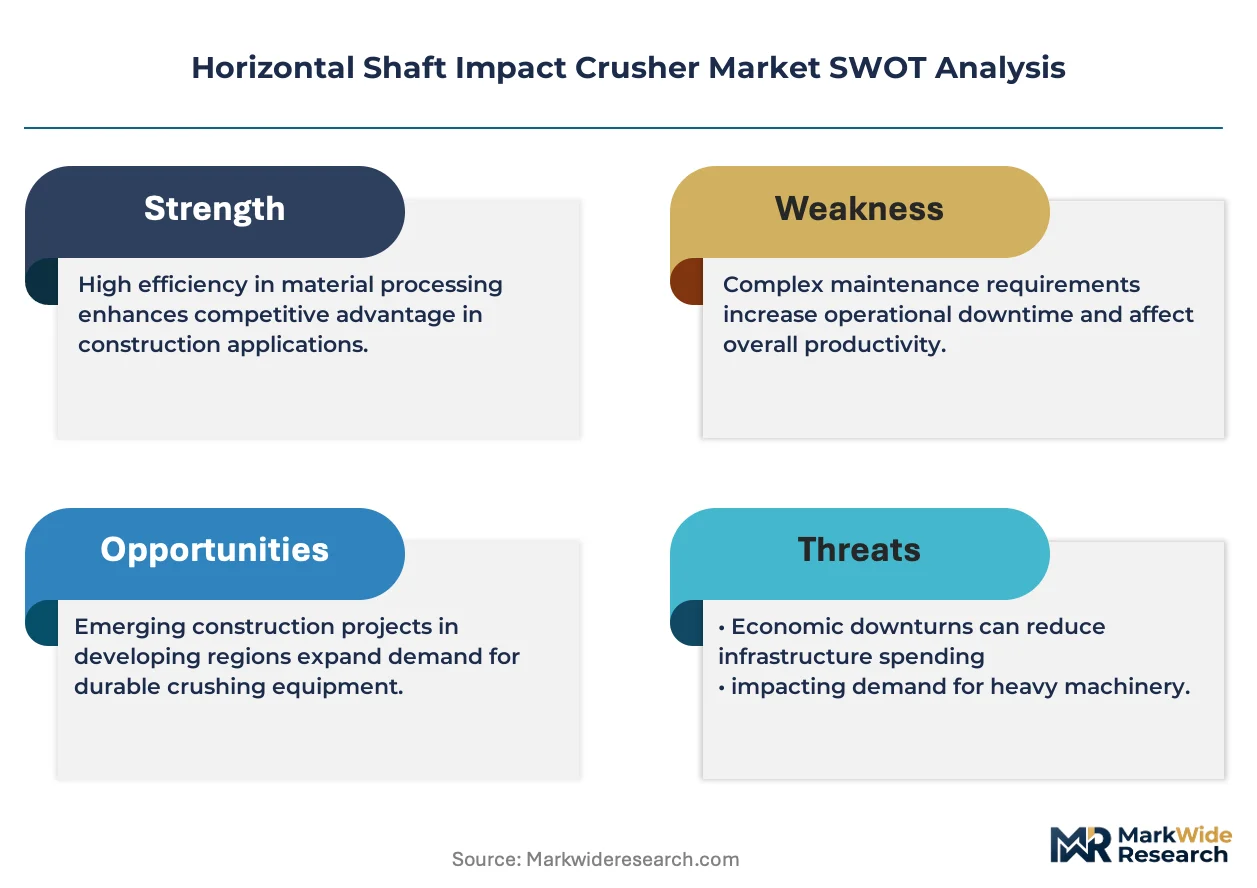
Electrification of quarry operations is compressing diesel-hydraulic equipment lifecycles as grid-connected sites seek to neutralize scope emissions exposure. Fleet operators now face replacement mathematics where carbon border adjustment mechanisms and state-level permitting restrictions alter total cost of ownership calculations.
Growth Catalysts
- EPA Tier 4 Final standards:Aftertreatment integration mandates are forcing diesel technology segments toward hybrid architectures or full electric retrofits, expanding addressable market for electric crusher variants.
- India's western states:National Highway Authority infrastructure deployment concentrates equipment procurement in Maharashtra and Gujarat, creating localized demand surges for mobile crushing units.
- Recycling infrastructure scaling:Construction and demolition waste processing facilities are decoupling aggregate production from pure mining exposure, diversifying end-user procurement bases.
Market Restraints
- High-grade manganese steel volatility:Blow bar and liner input costs fluctuate with mining output constraints, compressing margin pools for wear part suppliers.
- Breaker plate fabrication concentration:Specialized foundry capacity clusters in select industrial regions, creating supply bottlenecks during demand spikes.
- EU F-Gas Regulation:Hydraulic system refrigerant compliance adds retrofit costs to legacy diesel-hydraulic units, extending replacement cycles.
Strategic Opportunities
- Remote monitoring convergence:Telematics platforms integrating vibration analysis and predictive wear algorithms enable outcome-based service contracts for fleet operators.
- India's secondary cities:Smart city initiatives and urban renewal projects in tier-2 municipalities expand addressable market beyond traditional highway construction.
- Carbon border adjustment mechanisms:Embedded emissions accounting creates competitive advantage for manufacturers with documented supply chain decarbonization.
Industry Challenges
- Rotor balancing technician scarcity:Precision assembly skills for high-speed impact crushers lag equipment complexity, extending commissioning timelines.
- ISO 21873 certification timelines:Mobile crusher safety specification compliance requires extensive testing protocols, delaying product launches.
- Legacy fleet integration complexity:Electric crusher retrofits demand grid infrastructure upgrades at established quarry sites, complicating capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Shaft Impact Crusher Market |
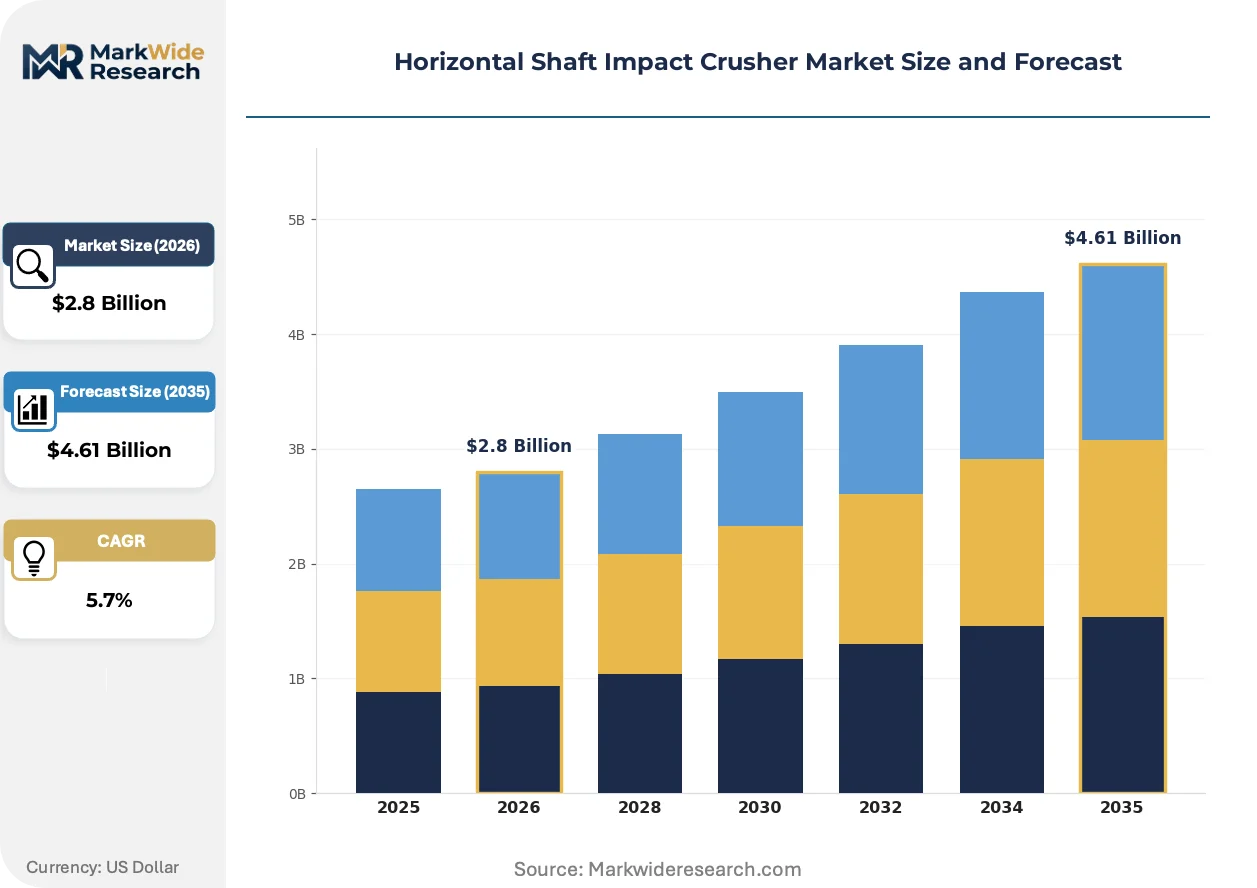
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Portable, Mobile, Stationary End User: Construction, Mining, Recycling, Aggregate Production Technology: Electric, Hydraulic, Pneumatic, Diesel Application: Crushing, Screening, Material Handling, Waste Management |
| Companies Covered | McCloskey International, Astec Industries, Metso Outotec, Shanghai SANME Mining Machinery Corporation, McLanahan Corporation, Sandvik, Eagle Crusher, Wirtgen Group, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Shaft Impact Crusher Market Emerging Trajectories
Powertrain architecture decisions now dominate equipment procurement as emissions accounting extends beyond tailpipe to full lifecycle carbon. Technical innovation clusters around electrification pathways, regulatory compliance automation, and service model restructuring.
Permanent magnet synchronous motor drives are electrifying mobile crusher propulsion and crushing functions simultaneously. Quarry operators with grid access are replacing diesel-hydraulic powertrains to secure operational permits in emissions-restricted zones. This shift is electrifying competitive positioning for manufacturers with integrated electric architectures, compressing market share for pure diesel specialists.
EU Stage V emissions frameworks compel aftertreatment system integration across diesel technology segments. Industrial consequence includes elevated equipment base prices and extended maintenance intervals for selective catalytic reduction components. Mobile units operating in European urban proximity zones face the strictest compliance thresholds, accelerating electric technology adoption.
Rental channel preference is consolidating fleet decisions around short-term flexibility rather than long-term ownership. Quarry operators and contractors now prioritize equipment availability over capital deployment, shifting volume toward rental-specialized distributors. This pattern concentrates most visibly in North American construction markets where project-based demand fluctuates seasonally.
Horizontal Shaft Impact Crusher Market Segmentation
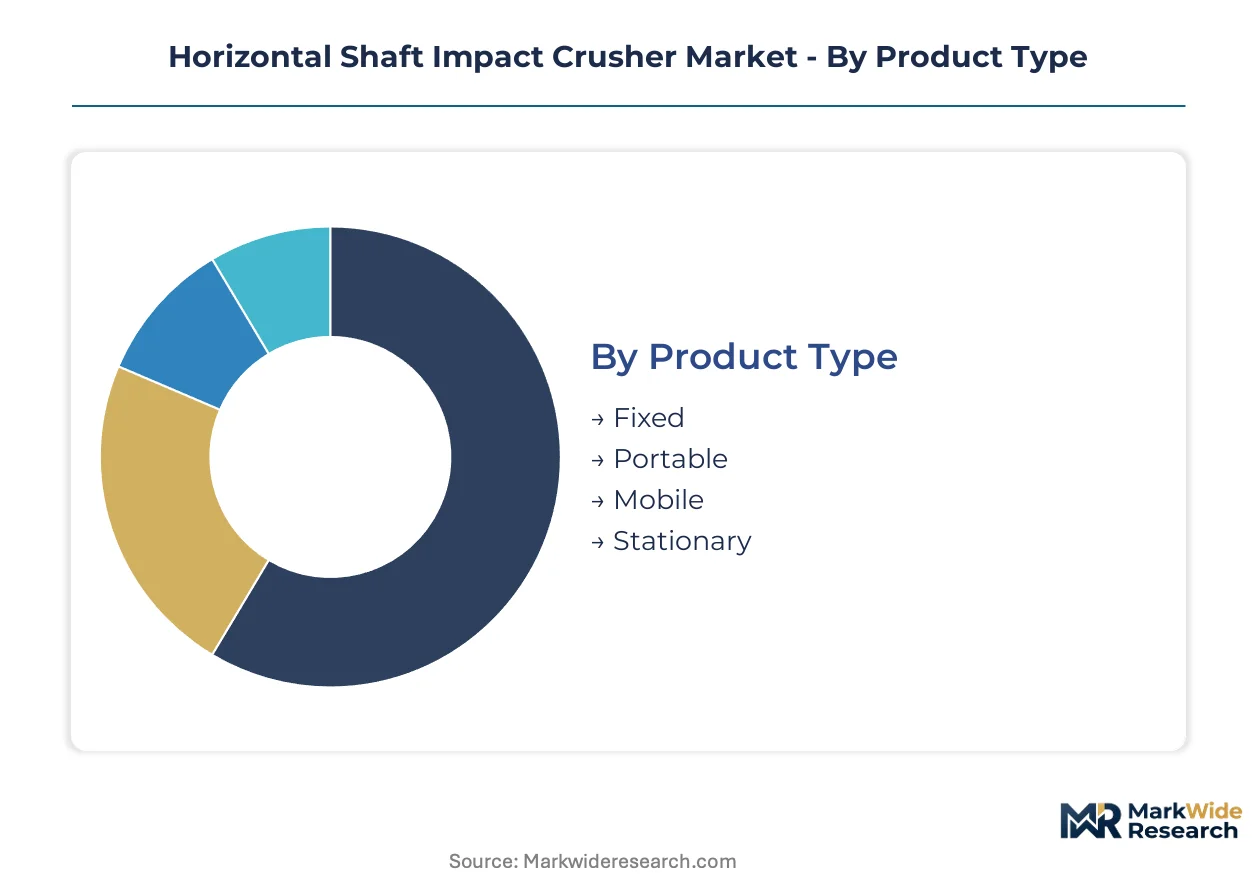
Horizontal shaft impact crusher procurement patterns diverge sharply across operational contexts. Product mobility, powertrain architecture, and end-use material specifications create distinct competitive arenas with separate margin profiles and replacement cycles.
Product Type:
Foundry capacity for specialized rotor housings concentrates manufacturing in established industrial clusters, creating supply bottlenecks during infrastructure investment surges.
- Fixed:Permanent installations anchor high-volume quarry operations with dedicated grid connections. Cement producers in Maharashtra and Gujarat favor fixed configurations for National Highway Authority aggregate supply contracts requiring continuous output.
- Portable:Skid-mounted units bridge mobility and stability for contractors serving multiple project sites. Road construction crews in India's western states deploy portable crushers to follow highway corridor progression without capital duplication.
- Mobile:Tracked propulsion systems dominate rental channel procurement where fleet flexibility outweighs unit economics. Quarry operators prioritize mobile units for rapid site relocation and permit-driven operational windows.
- Stationary:Heavy-frame installations process the largest feed sizes for mining-scale reduction. Integrated processing plants specify stationary units for captive aggregate production decoupled from external supply.
Today's leader: Mobile. Tomorrow's challenger: Portable.
End User:
Customer procurement sophistication varies dramatically across material sourcing strategies, with recycling infrastructure scaling fastest among non-traditional buyers.
- Construction:General contractors specify mobile units for project-based aggregate demand with seasonal fluctuation. Telematics integration enables rental channel dominance for short-term fleet deployment.
- Mining:Traditional extraction operations favor fixed installations with premium wear part programs. Sandvik's aftermarket service density targets mining procurement committees with lifecycle cost optimization.
- Recycling:Construction and demolition waste processors are climbing the fastest as circular economy mandates expand feedstock availability. EPA emissions standards accelerate electric crusher adoption for urban material recovery facilities.
- Aggregate Production:Dedicated producers balance captive quarry output with external sales to ready-mix concrete suppliers. McCloskey International's portable specialization captures North American independent producer demand.
Recycling end users are gaining share fastest; mining retains absolute volume dominance but faces procurement decoupling.
Technology:
Powertrain selection now determines permit eligibility in emissions-restricted zones, compressing diesel-hydraulic equipment lifecycles.
- Electric:Permanent magnet synchronous motor drives eliminate tailpipe emissions for grid-connected quarry sites. EU Stage V compliance costs accelerate electric adoption in European urban proximity zones.
- Hydraulic:Legacy diesel-hydraulic systems face EU F-Gas Regulation retrofit requirements for refrigerant compliance. Extended replacement cycles emerge as operators delay capital deployment pending electrification clarity.
- Pneumatic:Compressed air drives serve specialized underground applications with explosion safety requirements. Limited deployment constrains aftermarket parts availability and service technician training.
- Diesel:EPA Tier 4 Final aftertreatment integration elevates base equipment pricing and maintenance complexity. Selective catalytic reduction component intervals reshape total cost of ownership calculations for fleet operators.
Electric technology captures margin expansion; diesel retains installed base dominance pending replacement cycle timing.
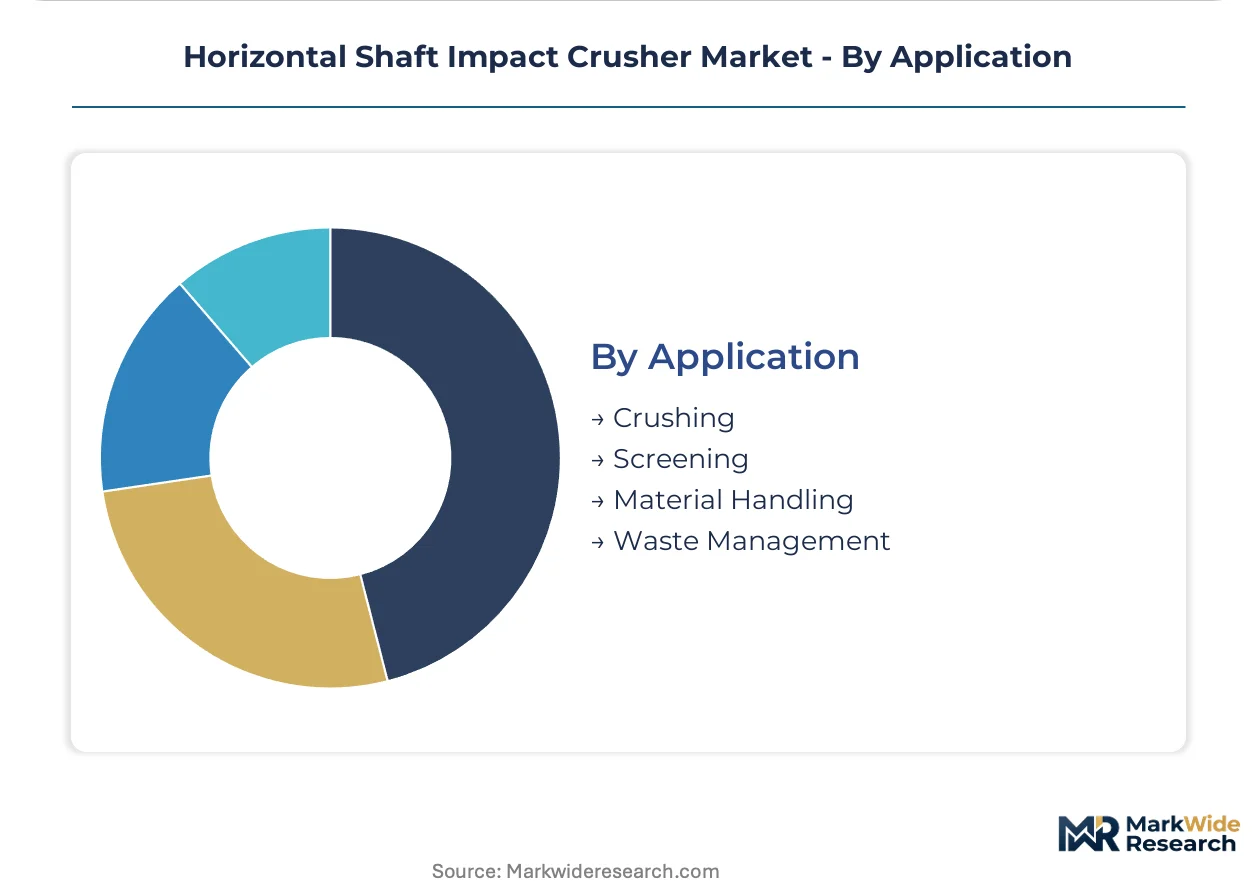
Application:
Downstream process integration determines equipment specification intensity, with multi-function units commanding premium positioning.
- Crushing:Primary reduction functions with rigid blow bars and adjustable breaker plates define core horizontal shaft impact crusher value. Rotor balancing precision requirements create technician scarcity bottlenecks during commissioning.
- Screening:Integrated sizing decks reduce material handling stages for cubical product specifications between 5 mm and 40 mm. Concrete and road base producers specify combined crushing-screening units for quality consistency.
- Material Handling:Feed and discharge conveyor integration determines throughput optimization for continuous operations. Mobile unit designers prioritize folding transport configurations for rapid site establishment.
- Waste Management:Specialized liner configurations process contaminated construction debris with extended wear part lifecycles. Recycling facility operators demand outcome-based service contracts for unpredictable feedstock variability.
Crushing remains the revenue anchor; waste management applications are expanding most quickly through circular economy infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat anchor equipment procurement intensity through National Highway Authority corridor development. Grid-connected quarry sites in these western states accelerate electric crusher adoption ahead of diesel-hydraulic replacement cycles.
United States
Asphalt recycling facilities in Ohio and Pennsylvania drive mobile unit demand for construction material recovery. EPA Tier 4 Final standards compress diesel equipment lifecycles toward hybrid or electric retrofits. McCloskey International's rental channel specialization captures seasonal construction demand fluctuations across the Great Lakes region.
Germany
Quarry operators in North Rhine-Westphalia face EU Stage V emissions thresholds for urban proximity zone permits. EU F-Gas Regulation compliance adds refrigerant retrofit costs to legacy hydraulic systems. Sandvik's aftermarket service density targets cement producers in the Rhineland with lifecycle cost optimization programs.
India
National Highway Authority projects concentrate crusher deployment in Maharashtra and Gujarat for aggregate supply contracts. BIS certification requirements shape equipment specification standards for domestic procurement. Smart city initiatives in Pune and Ahmedabad expand demand beyond traditional highway construction into urban renewal applications.
China
Yangtze River Delta infrastructure investment sustains stationary unit demand for high-volume cement production. MIIT industrial equipment standards accelerate permanent magnet synchronous motor adoption in grid-connected sites. Zhengzhou-based fabricators supply the domestic mining sector with heavy-frame configurations for captive aggregate production.
Australia
Western Australia iron ore operations favor fixed installations with premium wear part programs for continuous output. ISO 21873 mobile crusher safety specifications delay product launches for export-oriented manufacturers. Perth-based quarry operators prioritize fleet flexibility for rapid site relocation across remote mining tenements.
Horizontal Shaft Impact Crusher Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek electrification technology access and regional distribution reach. The vendor base organizes into three tiers: multinational full-line suppliers with aftermarket density, regional specialists with rental channel focus, and domestic fabricators serving captive mining demand. Two archetypes define positioning: integrated technology providers bundling electric powertrains with predictive maintenance platforms, and mobility-first specialists optimizing rapid deployment logistics. M&A activity concentrates on telematics capabilities and foundry capacity for specialized wear components.
Among North American mobility specialists, McCloskey International and Eagle Crusher exemplify rental channel anchoring and asphalt recycling application focus respectively. Astec Industries occupies a position bridging portable configuration expertise with domestic manufacturing scale. Shanghai SANME Mining Machinery Corporation represents the Chinese domestic fabricator archetype targeting mining-scale stationary demand. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| McCloskey International |
| Astec Industries |
| Metso Outotec |
| Shanghai SANME Mining Machinery Corporation |
| McLanahan Corporation |
| Sandvik |
| Eagle Crusher |
| Wirtgen Group |
| Terex Corporation |
| Others |
Supply Flow & Price Mechanics
Permanent magnet synchronous motor adoption is compressing diesel-hydraulic equipment valuations while concentrating procurement power among grid-connected quarry operators with capital for electrification retrofits. This technology transition simultaneously elevates upfront cost thresholds for electric variants and fragments supplier pricing power across legacy and emerging powertrain architectures.
Pricing Analysis
Input-cost pass-through from high-grade manganese steel volatility shapes blow bar and liner pricing tiers, with foundry capacity constraints in select industrial regions amplifying premium-standard-economy differentiation across wear part programs. EPA Tier 4 Final aftertreatment integration and EU Stage V compliance costs elevate base equipment pricing for diesel technology segments. Price compression runs through hydraulic system tiers as EU F-Gas Regulation refrigerant retrofit requirements extend replacement cycles. Rental channel buyers exhibit highest price sensitivity due to project-based demand fluctuation, while cement producers in Maharashtra and Gujarat prioritize lifecycle cost optimization over upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining demand for stationary units, while rental-specialized distributors dominate mobile crusher procurement across North American construction markets. Foundry capacity for specialized rotor housings and breaker plate fabrication concentrates in Germany, China, and India, with Zhengzhou-based fabricators supplying heavy-frame configurations for captive aggregate production. Supply chains draw from manganese mining output in South Africa and Australia, coupled with specialized steel alloying inputs from Japanese and European metallurgical producers. Single-source vulnerability around precision rotor balancing technician scarcity extends commissioning timelines. Distribution runs through aftermarket service networks where Sandvik's density targets mining procurement committees with wear part lifecycle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electric technology adoption and recycling infrastructure scaling concentrate procurement among operators seeking premium specifications with documented emissions compliance.
For Market Incumbents: Hedge diesel technology exposure through hybrid architecture development or full electric retrofit capabilities as carbon border adjustment mechanisms reshape fleet replacement mathematics. Defensive consolidation should prioritize foundry capacity for specialized wear components and telematics platform integration enabling predictive maintenance contracts. Channel control through rental-specialized distributor networks protects against mobility-first specialists capturing seasonal construction demand. For New Entrants and Emerging Players: EU Stage V emissions frameworks in Germany open a window for electric crusher variants targeting urban proximity zone quarry operators facing strictest compliance thresholds. White-space opportunities concentrate in India's tier-2 smart city initiatives beyond traditional National Highway Authority corridor development, and in construction and demolition waste processing facilities requiring outcome-based service contracts for unpredictable feedstock. Go-to-market positioning should anchor on remote monitoring convergence with vibration analysis and predictive wear algorithms. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mobility specialists with rental channel focus but limited aftermarket service density. Long-term viability over the next decade hinges on electrification technology access and documented supply chain decarbonization for carbon border adjustment compliance. Acquisition targets should exhibit integrated electric architectures or captive foundry capacity for specialized wear components. The signal to watch is permitting restriction acceleration in emissions-restricted zones compressing diesel-hydraulic replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive supply of high-grade manganese blow bars insulates margin pools from mining output constraints. |
| Electric Powertrain Platform Development | Permanent magnet synchronous motor integration secures permit eligibility in EU Stage V urban proximity zones. |
| Predictive Maintenance Platform Launch | Telematics integrating vibration analysis enables outcome-based service contracts for recycling facility operators. |
| Rental Channel Distribution Expansion | Equipment availability prioritization captures seasonal construction demand fluctuations across North American markets. |
| Regulatory Compliance Certification Investment | ISO 21873 mobile crusher safety specification accelerates product launch timelines for export-oriented manufacturers. |
Methodological Framework
Direct dialogue with quarry maintenance directors, OEM procurement teams, aftermarket service heads, and rental channel distributors anchored qualitative insight generation. Secondary validation drew from EPA emissions filings, EU Stage V compliance databases, MIIT industrial equipment standards, BIS certification records, and customs trade data for manganese steel alloying inputs. Bottom-up equipment shipment analysis triangulated against top-down infrastructure investment tracking across National Highway Authority projects and smart city initiatives.
Segment-level outputs across product mobility, powertrain architecture, end-use application, and regional regulatory clusters were generated through the projection horizon. CAGRs were derived from equipment replacement cycle modeling incorporating emissions compliance cost trajectories and grid infrastructure expansion patterns. Forecast inputs included quarry electrification adoption curves, recycling infrastructure capacity buildouts, and foundry capacity utilization for specialized wear components.
Revisions become necessary when carbon border adjustment mechanism implementation accelerates, state-level quarry permitting restrictions tighten, or manganese mining output constraints intensify beyond baseline assumptions. Forecasts reflect documented assumptions regarding electrification technology cost curves and regulatory enforcement timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Continuous Miners Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Global Dozers Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Underground Mining Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Mining Tester Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Rock Drill Shank Adaptor Market