
 Continuous Miners Market | 2026-2036
Continuous Miners Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Miners Market Analysis
Project finance tied to equipment leasing and asset-light contracting is fragmenting the competitive landscape for continuous mining systems. Komatsu Ltd. leverages its global service network to sustain aftermarket revenue streams across captive coal operations. Caterpillar Inc. anchors North American demand through integrated power and cutting technology platforms. Sandvik AB differentiates via narrow-vein specialization for hard-rock applications where standard units underperform.
Continuous miners are self-propelled cutting machines designed to extract coal and soft minerals through a rotating drum mechanism with carbide-tipped picks, typically operating at cutting heights between 1.3 and 6.0 meters and conveying broken material via an integral chain conveyor to shuttle cars or bridge conveyors. Electric drive technology leads the technology segment as underground operators replace diesel-hydraulic fleets to comply with ventilation and emissions standards, while teleoperation represents the fastest-growing technology category as remote operation centers reduce workforce exposure in gassy seams. The application segment tilts toward coal mining where longwall development and room-and-pillar methods consume the majority of new machine deliveries, though tunneling applications for infrastructure projects are expanding the addressable base.
The EPA enforces diesel particulate matter limits through 30 CFR Part 72 that constrain engine specifications for underground continuous miners, while MSHA mandates proximity detection systems under 30 CFR 75.1732 to prevent crushing incidents during tramming operations. OSHA standards for noise exposure and respirable dust further shape machine enclosure and ventilation designs. Stakeholders must weigh electrification capital costs against regulatory compliance timelines and ventilation infrastructure savings.
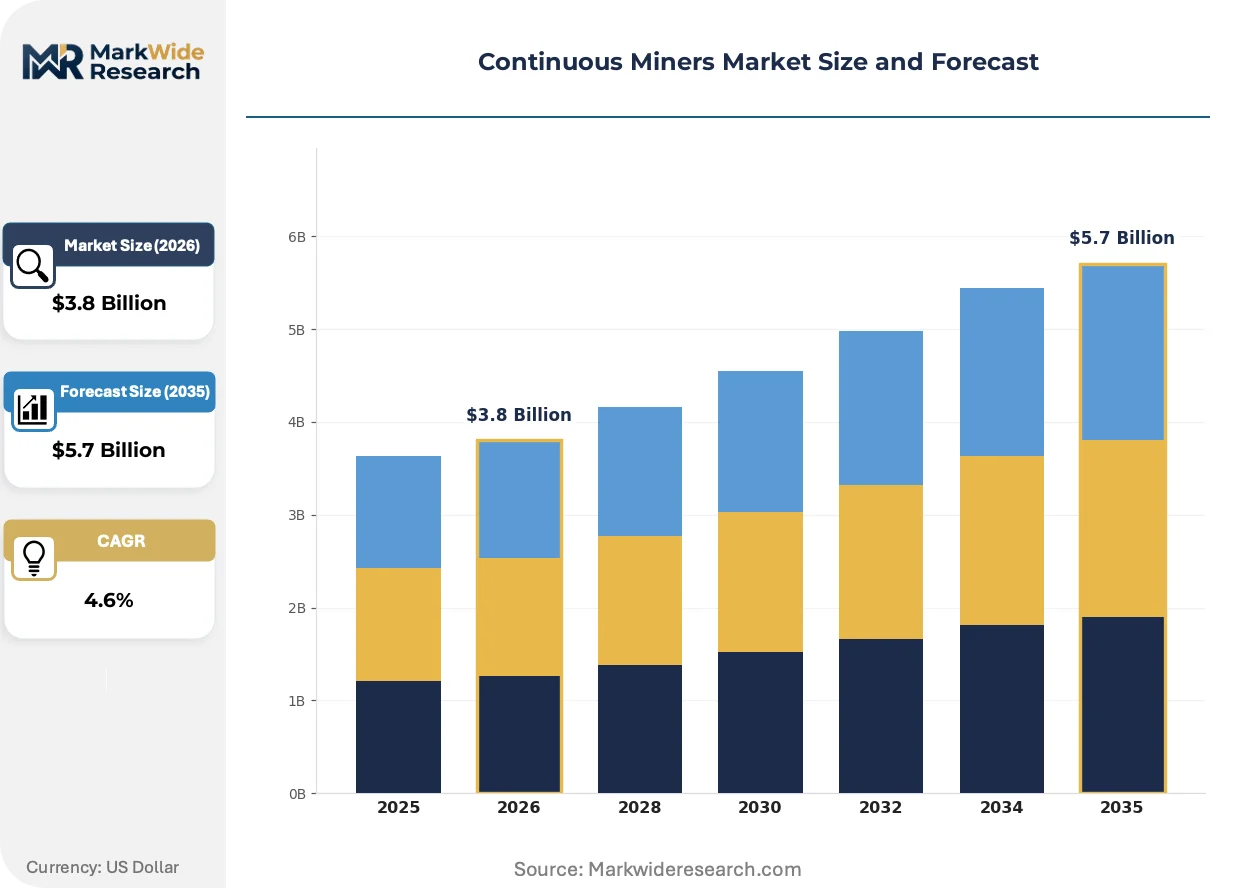
Market Dynamics
Electrification mandates from underground safety regulators are forcing diesel-hydraulic fleet retirements faster than capital replacement cycles, compressing equipment procurement timelines and reshaping vendor-customer contracting structures.
Growth Catalysts
- EPA 30 CFR Part 72 diesel particulate limits:Underground coal operators in Queensland's Bowen Basin must replace non-compliant engines, triggering equipment refresh cycles.
- Teleoperation centers:Remote operation technology eliminates workforce exposure in gassy seam environments, expanding addressable mine depth and seam complexity.
- Room-and-pillar method expansion:Thin-seam coal deposits in Appalachia and the Powder River Basin require continuous miner deployment for viable extraction economics.
Market Restraints
- Battery energy density limitations:Electric drive systems face operational range constraints in multi-shift underground operations without mid-shift charging infrastructure.
- Cutting tool supply concentration:Tungsten carbide pick manufacturing concentrates in Chinese smelting corridors, exposing buyers to raw material export control risks.
- Ventilation infrastructure retrofit costs:Electrification requires cable routing and substation installation that exceeds original mine development capital allocations.
Strategic Opportunities
- Infrastructure tunneling applications:Urban subway and utility corridor projects in India and Southeast Asia represent untapped demand outside captive coal operations.
- MSHA 30 CFR 75.1732 proximity detection mandates:Regulatory compliance creates aftermarket retrofit and integrated system bundling opportunities for safety technology providers.
- Condition monitoring convergence:Vibration sensing and predictive analytics integration enables uptime-based service contracting distinct from traditional equipment sales.
Industry Challenges
- Underground electrician certification timelines:Electric drive maintenance requires specialized trade credentials that training programs cannot produce at fleet replacement velocity.
- Legacy diesel-hydraulic parts rationalization:Manufacturers face portfolio complexity decisions as electrified platforms diverge from established component supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Miners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Surface Miners, Auger Miners, Rock Dusting, Vertical Shaft Miners Application: Coal Mining, Mineral Extraction, Quarry Operations, Tunneling Technology: Hydraulic Systems, Electric Drive, Computer-Controlled, Teleoperation End User: Mining Companies, Contractors, Government Agencies, Research Institutions |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Sandvik AB, Eickhoff Bergbautechnik GmbH, Epiroc AB, FAMUR S.A., Atlas Copco AB, Joy Global Inc., XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Miners Market Emerging Trajectories
Digital twin technology and autonomous tramming systems are compressing the gap between surface control centers and underground cutting faces, redefining operational staffing models and capital deployment patterns.
Teleoperation infrastructure is virtualizing the physical presence of machine operators above ground. Coal operators in Australia's Queensland region are deploying fiber-linked control rooms that manage multiple cutting units across dispersed longwall developments. This virtualization eliminates ventilation requirements for manned cabins and permits workforce consolidation in regional processing hubs rather than remote camp accommodations.
MSHA proximity detection enforcement under 30 CFR 75.1732 is mandating collision-avoidance sensor arrays on all tramming equipment. Underground operators must integrate radar and ultrasonic systems that automatically brake machines when personnel enter defined exclusion zones. Room-and-pillar operations in Appalachia face the steepest compliance curve due to confined heading geometries and legacy fleet density.
After-sales service unbundling is fragmenting traditional equipment procurement relationships. Mine operators in South Africa's Highveld coalfields are separating cutting unit purchases from maintenance contracts, sourcing spare parts through third-party distributors and performing overhauls through independent workshops. This disintermediation pressures OEM margin structures while expanding the addressable market for component specialists.
Continuous Miners Market Segmentation
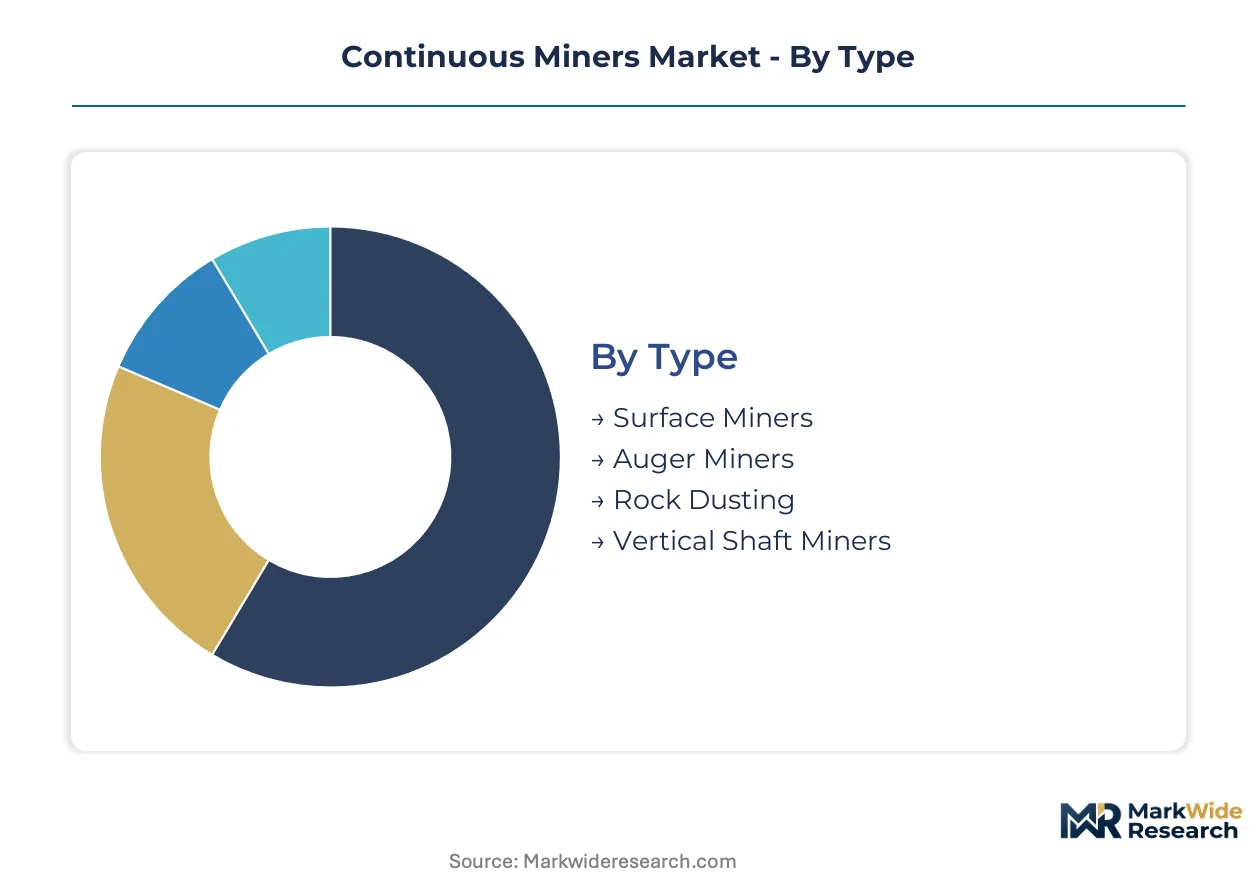
Segmentation in continuous miners determines aftermarket service intensity, spare parts velocity, and equipment financing structures. Mining contractors prioritize rental flexibility over ownership, while captive operators optimize for total cost of ownership across 15-year fleet cycles.
Type:
After-sales service intensity varies sharply by machine type, with cutting drum rebuilds and conveyor chain replacements driving recurring revenue for surface-dominant configurations.
- Surface Miners:These machines extract material through rotating drums operating at cutting heights above seam level, eliminating the need for drilling and blasting. Australian open-cut coal operations in the Hunter Valley deploy surface miners for overburden removal where diesel particulate regulations are less restrictive than underground environments. Cutting tool consumption runs higher than underground equivalents due to abrasive overburden composition.
- Auger Miners:Horizontal boring machines extract coal through spiral flighting that conveys material directly to surface without auxiliary haulage. Appalachia's contour strip operations use auger miners to recover thin seams beneath highwalls where conventional equipment cannot operate. The technology faces declining deployment as MSHA ground control standards tighten highwall stability requirements.
- Rock Dusting:Specialized units distribute inert limestone dust to suppress combustible coal dust in underground headings. Regulatory mandates in US and Australian coal operations sustain fleet deployment regardless of production economics.
- Vertical Shaft Miners:Shaft-sinking machines excavate vertical openings through full-face cutting mechanisms for mine development and ventilation infrastructure. South African platinum belt operators deploy these units for deep-level shaft sinking where labor-intensive drill-and-blast methods face productivity constraints.
Surface Miners holds the largest share; momentum sits with Auger Miners in thin-seam recovery applications.
Application:
Application focus shapes capital deployment cycles, with coal mining commanding multi-unit fleet purchases while tunneling contracts favor single-machine procurement with maintenance-included leasing.
- Coal Mining:Room-and-pillar and longwall development methods consume the majority of continuous miner deliveries. Queensland's Bowen Basin longwall operations require higher-capacity cutting units with integrated bolting platforms for rapid entry development. EPA emissions rules tighten diesel particulate limits, forcing fleet electrification in US and Australian underground operations.
- Mineral Exstrong>Mineral Extraction:Potash, trona, and salt mining applications demand corrosion-resistant materials and explosion-proof electrical systems. Saskatchewan's potash corridor sustains specialized machine demand with cutting heights optimized for 2.1-meter seams.
- Quarry Operations:Dimension stone and aggregate producers deploy modified continuous miners for selective excavation where blasting damages product quality. Italian Carrara marble quarries use electric-drive units for precision bench cutting.
- Tunneling:Urban subway and utility corridor projects in India and Southeast Asia represent expanding demand outside captive mining. Mumbai Metro Line 3 contractors deployed teleoperated continuous miners for station box excavation through basalt formations.
Coal Mining retains dominant volume; tunneling climbs fastest as infrastructure investment accelerates in South and Southeast Asia.
Technology:
Technology selection determines ventilation infrastructure requirements, workforce certification needs, and regulatory compliance timelines across jurisdictions.
- Hydraulic Systems:Diesel-hydraulic power trains dominate legacy fleets but face accelerated retirement under underground emissions standards. US coal operators in Appalachia maintain hydraulic spare parts inventories while transitioning procurement to electric platforms.
- Electric Drive:AC and DC electric systems eliminate diesel particulate emissions and reduce ventilation requirements. Australian underground operators in Queensland's gassy seams prioritize electric drive for regulatory compliance and workforce safety.
- Computer-Controlled:Automated cutting sequences and horizon control systems optimize extraction consistency. South African platinum mines deploy computer-controlled units for narrow-vein extraction where grade variability demands precise cutting depth management.
- Teleoperation:Fiber-linked surface control centers eliminate operator exposure in hazardous headings. Australian coal operators deploy multi-machine control rooms that manage cutting units across dispersed longwall developments.
Electric Drive commands current procurement volume; teleoperation gains share fastest as labor costs and safety liabilities reshape staffing models.
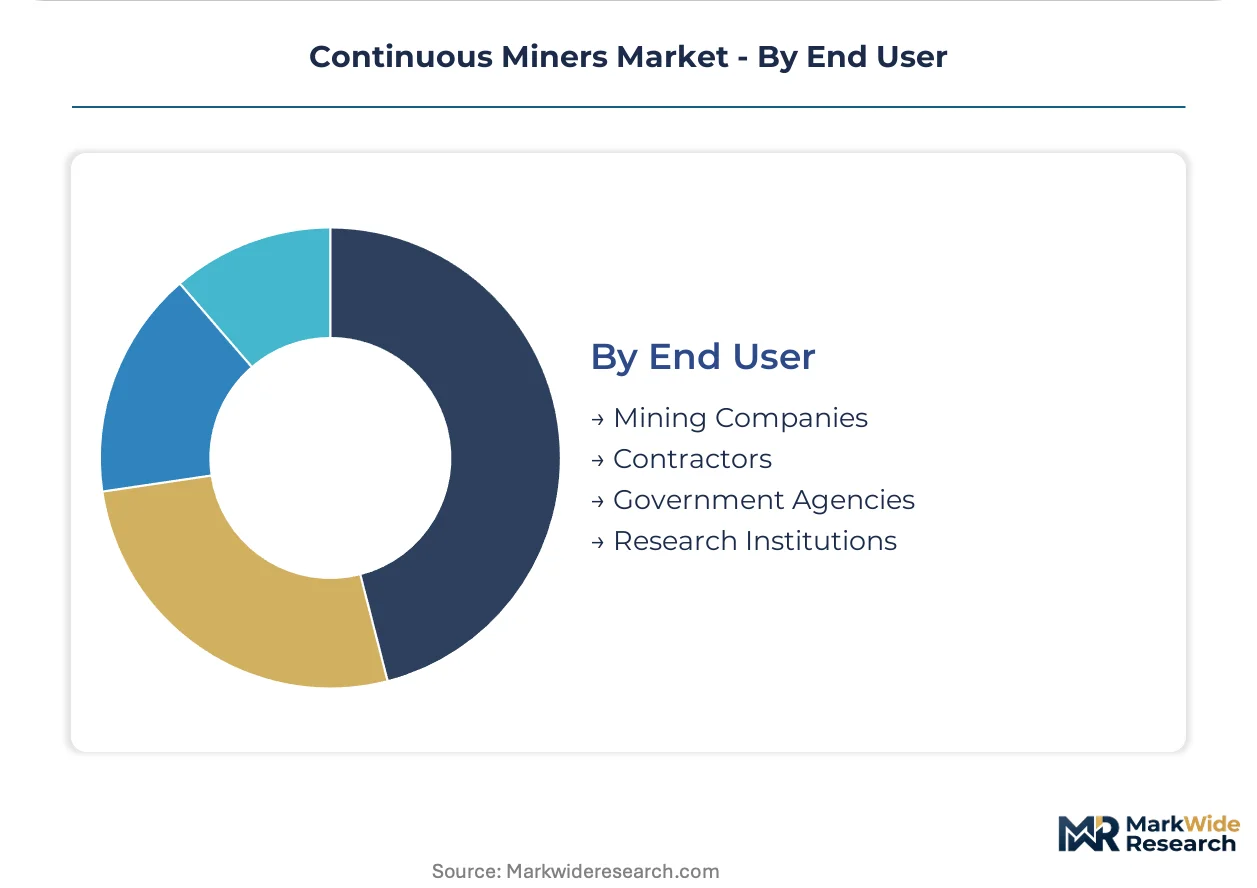
End User:
End-user category determines financing structure, with mining companies favoring ownership and contractors prioritizing operating lease arrangements with maintenance bundling.
- Mining Companies:Captive coal and mineral producers optimize fleet configurations for 15-year mine plans with integrated maintenance capabilities. Glencore's Australian coal operations maintain in-house rebuild facilities for cutting unit overhaul cycles.
- Contractors:Mining services firms demand equipment flexibility with rapid deployment and return provisions. Indian contract miners in the Singareni coalfields source machines through rental arrangements that transfer obsolescence risk to lessors.
- Government Agencies:State-owned mining enterprises in China and India procure through centralized tender processes with domestic content requirements. Coal India Limited's equipment standardization programs constrain vendor selection to approved manufacturer lists.
- Research Institutions:Universities and national laboratories operate pilot-scale continuous miners for cutting mechanics research and automation development. CSIRO's Brisbane facility maintains test units for Australian coal industry collaborative research programs.
Mining Companies represent the largest procurement segment; contractors expand most quickly as asset-light operating models penetrate emerging mining jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Australia's Bowen Basin exceeds that of Appalachian operators by roughly 15-20% due to higher seam productivity and integrated export infrastructure. This asymmetry shapes equipment procurement cycles and technology adoption timelines across both markets.
Australia
Queensland's longwall development drives demand for higher-capacity electric cutting units with integrated bolting platforms. The country's EPA enforces diesel particulate limits that accelerate fleet electrification timelines. Bowen Basin operators deploy teleoperation centers in Mackay and Rockhampton to manage dispersed cutting faces remotely.
United States
Appalachian room-and-pillar operations require continuous miners for thin-seam deposits where longwall economics fail. MSHA mandates proximity detection systems under 30 CFR 75.1732 for all tramming equipment. West Virginia and Kentucky coal counties face the steepest compliance costs due to confined heading geometries and legacy fleet density.
China
State-owned mining enterprises procure through centralized tender processes with domestic content requirements under MIIT guidelines. The country's dual carbon goals force underground electrification despite abundant thermal coal reserves. Shanxi and Shaanxi provinces concentrate manufacturing capacity for cutting tool components and electric drive systems.
South Africa
Platinum belt operators deploy narrow-vein continuous miners where labor-intensive methods face productivity constraints. The country's mining regulator enforces noise exposure and respirable dust standards that shape machine enclosure designs. Rustenburg and Limpopo mining clusters sustain demand for specialized shaft-sinking and development equipment.
India
Singareni coalfield contract miners source machines through rental arrangements that transfer obsolescence risk to lessors. The CEA mandates electrical safety standards for underground equipment that complicate import procurement. Telangana and Jharkhand states concentrate underground development where Coal India Limited standardization programs constrain vendor selection.
Continuous Miners Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cutting tools, conveyor chains, and hydraulic subsystems. The vendor base organizes around three strategic archetypes: diversified mining equipment conglomerates with global service networks, regional fabricators serving captive coal operations, and narrow-vein specialists for hard-rock applications. Consolidation pressure runs highest among mid-tier hydraulic component suppliers as electrification eliminates legacy powertrain demand. Geographic expansion and technology licensing represent the dominant competitive moves as electric drive platforms require new certification pathways in each jurisdiction.
Among diversified equipment conglomerates, Caterpillar Inc. and Komatsu Ltd. occupy positions anchored by integrated power and cutting technology platforms. Sandvik AB exemplifies the narrow-vein specialization archetype for applications where standard units underperform. Eickhoff Bergbautechnik GmbH represents the regional fabrication tier with engineering proximity to European coal and potash operations.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Sandvik AB |
| Eickhoff Bergbautechnik GmbH |
| Epiroc AB |
| FAMUR S.A. |
| Atlas Copco AB |
| Joy Global Inc. |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Australian cutting tool rebuild facilities is compressing supplier lead times and amplifying configured-to-order premiums for Queensland's Bowen Basin operators. This utilization squeeze tightens vendor pricing discipline while forcing buyers into longer-term service contracts that bundle spare parts with technical labor.
Pricing Analysis
Configured-to-order pricing for integrated bolting platforms commands spreads of 25-35% above standard cutting unit configurations. Three-tier pricing structure across premium, standard, and economy levels segments by automation grade and proximity detection integration. Cost compression in economy-tier electric drive systems is intensifying because Chinese motor suppliers are expanding export capacity. Contract miners in India's Singareni coalfields exhibit highest price sensitivity due to rental-model procurement, while captive Australian operators prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Tungsten carbide feedstock smelting concentrates in China's Hunan and Jiangxi provinces, with secondary processing anchored in Germany's Ruhr industrial cluster. Cutting tool manufacturing draws from cobalt concentrates sourced from the DRC and recycled hard scrap from European machine shops. Single-source vulnerability runs through Chinese export license administration for strategic mineral powders. Distribution runs through OEM captive service networks in Australia and North America, with third-party parts distributors gaining share in South Africa's Highveld coalfields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian longwall operators as fleet standardization programs reduce vendor count across Queensland's Bowen Basin. This consolidation shifts negotiation leverage toward multi-unit procurement with embedded service commitments.
For Market Incumbents: Entrench aftermarket revenue streams by capturing rebuild cycles through predictive maintenance subscriptions. Komatsu Ltd. and Caterpillar Inc. should deepen backward integration into cutting tool supply to offset Chinese export control exposure. Electrification certification investments in MSHA and EPA jurisdictions will defend position against regional fabricators lacking compliance infrastructure.
For New Entrants and Emerging Players: India's infrastructure tunneling sector remains underpenetrated by teleoperation specialists, with Mumbai Metro and Bangalore subway expansions creating white-space demand. Southeast Asian urban rail projects in Vietnam and Indonesia offer comparable entry points. A rental-first go-to-market model with maintenance bundling aligns with contract miner procurement preferences in emerging jurisdictions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electric drive platforms as battery pack costs compress and motor manufacturing scales. Acquisition targets should display narrow-vein engineering capabilities for platinum and potash applications, where standard units underperform. The signal to watch is MSHA enforcement velocity on proximity detection retrofits, which will determine aftermarket service contract attach rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Teleoperation Infrastructure Deployment | Fiber-linked control centers in Mackay and Rockhampton eliminate operator exposure in gassy Queensland seams. |
| Cutting Tool Supply Integration | Backward integration into tungsten carbide pick manufacturing reduces Chinese export license vulnerability. |
| Electric Drive Platform Certification | MSHA and EPA compliance investments defend margin position against non-compliant regional fabricators. |
| Condition Monitoring Convergence | Vibration sensing and predictive analytics enable uptime-based service contracting distinct from equipment sales. |
| Infrastructure Tunneling Expansion | Urban subway projects in India and Southeast Asia diversify revenue beyond captive coal operations. |
Methodological Framework
A spread of perspectives from mine maintenance directors, OEM procurement teams, aftermarket service heads, and underground safety regulators converged on the working assumptions driving this analysis. Primary fieldwork with Australian longwall operators and Appalachian room-and-pillar engineers combined with secondary validation through MSHA enforcement records, EPA emissions compliance databases, and customs trade data for cutting tool imports. Bottom-up equipment shipment tallies and top-down mining capital expenditure surveys triangulated on segment-level demand estimates.
Demand-supply balance modeling across the projection horizon incorporated electric drive adoption curves, diesel-hydraulic retirement schedules, and ventilation infrastructure retrofit timelines. Segmentation dimensions included machine type, application method, technology platform, and end-user procurement structure. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Industry-specific inputs captured proximity detection mandate enforcement velocity and teleoperation fiber deployment rates in Australian coal regions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese electric drive suppliers or accelerated MSHA rulemaking would shift outcomes beyond modeled ranges. Cross-checking against mining equipment capex disclosures and regional coal production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Smart Mining Market
Mining Equipment
Logging Cable Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Rock Duster Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
DTH Drill Rig Market