
 Mechanical Mine Clearance System Market | 2026-2036
Mechanical Mine Clearance System Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Mine Clearance System Market Outlook
Humanitarian assistance agencies is rotating procurement priority away from legacy military surplus toward purpose-built commercial systems. DOK-ING leverages its Croatian manufacturing base to dominate European tender pipelines. Rheinmetall AG anchors German defense exports through integrated flail-and-plow platforms. Pearson Engineering specializes in armored earth-moving attachments that extend NATO vehicle lifecycles.
A mechanical mine clearance system encompasses flail, tiller, and plow platforms engineered to detonate or excavate buried explosive ordnance through mechanical agitation, typically operating at depths of 20-30 centimeters with armored hull protection against blast overpressure. These systems serve military route clearance, humanitarian land release, and post-conflict infrastructure rehabilitation by rendering hazardous ground passable for civilian resettlement and construction activity. Tracked vehicles occupy the largest installed base due to superior ground pressure distribution across uneven terrain, while autonomous systems represent the fastest-expanding technology category as operators seek to remove human exposure from blast zones. Wheeled robots concentrate margin pools in urban remediation contracts where maneuverability outweighs soil penetration depth.
The US Department of State's Office of Weapons Removal and Abatement shapes procurement standards through its Quality Assurance Program for demining equipment, while the EU's Common Security and Defence Policy frameworks coordinate multinational humanitarian fleet purchases. ISO 9001 and NATO STANAG 4569 certifications function as de facto market access requirements for systems entering Western-funded clearance programs. Stakeholders must monitor how emerging national stockpile destruction mandates in former conflict states redirect contractor spending from detection-only contracts toward full mechanical neutralization services.
Market Dynamics
Autonomous platform integration is compressing procurement cycles across humanitarian and military clearance programs, forcing incumbent manufacturers to reengineer armored hull architectures around remote-operated turret systems rather than protected crew compartments.
Growth Catalysts
- EU Anti-Personnel Mine Ban Convention compliance protocols:Fleet modernization mandates in Croatia, Bosnia-Herzegovina, and Cyprus are accelerating replacement of manual demining teams with mechanical systems.
- Southeast Asian border clearance corridors:Vietnam, Cambodia, and Laos are channeling development aid into mechanized land release programs along former conflict zones.
- Autonomous tiller platforms:Machine-vision-guided soil agitation systems are reducing operator exposure while maintaining clearance depth consistency across variable terrain.
Market Restraints
- High-grade armor steel input costs:Blast-resistant hull fabrication depends on specialized alloy supply concentrated in Ukrainian and Russian metallurgical facilities.
- ISO 9001 and NATO STANAG 4569 certification timelines:Western-funded clearance programs require multi-year validation protocols that freeze out emerging suppliers.
- Manual demining labor substitution:Low-cost human clearance teams remain competitive in donor-fatigued humanitarian contexts with limited mechanization budgets.
Strategic Opportunities
- Urban remediation contracts:Wheeled robotic platforms with reduced ground pressure are penetrating post-conflict infrastructure rehabilitation in Mosul, Raqqa, and Mariupol.
- US Department of State Quality Assurance Program:Equipment standardization creates first-mover advantage for certified systems entering State Department-funded clearance pipelines.
- Sensor-flail convergence:Integration of ground-penetrating radar with mechanical agitation heads enables real-time threat confirmation before soil engagement.
Industry Challenges
- Blast trauma engineering talent scarcity:Specialized armor design expertise resides with a shrinking cohort of Cold War-era defense contractors in Germany, the UK, and the US.
- Legacy vehicle integration complexity:NATO surplus chassis retrofits require extensive hull reinforcement that extends deployment timelines and voids original manufacturer warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Mine Clearance System Market |
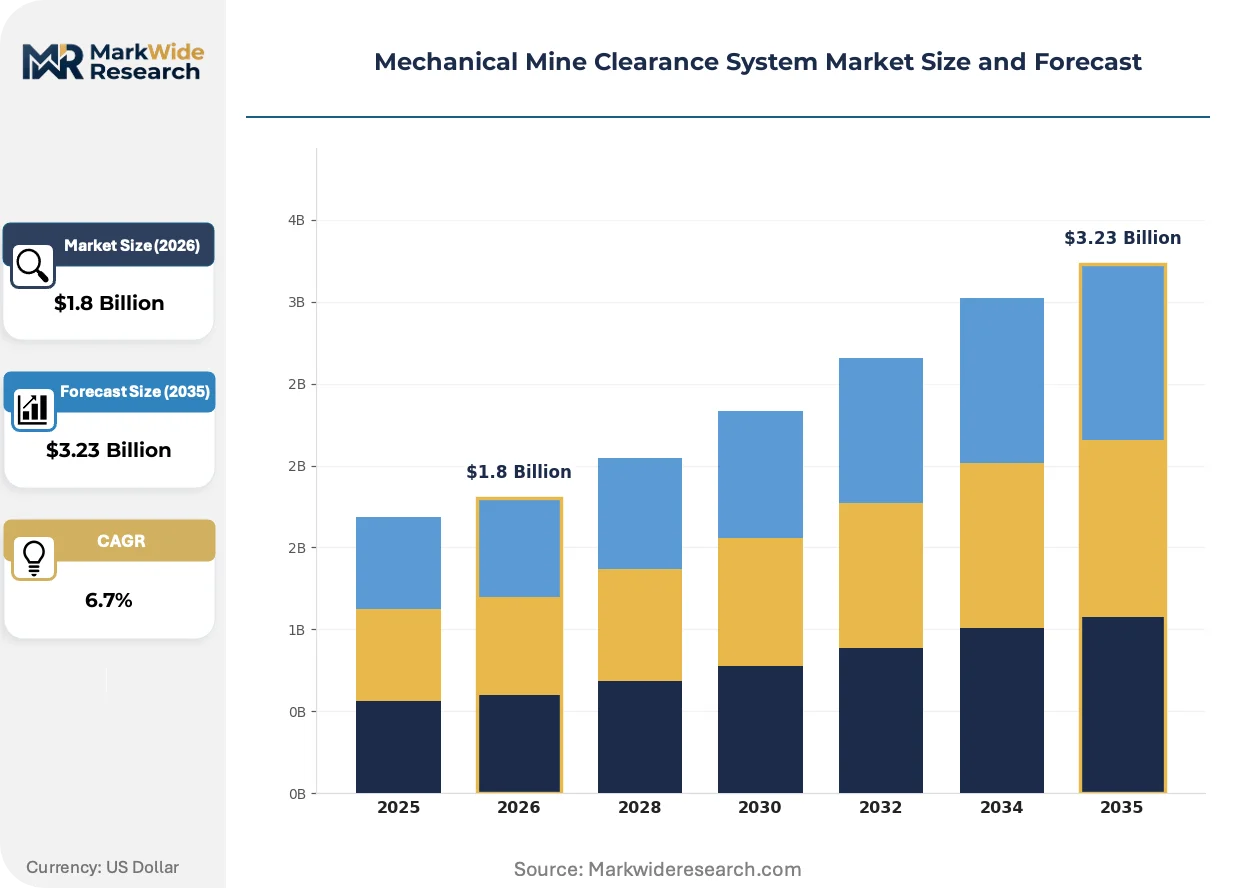
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracked Vehicles, Wheeled Robots, Demining Plows, Explosive Carrying Systems Technology: Remote Operated, Autonomous Systems, Hybrid Technology, Manual Control Application: Military Operations, Humanitarian Assistance, Infrastructure Development, Environmental Remediation End User: Government Agencies, Non-Governmental Organizations, Private Contractors, Defense Forces |
| Companies Covered | Pearson Engineering, DOK-ING, Rheinmetall AG, Armtrac Limited, Hydrema Holding ApS, MineWolf Systems AG, FAE Group, Komatsu Limited, Mahindra Defence Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Mine Clearance System Market Strategic Shifts
Electrification of drivetrains and payload systems is redefining platform endurance metrics, while machine perception advances are collapsing the sensor-to-actuator loop in contested terrain. These shifts are compressing the capability gap between military route clearance and humanitarian demining specifications.
Ground-penetrating radar arrays fused with electromagnetic induction sensors are miniaturizing into flail-mounted pods that provide real-time metallic anomaly classification before mechanical engagement. Humanitarian agencies in Afghanistan and Ukraine are field-testing these integrated heads to reduce false-positive detonations that degrade tiller blade life. The technology is miniaturizing clearance cost structures by eliminating redundant detection passes and reducing spare parts consumption in extended operations.
REACH substance restrictions on hexavalent chromium plating are forcing armor component suppliers to transition toward trivalent alternatives or ceramic-composite surface treatments. German and French defense procurement offices are incorporating these material compliance requirements into technical specifications for new fleet acquisitions. NATO STANAG 4569 test protocols are being revised to validate blast performance of non-chromate hull configurations without degrading spall protection.
Service unbundling is separating equipment ownership from operational risk in donor-funded programs. Contractors in Cambodia and Angola are migrating toward leased-platform models where manufacturers retain residual value and maintenance liability. This restructuring concentrates capital requirements with OEM balance sheets while transferring operational expertise to field service organizations rather than national demining agencies.
Mechanical Mine Clearance System Market Segmentation
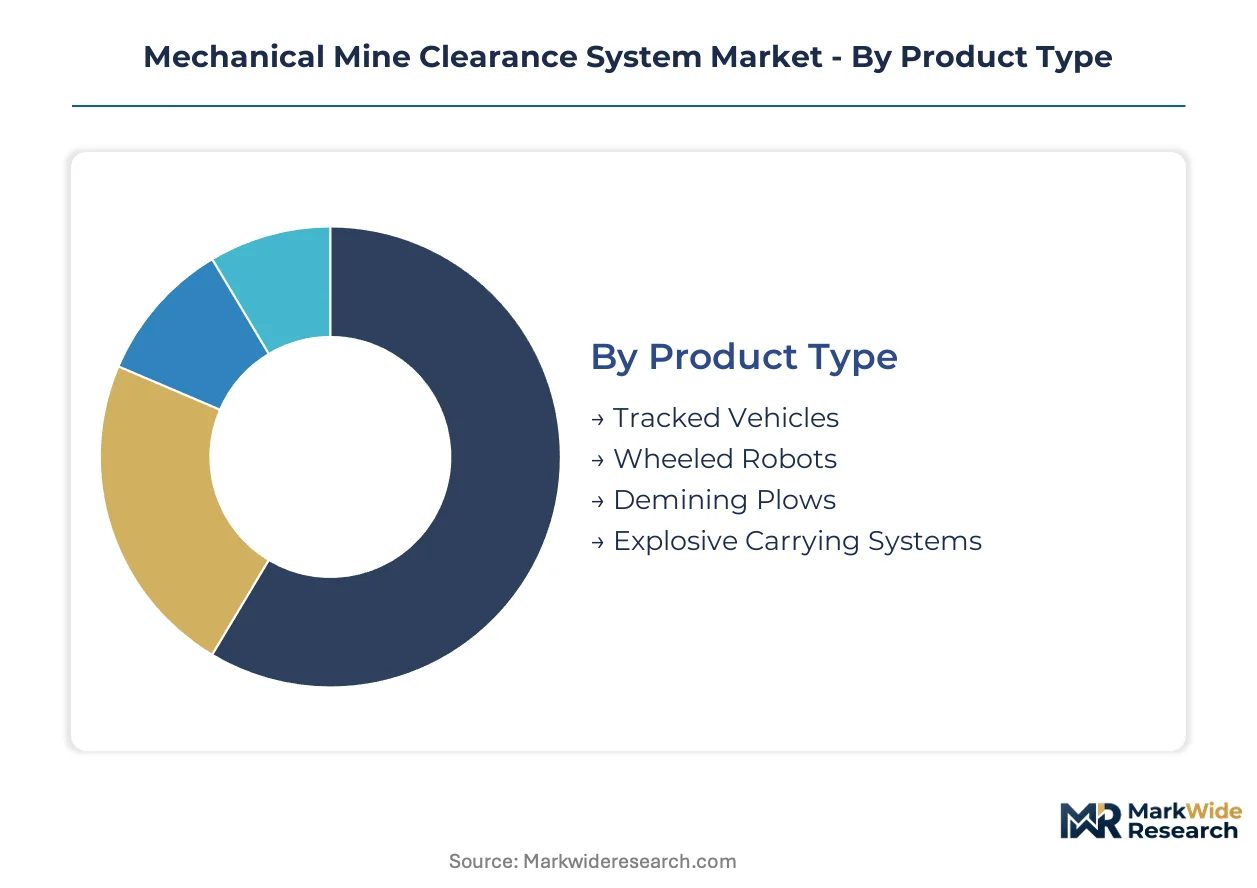
Segmentation reveals how procurement priorities diverge between military route clearance and humanitarian land release programs. Technology choices and platform configurations carry vastly different risk profiles across these use cases, reshaping vendor positioning and certification requirements.
Product Type:
Tracked vehicles face mounting substitution pressure from wheeled platforms in urban contracts, while explosive carrying systems confront regulatory headwinds from evolving blast safety protocols.
- Tracked Vehicles:Armored hulls with distributed ground pressure dominate uneven terrain clearance in Southeast Asian border corridors. NATO surplus chassis retrofits and purpose-built Croatian manufacturing supply most procurement pipelines, though hull reinforcement complexity extends deployment timelines.
- Wheeled Robots:Reduced ground pressure configurations penetrate post-conflict infrastructure rehabilitation in Mosul, Raqqa, and Mariupol where maneuverability outweighs soil penetration depth. REACH substance restrictions on hexavalent chromium plating are forcing armor suppliers toward trivalent alternatives.
- Demining Plows:Soil excavation attachments extend NATO vehicle lifecycles through armored earth-moving integration.
- Explosive Carrying Systems:Blast-resistant payload platforms face tightening EU safety mandates under revised Anti-Personnel Mine Ban Convention protocols.
Tracked vehicles retain volume leadership; wheeled robots hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium autonomous platforms from budget manual systems, with hybrid configurations capturing mid-tier humanitarian contracts.
- Remote Operated:Turret-based control architectures are displacing protected crew compartments as manufacturers reengineer armored hulls around off-board operator stations. US Department of State Quality Assurance Program certification creates first-mover advantage for standardized systems.
- Autonomous Systems:Machine-vision-guided soil agitation reduces operator exposure while maintaining clearance depth consistency across variable terrain. Humanitarian agencies in Afghanistan and Ukraine are field-testing integrated ground-penetrating radar heads to reduce false-positive detonations.
- Hybrid Technology:Dual-mode operation bridges military and humanitarian specification gaps through selectable autonomy levels.
- Manual Control:Low-cost operator-dependent platforms remain competitive in donor-fatigued contexts with limited mechanization budgets.
Remote operated systems anchor current procurement; autonomous platforms are gaining share fastest.
Application:
Application mix determines margin structure, with military operations commanding premium pricing and humanitarian assistance driving volume through donor-funded fleet programs.
- Military Operations:Route clearance specifications demand NATO STANAG 4569 blast protection and integrated flail-and-plow payload versatility. German defense exports anchor this segment through integrated platform offerings.
- Humanitarian Assistance:Land release programs in Cambodia, Angola, and Laos are migrating toward leased-platform models where manufacturers retain residual value. Service unbundling concentrates capital requirements with OEM balance sheets.
- Infrastructure Development:Post-conflict construction preparation requires passable ground certification for civilian resettlement activity.
- Environmental Remediation:Contaminated site restoration applies mechanical clearance to industrial explosive ordnance disposal.
Military operations retain pricing power; humanitarian assistance delivers the steepest unit volume trajectory.
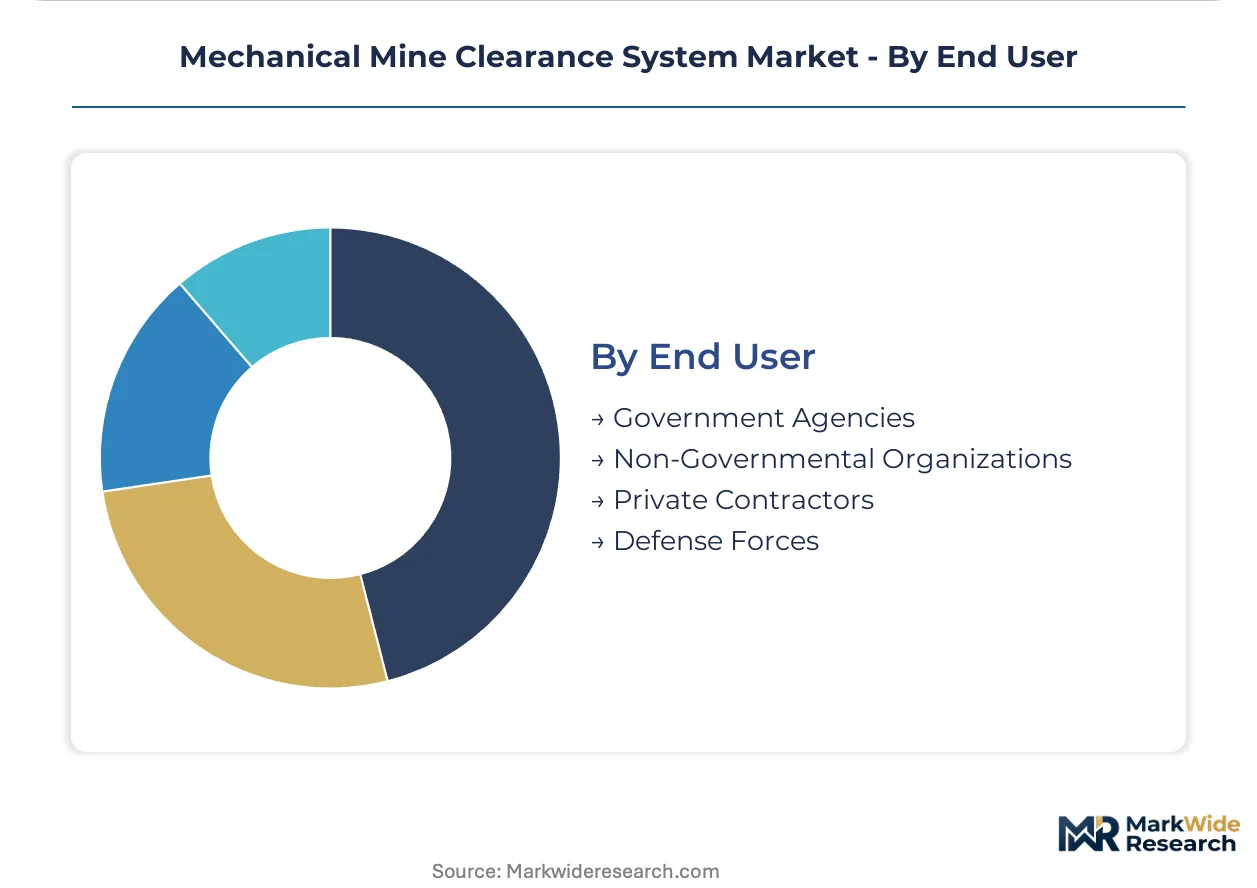
End User:
Customer type shapes procurement modality, with government agencies favoring ownership models and private contractors adopting operational risk transfer structures.
- Government Agencies:National demining authorities in Croatia, Bosnia-Herzegovina, and Cyprus are accelerating fleet modernization under EU compliance mandates. ISO 9001 certification functions as de facto market access requirement.
- Non-Governmental Organizations:Humanitarian agencies rotate procurement priority away from legacy military surplus toward purpose-built commercial systems with standardized maintenance protocols.
- Private Contractors:Field service organizations absorb operational expertise as national agencies outsource platform deployment and maintenance liability.
- Defense Forces:Military procurement offices specify integrated detection-neutralization capabilities through sensor-flail convergence requirements.
Government agencies dominate current installed base; private contractors are expanding most quickly through service restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sino-Vietnamese border rail corridor underwrites Southeast Asia's concentration of demining demand, connecting clearance contracts to infrastructure rehabilitation timelines across former conflict zones.
Croatia
EU Anti-Personnel Mine Ban Convention compliance deadlines are accelerating fleet replacement in border counties. The country's national demining regulator coordinates tender specifications with Brussels funding protocols. Zagreb-based manufacturing clusters supply armored hull components to Bosnian and Cypriot modernization programs.
Vietnam
Development aid from bilateral donors is channeling into mechanized land release along the Cambodian and Laotian frontiers. The Ministry of National Defense issues technical standards that align with ISO certification requirements. Da Nang port clearance operations are integrating autonomous platforms for harbor rehabilitation contracts.
Germany
Defense export financing supports integrated flail-and-plow platform sales to NATO partner nations. The KBA and federal procurement offices enforce STANAG 4569 validation for hull blast protection. Rheinmetall's engineering base in Düsseldorf anchors Continental European supply chains for armored earth-moving attachments.
United States
The Department of State's Office of Weapons Removal and Abatement shapes global procurement standards through its Quality Assurance Program. OSHA and federal acquisition regulations govern contractor safety protocols for domestic training facilities. Texan defense contractors near Fort Hood are retrofitting surplus chassis for humanitarian lease programs.
Afghanistan
Humanitarian agencies are field-testing machine-vision-guided tillers to reduce operator exposure in high-threat corridors. The country's national mine action authority coordinates with UN Development Programme funding mechanisms. Kabul periphery clearance zones are concentrating leased-platform deployments from regional OEM service organizations.
Mechanical Mine Clearance System Market Competitive Environment
Listed leaders compete with private specialists across certification access, where public equity financing enables faster ISO 9001 and NATO STANAG validation cycles than family-held counterparts can sustain. The vendor base concentrates around three strategic archetypes: integrated defense conglomerates with captive metallurgical supply, specialized demining equipment pure-plays with field service expertise, and diversified industrial manufacturers leveraging construction equipment distribution networks. Consolidation pressure is accelerating through cross-border M&A and strategic partnerships that transfer operational risk from national agencies to OEM balance sheets.
Among European defense-industrial anchors, Rheinmetall AG and DOK-ING occupy positions that exemplify the divergence between scale-driven platform integration and agile specialist manufacturing. Pearson Engineering represents the attachment-system archetype that extends vehicle lifecycles without requiring full platform ownership. These three entities collectively illustrate how geographic clustering—German industrial engineering, Croatian manufacturing cost structures, and British armor design heritage—shapes competitive positioning across tender pipelines.
| Leading Market Players |
|---|
| Pearson Engineering |
| DOK-ING |
| Rheinmetall AG |
| Armtrac Limited |
| Hydrema Holding ApS |
| MineWolf Systems AG |
| FAE Group |
| Komatsu Limited |
| Mahindra Defence Systems |
| Others |
Value Chain & Pricing Dynamics
NATO STANAG 4569 certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where certified hull fabricators command premium positioning while uncertified suppliers compete on cost in donor-fatigued procurement contexts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Premium tiers attach field service organizations and spare parts guarantees that extend platform lifecycle economics. Price erosion runs through economy tiers as Ukrainian and Russian metallurgical supply disruptions compress margins on blast-resistant alloy inputs. Humanitarian agencies exhibit highest price sensitivity, while defense procurement offices prioritize performance specifications over unit cost.
Supply Chain Analysis
Germany and Croatia anchor armored hull fabrication and integrated platform assembly for European tender pipelines. Specialized alloy supply draws from Ukrainian and Russian metallurgical facilities, creating single-source vulnerability for high-grade armor steel inputs. REACH substance restrictions on hexavalent chromium plating are forcing component suppliers toward trivalent alternatives or ceramic-composite surface treatments. Distribution runs through OEM field service organizations rather than national demining agency ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling transforms hardware vendors into recurring-revenue platforms, with leased-platform models and maintenance liability transfers expanding faster than equipment sales in donor-funded humanitarian programs.
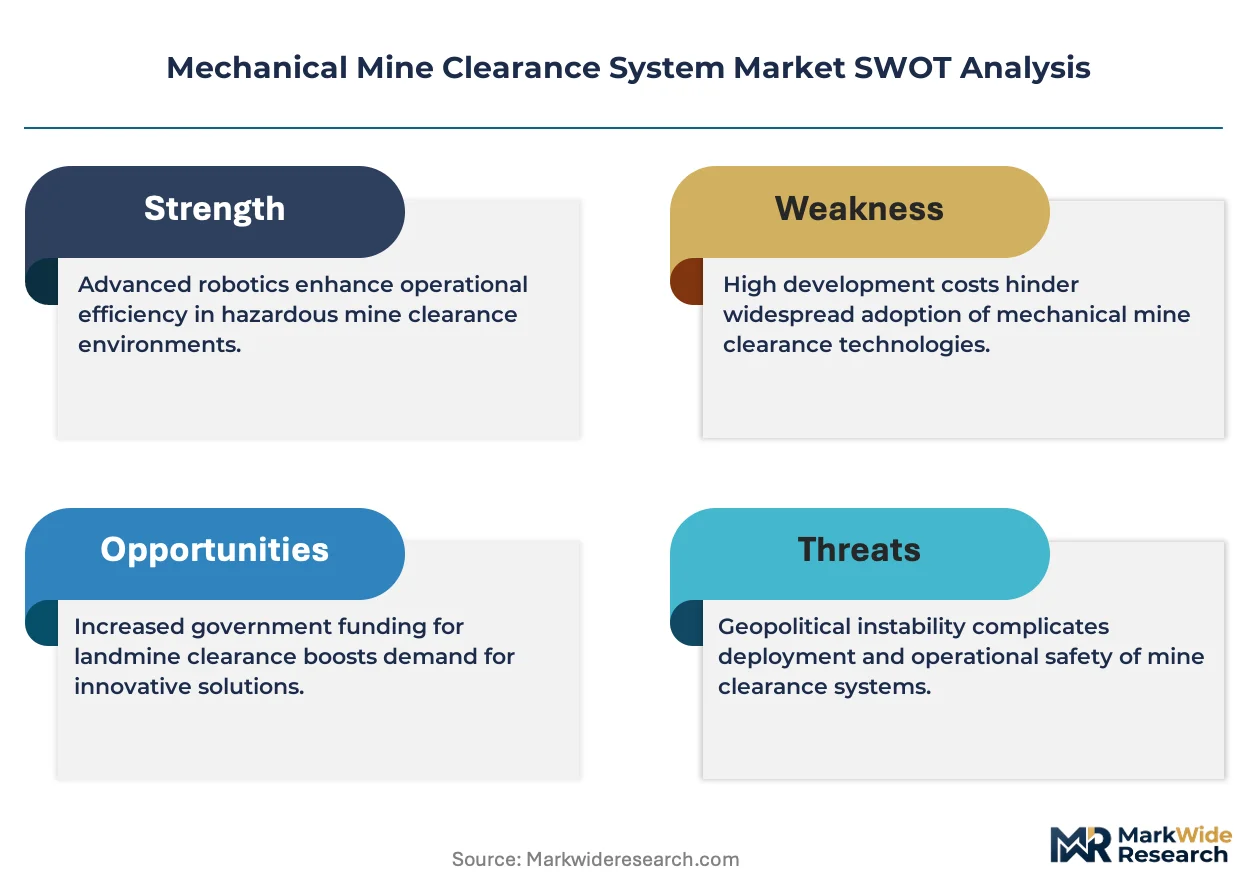
For Market Incumbents: Compound defensive positioning through backward integration into specialized alloy supply chains and captive certification consulting services. Autonomous platform entrants threaten route clearance incumbents with compressed deployment timelines; counter through sensor-flail convergence R&D and exclusive field service organization partnerships in Southeast Asian border corridors. For New Entrants and Emerging Players: Lead with wheeled robotic platforms in urban remediation contracts where maneuverability premiums outweigh soil penetration specifications. Post-conflict infrastructure rehabilitation in Mosul, Raqqa, and Mariupol represents the most penetrable application segment; establish go-to-market presence through OEM service organization subcontracts rather than direct government tender competition. For Investors and Strategic Acquirers: EU Anti-Personnel Mine Ban Convention compliance deadlines reshape the acquisition landscape toward certified platform specialists with established tender pipeline access. Long-term viability centers on service-attach revenue durability rather than hardware shipment cyclicality. Target field service organizations with captive operational expertise in leased-platform deployments; monitor national stockpile destruction mandate announcements as inflection indicators for contractor spending redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Flail Convergence Development | Ground-penetrating radar integration with mechanical agitation heads reduces false-positive detonations in Afghanistan and Ukraine field tests. |
| Leased-Platform Service Model | Residual value retention and maintenance liability transfer concentrate capital requirements with OEM balance sheets in Cambodia and Angola. |
| Autonomous Platform Certification | Machine-vision-guided tiller systems gain US Department of State Quality Assurance Program validation for humanitarian deployment pipelines. |
| Non-Chromate Armor Surface Treatment | Ceramic-composite alternatives to hexavalent chromium plating satisfy REACH restrictions while maintaining NATO STANAG 4569 blast protection. |
| Regional Field Service Expansion | Operational expertise absorption by private contractors accelerates platform deployment in Southeast Asian border clearance corridors. |
Study Parameters
A standing panel of demining equipment procurement officers, armored hull engineering specialists, humanitarian program directors, and OEM field service managers provided ongoing calibration across primary interview cycles and secondary validation. NATO STANAG certification databases, EU Anti-Personnel Mine Ban Convention compliance filings, US Department of State Quality Assurance Program equipment registries, and customs trade records furnished bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology tier, application use case, and end-user procurement modality dimensions. CAGRs derived from unit shipment trajectories and average selling price evolution, with alloy input cost indices and certification timeline assumptions feeding scenario sensitivity analysis.
Forecasts assume regulatory continuity in EU Anti-Personnel Mine Ban Convention protocols and NATO STANAG validation regimes; material policy shifts would require re-modeling. Specific risks include donor fatigue compressing humanitarian mechanization budgets, blast trauma engineering talent scarcity extending platform development cycles, and legacy vehicle integration complexity voiding manufacturer warranties. Recalibration cycles align with material shifts in national stockpile destruction mandates and autonomous platform field-testing outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Smart Mining Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Mining Equipment Parts and Attachments Market