
 Conveyor Sprocket Market | 2026-2036
Conveyor Sprocket Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Sprocket Market Outlook
Buyer concentration among e-commerce fulfillment centers and automated distribution warehouses is realigning procurement patterns across the conveyor sprocket supply base. Rexnord Industries LLC leverages its integrated manufacturing footprint to serve bulk material handlers with standardized large-pitch sprocket lines. Martin Sprocket & Gear, Inc. anchors its position through extensive distributor channel control across North American industrial corridors. Tsubaki Group competes on heat-treated precision tooth profiles for high-cycle automotive assembly applications.
A conveyor sprocket is a toothed mechanical wheel that meshes with conveyor chain links to transmit rotary motion into linear belt or chain movement, typically manufactured from medium-carbon or alloy steel through hobbing, shaping, or CNC machining followed by induction hardening to achieve tooth surface hardness of 50-60 HRC. Chain sprockets occupy the largest volume share due to universal deployment in heavy manufacturing and mining conveyors. Steel material grades dominate margin pools where thermal processing and alloy specification differentiate supplier performance. Specialty sprockets represent the fastest-growing category as food-grade stainless and corrosion-resistant coatings expand into pharmaceutical and chemical processing lines.
ISO 606 and ANSI B29.1 chain standards govern tooth geometry and pitch tolerances that determine interchangeability and load ratings across international supply chains. OSHA machinery guarding regulations in the United States and CE machinery directives in Europe mandate physical enclosure and emergency stop integration for exposed sprocket drives, elevating demand for compact hub designs that fit within safety housings. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal and emerging state-level industrial emissions frameworks that could reshape material sourcing and thermal processing economics for forged and machined sprocket producers.
Market Dynamics
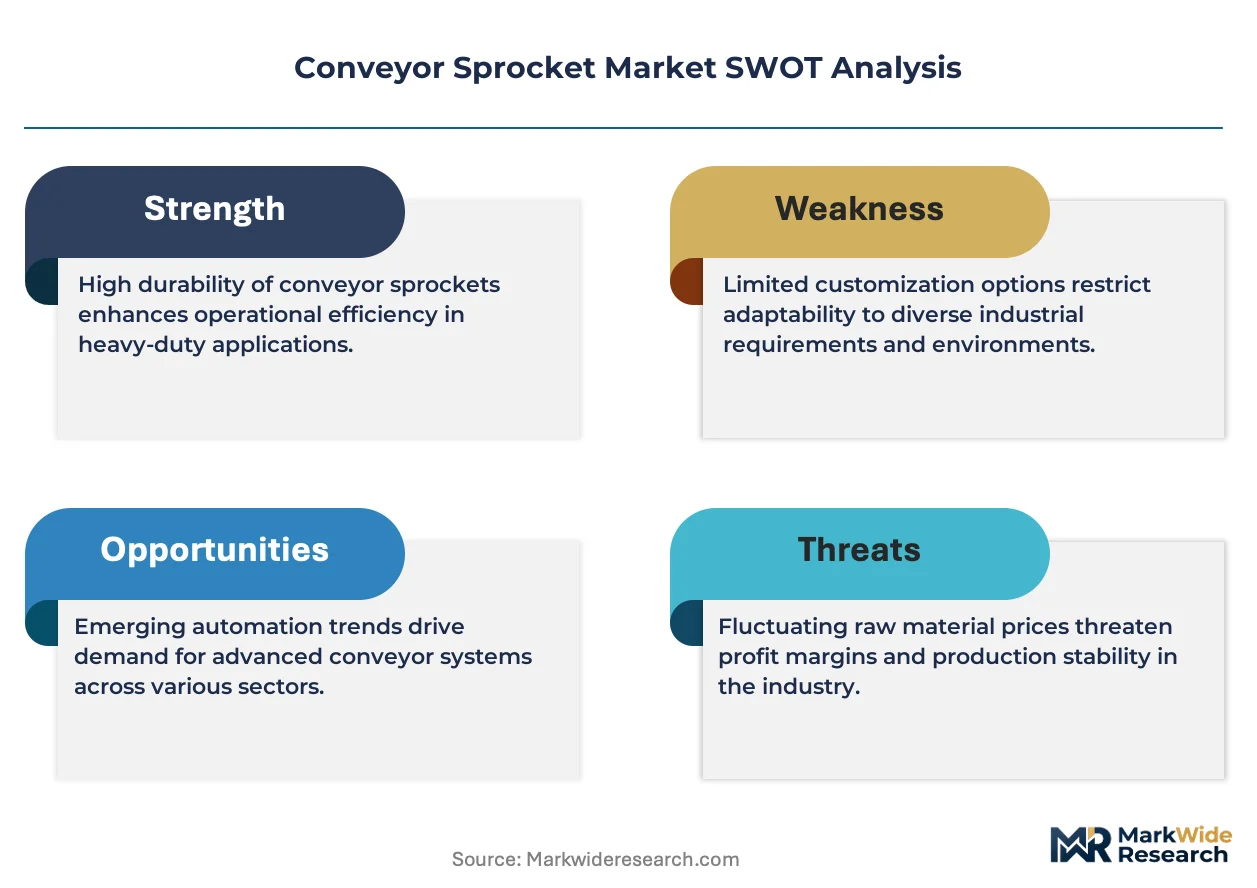
Heat treatment advances and precision CNC machining capabilities are compressing supplier differentiation around tooth hardness and wear resistance, forcing mid-tier manufacturers to consolidate or specialize in niche alloy formulations.
Growth Catalysts
- Port Automation Infrastructure:China's ongoing bulk logistics investment drives heavy-duty sprocket procurement for automated material handling systems at coastal terminals.
- OSHA Machinery Guarding Mandates:Physical enclosure requirements for exposed drives elevate demand for compact hub designs that integrate within safety housings across US manufacturing facilities.
- Induction Hardening Process Refinement:Advances in thermal processing enable consistent 50-60 HRC tooth surface hardness, extending service intervals in mining and aggregate operations.
Market Restraints
- Alloy Steel Input Volatility:Medium-carbon and specialty steel price fluctuations compress margin pools for forged sprocket producers dependent on spot market sourcing.
- Supplier Concentration in East Asia:Heat treatment capacity and precision machining equipment cluster in Chinese industrial corridors, creating geographic supply risk for Western buyers.
- Chain-Belt Substitution:Modular plastic conveyor systems displace metal chain drives in light-load food processing and packaging applications.
Strategic Opportunities
- Pharmaceutical Processing Lines:Food-grade stainless steel and corrosion-resistant coating specifications create premium positioning for specialty sprocket categories in drug manufacturing.
- EU Green Deal Carbon Accounting:Emerging industrial emissions frameworks reshape thermal processing economics, rewarding low-carbon heat treatment investments with regulatory preference.
- Automotive Assembly Integration:High-cycle precision tooth profiles converge with collaborative robotics in electric vehicle production lines, opening specification-driven procurement channels.
Industry Challenges
- CNC Programming Talent Scarcity:Precision tooth profile machining requires specialized operator skills that outpace vocational training pipeline output in mature manufacturing economies.
- ISO 606 Certification Timelines:Third-party validation of pitch tolerance and interchangeability standards extends product launch cycles for new sprocket geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Sprocket Market |
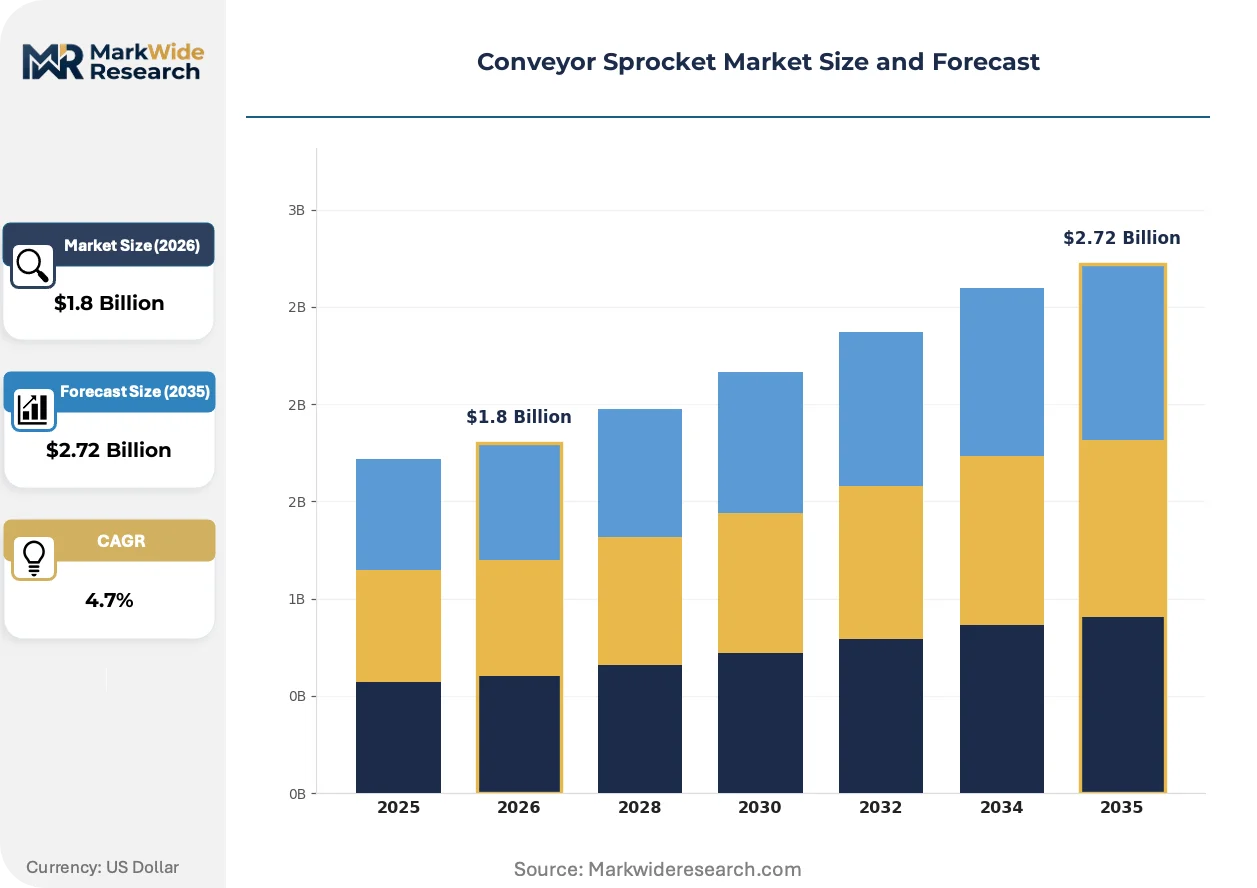
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Sprockets, Gear Sprockets, Timing Sprockets, Specialty Sprockets Material: Steel, Plastic, Aluminum, Composite End User: Manufacturing, Automotive, Food & Beverage, Packaging Size: Small, Medium, Large, Customized |
| Companies Covered | Diamond Chain Company, Rexnord Industries LLC, Suzhou Newball Conveyor Chain Manufacturing Co.,Ltd, DCC (Changzhou Dongchuan Chain Transmission Technology), Martin Sprocket & Gear, Inc., Tsubaki Group, Iwis Antriebssysteme GmbH & Co. KG, Peer Chain, Renold plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Sprocket Market Strategic Shifts
Digital manufacturing integration and regulatory emissions pressure are restructuring how conveyor sprockets are specified, produced, and procured across heavy industry verticals.
Corrosion-resistant coating technologies, including plasma-transferred arc welding and physical vapor deposition, are expanding into chemical processing and marine material handling environments. Petrochemical facilities and offshore bulk terminals adopt these surfaces to combat salt and caustic exposure. The technology is expanding into segments previously dominated by standard carbon steel, compressing the addressable market for unprotected sprocket grades.
REACH substance restrictions and evolving EU Green Deal carbon border adjustment mechanisms impose material traceability and thermal processing disclosure obligations on forged component suppliers. European OEMs now require documented alloy sourcing and heat treatment energy intensity data for CE machinery directive compliance. German and French conveyor system integrators lead this specification shift, pressuring upstream suppliers to invest in emissions monitoring infrastructure.
Buyer concentration among automated distribution warehouses consolidates procurement authority toward e-commerce fulfillment operators with standardized large-pitch requirements. Traditional distributor channel relationships fragment as direct specification authority migrates to facility engineering teams. This pattern concentrates most visibly in US Midwest logistics corridors and Chinese Yangtze River Delta port automation clusters.
Conveyor Sprocket Market Segmentation
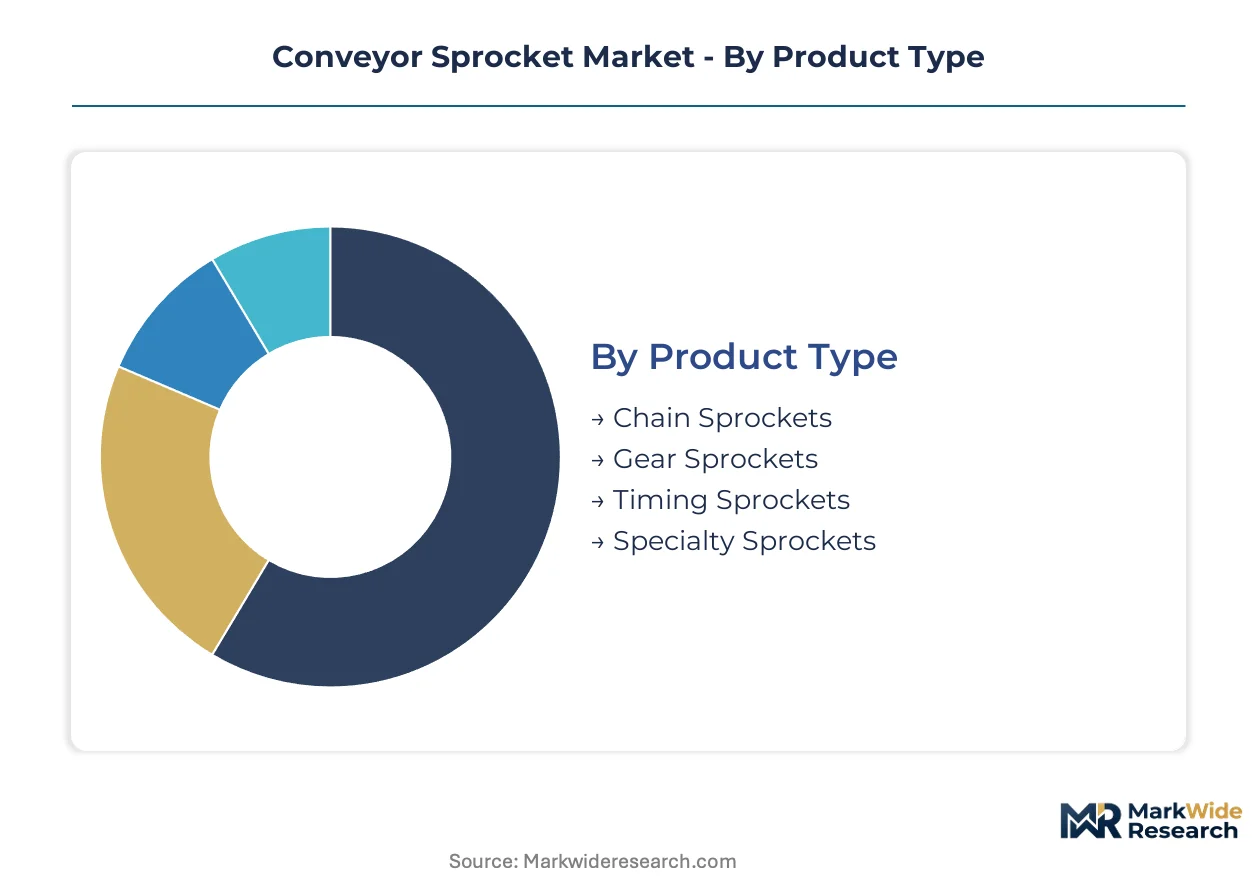
Conveyor sprocket procurement patterns diverge sharply across product categories, with certification requirements and thermal processing standards dictating supplier eligibility in regulated end-uses. Material selection and dimensional specifications further fragment addressable markets, creating distinct margin pools that reward specialized manufacturing capabilities.
Product Type:
ISO 606 and ANSI B29.1 compliance burdens fall heaviest on precision tooth profiles for high-cycle applications, while specialty grades face additional FDA or EU 1935/2004 food-contact mandates.
- Chain Sprockets:Hobbed or CNC-machined wheels with induction-hardened teeth meshing with roller chain in heavy manufacturing and mining conveyors. Demand concentrates in Chinese port automation terminals where bulk logistics infrastructure investment drives procurement of standardized large-pitch lines. OSHA machinery guarding regulations in US facilities elevate specification priority for compact hub designs integrating within safety housings.
- Specialty Sprockets:Stainless steel or corrosion-resistant coated wheels engineered for pharmaceutical cleanrooms, chemical processing, and marine environments. REACH substance restrictions and EU Green Deal carbon accounting reshape thermal processing economics for these premium grades, with German and French system integrators leading documented alloy sourcing requirements.
- Gear Sprockets:Precision-machined components transmitting motion through meshed gear teeth rather than chain engagement.
- Timing Sprockets:Synchronized drive wheels maintaining positional accuracy in automated assembly lines.
Leading the category by volume: Chain Sprockets. Growing fastest: Specialty Sprockets.
Material:
Cost tiers stratify around thermal processing intensity and alloy specification, with premium grades commanding 3-4x standard carbon steel pricing.
- Steel:Medium-carbon and alloy grades dominate margin pools where induction hardening to 50-60 HRC tooth surface hardness differentiates supplier performance. Mining and aggregate material handlers in China's Yangtze River Delta port clusters drive heavy-duty procurement, though alloy input volatility compresses margins for spot-market-dependent forgers.
- Plastic:Modular acetal or nylon sprockets displacing metal in light-load food processing and packaging applications where USDA sanitary design standards apply.
- Aluminum:Lightweight grades specified for portable conveyor systems and weight-sensitive automated guided vehicle integrations.
- Composite:Hybrid fiber-reinforced polymers emerging in corrosive chemical handling environments.
Highest volume segment: Steel. Steepest expansion trajectory: Plastic.
End User:
Application-specific duty cycles and contamination sensitivity reshape tooth geometry requirements and surface finish specifications.
- Manufacturing:General industrial material handling spans the widest pitch range, from precision small-pitch assembly lines to heavy-aggregate quarry operations.
- Automotive:High-cycle precision tooth profiles converge with collaborative robotics in electric vehicle production lines, opening specification-driven procurement channels where Tsubaki Group competes on heat-treated durability.
- Food & Beverage:FDA-compliant stainless steel and corrosion-resistant coatings mandatory for pharmaceutical processing line integration.
- Packaging:Modular plastic conveyor systems displace metal chain drives in light-load carton handling and sortation.
Dominant procurement volume: Manufacturing. Fastest specification evolution: Automotive.
Size:
Customer type fragmentation separates engineered-to-order mining components from standardized distributor-catalog items.
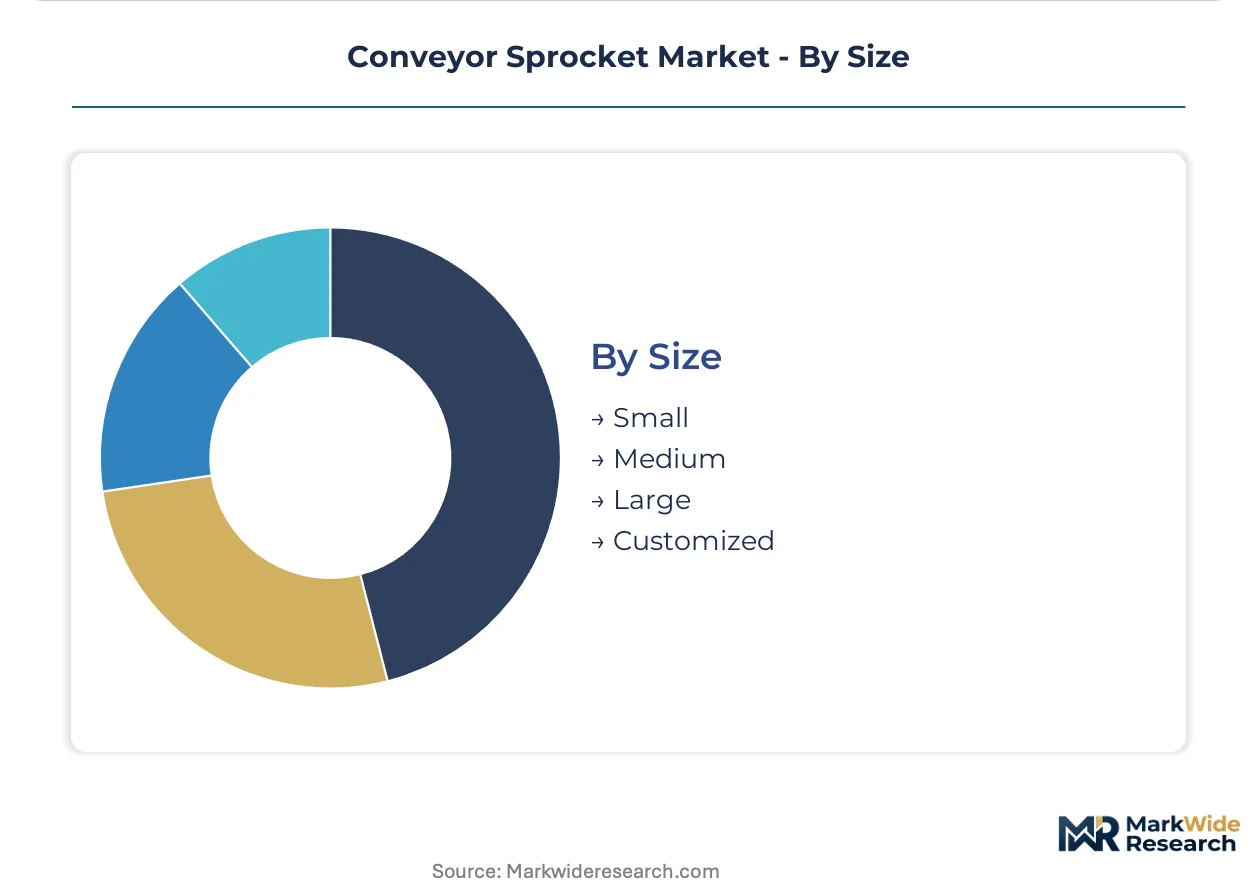
- Large:Custom-forged wheels with integral hub designs for bulk terminal and mining conveyor systems, procured direct by facility engineering teams bypassing traditional distribution.
- Medium:Standardized pitch lines moving through Rexnord Industries and Martin Sprocket distributor channels across North American industrial corridors.
- Small:Precision miniature sprockets for automated assembly and electronics manufacturing.
- Customized:Application-specific geometries requiring extended ISO 606 certification timelines and specialized CNC programming talent.
Volume concentration: Medium. Margin expansion: Customized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates bulk logistics infrastructure investment, while Germany and the United States anchor precision manufacturing demand for heat-treated conveyor sprocket systems.
China
Yangtze River Delta port automation terminals drive heavy-duty sprocket procurement for automated material handling systems. MIIT's dual carbon goals reshape thermal processing economics for forged component suppliers. Shanghai-Ningbo port clusters concentrate procurement authority among facility engineering teams bypassing traditional distribution channels.
Germany
Automotive assembly integration demands high-cycle precision tooth profiles for electric vehicle production lines. EU Green Deal carbon border adjustment mechanisms impose documented alloy sourcing requirements on forged component suppliers. Bavarian and North Rhine-Westphalian conveyor system integrators lead specification shifts toward emissions monitoring infrastructure.
United States
E-commerce fulfillment centers consolidate procurement authority toward automated distribution warehouses with standardized large-pitch requirements. OSHA machinery guarding regulations mandate physical enclosure and emergency stop integration for exposed sprocket drives. Midwest logistics corridors concentrate buyer concentration among facility engineering teams.
Japan
Precision tooth profile machining serves high-cycle automotive and electronics manufacturing applications. METI industrial standards govern material traceability for CE machinery directive compliance. Kanto and Kansai industrial clusters anchor demand for heat-treated durability in collaborative robotics integration.
India
Mining and aggregate material handling operations expand procurement of heavy-duty conveyor sprocket systems across domestic mineral processing corridors. BIS standards and PLI scheme incentives reshape supplier certification requirements for precision machined components. Gujarat and Maharashtra industrial corridors concentrate emerging distributor channel control for standardized pitch lines.
Conveyor Sprocket Market Competitive Environment
East Asian producers anchor one tier; European and North American specialists hold premium positioning through precision certification and distributor channel control. The vendor base stratifies across heat treatment capacity holders, precision machining specialists, and integrated manufacturing footprint operators. Three archetypes dominate: scale-driven bulk material handlers, precision-certified automotive suppliers, and distributor-channel-anchored regional players. Competitive moves concentrate on backward integration into alloy sourcing and geographic expansion through distributor network acquisition.
Among Japanese precision specialists, Tsubaki Group exemplifies the heat-treated durability archetype for high-cycle applications. German engineering-focused fabricators include Iwis Antriebssysteme GmbH & Co. KG, representing precision transmission system integration. Rexnord Industries LLC and Martin Sprocket & Gear, Inc. anchor North American positions through contrasting approaches—integrated manufacturing footprint versus extensive distributor channel control. Suzhou Newball Conveyor Chain Manufacturing Co.,Ltd and DCC (Changzhou Dongchuan Chain Transmission Technology) occupy positions within Chinese industrial corridors where heat treatment capacity clusters.
| Leading Market Players |
|---|
| Diamond Chain Company |
| Rexnord Industries LLC |
| Suzhou Newball Conveyor Chain Manufacturing Co.,Ltd |
| DCC (Changzhou Dongchuan Chain Transmission Technology) |
| Martin Sprocket & Gear, Inc. |
| Tsubaki Group |
| Iwis Antriebssysteme GmbH & Co. KG |
| Peer Chain |
| Renold plc |
| Others |
Value Chain & Pricing Dynamics
Induction hardening process refinement simultaneously compresses cost differentials among mid-tier suppliers and concentrates production capability in Chinese industrial corridors with thermal processing infrastructure. This technological shift rewards scale-driven operators while forcing smaller forgers toward specialty alloy niches or distributor channel dependency.
Pricing Analysis
Volume concentration in standardized large-pitch chain sprockets compresses margins through commodity-like spot-market dynamics, while specialty stainless and corrosion-resistant grades command premium positioning through FDA and EU 1935/2004 compliance burdens. Price differentiation hinges on certification tier and thermal processing intensity, with induction-hardened 50-60 HRC tooth surfaces separating premium suppliers from standard-grade competitors. Pricing pressure intensifies in carbon steel segments due to alloy input volatility and buyer consolidation among e-commerce fulfillment operators with standardized requirements. Maintenance directors at bulk material handling facilities exhibit highest price sensitivity, whereas pharmaceutical cleanroom engineers prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Alloy steel supply rests on Chinese blast furnace output, German specialty steel mills, and Japanese precision forging operations, with medium-carbon grades drawing from spot-market volatility and specialty alloys anchored in long-term offtake agreements. Critical inputs include induction hardening equipment, CNC machining centers, and corrosion-resistant coating systems. Single-source vulnerability concentrates in Yangtze River Delta heat treatment capacity, where MIIT dual carbon goals threaten thermal processing economics. Distribution runs through Rexnord's integrated manufacturing footprint and Martin Sprocket's North American distributor network, with direct procurement bypassing traditional channels in Chinese port automation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as heat treatment advances and precision CNC capabilities compress differentiation space for undifferentiated mid-tier manufacturers. Alloy input volatility and certification timeline burdens force weaker players toward acquisition or exit.
For Market Incumbents: Cement defensive positioning through backward integration into alloy sourcing and captive heat treatment capacity in Chinese industrial corridors. Prioritize ISO 606 certification pipeline acceleration to extend product launch cycles that new entrants cannot match. Channel control investments across Midwest logistics corridors and Yangtze River Delta port clusters defend against direct procurement migration to facility engineering teams.
For New Entrants and Emerging Players: Digital distributor platforms for standardized medium-pitch sprockets offer the most penetrable entry vector, bypassing Rexnord and Martin Sprocket's entrenched field sales organizations. Target pharmaceutical processing line specifications where corrosion-resistant coating expertise creates specification-driven procurement channels isolated from commodity pricing. Pursue white-label manufacturing partnerships with Chinese heat treatment operators to compress capital requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision-certified automotive suppliers with Tsubaki-like heat-treated durability positioning and documented METI material traceability compliance. Long-term viability favors operators with in-house thermal processing and CNC programming talent pipelines. Monitor EU Green Deal carbon border adjustment implementation as inflection signal for low-carbon heat treatment investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Captive supply of medium-carbon grades insulates margin pools from spot-market volatility. |
| Low-Carbon Heat Treatment Investment | EU Green Deal compliance positions suppliers for German and French system integrator preference. |
| Precision CNC Programming Talent Pipeline | Specialized operator skills defend tooth profile quality in high-cycle automotive applications. |
| Corrosion-Resistant Coating Certification | FDA-compliant surface technologies unlock pharmaceutical cleanroom procurement channels. |
| Distributor Network Geographic Expansion | Channel control in Midwest logistics corridors captures e-commerce fulfillment consolidation. |
Study Parameters
Multi-period observation of heat treatment capacity expansion, port automation procurement cycles, and distributor channel consolidation anchored the trend analysis, supplemented by interviews with plant engineers at bulk material handling facilities, procurement leads at automotive OEMs, aftermarket service heads at conveyor system integrators, and technical directors at precision machining operations. Secondary validation drew from MIIT industrial policy filings, OSHA machinery guarding enforcement data, EU ETS emissions disclosures, and SEC 10-K filings of listed component suppliers. Bottom-up volume aggregation across product type, material grade, and end-use segments triangulated against top-down market sizing from trade flow analysis.
Input-output matrix modeling connected alloy steel price indices, thermal processing energy costs, and certification timeline data to shipment volume projections across the analysis window. Segmentation dimensions included product type precision requirements, material thermal processing intensity, end-use duty cycle specifications, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement patterns and infrastructure investment pipelines, with automotive assembly integration rates and pharmaceutical processing line expansion serving as industry-specific demand drivers.
The model holds under stable alloy input cost assumptions and continued MIIT dual carbon policy implementation; deviation in EU carbon border adjustment timelines or sudden OSHA machinery guarding enforcement shifts would revise supplier margin projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Air Hoist Market