
 Global Large Mining Shovels Market | 2026-2036
Global Large Mining Shovels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Large Mining Shovels Market Intelligence
The adoption of high-strength, low-alloy (HSLA) steels in place of conventional carbon steel for shovel buckets and structures is repositioning equipment lifecycle economics. Caterpillar leverages its extensive service network and parts availability to support fleets in remote mining locations. Komatsu differentiates through its integration of proprietary fleet management software and autonomous haulage systems. In contrast, manufacturers such as XCMG and Sany Heavy Industry compete on initial acquisition cost and shorter delivery lead times.
Large mining shovels are heavy-duty excavation machines designed for high-volume material handling in surface mining operations. These machines feature dipper capacities often exceeding 40 cubic meters and are powered by either electric or diesel-electric systems. Hydraulic shovels offer greater mobility and are preferred for selective digging, while electric rope shovels dominate in long-life mines with stable power infrastructure. Demand from ore extraction for metals like copper and iron represents the fastest-growing application segment, supplementing steady volume from coal mining.
Safety and emissions standards from bodies like the US Mine Safety and Health Administration (MSHA) and Australia's state-level regulators dictate equipment design and operational protocols. Concurrently, the EU's F-Gas Regulation and China's dual carbon goals are accelerating the shift from diesel to electric drive systems. Navigating the capital investment cycle for fleet replacement versus retrofitting existing assets with automation and cleaner power sources remains a critical decision for mine operators.
Market Dynamics
The imperative to reduce operational emissions, driven by policies like the EU Green Deal and China's dual carbon goals, is converging with the need for higher material throughput. This dual pressure accelerates the shift toward electric drive systems and larger capacity equipment, fundamentally altering fleet investment decisions for mine operators.
Growth Catalysts
- Commodity Demand:Rising consumption of copper and iron ore for energy transition infrastructure and urban development in Asia-Pacific economies fuels new mine development and fleet expansion projects.
- Material Science Advances:The application of high-strength, low-alloy (HSLA) steels enables the construction of larger, more durable dippers without a proportional weight penalty, improving payload capacity and efficiency.
- Enhanced Safety Standards:Regulations from bodies like the US Mine Safety and Health Administration (MSHA) that mandate improved operator visibility and collision avoidance systems are driving adoption of shovels with integrated sensor technology.
Market Restraints
- Intensive Capital Outlay:The significant upfront investment required for a single large mining shovel restricts acquisition to major mining corporations and lengthens fleet renewal cycles, slowing the introduction of new technology.
- Power Infrastructure Dependency:The operational effectiveness of electric rope shovels depends on stable, high-voltage power infrastructure, limiting their deployment in remote or underdeveloped mining regions without reliable grid access.
- Logistical Complexity:Transporting and assembling these massive machines at remote mine sites presents significant logistical and cost challenges, often requiring specialized transport and extended on-site construction periods.
Strategic Opportunities
- Automation Retrofits:Offering modular automation and remote operation packages for existing shovel fleets presents an opportunity to capture value from operators delaying full asset replacement, enhancing safety and productivity.
- African Resource Development:Growing mining investment in African nations, particularly for copper and cobalt, creates new greenfield opportunities for shovel deployment where modern fleets are underrepresented.
- Predictive Maintenance Services:Leveraging onboard telematics and proprietary software to offer predictive maintenance as a subscription service provides a recurring revenue stream beyond initial equipment sales.
Industry Challenges
- Skilled Operator Shortage:A global shortage of operators and maintenance technicians skilled in managing complex hydraulic, electric, and digital control systems creates operational bottlenecks and increases labor costs for mine operators.
- Legacy System Integration:Integrating new, digitally advanced shovels with existing haulage fleets and mine management software platforms often creates significant technical and workflow challenges, delaying the realization of efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Large Mining Shovels Market |
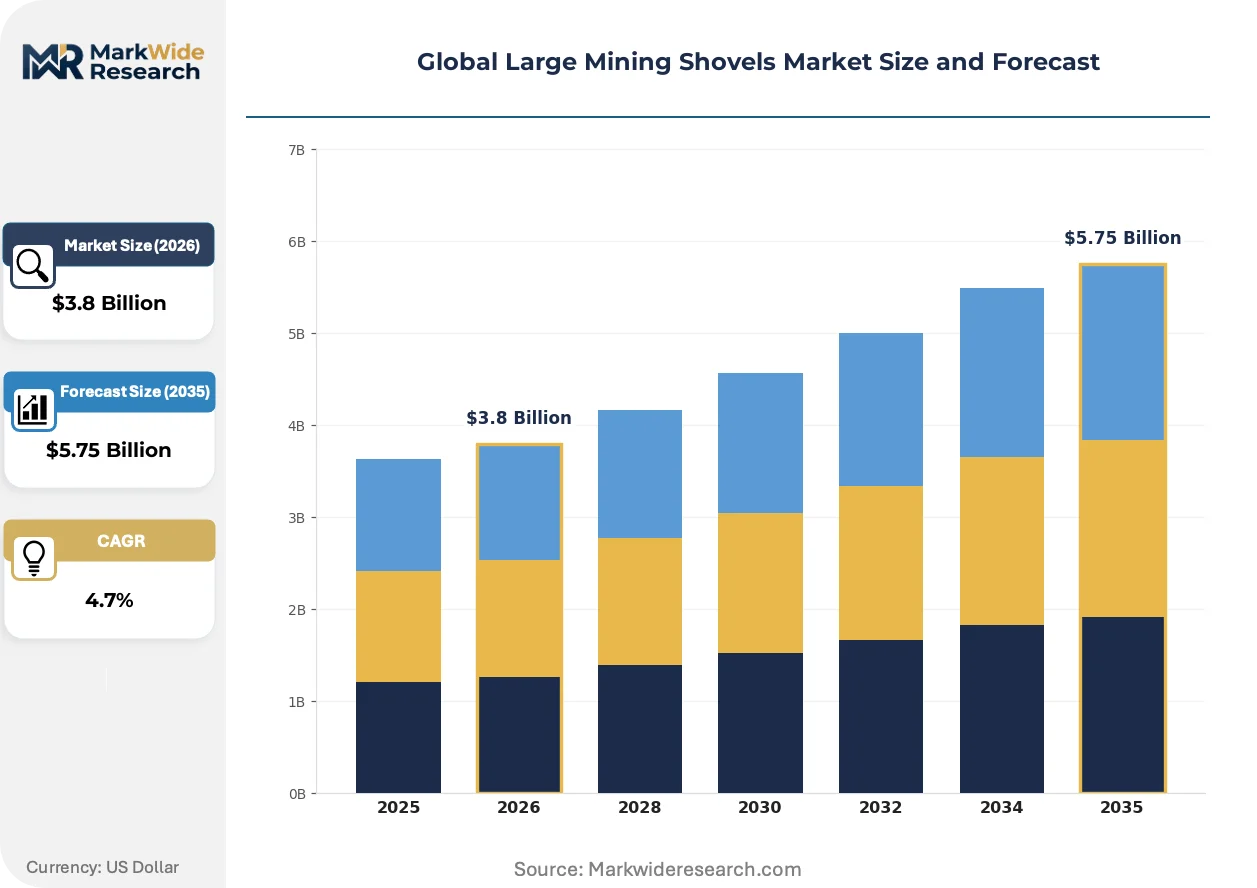
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rope Shovel, Hydraulic Shovel, Cable Excavator, Front Shovel Technology: Hydraulic System, Electric Drive, Diesel Engine, Hybrid Drive, Automation Application: Ore Extraction, Earth Moving, Quarrying, Construction Aggregates, Coal Mining End User Industry: Mining Contractors, Bulk Material Handlers, Mineral Processing Plants, Open-pit Excavators |
| Companies Covered | Hitachi Construction Machinery, XCMG, Caterpillar, Volvo Construction Equipment, Terex, Komatsu, Sany Heavy Industry, Doosan, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Large Mining Shovels Market Strategic Shifts & Innovations
A dual push toward decarbonization and data-driven operational intelligence defines the evolution of large mining shovels. These forces are fundamentally altering equipment design, power systems, and the economic models of fleet management for mining companies globally.
Battery-electric and trolley-assist powertrains provide an alternative to traditional diesel-electric or tethered electric rope shovels. Major mine operators in Australia and Canada are piloting these systems to reduce on-site emissions and fuel costs. This technological shift is rewriting the economic and logistical calculus of mine planning, enabling more flexible and lower-emission pit designs.
The European Union's F-Gas Regulation, which mandates the phase-down of hydrofluorocarbons, directly impacts the design of operator cabin air conditioning systems. This forces manufacturers to re-engineer climate control units using lower global warming potential refrigerants. The most affected are global equipment manufacturers who must standardize on compliant systems across their product lines to maintain access to key regulated markets.
Mine operators are increasingly moving away from simple transactional purchases toward long-term performance and maintenance contracts. This model disrupts the traditional one-time sale, placing more emphasis on total cost of ownership, guaranteed uptime, and productivity metrics. This procurement evolution is most prominent within the large-scale iron ore and coal sectors in Australia, where maximizing asset utilization is paramount.
Global Large Mining Shovels Market Segmentation
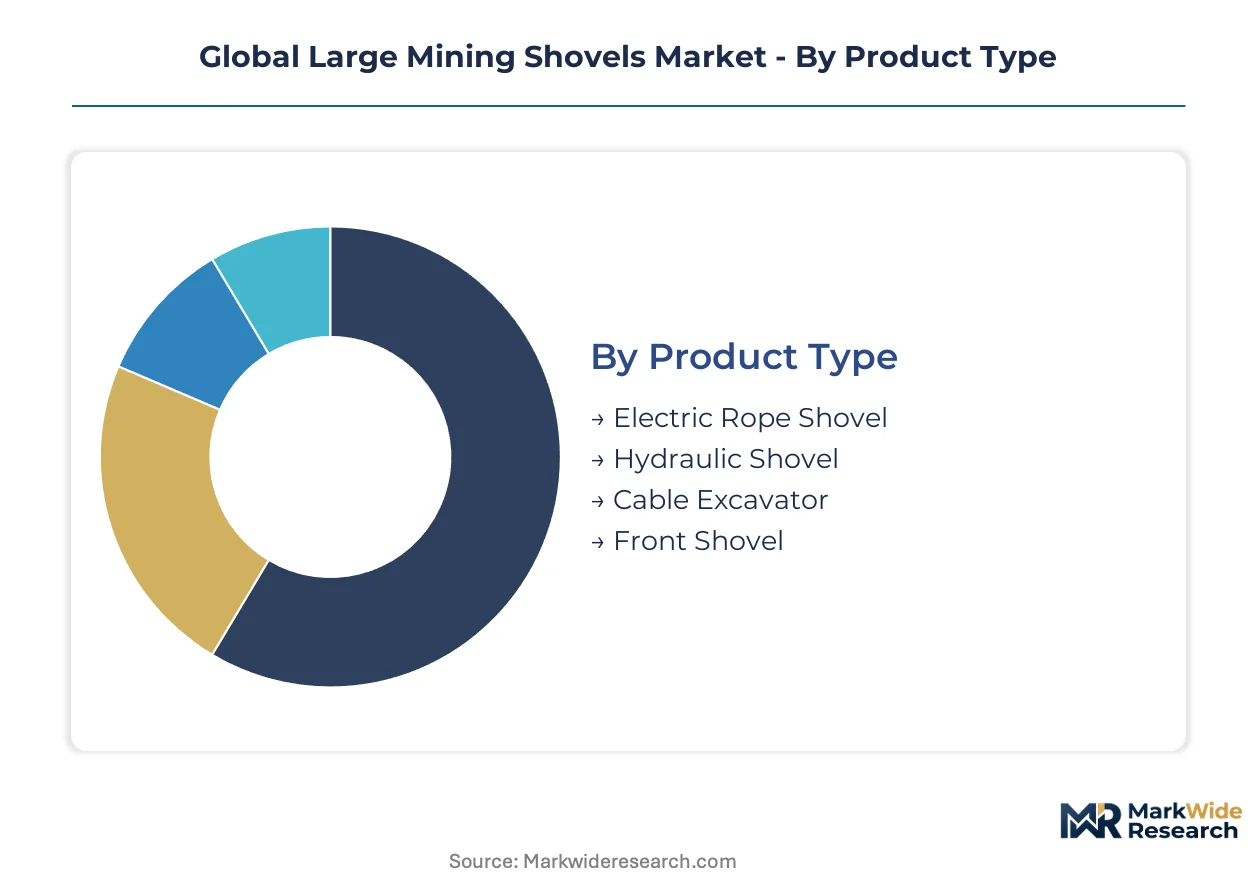
The large mining shovels market segments reflect the diverse operational demands and technological preferences within the global mining industry. Understanding these segments helps manufacturers tailor equipment specifications and service offerings to specific customer needs. This segmentation reveals how different machine types and power sources address varying geological conditions and regulatory environments.
Product Type:
The market's product type segmentation highlights the trade-offs between capital expenditure and operational flexibility. Volume-centric operations often prioritize high-capacity electric rope shovels, while more selective digging tasks favor the mobility of hydraulic units.
- Electric Rope Shovel:These heavy-duty machines utilize electric motors and wire ropes for digging, offering immense dipper capacities often exceeding 40 cubic meters. Their deployment is concentrated in long-life mines in Australia and North America, where stable power infrastructure is available.
- Hydraulic Shovel:Featuring hydraulic cylinders for precise boom and stick movements, these shovels provide greater maneuverability and selective digging capabilities. They are favored for dynamic pit designs and smaller-scale operations across South America and Africa, where flexibility is paramount.
- Cable Excavator:Cable excavators represent a foundational technology, typically employed in large-scale bulk excavation projects. Their robust design supports continuous operation in demanding environments.
- Front Shovel:Optimized for digging into a bank or face, front shovels are commonly used in quarrying and hard rock mining applications. They offer high breakout force for dense materials.
Mature deployment sits with Electric Rope Shovel. Newer deployment is concentrated in Hydraulic Shovel.
Technology:
The technology segment reveals the industry's drive towards efficiency, environmental compliance, and enhanced operational control. Power system choices directly impact fuel consumption and emissions profiles for mine operators.
- Electric Drive:These systems power shovels using electricity, either directly from a grid or via on-board generators, significantly reducing diesel consumption and emissions. Adoption is accelerating in regions like Canada and the EU, driven by stringent decarbonization goals.
- Hydraulic System:Utilizing pressurized fluid to actuate digging and movement functions, hydraulic systems offer precise control and high power density. This technology is foundational for hydraulic shovels and remains critical for selective digging applications.
- Diesel Engine:Traditional diesel engines provide self-contained power for shovels, offering independence from grid infrastructure. They are prevalent in remote mining locations without reliable power access.
- Hybrid Drive:Hybrid systems combine diesel engines with electric components, aiming to optimize fuel efficiency and reduce emissions. These systems capture regenerative energy during operation.
- Automation:This technology integrates sensors, software, and remote control capabilities to enhance safety, improve precision, and enable autonomous operation. Automation systems are increasingly deployed in advanced mining operations.
Electric Drive technology is gaining share fastest. Diesel Engine technology maintains a significant installed base.
Application:
The application segment illustrates the primary end-uses for large mining shovels, reflecting global resource demands. Different materials require specific shovel configurations and operational strategies for efficient extraction.
- Ore Extraction:This application involves removing valuable minerals such as copper, iron, and gold from the earth, often in large open-pit mines. Demand from ore extraction for metals like copper and iron represents the fastest-growing application segment.
- Coal Mining:Large shovels are fundamental to surface coal mining operations, handling vast quantities of overburden and coal seams. This segment provides steady volume due to sustained energy needs in developing economies.
- Earth Moving:Earth moving encompasses general excavation, overburden removal, and site preparation tasks in large-scale mining projects. Shovels facilitate efficient material relocation within mine sites.
- Quarrying:Quarrying operations extract aggregates, limestone, and other rock materials for construction and industrial uses. Shovels are essential for breaking and loading blasted rock.
- Construction Aggregates:This application focuses on extracting sand, gravel, and crushed stone for infrastructure development. Shovels provide the high-volume loading capacity required for these operations.
Ore Extraction shows the steepest expansion trajectory. Coal Mining continues to drive substantial demand.
End User Industry:
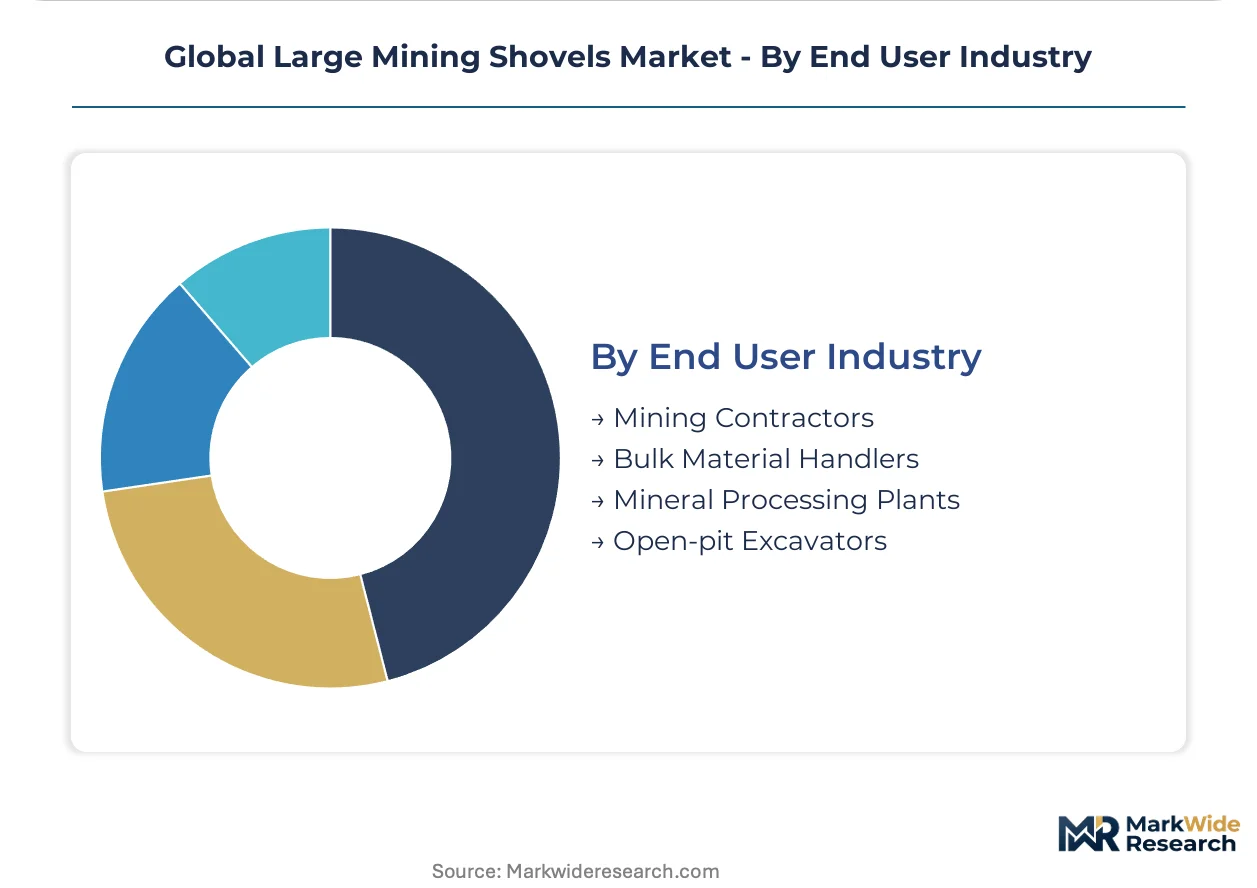
The end user industry segmentation identifies the primary economic entities that purchase and operate large mining shovels. Each industry has distinct procurement processes and operational requirements for its equipment fleet.
- Mining Contractors:These companies specialize in providing mining services, including excavation and material handling, to mine owners. They often operate diverse fleets to meet various client project specifications.
- Open-pit Excavators:Operators focused specifically on large-scale surface mining, these entities manage the extraction of minerals and overburden. Their operations demand robust, high-capacity shovels for continuous duty.
- Bulk Material Handlers:Companies involved in the large-volume movement of raw materials, including minerals and aggregates, utilize shovels for efficient loading onto transport systems. Their focus is on throughput and continuous operation.
- Mineral Processing Plants:While not direct operators of shovels for excavation, these plants receive material loaded by shovels and require consistent feed rates. Shovels at the mine interface ensure steady supply to processing.
Mining Contractors exhibit strong procurement patterns. Open-pit Excavators prioritize asset utilization in their fleet investment decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for large mining shovels is concentrating in key resource-rich economies. These regions drive fleet expansion and technological adoption, influenced by commodity prices and regulatory frameworks. This geographic focus shapes investment decisions for manufacturers.
Australia
Australia's extensive iron ore and coal extraction operations fuel a significant demand for high-capacity shovels. State-level regulators dictate equipment design and operational protocols, emphasizing safety and emissions. Western Australia's Pilbara region, a major iron ore hub, consistently invests in new and upgraded fleets.
China
China's sustained energy needs and industrial development drive substantial demand for coal and iron ore mining equipment. The nation's dual carbon goals accelerate the shift toward electric drive systems in its mining sector. Key mining provinces like Shanxi and Inner Mongolia are seeing significant fleet modernization efforts.
Chile
Chile's position as a leading copper producer necessitates continuous investment in large mining shovels for open-pit operations. Environmental regulations increasingly influence the adoption of cleaner electric-powered machinery. The Atacama Desert region, home to major copper mines, sees ongoing expansion and technology upgrades.
Brazil
Brazil's vast iron ore and bauxite reserves generate consistent demand for heavy-duty excavation equipment. Strict environmental licensing processes guide the deployment of new mining projects and fleet acquisitions. Minas Gerais, a core mining state, remains a critical market for shovel manufacturers.
South Africa
South Africa's significant platinum group metals and coal mining sectors require robust large mining shovels for high-volume extraction. The country's Mining Charter influences local procurement and operational standards for equipment. Limpopo province, known for its platinum mines, is a focal point for new equipment deployment.
Global Large Mining Shovels Market Key Industry Players
Geographic expansion dominates the current competitive landscape for large mining shovels, particularly as manufacturers target emerging mining regions. The market structure exhibits consolidation among established global manufacturers, with a fragmented base of regional and specialized players. Three strategic archetypes emerge: premium technology providers, cost-efficient volume producers, and niche solution developers focused on specific applications. Portfolio diversification and strategic partnerships are also critical competitive moves for sustaining market leadership.
On the premium-tier vector, Caterpillar and Komatsu exemplify global original equipment manufacturers that leverage extensive service networks and proprietary software integration. These companies, with their long-standing presence, anchor segments requiring advanced technology and comprehensive support for complex operations. XCMG, a Chinese heavy machinery manufacturer, represents the archetype of a cost-competitive entrant, focusing on initial acquisition cost and shorter delivery lead times for large mining shovels in various global markets.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| XCMG |
| Caterpillar |
| Volvo Construction Equipment |
| Terex |
| Komatsu |
| Sany Heavy Industry |
| Doosan |
| Liebherr |
| Others |
Cost & Logistics Intelligence
Mining contractors often drive acquisition decisions, influencing the long-term performance-based contract model. Major open-pit excavators prioritize total cost of ownership over initial acquisition price.
Pricing Analysis
Volume-centric operations often prioritize capital expenditure efficiency, while specialized tasks demand premium features. Pricing for large mining shovels is typically transactional for initial acquisition, but increasingly shifts towards performance and maintenance contracts. Technology integration, such as automation and electric drive systems, along with comprehensive after-sales service networks, serve as key differentiation drivers. Pricing softness reflects increased competition from cost-competitive entrants. Mining contractors exhibit higher price sensitivity on initial purchases, whereas large open-pit excavators focus on long-term operational costs and guaranteed uptime.
Supply Chain Analysis
Component sourcing for large mining shovels draws from global manufacturing hubs in Japan, Germany, China, and the USA. Key raw material and component dependencies include high-strength, low-alloy (HSLA) steels for structures, electric drive systems, and advanced hydraulic components. A structural risk involves logistics chokepoints for transporting massive sub-assemblies and completed machines to remote mine sites. Distribution runs through established direct sales channels complemented by extensive global dealer networks, providing localized support and service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The large mining shovels market is a consolidation play, driven by the intensive capital outlay required for advanced equipment. This capital requirement pushes smaller manufacturers to exit or specialize.
For Market Incumbents:Anchor service networks and parts availability in remote mining locations to counter emerging entrants. Invest in research and development for advanced electric drive systems and modular automation retrofits to address decarbonization goals. This counters the threat of new, specialized technology providers that may offer point solutions without comprehensive support.
For New Entrants and Emerging Players:Launch via modular automation packages for existing fleets, targeting operators delaying full asset replacement. Focus on the African resource development segment, where modern fleets are underrepresented. Offer cost-effective hydraulic shovels with integrated sensor technology for selective digging applications in dynamic pit designs.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers with deep pockets and long-term vision for industrial asset management. Target specialized technology providers offering automation or battery-electric solutions to capture future market share. A signal to watch is the accelerated adoption rate of electric rope shovels in new greenfield projects across resource-rich regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Global Service Network | Ensures uptime and operational continuity for high-value assets in remote regions. |
| Invest in Electric Drive R&D | Addresses stringent emissions regulations and reduces operational costs for mine operators. |
| Develop Modular Automation Retrofits | Captures value from operators extending asset lifecycles and enhances safety standards. |
| Secure HSLA Steel Supply Agreements | Guarantees material availability for durable, high-capacity shovel components. |
| Target African Resource Development | Accesses new greenfield opportunities for shovel deployment in underrepresented markets. |
Research Approach
Independent corroboration across industry reports, US Mine Safety and Health Administration (MSHA) safety data, and original equipment manufacturer financial disclosures underwrites the qualitative findings. Primary interviews with mine operators, equipment procurement managers, and maintenance technicians provided granular insights. Secondary validation included analysis of regulatory body publications and material science journals. Bottom-up and top-down triangulation ensured data consistency.
Historical market performance across comparable periods anchored the forecast framework over the projection horizon. Segmentation dimensions modeled included product type, technology, application, and end user industry. Compound annual growth rates were derived from a multi-variant regression analysis. Key forecast inputs included commodity price trends and regional infrastructure development plans across the modeling period.
Geopolitical instability, commodity price volatility, and evolving environmental regulations are the dominant revision risks. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Mining Drill Bits Market