
 Global Dozers Market | 2026-2036
Global Dozers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dozers Market Analysis
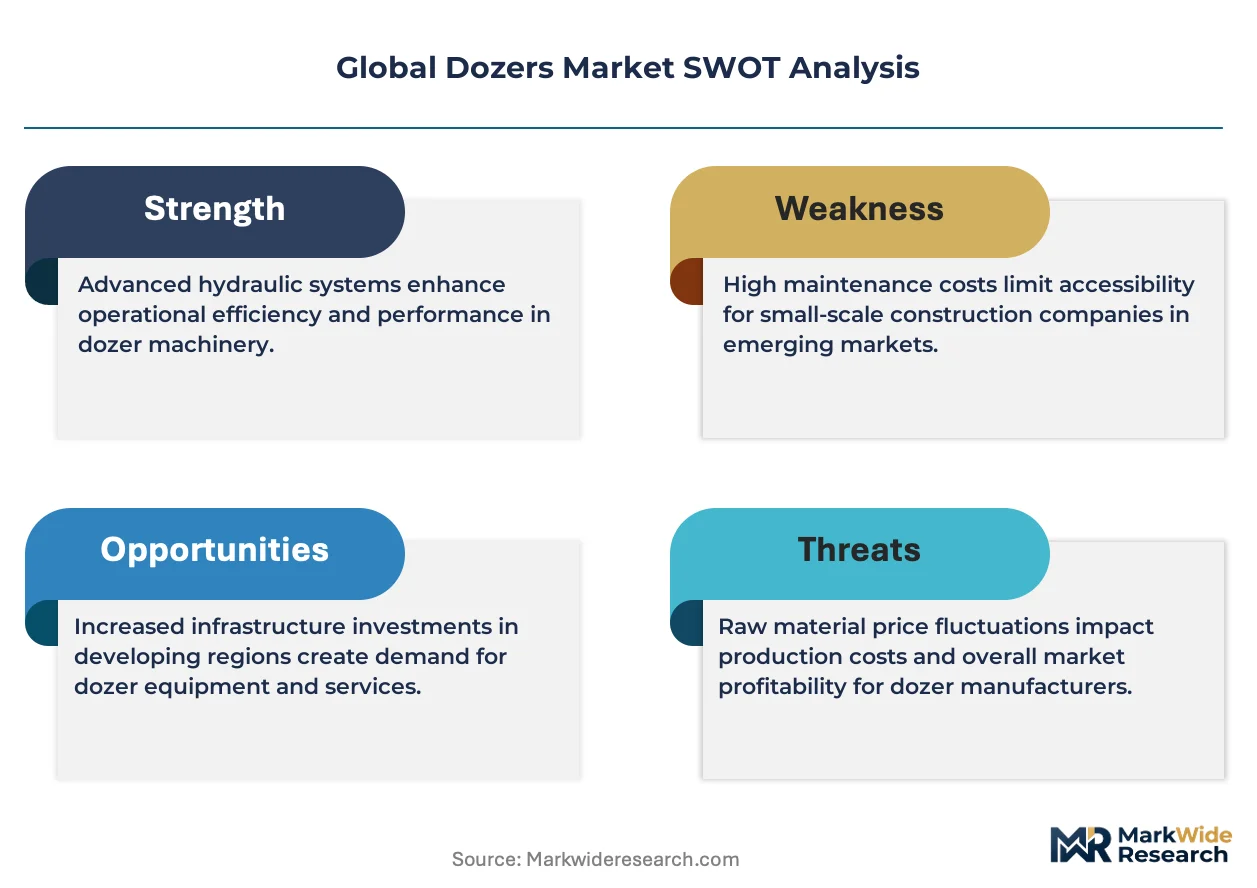
High-strength steel is realigning dozer blade and undercarriage economics as fabricators substitute conventional carbon plate with advanced abrasion-resistant alloys. Caterpillar leverages captive metallurgy research to sustain margin advantages in mining-class machines. Komatsu anchors its position through integrated powertrain manufacturing in Japan and North America. Deere & Company competes by specializing in agricultural crossover dozers with precision grading packages.
A dozer is a tracked or wheeled earthmoving machine featuring a hydraulically actuated blade mounted to the front chassis, typically delivering drawbar pull exceeding 200 kN and operating at blade capacities from 2 to 60 cubic meters for cut-and-fill operations, stockpile management, and rough grading. Crawler dozers dominate mining and heavy civil applications where traction and low ground pressure prove decisive, while mini dozers capture residential and utility contracting segments where transportability and fuel efficiency command premium positioning. Electrified technology represents the fastest-growing dimension as battery-hybrid architectures displace mechanical drivetrains in regulated jurisdictions.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine redesigns and aftertreatment integration, directly elevating product cost and reshaping supplier qualification criteria. China's MIIT enforces GB national standards on non-road mobile machinery, creating parallel certification demands for OEMs serving domestic and export channels. Stakeholders must monitor powertrain subsidy thresholds and charging infrastructure buildouts to calibrate electrification investment timing against diesel residual value curves.
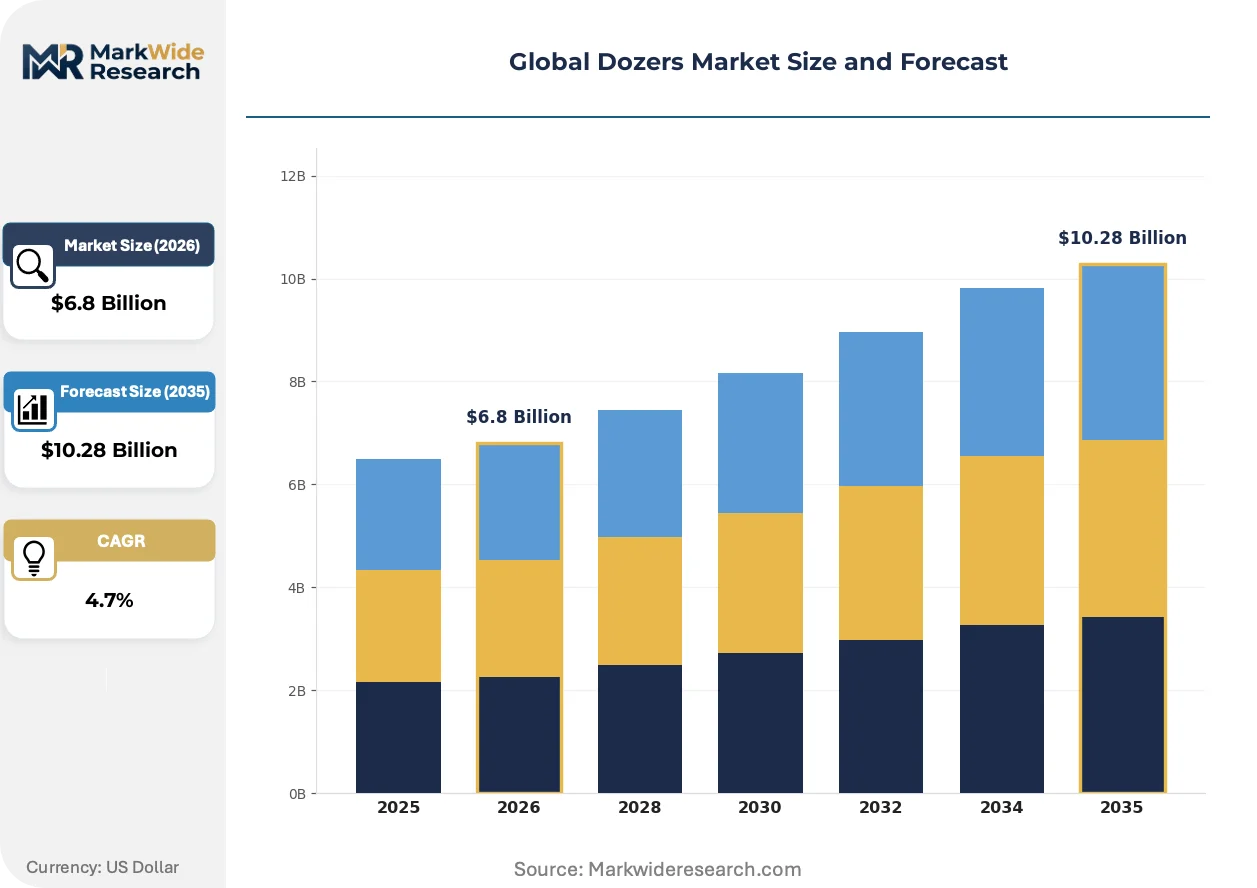
Market Dynamics
Electrified powertrain mandates from EPA Tier 4 Final and EU Stage V are compressing diesel residual values while forcing OEMs to absorb battery supply chain premiums, fundamentally restructuring how fleet operators calculate total cost of ownership across mining and heavy civil applications.
Growth Catalysts
- Bulk Earthworks Expansion:Mining operators in Australia and Chile are expanding crawler dozer fleets to support copper and iron ore extraction, driving replacement demand for high-drawbar-pull machines in high-abrasion environments.
- State-Backed Infrastructure:China's western provinces require heavy land-clearing capacity under state-backed infrastructure programs, concentrating demand for large-blade crawler configurations in Sichuan and Xinjiang.
- Emissions-Driven Product Refresh:EPA Tier 4 Final and EU Stage V compel engine redesigns and aftertreatment integration, accelerating fleet turnover as older machines face operational restrictions in regulated jurisdictions.
Market Restraints
- High-Strength Steel Input Costs:Advanced abrasion-resistant alloys for blades and undercarriages command premiums over conventional carbon plate, compressing fabricator margins when mining customers resist price escalation.
- Battery Supply Concentration:Cell manufacturing concentrates in East Asian supply bases, exposing OEMs to logistics bottlenecks and geopolitical friction when scaling electrified product lines.
- Mechanical Drivetrain Substitution:Battery-hybrid architectures threaten service revenue streams tied to engine rebuilds and transmission overhauls, creating channel conflict with dealer networks.
Strategic Opportunities
- Charging Infrastructure Buildouts:Powertrain subsidy thresholds in regulated markets create first-mover advantages for OEMs that bundle charging hardware with machine sales.
- Agricultural Crossover Segments:Precision grading packages for agricultural crossover dozers capture utility contractors seeking transportability without sacrificing cut-and-fill accuracy.
- Integrated Powertrain Manufacturing:Captive production of electric motors and inverters in Japan and North America insulates against supplier qualification delays while accelerating electrified product launches.
Industry Challenges
- Aftertreatment Integration Complexity:EPA Tier 4 Final and EU Stage V certification timelines extend product development cycles, delaying revenue recognition for redesigned engine platforms.
- Skill Gaps in Electrified Service:Dealer technicians require retraining on high-voltage systems and battery thermal management, straining OEM training infrastructure during product transitions.
- Parallel Certification Demands:China's MIIT enforces GB national standards on non-road mobile machinery, forcing OEMs to maintain separate testing protocols for domestic and export channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dozers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Dozers, Wheel Dozers, Mini Dozers, Grade Dozers End User: Construction, Mining, Agricultural, Forestry Technology: Hydraulic, Integrated, Electrified, Autonomous Application: Site Preparation, Road Construction, Material Handling, Land Clearing |
| Companies Covered | Caterpillar, Komatsu, XCMG Group, Deere & Company, Liebherr Group, Shantui Construction Machinery, Volvo Construction Equipment, Hitachi Construction Machinery, Sany Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dozers Market Emerging Trajectories
Battery-hybrid architectures are actively displacing mechanical drivetrains as the dominant technical focus, while regulatory frameworks and procurement patterns simultaneously reshape how value flows through manufacturer-dealer-fleet relationships.
Telematics-enabled predictive maintenance is integrating real-time blade wear monitoring and undercarriage health diagnostics into fleet management platforms. Mining operators in Chile and Australia are adopting these systems fastest, demanding API integrations with existing enterprise resource planning infrastructure. This convergence is integrating machine data streams into capital allocation decisions, compressing replacement cycles for components before catastrophic failure.
EU Stage V and EPA Tier 4 Final are tightening particulate matter and nitrogen oxide limits for non-road mobile machinery, compelling exhaust aftertreatment systems that add weight and consume payload capacity. OEMs serving European and North American markets are responding with compact selective catalytic reduction designs and diesel exhaust fluid tank repositioning to preserve blade geometry.
Service contract unbundling is fragmenting traditional dealer revenue models as fleet operators prefer à-la-carte maintenance subscriptions over bundled warranties. Mining contractors in Western Australia are piloting outcome-based uptime guarantees separate from machine purchase agreements. This restructuring is most visible in copper and iron ore extraction segments where downtime costs exceed preventive maintenance premiums.
Global Dozers Market Segmentation
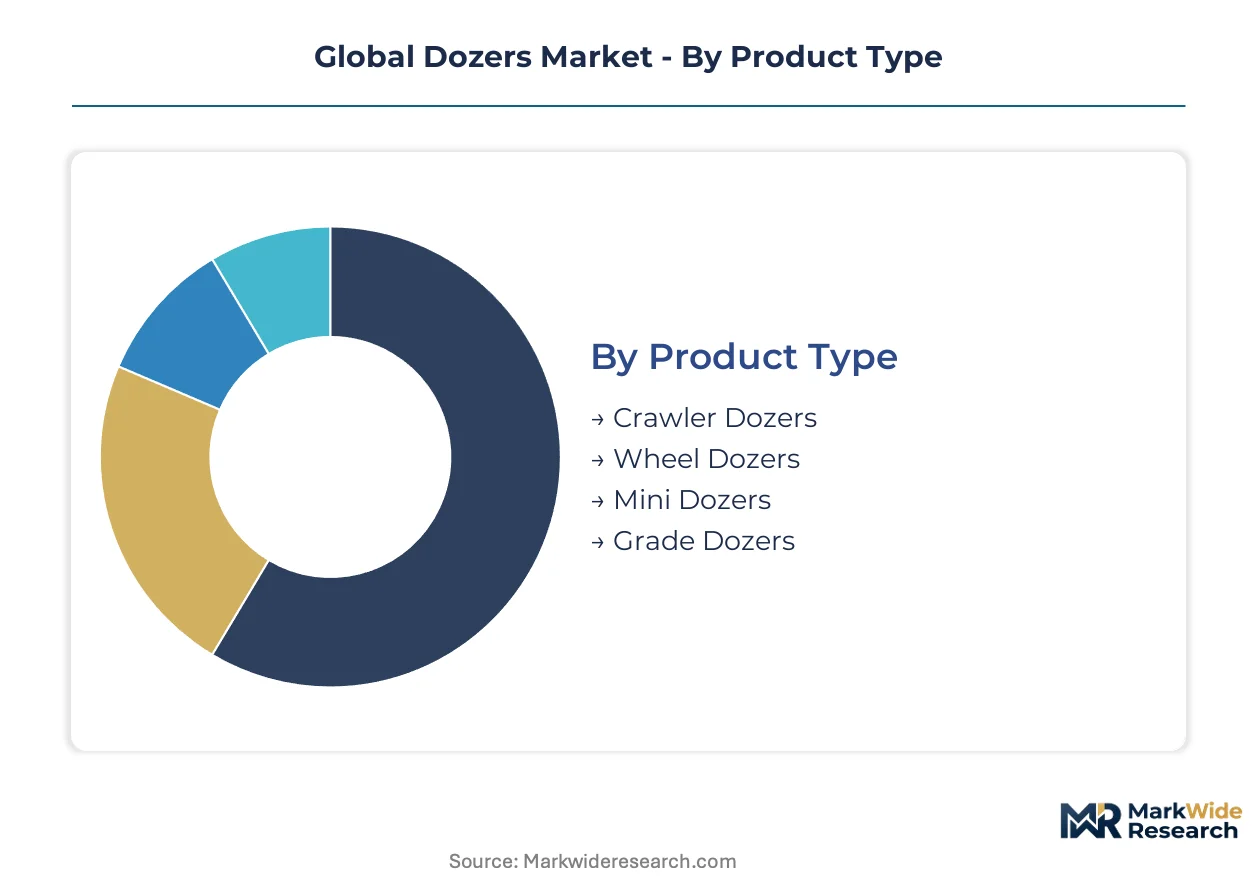
Dozer segmentation tracks divergent engineering requirements across traction systems, powertrain architectures, and duty-cycle intensity. Mining contractors in Australia and Chile select crawler configurations for drawbar pull, while urban utilities prioritize mini dozers for transportability. Technology choices increasingly hinge on emissions compliance timelines rather than pure performance metrics.
Product Type:
Blade mounting geometry and undercarriage specification determine ground pressure distribution, cut-and-fill precision, and transport logistics across operating environments.
- Crawler Dozers:Tracked undercarriages with sealed and lubricated track chains distribute machine weight across broad ground contact areas. Mining operators in Western Australia and Chile's Atacama Desert specify high-horsepower crawler configurations for bulk earthworks in high-abrasion conditions where traction and low ground pressure prove decisive.
- Mini Dozers:Compact chassis designs with operating weights below 10 tonnes enable trailer transport without specialized permits. Residential contractors in Germany and utility operators in Japan specify mini configurations for confined-site grading where maneuverability and fuel efficiency command premium positioning.
- Wheel Dozers:Articulated steering and rubber-tired mobility deliver higher travel speeds for stockpile management and hopper feeding.
- Grade Dozers:Integrated GPS and laser-guided blade control systems enable precision finishing work with millimeter-level accuracy.
Crawler dozers lead on scale; mini dozers lead on momentum.
End User:
Capital intensity and fleet replacement cycles vary sharply across extractive industries, civil infrastructure, and agricultural crossover applications.
- Mining:Continuous-duty operations in copper and iron ore extraction demand machines with drawbar pull exceeding 200 kN and blade capacities above 30 cubic meters. Fleet operators in Chile's Escondida complex and Australia's Pilbara region specify abrasion-resistant blade alloys and heavy-duty undercarriages for 15,000-hour service intervals.
- Construction:Project-based procurement patterns concentrate demand in China's western provinces where state-backed infrastructure programs require heavy land-clearing capacity for highway and rail corridors through Sichuan and Xinjiang terrain.
- Agricultural:Precision grading packages for land leveling and drainage installation serve contractors seeking transportability without sacrificing cut-and-fill accuracy.
- Forestry:Specialized guarding and winch configurations adapt base machines for log skidding and site rehabilitation in managed timber operations.
Mining leads on scale; construction leads on momentum.
Technology:
Powertrain architecture selection increasingly correlates with regulatory jurisdiction rather than application type alone.
- Electrified:Battery-hybrid architectures with electric traction motors and onboard energy storage displace mechanical drivetrains in regulated markets. EPA Tier 4 Final and EU Stage V emissions frameworks accelerate fleet turnover as battery energy density improvements compress total cost of ownership calculations for mining contractors in Germany and California.
- Autonomous:Sensor fusion systems with LiDAR, radar, and machine vision enable remote operation and unmanned convoy following in repetitive haul cycles. Rio Tinto and BHP deploy autonomous dozer fleets in Western Australian iron ore operations where labor scarcity and safety requirements justify capital investment.
- Hydraulic:Conventional open-center and load-sensing hydraulic systems retain cost advantages in unregulated markets with lower fuel pricing.
- Integrated:Closed-loop electro-hydraulic architectures combine electronic control with proven fluid power for transitional compliance strategies.
Hydraulic leads on scale; electrified leads on momentum.
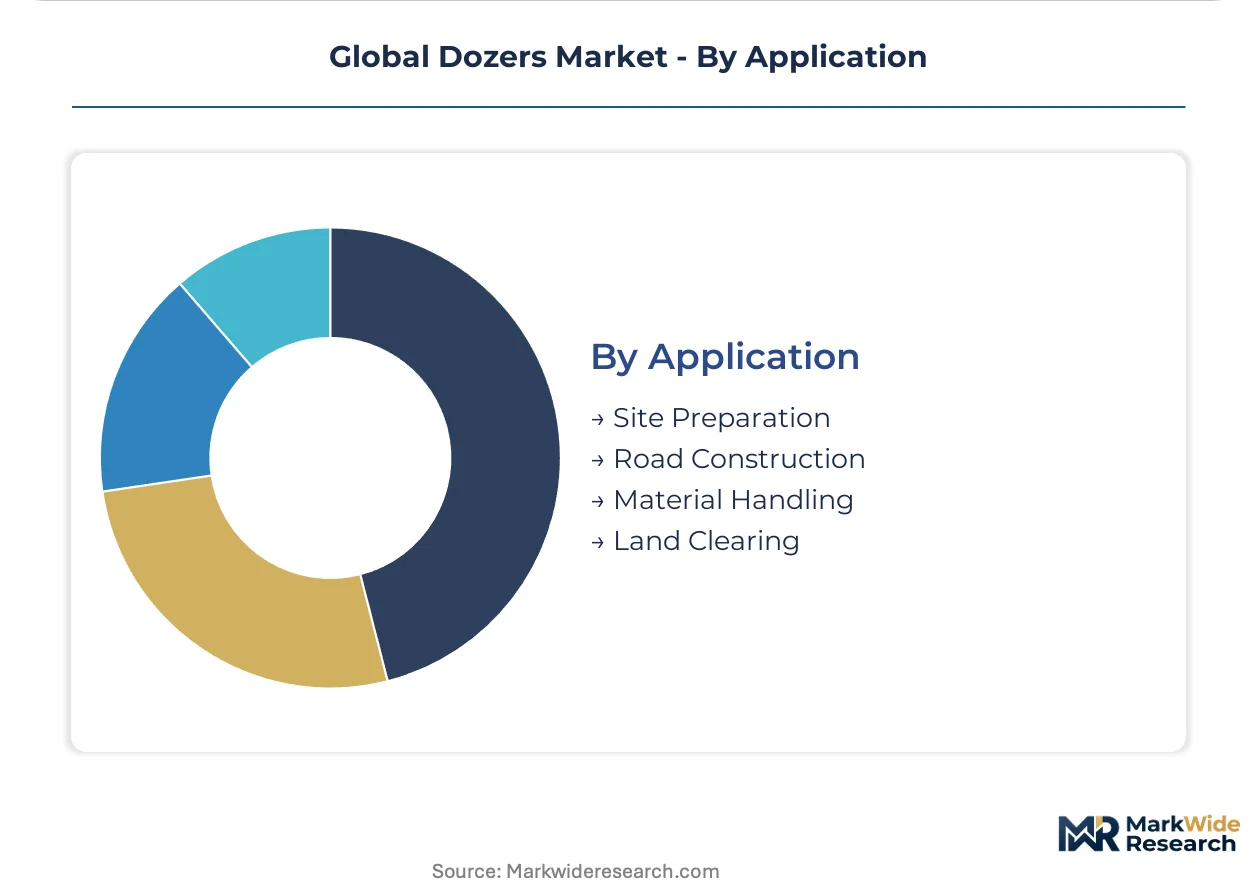
Application:
Soil mechanics and material properties dictate blade geometry, ripper configuration, and ground engagement tool selection.
- Site Preparation:Bulk cut-and-fill operations requiring high production rates in unconsolidated materials drive demand for large-blade crawler configurations. Developers in China's western provinces specify heavy-duty machines for terrain modification before structural foundation work.
- Land Clearing:Vegetation removal and stump extraction in forestry and agricultural conversion applications require specialized rake attachments and protective guarding. Contractors in Brazil's Mato Grosso and Indonesia's Sumatra deploy modified dozers for plantation establishment where biomass accumulation challenges machine durability.
- Road Construction:Subgrade preparation and embankment compaction demand precise blade control for specified slope gradients and crown profiles.
- Material Handling:Coal and aggregate stockpile management prioritizes travel speed and visibility over pure cutting force.
Site preparation leads on scale; land clearing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara region anchors global demand for high-drawbar-pull crawler configurations, with mining contractors specifying abrasion-resistant blade alloys for iron ore extraction. Fleet operators across Chile, Australia, China, Germany, and the United States drive regional differentiation through emissions compliance timelines and mineral extraction intensity.
Chile
Copper extraction at the Escondida complex drives replacement demand for heavy-duty undercarriages rated for 15,000-hour service intervals. The country's Ministry of Mining enforces progressive closure plans that mandate site rehabilitation equipment. Antofagasta-based contractors deploy modified dozers for bulk earthworks in the Atacama Desert where traction and low ground pressure prove decisive.
Australia
Iron ore operators in Western Australia expand autonomous dozer fleets to address labor scarcity and safety requirements in repetitive haul cycles. The country's Department of Climate Change, Energy, the Environment and Water administers fuel quality standards affecting diesel engine specifications. Perth-headquartered mining contractors pilot telematics-enabled predictive maintenance systems with API integrations into enterprise resource planning infrastructure.
China
State-backed infrastructure programs in Sichuan and Xinjiang provinces concentrate demand for large-blade crawler configurations in highway and rail corridor development. The Ministry of Industry and Information Technology enforces GB national standards on non-road mobile machinery, creating parallel certification demands for domestic and export channels. Chengdu-based fabricators face margin compression when mining customers resist price escalation for advanced abrasion-resistant alloys.
Germany
Residential contractors specify mini dozer configurations for confined-site grading where maneuverability and fuel efficiency command premium positioning. EU Stage V emissions frameworks compel compact selective catalytic reduction designs and diesel exhaust fluid tank repositioning to preserve blade geometry. Bavaria-based utility operators adopt battery-hybrid architectures as battery energy density improvements compress total cost of ownership calculations.
United States
California mining contractors accelerate fleet turnover as battery-hybrid architectures displace mechanical drivetrains under EPA Tier 4 Final mandates. The Environmental Protection Agency enforces particulate matter and nitrogen oxide limits that elevate product cost through aftertreatment integration. Arizona-based copper extraction operations demand machines with drawbar pull exceeding 200 kN for continuous-duty bulk earthworks.
Global Dozers Market Vendor Landscape
Global majors compete with regional champions across powertrain electrification and integrated manufacturing depth. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive metallurgy research, specialized construction equipment fabricators with regional density, and emerging battery-technology entrants from adjacent automotive supply chains. Dominant competitive moves include backward integration into electric motor and inverter production, and strategic bundling of charging hardware with machine sales to capture first-mover subsidies.
Within the diversified industrial tier, Caterpillar, Komatsu, and Deere & Company exemplify contrasting strategic postures. Caterpillar leverages captive metallurgy research to sustain margin advantages in mining-class machines. Komatsu anchors its position through integrated powertrain manufacturing in Japan and North America. Deere & Company occupies a specialization niche in agricultural crossover dozers with precision grading packages.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| XCMG Group |
| Deere & Company |
| Liebherr Group |
| Shantui Construction Machinery |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Sany Construction |
| Others |
Supply Flow & Price Mechanics
High-strength steel alloying costs cascade from East Asian metallurgical plants through three-tier pricing structures across premium, standard, and economy levels, with mining-class machine fabricators absorbing margin compression when Australian and Chilean fleet operators resist escalation.
Pricing Analysis
Input-cost pass-through from advanced abrasion-resistant alloys and battery cell supply premiums stratifies pricing across mining-class, civil construction, and agricultural crossover tiers. EPA Tier 4 Final and EU Stage V certification requirements differentiate premium electrified configurations from standard hydraulic machines. Price erosion runs through economy-tier hydraulic dozers as Chinese fabricators compete on volume. Mining contractors in Western Australia exhibit lowest price sensitivity due to uptime value; residential contractors in Germany face highest pressure.
Supply Chain Analysis
High-voltage battery cell supply rests on South Korean and Japanese producers, while high-strength steel plate draws from Chinese and Indian metallurgical complexes. Critical dependencies include lithium-ion cells, abrasion-resistant alloys, and precision hydraulic components. Single-source vulnerability concentrates in East Asian cell manufacturing. Distribution runs through OEM captive dealer networks and independent rental channels serving project-based construction procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V emissions compounding is accelerating fleet turnover and electrified product investment across mining and heavy civil applications.
For Market Incumbents: Cement metallurgy research advantages through captive alloy development for high-abrasion mining environments. Deepen backward integration into electric motor and inverter production in Japan and North America to insulate against supplier qualification delays. Battery supply chain bottlenecks threaten electrified product launch timing.
For New Entrants and Emerging Players: Battery-hybrid powertrain architectures offer entry wedge into California and German mining contractor segments where regulatory mandates compress diesel residual values. Target agricultural crossover precision grading packages where Deere & Company's specialization leaves white space for transportable mini dozer configurations. Bundle charging hardware with machine sales to capture first-mover subsidy thresholds.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with dense aftermarket parts distribution because electrified drivetrains fragment traditional dealer revenue streams and create consolidation opportunities. Target mid-tier fabricators with GB standard certification for Chinese domestic channel access. Watch EPA enforcement intensity and EU Green Deal implementation pace as inflection signals for electrification investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electric Powertrain Components | Captive motor and inverter production in Japan accelerates electrified product launches against supplier bottlenecks. |
| Charging Infrastructure Bundling | Hardware-integrated sales capture first-mover subsidies in California and German regulated markets. |
| High-Strength Steel Alloy Development | Proprietary metallurgy sustains margin advantages in Escondida and Pilbara mining-class machines. |
| Telematics Platform Integration | API-connected predictive maintenance systems compress replacement cycles for Chilean copper operators. |
| GB Standard Certification Investment | Parallel testing protocols unlock Sichuan and Xinjiang state-backed infrastructure procurement channels. |
Methodological Framework
Multiple input streams — OEM product planning interviews, mining fleet operator procurement surveys, and regulatory filing analysis — were reconciled against customs trade data and equipment registration databases. Primary discussions with maintenance directors at Western Australian iron ore operations, aftermarket service heads in Chile's Antofagasta region, and OEM procurement teams in Japan informed demand-side assumptions. Secondary validation drew from EPA certification records, EU Stage V type-approval documentation, and MIIT GB standard enforcement notices. Bottom-up unit shipment estimates triangulated with top-down value projections.
Data-stream reconciliation across powertrain architecture, blade capacity tier, and end-use intensity dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate analysis weighted by regional regulatory compliance timelines. Industry-specific forecast inputs included mining extraction capital expenditure patterns and infrastructure program allocation flows from China's western provinces.
The model holds under sustained emissions enforcement intensity; deviation in battery supply chain reshoring velocity or high-strength steel price volatility would shift electrification adoption curves. A concentrated watch set on EPA enforcement actions, EU Green Deal implementation pace, and Chinese dual carbon goal acceleration warrants ongoing monitoring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Kazakhstan Mining Market