
 Underground Mining Automation Market | 2026-2036
Underground Mining Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Mining Automation Market Analytics
ISO 17757 is restructuring the cost-of-entry calculus for automation suppliers by mandating functional safety validation for autonomous mining equipment. Komatsu leverages its integrated autonomous haulage systems to dominate deployment scale across deep ore bodies. Sandvik AB anchors its position through purpose-built underground loaders with tele-remote and fully autonomous tramming capabilities. Epiroc AB specializes in drill rig automation, competing on precision and machine interoperability in narrow-vein operations.
Underground mining automation encompasses the integration of autonomous vehicles, remote control architectures, sensor networks, and data analytics platforms to execute drilling, hauling, and material handling without continuous human presence in hazardous zones. These systems typically operate on hardened industrial networks with sub-50 millisecond latency requirements for real-time equipment command and collision avoidance. The technology segment splits functionally: autonomous vehicles capture the largest capital allocation due to haulage fleet replacement cycles, while sensor technologies represent the fastest-expanding margin pool as predictive maintenance adoption deepens. Application demand clusters around material handling and safety monitoring, where labor substitution yields immediate operational expenditure reduction and regulatory compliance benefits.
Australia's DNRME, Canada's provincial mining regulators, and South Africa's Department of Mineral Resources and Energy each enforce distinct ventilation, rock-burst, and remote-operation standards that shape equipment certification requirements and deployment timelines. The European Union's Machinery Directive and associated CE conformity processes add compliance layers for vendors serving import-dependent markets. Stakeholders must monitor how regulatory divergence between hard-rock and coal jurisdictions affects platform standardization strategies and service architecture investments.
Market Dynamics
ISO 17757 functional safety mandates are compressing vendor qualification timelines while hard-rock operators in Australia's Western Australia iron ore belt and Chile's Atacama copper operations accelerate fleet replacement cycles. This regulatory-technological collision is restructuring capital deployment patterns across deep-ore extraction.
Growth Catalysts
- Australia's DNRME ventilation mandates:Remote-operation standards for hazardous zones are compelling underground operators to prioritize tele-remote loader deployments over conventional manned equipment.
- Hard-rock metal extraction:Narrow-vein copper and gold operations in Chile and Canada are scaling autonomous drill rig fleets to maintain production depth without proportional labor expansion.
- Sensor fusion architectures:LiDAR-radar-vision integration for collision avoidance is reducing insurance premiums and accelerating payback calculations for autonomous haulage investments.
Market Restraints
- Sub-50 millisecond latency requirements:Hardened industrial network infrastructure demands specialized fiber-optic and private 5G deployments that inflate initial capital outlays by 40-60% versus standard surface automation.
- Canadian provincial certification divergence:British Columbia, Ontario, and Quebec maintain non-harmonized electrical safety standards for battery-electric underground vehicles, fragmenting equipment approval pathways.
- Rock-burst prediction limitations:Current seismic monitoring systems generate false-positive rates exceeding 15% in deep-level South African gold operations, constraining full autonomy deployment.
Strategic Opportunities
- Platinum-group metal operations in South Africa:Rustenburg and Limpopo belt mines remain underpenetrated by autonomous haulage due to shaft geometry constraints, creating retrofit-ready demand as ISO 17757 compliance deadlines approach.
- Predictive maintenance platforms:Vibration and thermal sensor analytics for continuous miners represent uncaptured margin pools as OEM service contracts expire and operators seek independent diagnostics.
- EU Green Deal carbon intensity disclosures:Battery-electric underground fleets qualify for preferential financing terms under the European Investment Bank's sustainable mining facility, redirecting procurement toward electrified automation.
Industry Challenges
- Tele-remote operator certification:Australia's DNRME and Canada's provincial regulators lack harmonized competency frameworks, forcing equipment vendors to maintain multiple training curricula and assessment protocols.
- Legacy SCADA integration:Brownfield underground operations running 1990s-era control systems face protocol translation complexity when connecting autonomous vehicles to centralized mine management platforms.
- Functional safety validation timelines:ISO 17757 third-party certification cycles extend 18-24 months for new autonomous tramming algorithms, delaying revenue recognition for technology suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Mining Automation Market |
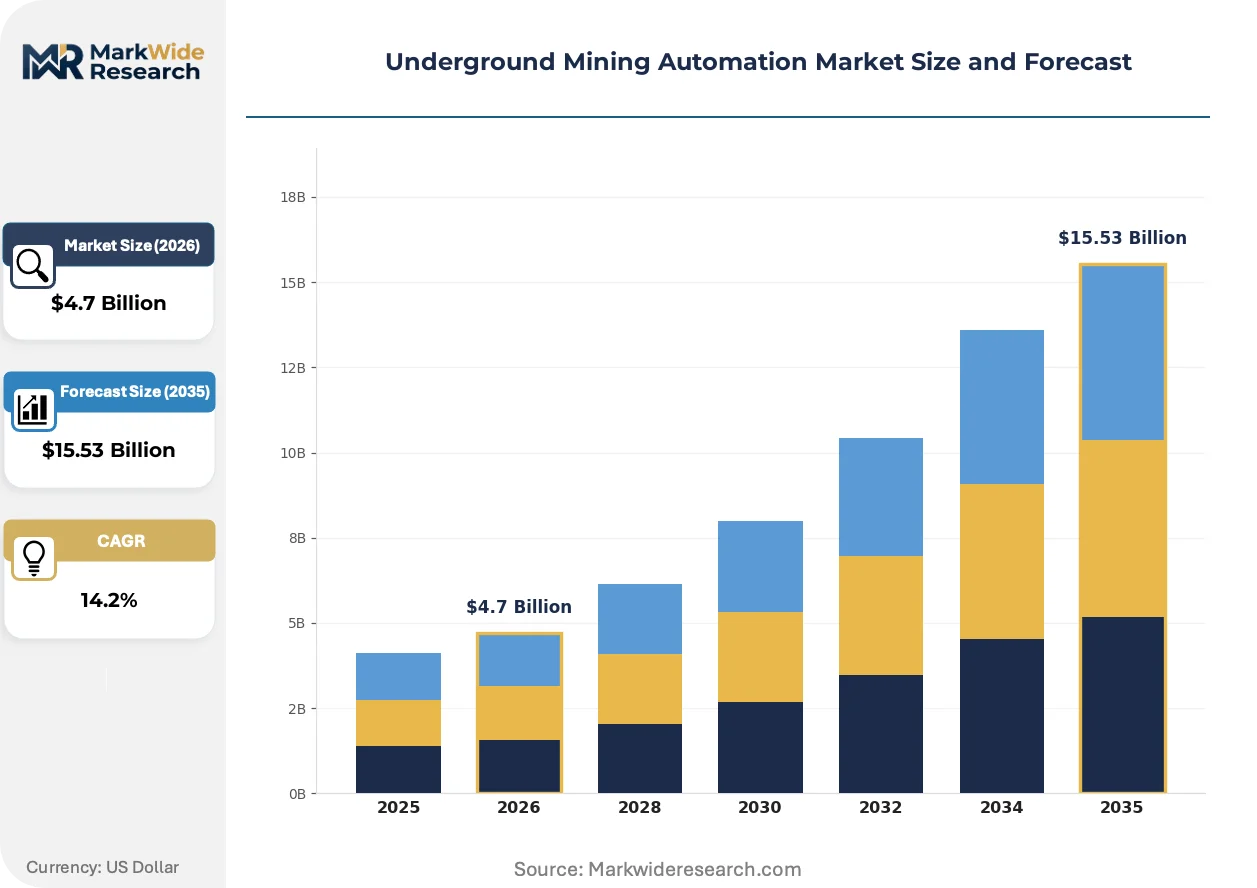
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous Vehicles, Remote Control Systems, Sensor Technologies, Data Analytics Application: Material Handling, Mine Development, Equipment Maintenance, Safety Monitoring End User: Mining Operators, Equipment Manufacturers, Safety Inspectors, Regulatory Bodies Deployment: On-Premise Solutions, Cloud-Based Services, Hybrid Models, Integrated Systems |
| Companies Covered | Komatsu, ABB, Sandvik AB, Hexagon, Rockwell Automation, Epiroc AB, Hitachi Construction Machinery, Autonomous Solutions, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Mining Automation Market Evolving Landscape
Autonomous haulage architectures are converging with battery-electric powertrains, while regulatory pressure on diesel particulate exposure accelerates platform replacement decisions. Equipment vendors and mine operators are recalibrating around unified control systems that span surface and underground operations.
LiDAR-based perception stacks are consolidating as the dominant environmental mapping standard for underground autonomous vehicles. Hard-rock operators in Western Australia and Chile's Atacama are specifying multi-spectral LiDAR configurations for dust-penetration performance. This sensor standardization is compressing vendor differentiation and forcing automation suppliers to compete on integration speed rather than hardware novelty.
Canada's provincial mining regulators are tightening diesel engine exhaust exposure limits through successive amendments to occupational health standards. British Columbia and Ontario have enacted phased reduction schedules for elemental carbon concentrations in underground atmospheres. Battery-electric loader and haul truck manufacturers are capturing specification priority in new fleet tenders as compliance deadlines approach.
After-sales service unbundling is disrupting traditional OEM captive maintenance arrangements. Large diversified miners in Australia and Chile are insourcing predictive analytics capabilities and procuring replacement components through independent distributors. This procurement fragmentation is most visible in Western Australia's Pilbara iron ore operations, where autonomous haulage fleet operators now source 30-40% of maintenance parts outside manufacturer channels.
Underground Mining Automation Market Segmentation
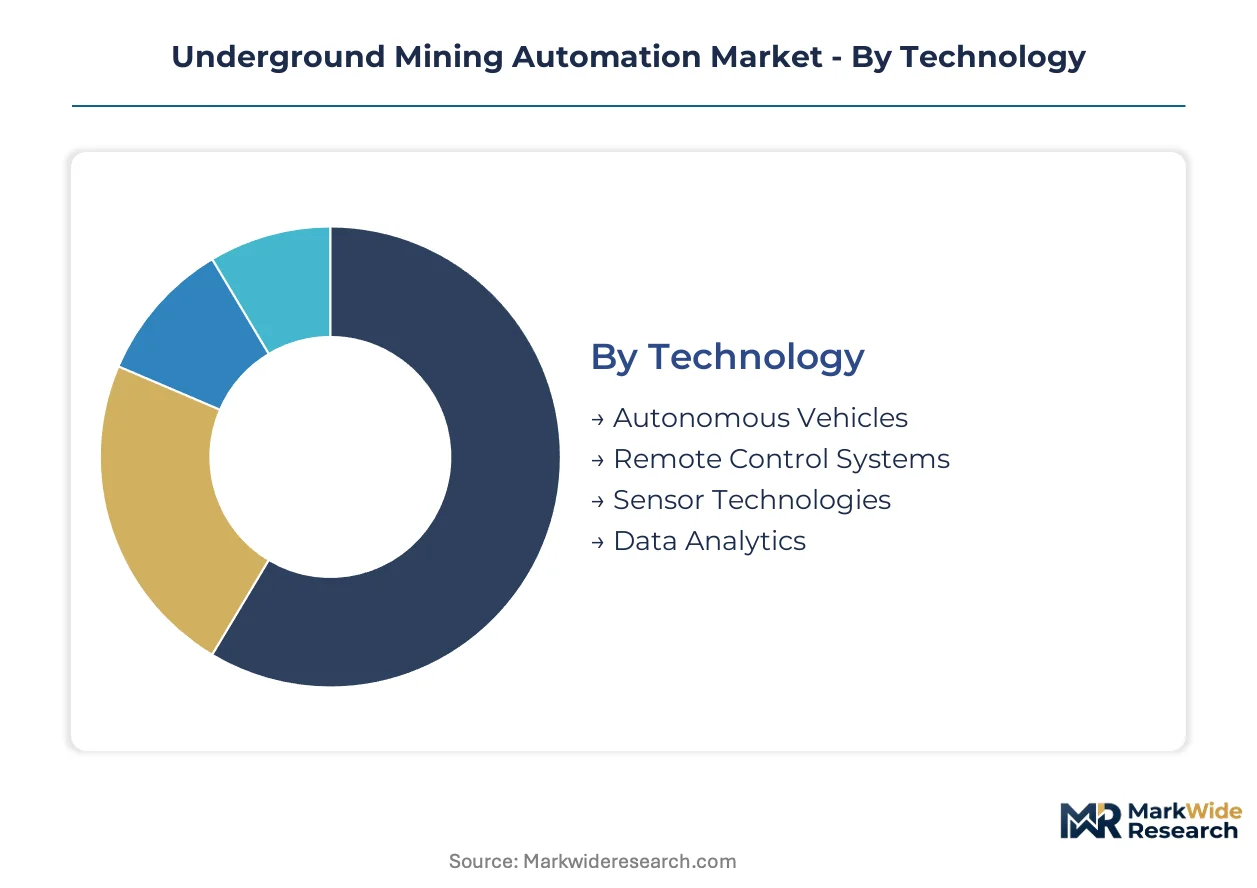
Underground mining automation segments fracture along capital intensity, operational risk exposure, and regulatory compliance depth. Buyers prioritize technology tiers that deliver immediate labor substitution in hazardous zones while meeting ISO 17757 functional safety mandates.
Technology:
Capital allocation splits between fleet-scale autonomous systems and sensor infrastructure that enables predictive maintenance.
- Autonomous Vehicles:Self-driving haul trucks and loaders execute tramming, hauling, and dumping cycles without continuous operator presence in active extraction zones. Australia's Western Australia iron ore belt and Chile's Atacama copper operations command the dominant fleet replacement volumes as depth-driven labor costs escalate.
- Sensor Technologies:Vibration, thermal, and acoustic monitoring arrays feed machine learning models for component failure prediction. South Africa's deep-level gold and platinum operations generate concentrated demand where seismic instability and equipment accessibility constraints amplify downtime costs.
- Remote Control Systems:Tele-remote architectures enable operator stations at surface or refuge bay locations to command underground equipment through hardened fiber-optic networks.
- Data Analytics:Mine management platforms aggregate fleet telemetry, geological surveys, and ventilation data for production optimization.
Volume sits with Autonomous Vehicles; growth tilts toward Sensor Technologies.
Application:
Operational priorities shift between production velocity and regulatory compliance depending on ore body depth and ventilation constraints.
- Material Handling:Autonomous loading, hauling, and dumping cycles in ore passes and decline ramps eliminate operator exposure to groundfall and diesel particulate hazards. Canada's Ontario and British Columbia hard-rock mines are scaling tele-remote loader deployments ahead of provincial diesel exposure limit deadlines.
- Safety Monitoring:Real-time gas detection, ground stability sensing, and personnel tracking systems enforce refuge bay protocols and evacuation triggers. Australia's DNRME ventilation mandates are accelerating capital flows into atmospheric monitoring infrastructure across Western Australia nickel and copper operations.
- Mine Development:Automated drilling and blasting preparation in decline construction and level development drives face advance rates without proportional labor expansion.
- Equipment Maintenance:Condition-based servicing schedules derived from operating hour accumulation and component stress telemetry reduce unplanned stoppages.
Material Handling captures the largest capital commitment; Safety Monitoring is climbing the fastest as regulatory enforcement tightens.
End User:
Procurement authority concentrates with operators who internalize operational risk, while manufacturers and regulators shape specification standards.
- Mining Operators:Integrated diversified miners and single-asset operators specify fleet automation architectures, negotiate service contracts, and absorb compliance liability. BHP, Rio Tinto, and Codelco drive standardization through multi-site deployment mandates that compress vendor qualification timelines.
- Equipment Manufacturers:OEMs including Komatsu, Sandvik AB, and Epiroc AB integrate automation stacks into original builds and retrofit packages, controlling software update pathways and spare part provisioning.
- Safety Inspectors:Third-party certification bodies validate ISO 17757 functional safety claims and provincial electrical safety compliance for battery-electric autonomous vehicles.
- Regulatory Bodies:Australia's DNRME, Canada's provincial mining regulators, and South Africa's Department of Mineral Resources and Energy enforce ventilation, rock-burst, and remote-operation standards that shape equipment certification requirements.
Mining Operators dominate procurement volume; Equipment Manufacturers are gaining specification influence through bundled automation-service contracts.
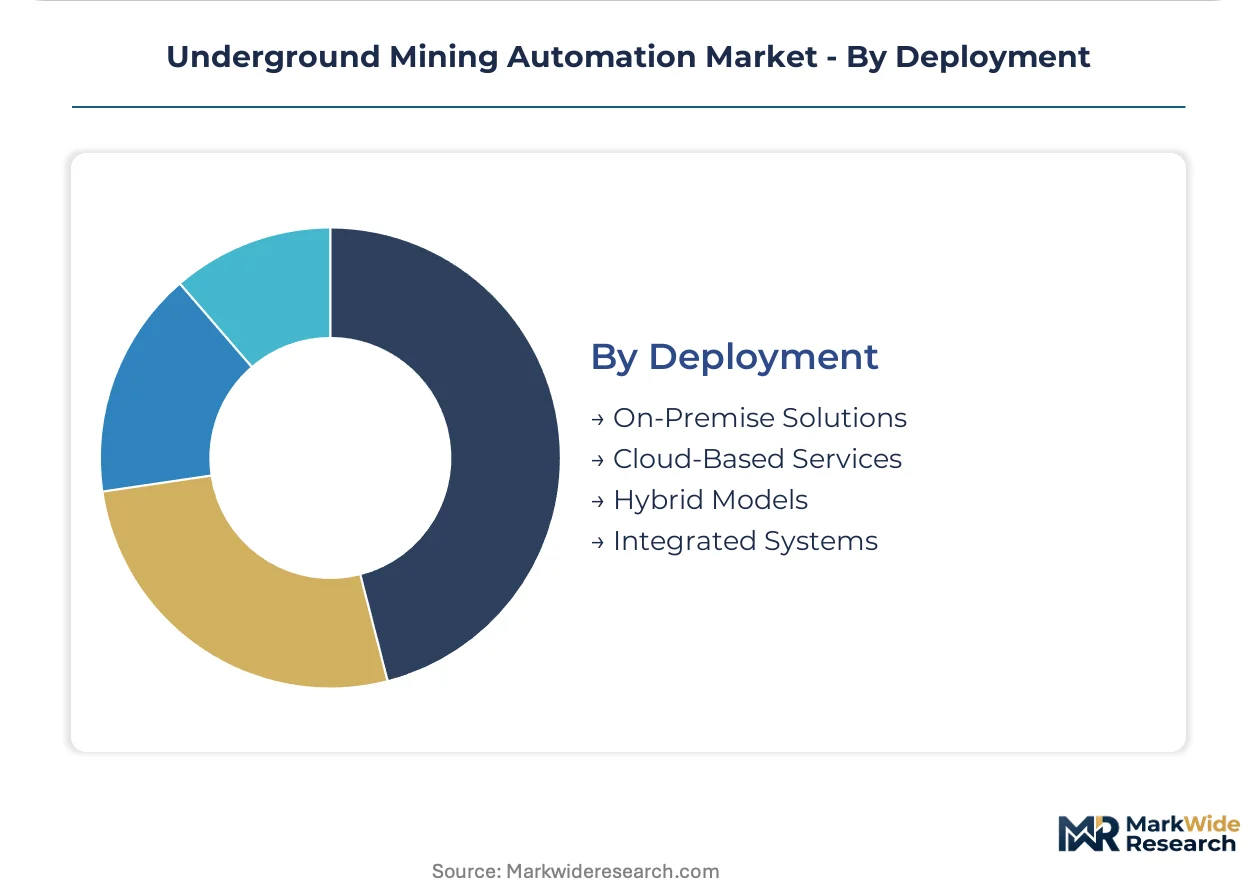
Deployment:
Network architecture choices trade latency performance against capital efficiency and cybersecurity exposure.
- On-Premise Solutions:Hardened underground fiber-optic rings and surface control rooms maintain sub-50 millisecond command latency for collision avoidance and emergency stop protocols. Australia's deep ore bodies in Western Australia and Queensland coal operations specify on-premise stacks where connectivity reliability overrides cloud cost advantages.
- Hybrid Models:Edge computing nodes underground process real-time control loops while surface cloud instances handle fleet optimization analytics and regulatory reporting. Chile's copper majors are piloting hybrid architectures to balance Atacama desert connectivity constraints against centralized data science resource access.
- Cloud-Based Services:Centralized data lakes and machine learning training environments aggregate multi-site telemetry for pattern recognition across dispersed operations.
- Integrated Systems:Unified surface-underground control platforms spanning open-pit and subterranean fleets enable operator mobility and consolidated maintenance protocols.
On-Premise Solutions anchor current deployment; Hybrid Models are gaining share fastest as private 5G underground networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama mining corridor operates as a tax-advantaged extraction zone where copper majors deploy autonomous haulage fleets at depth. Australia's Western Australia iron ore belt and South Africa's platinum-rich Rustenburg basin concentrate capital deployment for remote-operated systems.
Australia
Western Australia's Pilbara and Goldfields regions host the densest concentration of autonomous haul truck deployments worldwide. Australia's DNRME enforces ventilation and remote-operation standards that compel operators to replace manned loaders with tele-remote systems in hazardous zones. The Kalgoorlie-Norseman belt drives fleet replacement cycles as nickel and gold operations extend below 1,000 meters.
Chile
Atacama Desert copper operations scale autonomous drill rig fleets to maintain production from ore bodies exceeding 3,000 meters depth. The country's mining regulator enforces seismic monitoring and refuge bay protocols that accelerate capital flows into ground stability automation. Antofagasta and Calama industrial clusters anchor deployment demand for collision-avoidance sensor networks.
South Africa
Rustenburg and Limpopo platinum-group metal mines face ISO 17757 compliance deadlines that retrofit-ready autonomous haulage demand. The Department of Mineral Resources and Energy maintains distinct rock-burst and ventilation standards that shape equipment certification timelines. Deep-level gold operations around Carletonville and Welkom constrain full autonomy deployment due to seismic prediction limitations.
Canada
Ontario and British Columbia hard-rock mines prioritize tele-remote loader deployments ahead of provincial diesel exposure limit deadlines. Provincial regulators enforce non-harmonized electrical safety standards that fragment battery-electric autonomous vehicle approval pathways. Sudbury and Red Lake mining camps concentrate specification priority for electrified automation platforms.
United States
Nevada's Carlin and Battle Mountain gold trends generate demand for autonomous haulage in open-pit-to-underground transition operations. OSHA and MSHA standards for ground control and ventilation shape equipment validation requirements for deep ore extraction. Elko and Winnemucca logistics hubs support fleet maintenance infrastructure for autonomous vehicle deployments.
Underground Mining Automation Market Competitive Landscape
Japanese and Swedish producers anchor one tier; North American automation specialists hold differentiated positions in control systems integration. Market structure concentrates around diversified industrial conglomerates with captive mining equipment divisions and pure-play automation vendors with hardened underground networking expertise. Strategic archetypes include integrated OEM-automation bundlers, standalone robotics platform developers, and industrial software houses with mining vertical specialization. Competitive moves center on autonomous tramming algorithm certification acceleration and battery-electric powertrain integration partnerships.
Within the integrated OEM tier, Komatsu and Sandvik AB exemplify bundled automation-service contract strategies that compress vendor qualification timelines for deep-ore operators. Epiroc AB occupies a position among Sweden-based specialists focused on narrow-vein drilling automation. These three entities represent contrasting approaches to ISO 17757 functional safety validation: conglomerate-scale certification resources versus specialist precision-engineering positioning.
| Leading Market Players |
|---|
| Komatsu |
| ABB |
| Sandvik AB |
| Hexagon |
| Rockwell Automation |
| Epiroc AB |
| Hitachi Construction Machinery |
| Autonomous Solutions |
| Caterpillar |
| Others |
Value Network & Pricing Analysis
Hardened fiber-optic cable and private 5G infrastructure costs cascade through autonomous haulage system pricing tiers, compressing margins for mid-tier suppliers while premium vendors capture ISO 17757 certification premiums in Australia's Western Australia iron ore belt and Chile's Atacama copper corridor.
Pricing Analysis
Short lead-time premiums for ISO 17757-certified autonomous tramming algorithms command substantial markups over standard delivery schedules. Contract-based long-term offtake agreements dominate, with price differentiation resting on certification grade and after-sales service bundling. Cost compression in tele-remote loader segments is intensifying because Canadian provincial regulators are accelerating diesel exposure compliance deadlines. Junior mining operators exhibit highest price sensitivity; integrated majors like BHP and Codelco absorb premium pricing for bundled automation-service contracts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Australia's Pilbara operators and Chile's copper majors, bypassing independent distributors for fleet-scale deployments. Manufacturing concentrates in Japan, Sweden, and Finland for autonomous vehicle platforms; sensor component fabrication centers on Germany and South Korea. Supply chains draw from lithium-ion battery cells, LiDAR perception modules, and hardened industrial networking gear. Single-source vulnerability in semiconductor content for collision-avoidance systems poses structural risk as automotive and mining sectors compete for foundry allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground mining automation sits in a technology-transition phase where battery-electric powertrains displace diesel-mechanical platforms, driven by Canada's provincial exhaust exposure limits and Australia's DNRME ventilation mandates.
For Market Incumbents: Lock in certification acceleration pathways for ISO 17757 functional safety validation to outpace 18-24 month third-party timelines threatening revenue recognition. Deepen vertical integration into predictive maintenance software stacks before independent analytics vendors capture aftermarket service contracts from expiring OEM agreements. Battery-electric powertrain partnerships represent the critical lever for defending specification priority in Canadian and Australian fleet tenders. For New Entrants and Emerging Players: Cloud-based subscription routes to predictive analytics platforms offer lowest friction entry into South Africa's Rustenburg and Limpopo platinum belt, where autonomous haulage penetration remains constrained by shaft geometry. Target South African deep-level gold operations with seismic monitoring false-positive reduction tools, addressing the 15% failure rate blocking full autonomy deployment. Partner with independent maintenance distributors in Western Australia's Pilbara to bypass incumbent OEM captive service networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor automation software specialists with hardened underground networking expertise in Canada's Sudbury and Red Lake mining camps, where provincial regulatory divergence fragments equipment approval pathways. Long-term viability centers on vendors capable of spanning surface-underground unified control platforms as operators consolidate fleet management. Watch private 5G underground network maturity as inflection indicator for hybrid cloud-edge deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17757 Certification Acceleration | Compresses 18-24 month validation timelines threatening revenue recognition for algorithm suppliers. |
| Battery-Electric Powertrain Integration | Captures specification priority in Canadian provincial tenders ahead of diesel exposure deadlines. |
| Predictive Maintenance Platform Development | Targets uncaptured margin pools as OEM service contracts expire across Australian iron ore operations. |
| Private 5G Underground Network Deployment | Enables hybrid cloud-edge architectures balancing Atacama connectivity constraints against analytics access. |
| Unified Surface-Underground Control System | Supports operator mobility and consolidated maintenance protocols for diversified miners like Rio Tinto. |
Research Methodology
Trade publications, equipment manufacturer technical documentation, and mining operator procurement disclosures formed the secondary backbone, cross-referenced against regulatory filings from Australia's DNRME, Canada's provincial mining regulators, and South Africa's Department of Mineral Resources and Energy. Primary interviews with automation engineering directors, mine operations managers, and aftermarket service heads at Western Australian and Chilean copper operations supplied deployment timeline validation. Bottom-up fleet replacement cycle analysis and top-down capital expenditure triangulation anchored market sizing.
Bottom-up modeling traced autonomous vehicle, sensor technology, and remote control system volumes through identified operator procurement pipelines. Segmentation dimensions spanned technology tier, application intensity, deployment architecture, and ore body depth category. CAGRs derived from regression against historical fleet automation adoption curves in comparable extraction industries. Key inputs included provincial diesel exposure limit phase-out schedules and ISO 17757 compliance deadline clustering.
The model holds under stable regulatory enforcement trajectories; deviation in provincial certification harmonization or seismic prediction accuracy breakthroughs would shift deployment velocity assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Drilling Rigs Market