
 Underground Mining Market | 2026-2036
Underground Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Mining Market Outlook
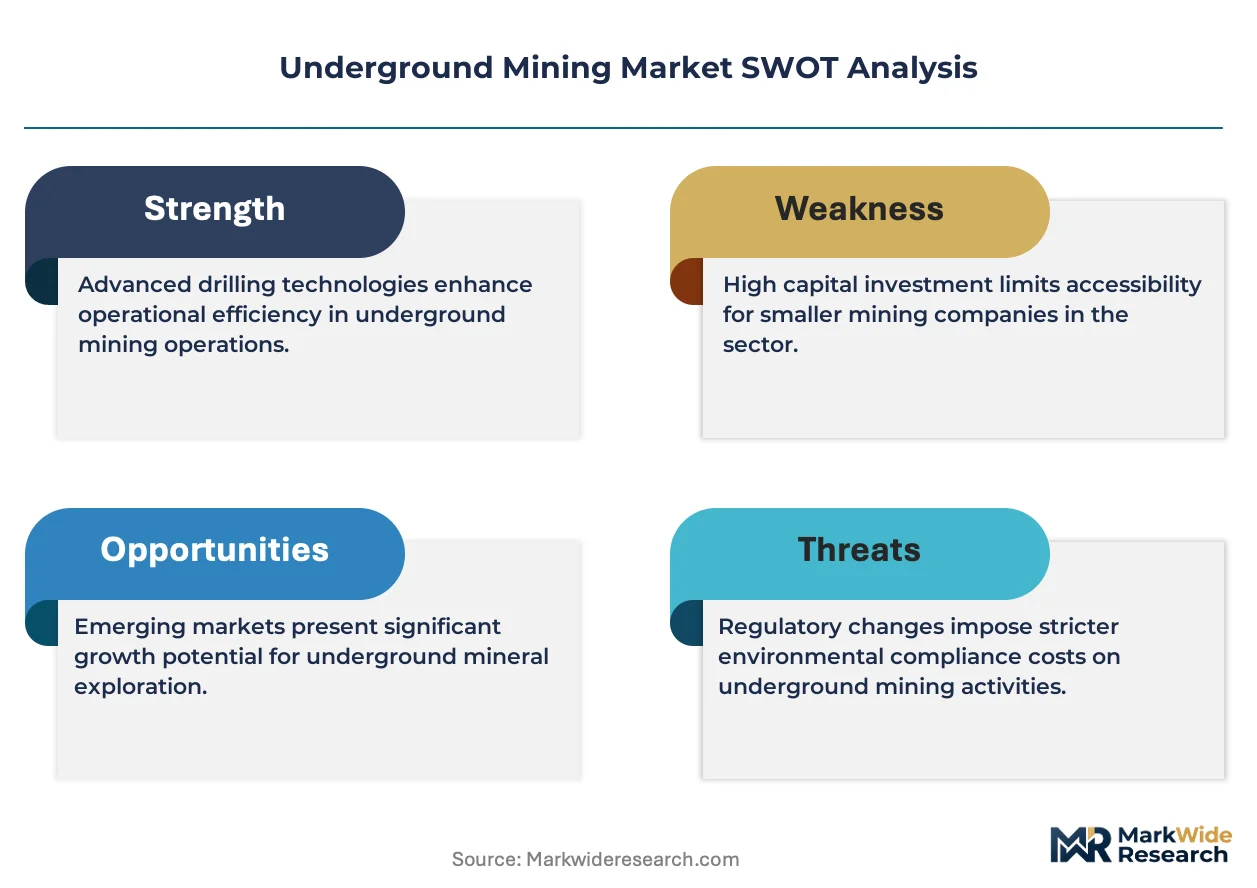
Project finance and equipment leasing is tilting competitive dynamics toward operators with balance-sheet flexibility rather than pure asset ownership. Komatsu Ltd. leverages its Joy Global heritage in hard-rock cutting systems to anchor positions in longwall and room-and-pillar operations. Sandvik AB sustains technology leadership through its AutoMine platform for autonomous loader and truck fleets. Epiroc AB differentiates via electrification-focused R&D, targeting zero-emission underground haulage architectures.
Underground mining encompasses the extraction of ore, coal, and industrial minerals through shafts, declines, and adits at depths typically exceeding 50 meters below surface level, employing drilling, blasting, mechanical cutting, and continuous haulage systems to maintain production rates while managing ground support, ventilation, and dewatering challenges. Drilling equipment and haulers command the largest installed base and replacement parts revenue pools, reflecting the high-wear nature of blasthole production and ore transport in confined stoping environments. Automation technology represents the fastest-expanding segment as mining companies pursue productivity gains through teleremote and fully autonomous loader-truck cycles that reduce exposure to seismic and ventilation hazards.
The US Mine Safety and Health Administration enforces respiratory protection and ground control standards that shape equipment ventilation and canopy designs, while ISO 19434 classification of mining accidents informs incident-response protocols adopted by major operators. Australia's state-based mine safety regulators and Chile's Superintendencia de Minería impose progressively stricter automation and worker-isolation requirements that filter into procurement specifications. Stakeholders must weigh electrification capex against diesel-phaseout timelines and assess which technology suppliers can deliver interoperable autonomous fleets without locking operations into single-vendor architectures.
Market Dynamics
Capital redeployment toward teleremote and fully autonomous underground fleets is compressing traditional equipment replacement cycles while reshaping vendor-customer relationships around interoperability guarantees rather than standalone hardware sales.
Growth Catalysts
- Copper-intensive electrification:Electric vehicle battery supply chains are pulling base metals extraction deeper in Chile, Peru, and Australia, expanding longwall and room-and-pillar operations.
- Australia's Mines Safety and Inspection Act:Automation mandates from state regulators are accelerating fleet modernization programs and creating captive demand for remote-controlled loader-truck architectures.
- Hard-rock mechanical cutting:Continuous miner adoption in narrow vein operations is displacing drill-and-blast cycles, reducing ventilation loads and ground support requirements in deep tabular deposits.
Market Restraints
- Steel and rare earth input volatility:Cutting tool alloys and permanent magnet supply concentration in China creates margin pressure for equipment OEMs during commodity spikes.
- Single-vendor fleet lock-in:Proprietary autonomous command protocols from dominant technology suppliers fragment interoperability, raising switching costs for multi-site operators.
- Groundwater management capex:Deepening operations below 1,000 meters in the Witwatersrand and Kolar belts requires dewatering infrastructure that consumes 15-25% of site development budgets.
Strategic Opportunities
- Canada's provincial automation incentives:Ontario and British Columbia regulators are offering accelerated depreciation for zero-emission underground haulage, creating first-mover advantages for battery-electric fleet suppliers.
- Battery-electric LHD convergence:Integration of fast-charge infrastructure with autonomous tramming systems opens greenfield sites previously excluded by diesel ventilation constraints.
- Aftermarket parts platformization:Independent remanufacturing networks in Western Australia and Nevada are capturing replacement component demand outside OEM service channels.
Industry Challenges
- Autonomous systems integration:Retrofitting teleremote capabilities onto legacy diesel fleets requires CAN bus architecture overhauls that extend commissioning timelines by 8-14 months.
- Seismic risk engineering talent:Shortages in ground control specialists and mine ventilation engineers are delaying automation certification for deep-level operations in South Africa and Canada.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Mining Market |
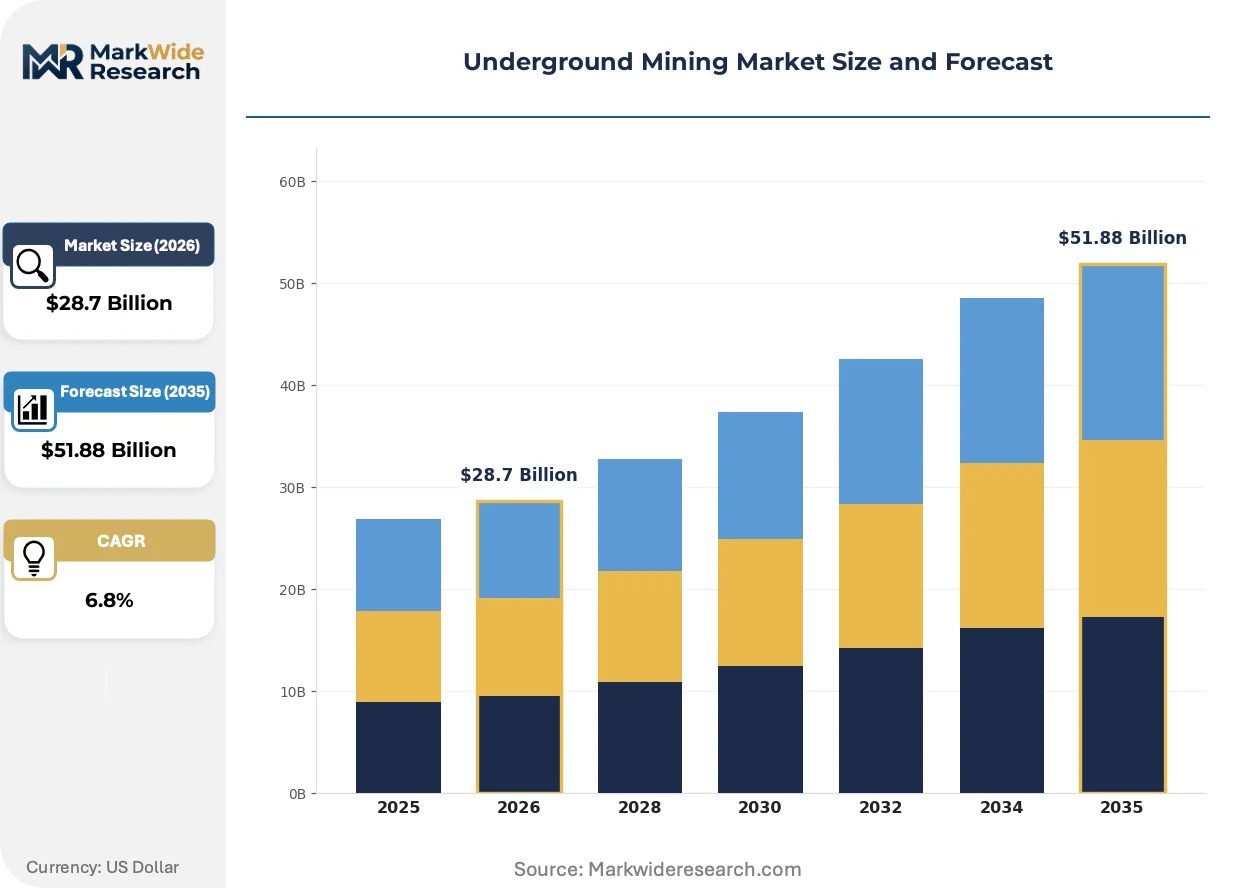
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Equipment, Loaders, Haulers, Crushing Equipment Technology: Automation, Remote Control, Surface Mining Integration, Monitoring Systems Application: Mineral Extraction, Coal Mining, Metal Mining, Tunneling End User: Mining Companies, Contractors, Operators, Service Providers |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Sandvik AB, Epiroc AB, Hitachi Construction Machinery, AB Volvo, Boart Longyear, J.H. Fletcher & Co., SMT Scharf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Mining Market Strategic Shifts
Electrification and autonomous tramming are converging to redefine underground haulage economics, while regulatory pressure on diesel particulate exposure accelerates technology substitution timelines.
Diesel-electric powertrain architectures for underground loaders and trucks are hybridizing across multiple voltage platforms, with 600V and 1000V systems competing for standardization. Tier 1 hard-rock operators in Canada and Sweden are piloting dual-mode fleets that switch between battery and tethered operation. This flexibility is hybridizing procurement specifications, compressing the distinction between pure-electric and diesel-mechanical equipment categories.
Chile's Superintendencia de Minería has imposed progressively stricter worker isolation requirements that mandate line-of-sight exclusion zones for autonomous equipment operation. The regulation forces open-pit vendors to adapt underground-certified systems and accelerates cross-segment technology transfer. Copper-gold operators in the Atacama are responding by consolidating fleet procurement under single autonomous platform providers to simplify compliance auditing.
Equipment-as-a-service contracting is displacing traditional capex-heavy ownership models among mid-tier base metal producers. Sandvik and Epiroc are unbundling hardware from maintenance and productivity guarantees, capturing recurring revenue through availability-based fee structures. This shift is most visible in Western Australian nickel and Western Canadian potash operations where balance-sheet-constrained operators prioritize cash flow predictability over asset control.
Underground Mining Market Segmentation
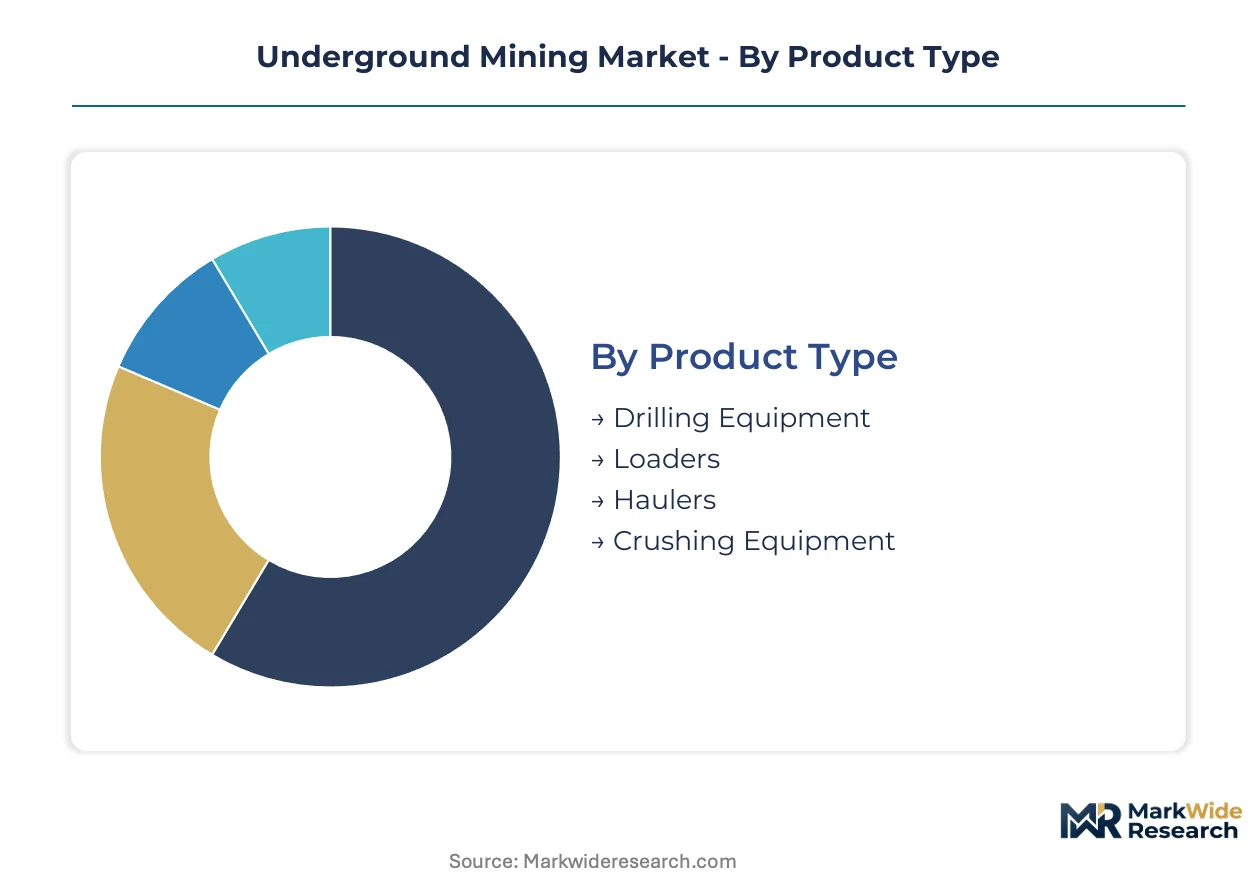
Underground mining equipment procurement follows distinct technical and commercial logics across product categories, automation readiness levels, and operational applications. Segmentation reveals where capital deployment concentrates and which technology trajectories are reshaping vendor-customer relationships.
Product Type:
Equipment selection spans the full extraction workflow from face penetration through ore transport to size reduction at shaft bottom.
- Drilling Equipment:Blasthole jumbos and production drills with hydraulic or electric powertrains penetrate rock faces at 51-127mm diameters. Demand clusters in Chilean porphyry copper operations where Australia's Mines Safety and Inspection Act ventilation requirements are driving electric-hydraulic substitutions for diesel rigs.
- Loaders:LHD (load-haul-dump) units with 6-21 tonne bucket capacities perform mucking in confined stoping environments. Canadian potash and Western Australian nickel operations are standardizing on battery-electric variants to eliminate diesel particulate exposure in exhaust-restricted drifts.
- Haulers:Articulated underground trucks with 30-60 tonne payloads move ore from drawpoints to crushers. Sandvik and Epiroc are capturing fleet standardization contracts through interoperability guarantees for autonomous tramming cycles.
- Crushing Equipment:Mobile and semi-mobile jaw, cone, and gyratory units reduce run-of-mine material at shaft stations or decline portals. Modular designs dominate greenfield projects in Peru's Andean copper belt where rapid relocation between ore zones matters.
The dominant share belongs to Drilling Equipment, while Loaders are closing the gap fastest.
Technology:
Capital allocation tilts toward systems that remove personnel from hazard zones while maintaining production continuity.
- Automation:Fully autonomous loader-truck fleets with LiDAR localization and centralized traffic management. Rio Tinto's Koodaideri and BHP's Olympic Dam deployments in Australia demonstrate 15-20% productivity gains from continuous operation without shift changes.
- Remote Control:Teleremote operation from surface control rooms via fiber or 5G backhaul. Chile's Superintendencia de Minería worker-isolation mandates are accelerating adoption at Codelco's El Teniente and Collahuasi divisions.
- Surface Mining Integration:Unified fleet management platforms spanning open-pit and underground operations. Glencore's Sudbury basin operations in Canada consolidate command centers for nickel-copper complexes with mixed surface-underground profiles.
- Monitoring Systems:Seismic, ventilation, and ground support sensors with predictive analytics. South Africa's deep-level gold producers deploy microseismic arrays to manage rockburst risks below 3,000 meters.
Automation commands the largest installed base investment, yet Remote Control is expanding most quickly in jurisdictions with phased regulatory timelines.
Application:
Deposit geology and commodity economics dictate equipment specifications across extraction contexts.
- Mineral Extraction:Potash, salt, and trona mining using continuous miners or longwall systems in flat-lying tabular deposits. Saskatchewan's potash corridor and Spain's K+S operations prioritize low-profile equipment for seam heights under 3 meters.
- Coal Mining:Longwall and room-and-pillar operations in metallurgical and thermal seams. Australia's Bowen Basin longwall installations deploy 400-tonne shield supports with automated shearer ranging arms.
- Metal Mining:Hard-rock base and precious metal extraction via sublevel stoping, cut-and-fill, or block caving. Sweden's Kiruna iron ore mine operates the world's largest autonomous underground haulage fleet at 1,365 meters depth.
- Tunneling:Civil infrastructure and mine development headings using roadheaders or drill-and-blast methods. Switzerland's Gotthard Base Tunnel legacy equipment suppliers now target mining development applications.
Metal Mining absorbs the dominant equipment procurement volume, though Tunneling is gaining share fastest as infrastructure-linked mining development accelerates.
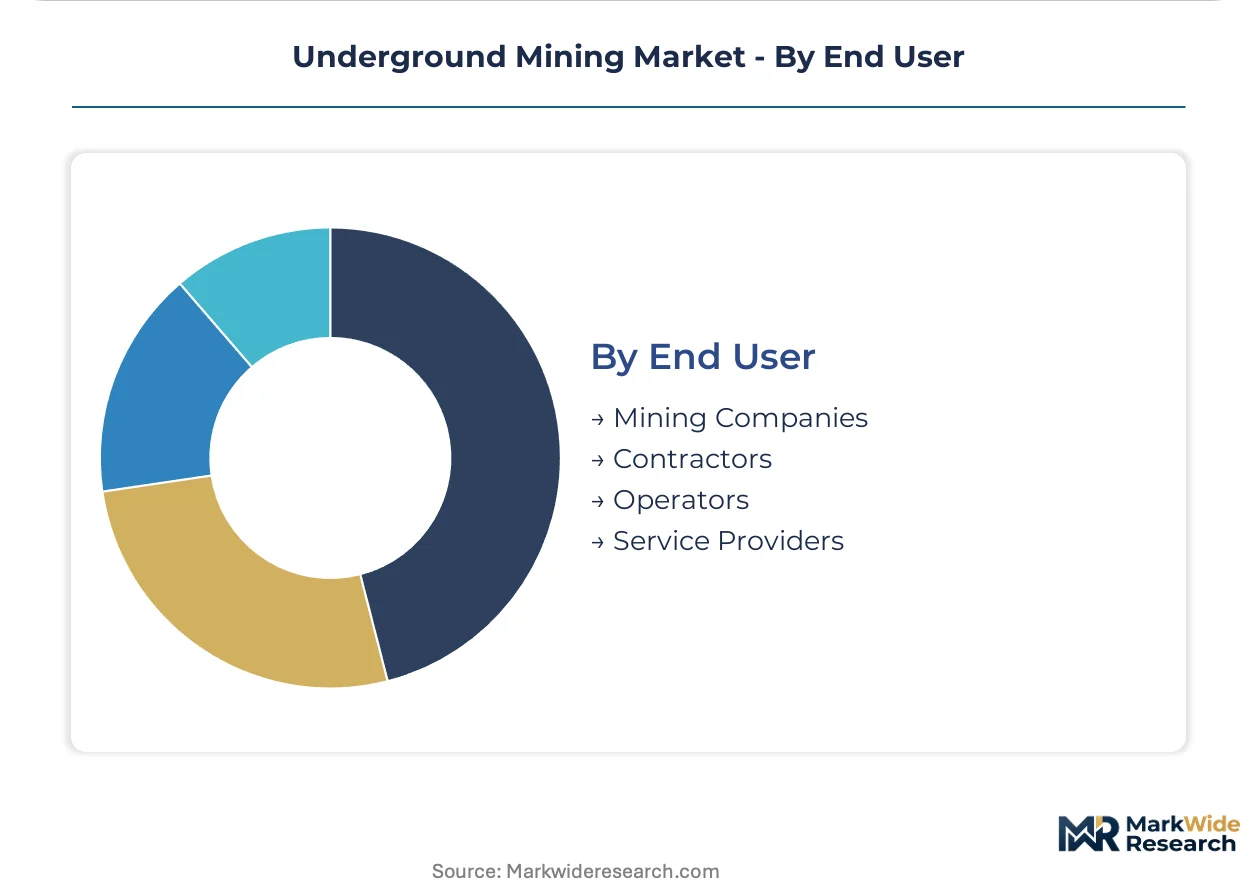
End User:
Procurement authority and risk allocation vary sharply across organizational archetypes.
- Mining Companies:Integrated majors with captive engineering and maintenance capabilities. BHP, Vale, and Glencore standardize fleet specifications across multi-site portfolios to capture scale economies in parts and training.
- Contractors:Specialized underground mining services firms operating on cost-per-tonne or fixed-schedule contracts. Australia's Byrnecut and Canada's Redpath negotiate equipment-as-a-service terms to preserve balance-sheet flexibility.
- Operators:Joint ventures and special-purpose vehicles with single-asset focus. Chilean copper-gold JVs in the Atacama consolidate procurement under single autonomous platform providers to simplify compliance.
- Service Providers:Equipment maintenance, rebuild, and technology integration specialists. Nevada and Western Australia host independent remanufacturing networks capturing replacement component demand outside OEM channels.
Mining Companies retain the dominant procurement share, while Contractors are closing the gap fastest through outsourcing of fleet ownership and maintenance risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated majors and specialized contractors concentrate procurement authority in mining jurisdictions with strict automation mandates and copper-intensive electrification demand. Chile, Australia, Canada, South Africa, and Peru host the deepest capital redeployment toward autonomous underground fleets.
Chile
Copper-gold operators in the Atacama Desert expand block caving and sublevel stoping operations to feed electric vehicle battery supply chains. The Superintendencia de Minería imposes progressively stricter worker isolation requirements that mandate line-of-sight exclusion zones for autonomous equipment. Codelco's El Teniente and Collahuasi divisions anchor fleet standardization contracts under single autonomous platform providers to simplify compliance auditing.
Australia
Western Australian nickel and Queensland metallurgical coal operations drive replacement demand for battery-electric LHD variants. The Mines Safety and Inspection Act ventilation requirements accelerate electric-hydraulic substitutions for diesel drilling rigs across the Pilbara and Kalgoorlie districts. Rio Tinto's Koodaideri and BHP's Olympic Dam demonstrate productivity gains from fully autonomous loader-truck fleets with continuous operation.
Canada
Ontario's Sudbury basin nickel-copper complexes and Saskatchewan's potash corridor prioritize low-profile equipment for seam heights under three meters. Provincial regulators in Ontario and British Columbia offer accelerated depreciation for zero-emission underground haulage, creating first-mover advantages for battery-electric fleet suppliers. Glencore consolidates command centers for mixed surface-underground operations across the basin.
South Africa
Deep-level gold producers below three thousand meters deploy microseismic arrays to manage rockburst risks in the Witwatersrand belt. The country's national mine safety regulator enforces ground control standards that shape automation certification timelines for ultra-deep operations. Dewatering infrastructure consumes substantial portions of site development budgets in the Kolar-equivalent depths.
Peru
Andean copper belt operations in the Ancash and Apurímac regions expand longwall and room-and-pillar architectures for porphyry extraction. The national mining regulator aligns procurement specifications with Chilean automation standards to facilitate cross-border fleet interoperability. Southern Copper and Buenaventura anchor greenfield project development with modular crushing equipment at shaft stations.
Underground Mining Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that tilts toward consolidated fleet procurement by integrated majors. Three to four technology suppliers capture dominant positions in autonomous command systems and battery-electric powertrains. Strategic archetypes include full-line mining equipment conglomerates, hard-rock cutting specialists, and electrification-focused technology vendors. Competitive moves center on interoperability guarantees for multi-site operators and equipment-as-a-service contracting to displace traditional capex-heavy ownership models.
Within the full-line equipment tier, Caterpillar Inc. and Komatsu Ltd. represent integrated majors with heritage positions in hard-rock mechanical cutting systems. Sandvik AB and Epiroc AB occupy the technology-specialist vector, with Sandvik anchoring autonomous fleet positions through centralized traffic management platforms and Epiroc exemplifying electrification-focused R&D targeting zero-emission haulage architectures. Hitachi Construction Machinery and AB Volvo sit within the diversified industrial conglomerate archetype, leveraging construction equipment cross-over capabilities.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Sandvik AB |
| Epiroc AB |
| Hitachi Construction Machinery |
| AB Volvo |
| Boart Longyear |
| J.H. Fletcher & Co. |
| SMT Scharf GmbH |
| Others |
Value Chain & Pricing Dynamics
Jiangsu Province's rare earth processing cluster controls permanent magnet supply for electric drivetrains, concentrating pricing power among integrated OEMs while forcing tier-2 suppliers into fixed-price contracts with quarterly steel indexation.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper and steel scrap indexation dominate fleet procurement agreements between Australian nickel operators and equipment vendors. Pricing stratifies across autonomous-certified, electric-hydraulic, and legacy diesel-mechanical tiers based on interoperability guarantees and ventilation compliance certification. Cost compression in battery-electric LHD segments is intensifying because fast-charge infrastructure bundling standardizes powertrain specifications. Contractor-operated fleets in Western Australia exhibit highest price sensitivity due to cost-per-tonne contract structures, while integrated majors at Codelco's Chilean divisions prioritize availability guarantees over unit economics.
Supply Chain Analysis
Export controls on high-performance permanent magnets and LiDAR sensor arrays under China's dual-use technology regulations constrain flows to autonomous mining equipment assemblers in Sweden and Finland. Manufacturing concentrates in China, Germany, and Japan for cutting tool alloys, battery cells, and hydraulic systems respectively. The supply chain draws from cobalt concentrates in the DRC, lithium carbonate from Chile's Atacama salares, and high-grade steel from South Korean integrated mills. Single-source vulnerability in rare earth separation creates procurement risk for zero-emission fleet suppliers. Distribution runs through OEM-owned service depots in Perth, Santiago, and Toronto rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground mining equipment demand tracks copper price cycles with a 12-18 month lag; the current electrification infrastructure buildout sustains replacement demand even through base metal price corrections.
For Market Incumbents: Build switching-cost moats through proprietary autonomous traffic management protocols that lock multi-site operators into single-vendor architectures. Sandvik and Epiroc should accelerate interoperability certification for third-party battery-electric LHD retrofits to preempt independent integrators. Defensive capacity expansion in Ontario and Western Australia captures provincial automation incentives before competitor localization. For New Entrants and Emerging Players: Battery-electric haulage retrofit kits for legacy diesel fleets in South Africa's deep-level gold operations represent the most penetrable entry point given seismic risk delays in full automation certification. Aftermarket remanufacturing networks in Nevada and Western Australia offer white-space acquisition targets outside OEM service channels. Go-to-market positioning as interoperability-agnostic integrators avoids direct confrontation with Sandvik's AutoMine platform dominance. For Investors and Strategic Acquirers: Long-term, this sits as a electrification infrastructure play because copper-intensive battery supply chains and diesel-phaseout mandates structurally expand the addressable market for zero-emission underground fleets. Acquisition targets should feature captive fast-charge infrastructure IP or exclusive service relationships with tier-1 base metal producers. Watch for Chile's Superintendencia de Minería extending worker-isolation mandates to open-pit operations as signal for accelerated cross-segment technology transfer.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Fleet Interoperability Certification | Unlocks multi-vendor procurement for BHP's Olympic Dam and Codelco's El Teniente without platform lock-in. |
| Battery-Electric Retrofit Program | Captures South African deep-level gold demand delayed by seismic automation certification timelines. |
| Fast-Charge Infrastructure Partnership | Enables greenfield site development previously excluded by diesel ventilation constraints in Canadian potash. |
| Aftermarket Remanufacturing Acquisition | Secures replacement parts revenue outside OEM channels in Western Australia's nickel corridor. |
| Provincial Incentive Localization | Positions for Ontario and British Columbia accelerated depreciation on zero-emission haulage deployments. |
Study Parameters
The analysis maps autonomous haulage systems, battery-electric powertrains, mechanical cutting equipment, and aftermarket services, each validated through mine engineering directors, equipment procurement managers, and autonomous technology integrators. Primary interviews with underground operations executives at tier-1 copper and nickel producers combined with secondary validation from SEC 10-K filings, Chile's Superintendencia de Minería regulatory databases, and Australia's Mines Safety and Inspection Act compliance records. Bottom-up unit economics from individual mine sites triangulated against top-down capex forecasts from major mining houses.
Assumptions held copper prices within historical trading bands while varying automation adoption rates across regulatory jurisdictions. The projection framework models equipment replacement cycles by product type, technology readiness tier, deposit geology, and end-user procurement authority. CAGRs derive from installed base turnover analysis and greenfield project pipelines. Forecast inputs include provincial incentive program durations, diesel particulate exposure limits, and battery energy density improvement trajectories.
Macroeconomic conditions sit as an overlay; deviation in Chinese rare earth export quotas or South African electricity grid stability would shift the trajectory. Material shifts in Chilean or Australian automation mandate timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Global Dozers Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Mining Drill Market
Mining Equipment
Crawler Drill Rig Market