
 Impact Crusher Market | 2026-2036
Impact Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Crusher Market Analytics
Aftermarket maintenance contracts and remote monitoring subscriptions is consolidating how OEMs capture lifetime value from installed crusher bases. Metso Corporation leverages its global service network to lock in multi-year wear parts agreements. Sandvik AB anchors its competitiveness through digital diagnostics bundled with original equipment sales. Terex Corporation competes by extending mobile crusher uptime guarantees through captive technician deployments.
An impact crusher is a mechanical reduction device that fractures feed material through high-velocity collision with rigid blow bars or anvils, typically processing material between 100 mm and 1,500 mm feed size down to quarry-specified gradations. The machine serves primary and secondary comminution duties across hard rock quarrying, construction demolition, and metallic ore preparation. Horizontal shaft impactors dominate mature quarrying installations where abrasive limestone and granite applications demand predictable wear economics. Mobile impact crushers represent the fastest-growing product configuration as contractors prioritize fleet flexibility across dispersed job sites. Electric drive technology is gaining share in stationary installations where grid access and carbon accounting favor motor-driven rotors over diesel-hydraulic powertrains.
EPA emissions standards and OSHA silica exposure limits shape crusher enclosure and dust suppression requirements in the United States, while China's MEE enforces ambient air quality thresholds that restrict uncontrolled fugitive dust from aggregate processing. The EU F-Gas Regulation and REACH compliance frameworks further constrain hydraulic system refrigerants and lubricant chemistries imported into European markets. Stakeholders must weigh electrification roadmaps against residual diesel-hybrid demand in remote mining frontiers where grid extension remains uneconomical.
Market Dynamics
Electrification of crushing circuits is forcing capital reallocation across quarrying and mining operations, as diesel-hydraulic systems face carbon accounting pressure and grid-access economics improve in mature extraction zones.
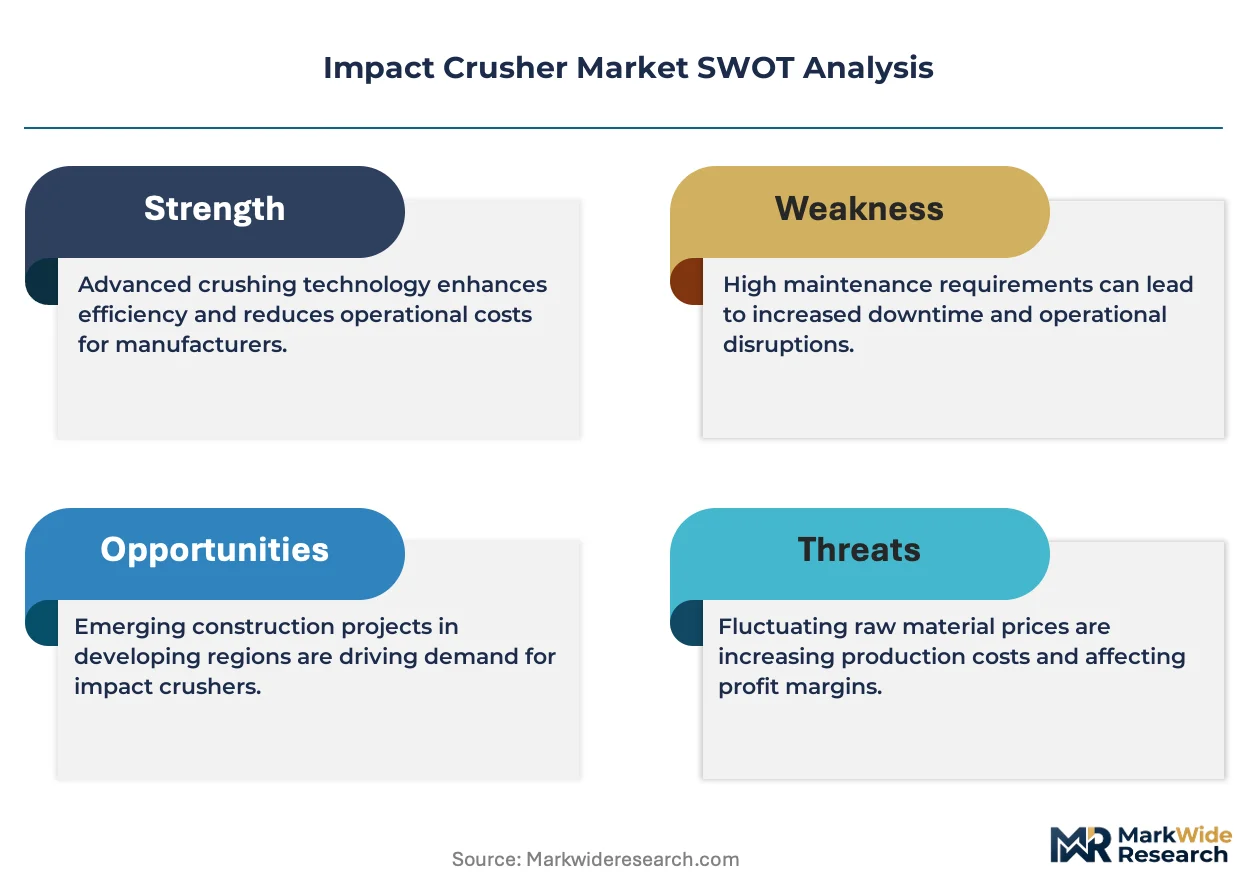
Growth Catalysts
- EPA Particulate Standards:Stricter emissions ceilings under EPA and MEE mandates are compelling enclosed crushing circuit upgrades, accelerating replacement cycles for open-air installations in the United States and China.
- Lower-Grade Ore Processing:Mining operators in Australia and Brazil are expanding mobile crusher fleets to economically process declining head grades, sustaining equipment demand despite commodity price volatility.
- Digital Diagnostics Bundling:Remote monitoring subscriptions are capturing lifetime value from installed bases, shifting OEM revenue toward recurring service architectures.
Market Restraints
- High-Manganese Steel Volatility:Blow bar and liner input costs swing with ferroalloy pricing, compressing margins for wear parts suppliers and forcing pass-through negotiations with end-users.
- Supply Concentration in China:Foundry capacity for crusher wear components clusters in Shandong and Henan provinces, creating geographic vulnerability to energy rationing or export control shifts.
- Substitution by Gyratory Systems:Hard rock mining above 1,500 mm feed size favors gyratory primary crushers, capping impact crusher addressable share in large-scale metallic ore preparation.
Strategic Opportunities
- Western China Infrastructure:Quarrying activity in Sichuan and Xinjiang outpaces coastal market saturation, creating demand pockets for mobile crushing fleets serving rail and highway construction.
- Construction Demolition Recycling:Circular economy mandates in the European Union are accelerating concrete and asphalt reuse, expanding secondary impact crusher deployment in urban material recovery facilities.
- EU F-Gas Phase-Down:Hydraulic system refrigerant restrictions are creating upgrade windows for electric drive retrofits in stationary installations across Germany and France.
Industry Challenges
- Rotor Balancing Expertise Gap:Specialized technicians for high-speed impactor maintenance are scarce in remote mining frontiers, constraining uptime guarantee fulfillment.
- Multi-Tier Certification Timelines:CE marking convergence with ISO 21873 mobile machinery standards delays product launches for European contractors.
- Legacy Control System Integration:Site-wide automation retrofits require protocol bridging between proprietary crusher PLCs and modern SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Crusher Market |
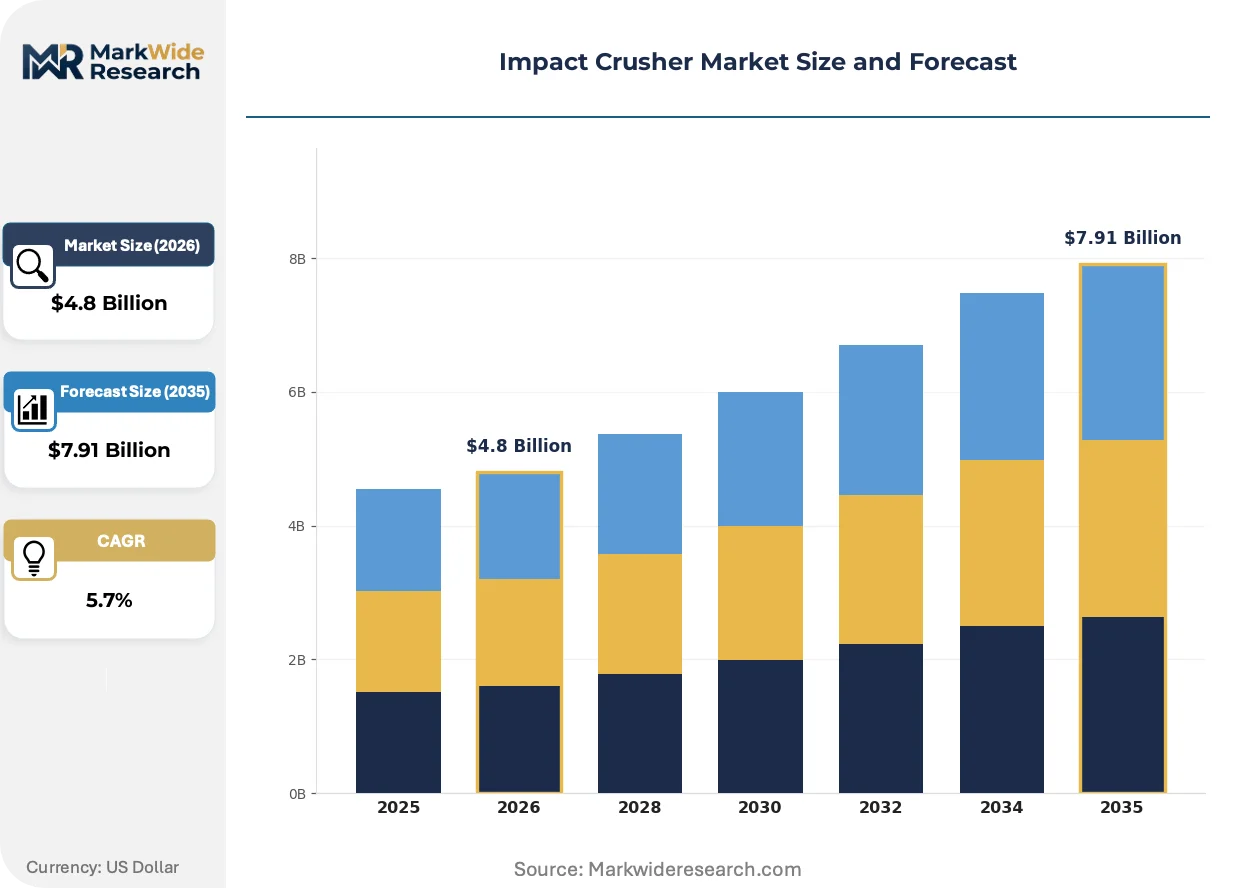
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Shaft Impactor, Vertical Shaft Impactor, Mobile Impact Crusher, Stationary Impact Crusher End User: Mining, Construction, Recycling, Aggregate Technology: Pneumatic, Hydraulic, Electric, Mechanical Application: Quarrying, Demolition, Road Construction, Metal Recycling |
| Companies Covered | Metso Corporation, Sandvik AB, Terex Corporation, Astec Industries, Weir Group, Hazemag, McCloskey International, Thyssenkrupp, Shanghai Shibang Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Crusher Market Evolving Landscape
Active rotor designs and intelligent feed control are compressing energy intensity per ton processed, while regulatory chemistry constraints and procurement model evolution reshape how crushing solutions are specified and financed.
Variable frequency drive technology is absorbing excess kinetic energy during non-peak feed conditions, reducing electrical draw by modulating rotor speed against material density. Quarry operators in Germany and Japan are retrofitting existing horizontal shaft impactors with this capability to meet site-level carbon targets. The technology is absorbing demand from conventional fixed-speed motor configurations, particularly in grid-connected installations where demand charges dominate operating economics.
REACH compliance frameworks are restricting lubricant additive packages and hydraulic fluid chemistries imported into European markets, forcing reformulation of bearing greases and seal compounds. Crusher OEMs serving EU contractors must now certify entire fluid systems against substance of very high concern thresholds. Mobile crusher lines destined for France and Italy face extended homologation cycles as lubricant portfolios are requalified.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-size aggregate producers seeking to offload residual value risk. Tiered service agreements now bundle wear parts, remote monitoring, and technician deployment into per-ton processed pricing. This shift is most visible in the United Kingdom and Netherlands, where contractor balance sheet constraints favor operational expenditure classification.
Impact Crusher Market Segmentation
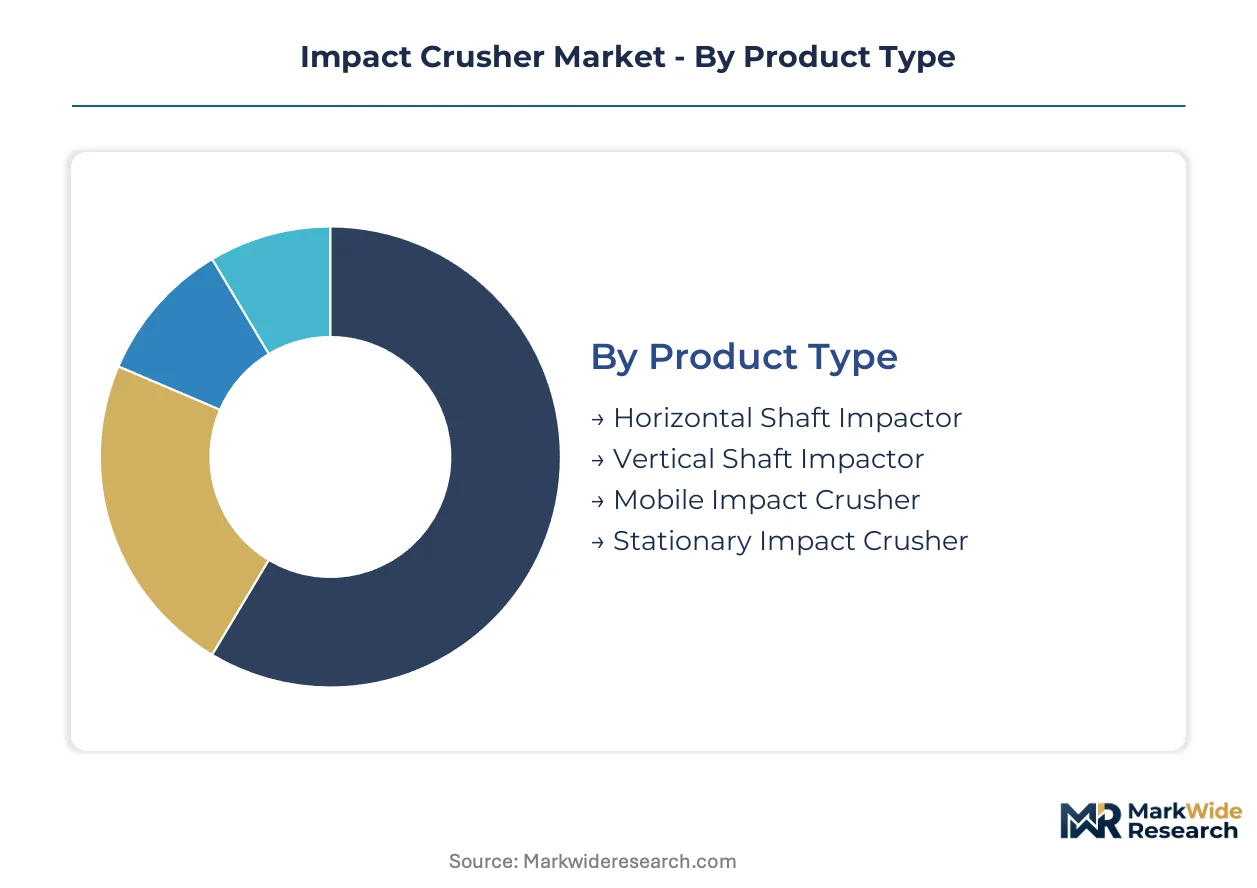
Segmentation in the impact crusher market reveals how equipment specifications align with distinct operational economics. Buyers prioritize rotor configuration, mobility requirements, and powertrain technology based on feed material abrasiveness and site infrastructure constraints.
Product Type:
Horizontal shaft and vertical shaft designs serve fundamentally different breakage mechanics, while mobility determines capital deployment flexibility across fixed quarry installations versus dispersed contracting.
- Horizontal Shaft Impactor:These machines accelerate feed material against rigid blow bars mounted on a spinning rotor, producing cubical product suited to asphalt and concrete aggregate specifications. Demand concentrates in limestone and granite quarries across Germany and Japan where predictable wear economics justify higher initial capital outlay.
- Mobile Impact Crusher:Self-propelled tracked or wheeled configurations integrate feed hopper, crusher, and discharge conveyor on a single chassis. Australian and Brazilian mining contractors are expanding these fleets to access lower-grade ore bodies at dispersed pit locations, prioritizing relocation speed over stationary throughput efficiency.
- Vertical Shaft Impactor:Rock-on-rock crushing action via high-speed rotor tip speeds generates fine gradations for manufactured sand and specialty aggregate applications.
- Stationary Impact Crusher:Fixed installations dominate high-volume quarry operations where grid access supports electric drive configurations and centralized maintenance staffing.
Volume sits with horizontal shaft installations in mature quarrying markets; growth tilts toward mobile configurations serving remote mining frontiers and urban demolition recycling.
End User:
Each end-use sector imposes distinct duty cycles, feed size distributions, and regulatory exposure that shape equipment specification priorities and aftermarket service contracting terms.
- Mining:Metallic ore preparation demands heavy-duty rotor designs processing feed up to 1,500 mm against abrasive silica-rich matrices. Australian iron ore and Brazilian copper-gold operations are driving demand for enclosed crushing circuits compliant with EPA and MEE particulate emissions mandates.
- Construction:Road building and infrastructure projects require rapid equipment redeployment across dispersed job sites. Contractors in China's western provinces—Sichuan and Xinjiang—are acquiring mobile fleets to serve rail and highway construction where coastal market saturation has already peaked.
- Recycling:Concrete and asphalt recovery operations process reinforced demolition debris with high tramp metal content, necessitating hydraulic relief systems and magnetic separation integration.
- Aggregate:Sand and gravel producers prioritize consistent gradation control for ready-mix concrete supply, favoring adjustable curtain settings and automated feed regulation.
Mining commands the largest installed base by unit value; recycling is climbing the fastest as circular economy mandates expand across European Union member states.
Technology:
Powertrain selection reflects site infrastructure maturity, carbon accounting requirements, and maintenance capability availability across grid-connected versus remote operating environments.
- Electric:Grid-connected motor-driven rotors eliminate diesel fuel logistics and exhaust aftertreatment complexity. German and Japanese quarry operators are retrofitting existing horizontal shaft impactors with variable frequency drive technology to modulate rotor speed against material density, reducing electrical draw during non-peak feed conditions.
- Hydraulic:Diesel-hydraulic systems retain dominance in remote mining frontiers where grid extension remains uneconomical, though EU F-Gas Regulation restrictions on refrigerant chemistries are creating upgrade windows for electric retrofits.
- Pneumatic:Compressed air actuation serves specialized niche applications requiring explosion-proof operation in certain underground mining environments.
- Mechanical:Direct mechanical drive configurations persist in smaller stationary installations where simplicity and local repairability outweigh efficiency optimization.
Hydraulic systems retain volume leadership in developing extraction zones; electric drive is gaining share fastest in grid-connected mature markets facing carbon accounting pressure.
Application:
Application context determines feed preparation requirements, product specification stringency, and the economic viability of mobile versus stationary equipment deployment.
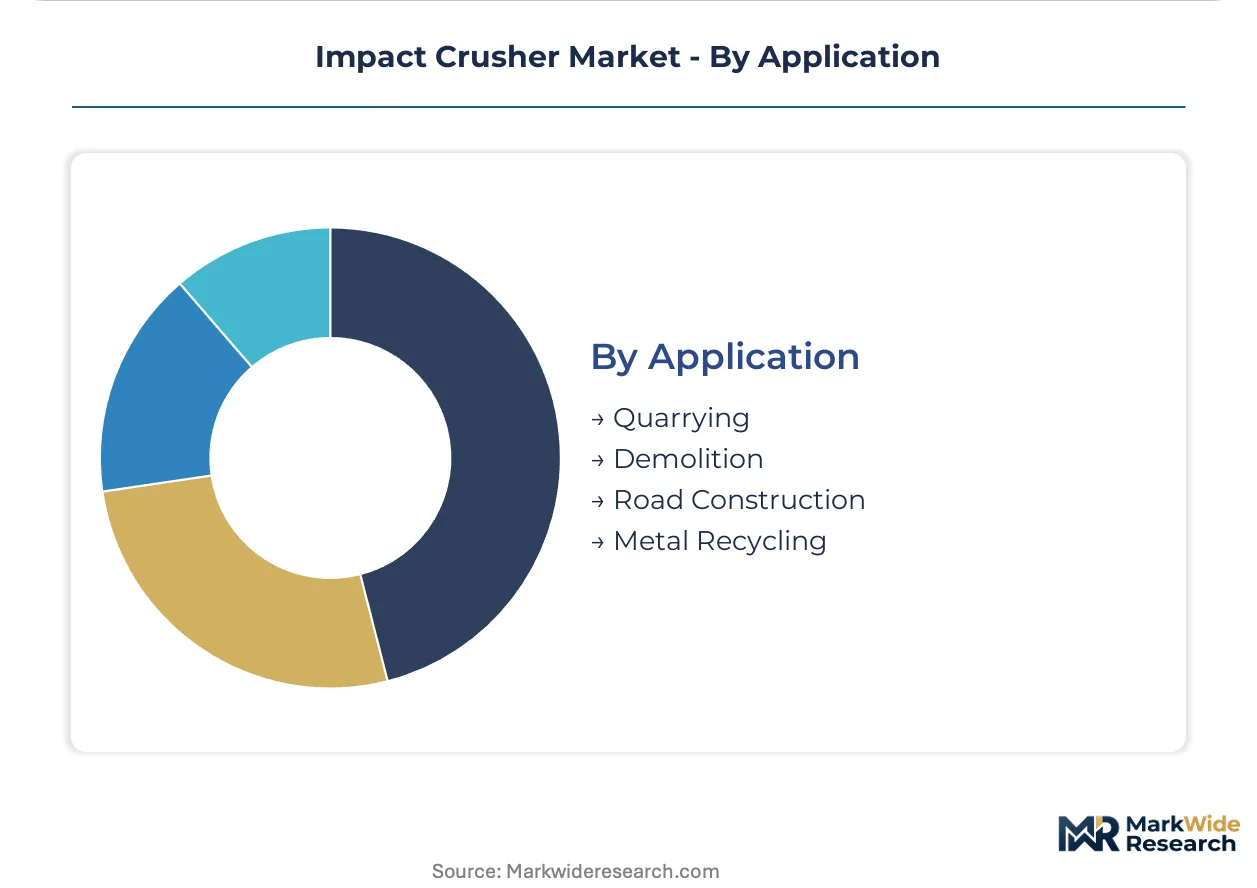
- Quarrying:Hard rock extraction of limestone, granite, and basalt demands predictable wear part economics and high availability guarantees. Horizontal shaft impactors dominate these installations where abrasive feed materials justify enclosed crushing circuit investments to meet EPA and MEE emissions thresholds.
- Demolition:Construction and demolition debris processing requires tramp metal tolerance and rapid setup capabilities. Mobile impact crushers serve urban material recovery facilities across France and Italy where EU circular economy mandates accelerate concrete and asphalt reuse.
- Road Construction:Highway and rail projects in China's western provinces require equipment mobility across challenging terrain, favoring tracked mobile configurations with independent diesel-hybrid power.
- Metal Recycling:Scrap metal preprocessing for steelmaking employs specialized impactor designs with reinforced housings and heavy-duty apron feeders.
Quarrying anchors equipment volume through replacement cycles; demolition applications show the steepest expansion trajectory as regulatory frameworks mandate construction waste diversion from landfills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Impact crusher consumption concentrates in mining-intensive economies, while foundry capacity for wear components clusters in manufacturing hubs. This geographic asymmetry shapes trade flows and supply vulnerability.
United States
EPA particulate emissions standards and OSHA silica exposure limits are compelling enclosed crushing circuit upgrades across Arizona and Nevada copper operations. Quarry operators in Texas and California are retrofitting horizontal shaft impactors with variable frequency drive technology to meet site-level carbon targets. Foundry supply for high-manganese blow bars remains concentrated in domestic specialty steel producers serving the Great Lakes industrial corridor.
Germany
REACH compliance frameworks and EU F-Gas Regulation restrictions on hydraulic refrigerants are accelerating electric drive retrofits in Bavarian limestone quarries. Equipment-as-a-service contracting is displacing capital purchases among mid-size aggregate producers in North Rhine-Westphalia. The Ruhr industrial region hosts specialized rotor balancing service providers supporting aftermarket maintenance networks.
China
MEE ambient air quality thresholds are restricting uncontrolled fugitive dust from aggregate processing in Sichuan and Xinjiang infrastructure corridors. Western provinces are outpacing coastal market saturation for mobile crushing fleets serving rail and highway construction. Foundry capacity for crusher wear components clusters in Shandong and Henan provinces, creating exposure to energy rationing policies.
Australia
Iron ore operators in Western Australia's Pilbara region are expanding mobile crusher fleets to process lower-grade ore bodies at dispersed pit locations. The country's national environmental regulator enforces dust suppression mandates at open-cut mining operations. Perth-based equipment distributors are locking in multi-year wear parts agreements with mining contractors seeking uptime guarantees.
Brazil
Copper-gold operations in Minas Gerais are driving demand for enclosed crushing circuits compliant with evolving environmental licensing requirements. ANVISA and state-level environmental agencies are tightening particulate monitoring at metallic ore preparation facilities. São Paulo industrial clusters house specialized technicians for high-speed impactor maintenance serving remote mining frontiers.
Impact Crusher Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the impact crusher supply base. Foundry-integrated OEMs command premium positioning through captive wear parts supply, while assembly-focused competitors rely on outsourced component sourcing. Three strategic archetypes dominate: vertically integrated mining equipment conglomerates, specialized mobile crushing specialists, and regional fabrication houses serving emerging market contractors. Competitive dynamics center on multi-year service contract capture and electric drive technology licensing.
Among Nordic-based mining equipment conglomerates, Metso Corporation and Sandvik AB exemplify the integrated archetype combining original equipment manufacturing with global aftermarket service networks. Terex Corporation occupies a position within the mobile-focused tier, anchoring competitiveness through fleet flexibility and technician deployment capabilities. These three companies represent contrasting strategic postures on electrification roadmaps and recurring revenue model adoption.
| Leading Market Players |
|---|
| Metso Corporation |
| Sandvik AB |
| Terex Corporation |
| Astec Industries |
| Weir Group |
| Hazemag |
| McCloskey International |
| Thyssenkrupp |
| Shanghai Shibang Machinery |
| Others |
Value Network & Pricing Analysis
Specialized rotor balancing technicians in Germany's Ruhr industrial region command premium wages that compress margins on mid-tier equipment, widening the spread between premium OEM servicing contracts and economy-tier third-party maintenance options. Labor-cost differentials between Western European technical centers and emerging market service hubs directly shape how pricing tiers separate bundled digital diagnostics from basic parts-only supply.
Pricing Analysis
Margin tightening in standard-tier horizontal shaft impactors reflects ferroalloy volatility in high-manganese blow bar inputs, forcing pass-through negotiations that erode distributor markups. Three-tier pricing structure across premium, standard, and economy levels separates Metso Corporation's multi-year wear parts agreements from regional fabrication houses serving emerging market contractors. Price differentiation hinges on after-sales bundling intensity and certification grade against ISO 21873 mobile machinery standards. Mining operators in Australia's Pilbara region exhibit lowest price sensitivity due to uptime guarantee requirements, while mid-size aggregate producers in the United Kingdom prioritize operational expenditure classification over capital ownership.
Supply Chain Analysis
Freight cost escalation on bulk wear components from China's Shandong and Henan foundry clusters to Brazilian copper-gold operations in Minas Gerais is compressing landed cost competitiveness against domestic Brazilian fabrication alternatives. Geographic supply concentration centers on China for high-manganese castings, Germany for precision rotor assemblies, and Australia for localized wear parts distribution. Raw material dependencies draw from ferroalloy pricing, specialty steel grades, and REACH-compliant lubricant formulations. Single-source vulnerability concentrates in Shandong province energy rationing exposure. Distribution runs through OEM captive service networks in mature markets and independent distributor channels in developing extraction zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where foundry-integrated OEMs capture premium positioning through captive wear parts supply, while assembly-focused competitors face margin compression from outsourced component sourcing.
For Market Incumbents: To counter substitution by gyratory systems in hard rock mining above 1,500 mm feed size, Metso Corporation and Sandvik AB should deepen backward integration into high-manganese foundry capacity and lock in multi-year digital diagnostics subscriptions. Channel control through captive technician deployments in remote mining frontiers defends against emerging mobile-focused specialists. For New Entrants and Emerging Players: Begin with construction demolition recycling in France and Italy where EU circular economy mandates accelerate concrete reuse but incumbent service networks remain underdeveloped. Urban material recovery facilities represent the most penetrable segment, with equipment-as-a-service contracting as the primary go-to-market angle to bypass capital-constrained contractor balance sheets. For Investors and Strategic Acquirers: The window for entry favors specialized rotor balancing service providers with proprietary technician training pipelines. Long-term viability over the next decade rests on electric drive retrofit capabilities as EU F-Gas Regulation phase-downs accelerate stationary installation upgrades. Watch ANVISA licensing timelines in Brazil as the inflection indicator for South American market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive high-manganese supply secures margin control against ferroalloy volatility in Shandong province. |
| Electric Drive Retrofit Program | Variable frequency drive installations in German quarries meet site-level carbon accounting thresholds. |
| Multi-Year Service Contract Capture | Remote monitoring subscriptions shift OEM revenue toward recurring architectures in Australian iron ore. |
| Technician Deployment Network Expansion | Specialized rotor balancing expertise scarcity in Brazil's remote frontiers creates uptime guarantee differentiation. |
| REACH-Compliant Lubricant Reformulation | Fluid system certification against substance thresholds unlocks EU market access for mobile crusher lines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving quarry maintenance directors, mining procurement leads, OEM aftermarket service heads, and foundry operations managers. Mining equipment trade association production statistics, EPA emissions compliance databases, MEE air quality threshold reports, and SEC 10-K equipment segment disclosures provided validation anchors. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from average selling price banding.
Granularity-level modeling deployed product type, end-use sector, powertrain technology, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived through logistic growth curve fitting against historical replacement cycle patterns and announced capacity expansion timelines. Forecast inputs incorporated electrification roadmaps, ore grade decline trajectories in Australian and Brazilian operations, and EU F-Gas Regulation phase-down schedules.
Underlying measurement precision varies by segment; mobile impact crusher forecasts carry tighter precision than stationary installations due to more transparent contractor fleet expansion announcements. Projections reflect assumptions regarding commodity price stability, grid extension economics in remote mining frontiers, and convergence timelines for CE marking with ISO 21873 standards. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Logging Cable Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Surface Mining Machinery Market