
 Global Autonomous Mining Equipment Market | 2026-2036
Global Autonomous Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Mining Equipment Market Analysis
Australia's Pilbara mining corridor is tilting toward full fleet autonomy as Rio Tinto and BHP accelerate driverless haulage conversions. Caterpillar Inc leverages its MineStar Command platform to dominate surface haul truck retrofits across Western Australian iron ore operations. Komatsu Ltd sustains competitive pressure through its FrontRunner AHS deployments in Chilean copper districts. Sandvik AB anchors underground specialization with its AutoMine portfolio targeting narrow-vein extraction in Canadian hard-rock mines.
Autonomous mining equipment encompasses self-propelled machinery capable of executing extraction, transport, and material handling cycles without continuous human operator intervention, typically integrating GPS positioning, LiDAR obstacle detection, and artificial intelligence-based path planning algorithms operating within defined geofenced zones. These systems execute repetitive, hazardous, or precision-critical tasks in surface pits and underground drifts where human fatigue and safety exposure create operational constraints. Haul trucks represent the most mature autonomous segment, with installed bases generating proven productivity deltas against manned equivalents across multiple commodity classes. Artificial intelligence is the fastest-expanding technology layer, as neural network-based perception systems displace rule-based autonomy stacks in complex terrain recognition scenarios. Underground mining applications command premium system pricing due to confined-space navigation complexity and the specialized sensor fusion required for GPS-denied environments.
FAA regulations govern aerial drone surveys supporting autonomous mine mapping in US jurisdictions, while Australia's state-based mine safety inspectorates enforce autonomous vehicle collision-avoidance protocols through mandatory technical standards. The EU AI Act's risk-classification framework is beginning to shape supplier liability structures for European-deployed autonomous haulage systems. Stakeholders must monitor how interoperability standards evolve across jurisdictional boundaries, as fleet operators increasingly demand vendor-agnostic autonomy layers that prevent single-supplier lock-in across mixed-equipment installations.
Market Dynamics
The autonomous mining equipment sector is being fundamentally restructured by Australia's tightening interoperability mandates for mixed-fleet operations, which force suppliers to decouple proprietary autonomy stacks from hardware platforms. Western Australian regulators are accelerating this transition through collision-avoidance technical standards that apply across surface and underground deployments.
Growth Catalysts
- Underground safety imperatives:Mining contractors in Canada and South Africa are eliminating human exposure in hazardous extraction zones through fleet automation programs.
- REACH compliance pressures:European hard-rock operators face escalating liability exposure under the EU AI Act's risk-classification framework for autonomous haulage systems.
- Sensor fusion advances:LiDAR-GPS integration is enabling centimeter-precision navigation in GPS-denied underground drifts where satellite positioning fails.
Market Restraints
- High-grade sensor dependency:Production-grade LiDAR units remain concentrated among a handful of specialized optical component suppliers, creating input bottlenecks.
- Capital intensity barriers:Full fleet retrofits require substantial upfront expenditure on geofencing infrastructure and control room systems before operational savings materialize.
- FAA airspace restrictions:Aerial drone surveys supporting autonomous mine mapping face operational altitude and beyond-visual-line-of-sight limitations in US jurisdictions.
Strategic Opportunities
- Chilean copper belt expansion:Narrow-vein extraction operations in the Atacama Desert present untapped demand for specialized underground autonomous loaders.
- Performance-based contracting:Equipment-as-a-service models are displacing traditional capital purchase structures among mid-tier Australian iron ore contractors.
- ISO 17757 harmonization:Emerging international standards for autonomous mining machine safety are creating first-mover certification advantages for compliant suppliers.
Industry Challenges
- Autonomy engineer scarcity:The specialized skill set combining robotics, mining operations, and safety systems engineering remains critically under-supplied across all major mining jurisdictions.
- Mixed-fleet integration complexity:Retrofitting legacy Caterpillar and Komatsu equipment with vendor-agnostic control layers demands extensive custom engineering per installation.
- TGA certification timelines:Australian state-based mine safety inspectorates impose prolonged approval cycles for new autonomous vehicle collision-avoidance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Mining Equipment Market |
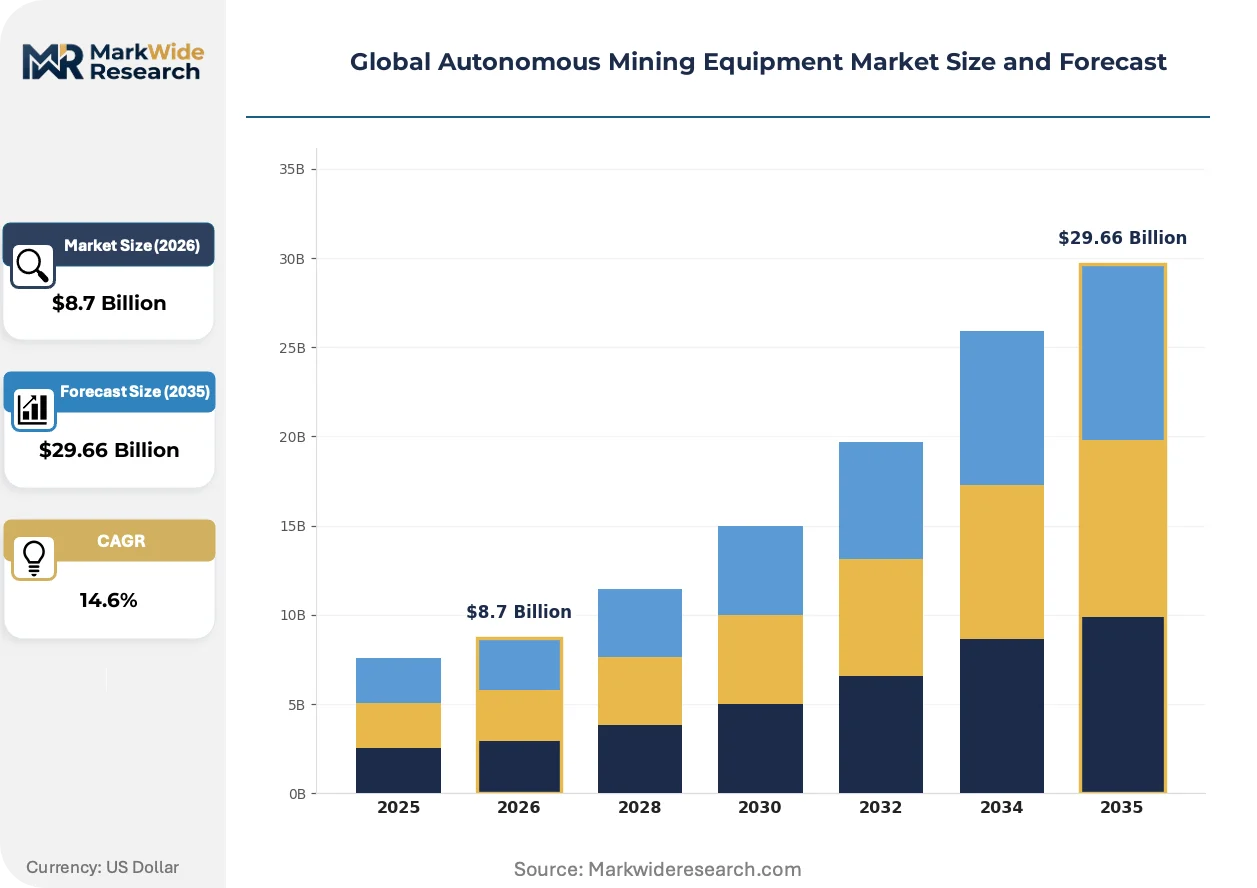
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulldozers, Excavators, Haul Trucks, Drills Technology: GPS, LiDAR, Artificial Intelligence, Robotics End User: Mining Companies, Contractors, Service Providers, Operators Application: Surface Mining, Underground Mining, Material Handling, Haulage |
| Companies Covered | Caterpillar Inc, Komatsu Ltd, Sandvik AB, Epiroc AB, Hitachi Construction Machinery Co Ltd, ABB Ltd, Rockwell Automation Inc, Hexagon AB, Autonomous Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Mining Equipment Market Emerging Trajectories
Artificial intelligence is hybridizing with established autonomy architectures, creating neural network-based perception systems that outperform rule-based stacks in complex terrain recognition. This convergence is compressing development cycles and expanding operational envelopes beyond geofenced boundaries.
Sensor fusion technology is hybridizing GPS-denied navigation with inertial measurement units and LiDAR point-cloud mapping for underground mining applications. Canadian hard-rock operators are deploying these integrated systems in narrow-vein extraction drifts where satellite positioning is unavailable. The structural consequence is opening previously uneconomical ore bodies to mechanized extraction by eliminating the productivity penalty of manual operation in confined spaces.
The EU AI Act's risk-classification framework is reshaping supplier liability structures for autonomous haulage systems deployed across European mining operations. Equipment manufacturers now face heightened documentation and conformity assessment burdens for AI-enabled decision-making components. Underground mining segments in Scandinavia and Germany are responding by accelerating ISO 17757 alignment to preempt regulatory friction.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in the Australian Pilbara iron ore precinct. Fleet operators are separating autonomy software updates from hardware service agreements, creating standalone subscription revenue streams for control system providers. This behavioral shift is most pronounced among Rio Tinto and BHP contractor networks seeking operational flexibility across mixed-equipment installations.
Global Autonomous Mining Equipment Market Segmentation
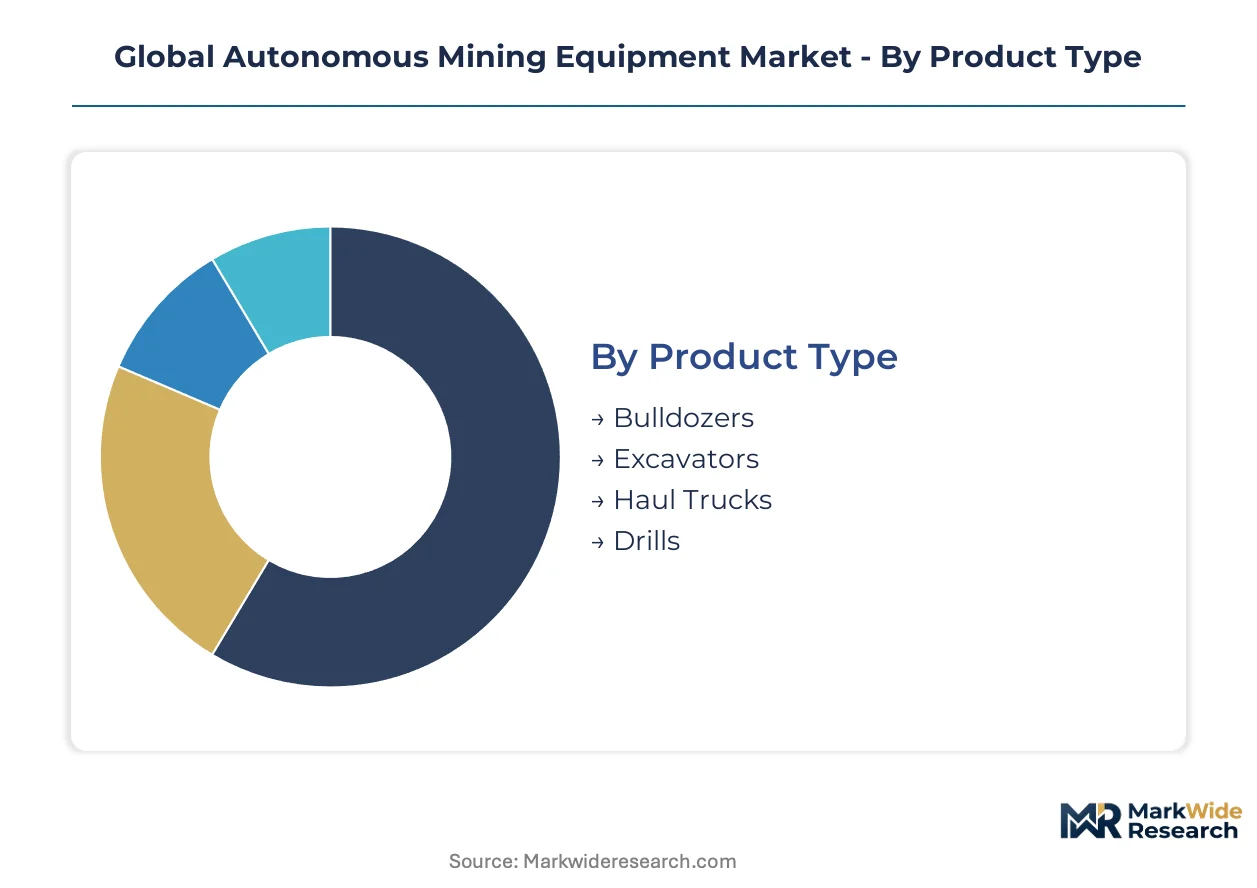
Equipment segmentation in autonomous mining reveals distinct technology maturity curves and capital deployment patterns across extraction environments. Product type stratification directly correlates with operational risk profiles, while application-based segmentation exposes divergent sensor fusion requirements between surface and underground deployments.
Product Type:
Cost tier differentiation across autonomous mining equipment reflects capital intensity gradients and retrofit complexity, with surface-focused machinery commanding premium system integration pricing against underground-specialized alternatives.
- Haul Trucks:These 240-ton-plus autonomous haulers integrate GPS positioning with LiDAR obstacle detection for pit-to-crusher material movement. Western Australia's Pilbara iron ore precincts concentrate fleet deployment demand as Rio Tinto and BHP accelerate driverless conversions to eliminate shift-change productivity losses.
- Excavators:Cable shovel and hydraulic excavator autonomy requires precision bucket positioning algorithms and real-time terrain mapping for selective ore loading. Chilean copper districts in the Atacama Desert represent concentrated demand zones where Komatsu's FrontRunner AHS-compatible loading units face integration complexity with mixed-fleet haulage systems.
- Bulldozers:Autonomous dozers execute precision grading and dump maintenance cycles using blade-mounted LiDAR arrays for terrain following.
- Drills:Blasthole and exploration drill rigs incorporate autonomous rod handling and depth-controlled penetration systems for pattern drilling consistency.
Haul Trucks hold installed capacity. Excavators is rotating up the share rankings.
Technology:
Application-specific technology layering determines operational envelope expansion and regulatory compliance pathways across mining jurisdictions.
- Artificial Intelligence:Neural network-based perception systems are displacing rule-based autonomy stacks in complex terrain recognition scenarios. Canadian hard-rock operators deploy these AI layers for narrow-vein extraction decision-making where GPS-denied environments demand adaptive path planning beyond geofenced boundaries.
- LiDAR:Production-grade optical distance measurement enables centimeter-precision navigation through point-cloud mapping of pit walls and underground drifts. Australia's state-based mine safety inspectorates mandate collision-avoidance technical standards that hinge on LiDAR sensor fusion reliability across surface and underground deployments.
- GPS:Satellite positioning systems provide primary localization for surface haulage routes within defined geofenced zones.
- Robotics:Manipulator systems and autonomous ground vehicles execute repetitive material handling cycles without continuous operator intervention.
LiDAR holds installed capacity. Artificial Intelligence is climbing the fastest.
End User:
Customer type segmentation exposes divergent procurement patterns between integrated miners and contractor fleets across autonomous equipment deployments.
- Mining Companies:Integrated operators like Rio Tinto and BHP deploy captive autonomous fleets with dedicated control room infrastructure and in-house autonomy engineering teams. Western Australia's Pilbara corridor concentrates their capital deployment as full-fleet autonomy programs eliminate human exposure in hazardous haulage zones.
- Contractors:Third-party extraction and haulage specialists face capital intensity barriers for full fleet retrofits but are accelerating adoption through equipment-as-a-service models. Mid-tier Australian iron ore contractors increasingly separate autonomy software subscriptions from hardware service agreements to preserve operational flexibility.
- Service Providers:Autonomy system integrators and retrofit specialists deliver vendor-agnostic control layer implementations for mixed-fleet installations.
- Operators:Equipment leasing and rental firms maintain autonomous fleet assets for short-term deployment to project-specific extraction campaigns.
Mining Companies hold installed capacity. Contractors is rotating up the share rankings.
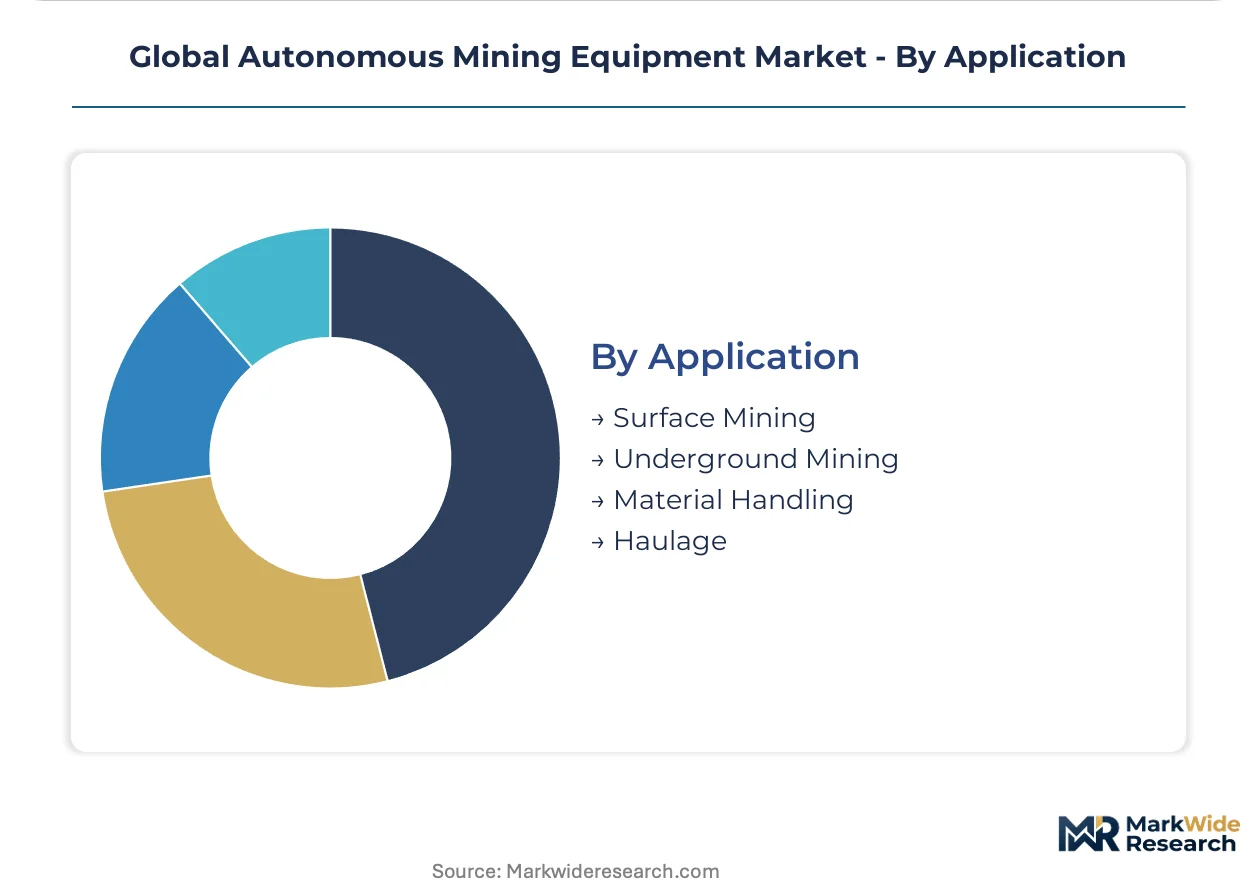
Application:
Volume concentration across application segments correlates with safety exposure severity and labor cost structures in extraction environments.
- Surface Mining:Open-pit copper, iron ore, and coal operations deploy autonomous haul trucks and loading equipment across standardized haul routes with GPS-defined geofencing. The Pilbara iron ore precincts in Western Australia anchor global surface autonomy deployment density with proven productivity deltas against manned equivalents.
- Underground Mining:Confined-space navigation in GPS-denied drifts demands specialized sensor fusion combining LiDAR, inertial measurement units, and artificial intelligence-based path planning. Canadian hard-rock narrow-vein extraction and South African platinum reef operations concentrate demand as contractors eliminate human exposure in hazardous zones.
- Haulage:Pit-to-processing plant material transport represents the most mature autonomous application segment with established collision-avoidance protocols.
- Material Handling:Stockpile management and processing facility feed systems utilize autonomous loaders and conveyor integration for continuous flow optimization.
Surface Mining holds installed capacity. Underground Mining is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers concentrate autonomous system integration capacity in mining-intensive economies where labor costs and safety exposure drive fleet automation decisions. National regulators in these jurisdictions impose divergent collision-avoidance and interoperability mandates that reshape competitive positioning.
Australia
Western Australia's Pilbara iron ore precincts anchor surface haulage automation deployment as Rio Tinto and BHP eliminate shift-change productivity losses. State-based mine safety inspectorates enforce TGA-mandated collision-avoidance technical standards across surface and underground operations. Perth-based engineering clusters supply control room infrastructure and autonomy software integration for mixed-fleet installations.
Chile
Atacama Desert copper districts concentrate demand for FrontRunner AHS-compatible loading units and autonomous haul trucks in open-pit extraction. The national mining regulator enforces autonomous vehicle operational safety protocols through mandatory geofencing and obstacle-detection certification. Antofagasta and Calama host service provider networks delivering retrofit integration for mixed Caterpillar-Komatsu fleets.
Canada
Ontario and Quebec hard-rock operations deploy narrow-vein autonomous loaders to eliminate human exposure in confined GPS-denied drifts. Health Canada and provincial occupational safety regulators mandate LiDAR-based collision-avoidance systems for underground mechanized equipment. Sudbury and Val-d'Or mining clusters anchor Sandvik AutoMine system deployment in nickel and gold extraction.
United States
Nevada and Arizona gold-copper operations integrate autonomous haulage with drone-based mine surveying for pit optimization. FAA regulations govern aerial drone altitude and beyond-visual-line-of-sight limitations for autonomous mapping support. Elko and Tucson host autonomy engineering talent pools serving surface mining contractors across the Southwest.
South Africa
Platinum reef and gold operations in the Bushveld Complex and Witwatersrand Basin accelerate underground fleet automation to reduce seismic and heat exposure risks. The Department of Mineral Resources and Energy enforces mandatory autonomous equipment safety standards through Mine Health and Safety Act amendments. Johannesburg and Rustenburg concentrate retrofit service capacity for narrow-reef mechanized extraction.
Global Autonomous Mining Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, control modules, and software layers. The vendor structure consolidates around full-stack autonomy providers capable of delivering geofencing infrastructure, fleet management systems, and regulatory compliance documentation. Two archetypes dominate: diversified industrial conglomerates with captive mining equipment divisions, and pure-play autonomy software houses licensing control layers across OEM hardware. Competitive dynamics center on strategic partnerships bridging hardware retrofit capability with AI-based perception software, and geographic expansion through regional service hub establishment.
Among diversified industrial equipment manufacturers, Caterpillar Inc and Komatsu Ltd exemplify platform integrators leveraging established dealer networks and captive fleet management software. Sandvik AB occupies a specialist position in underground autonomy where GPS-denied navigation complexity commands premium system pricing. These three anchors demonstrate how competitive positioning stratifies between surface-focused scale players and underground-focused technology specialists.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Komatsu Ltd |
| Sandvik AB |
| Epiroc AB |
| Hitachi Construction Machinery Co Ltd |
| ABB Ltd |
| Rockwell Automation Inc |
| Hexagon AB |
| Autonomous Solutions Inc |
| Others |
Supply Flow & Price Mechanics
Production-grade LiDAR sensor manufacturing concentrates in specialized optical component suppliers across Germany, Japan, and the United States, anchoring margin capture upstream while autonomous system integrators downstream compete on software differentiation and service attach rates. This upstream concentration creates pricing power asymmetries that equipment manufacturers navigate through long-term component supply agreements and captive sensor development programs.
Pricing Analysis
Australia's TGA-mandated collision-avoidance technical standards dictate the pricing tier structure across autonomous mining equipment deployments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17757-certified systems with full regulatory documentation from uncertified alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with premium tiers capturing standalone software subscription revenue. Pricing pressure stems from equipment-as-a-service model proliferation among mid-tier contractors seeking operational flexibility. Mining companies exhibit lowest price sensitivity due to captive fleet economics, while third-party contractors face capital intensity barriers that amplify cost responsiveness.
Supply Chain Analysis
High-grade optical distance measurement components draw from specialized suppliers concentrated in Germany, Japan, and the United States. Raw material dependencies span precision-manufactured laser diodes, specialized optical substrates, and high-performance inertial measurement units. Single-source vulnerability persists for production-grade LiDAR units where qualified alternative suppliers remain limited. Distribution runs through OEM captive dealer networks and regional autonomy integration specialists serving mixed-fleet retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous mining equipment markets reward service-attach strategies where standalone software subscription revenue expands faster than hardware replacement cycles, particularly in Australian Pilbara operations separating control system updates from maintenance agreements.
For Market Incumbents: Entrench platform dominance by deepening backward integration into LiDAR sensor supply chains and accelerating ISO 17757 certification across full product portfolios. Pure-play autonomy software houses threaten hardware-agnostic control layer licensing, making captive sensor development and regulatory documentation capabilities critical defensive levers. For New Entrants and Emerging Players: Build out narrow-vein underground specialization targeting Canadian hard-rock and South African platinum reef operations where GPS-denied navigation complexity commands premium system pricing. Chilean copper belt expansion presents accessible white-space for FrontRunner AHS-compatible loading unit integration. Go-to-market execution should anchor on regional service hub establishment in Antofagasta and Sudbury mining clusters. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play autonomy software houses with demonstrated AI-based perception capabilities and existing regulatory compliance documentation across multiple mining jurisdictions. Long-term viability in this sector depends on vendor-agnostic control layer scalability and recurring software revenue attachment rates. Watch for Australian interoperability mandate acceleration as the inflection signal indicating market consolidation toward open-architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | LiDAR-GPS-inertial measurement unit convergence enables centimeter-precision navigation in GPS-denied underground drifts. |
| ISO 17757 Certification Investment | First-mover safety standard compliance creates regulatory approval advantages in Australian and European deployments. |
| Equipment-as-a-Service Launch | Performance-based contracting displaces capital purchase structures among mid-tier Australian iron ore contractors. |
| Regional Service Hub Expansion | Perth and Antofagasta engineering clusters anchor control room infrastructure delivery for mixed-fleet installations. |
| AI Perception Layer Acquisition | Neural network-based terrain recognition capabilities displace rule-based autonomy stacks in complex extraction environments. |
Methodological Framework
Cross-validation between primary interviews with autonomy engineering directors, mine safety regulators, and aftermarket service heads anchors the qualitative findings against secondary validation from SEC equipment manufacturer filings, Australian TGA technical standards documentation, and Chilean mining regulator safety protocols. Bottom-up triangulation against top-down market sizing ensures segmentation integrity across equipment type, technology layer, and end-user archetype dimensions.
Calibration against historical fleet deployment data and documented productivity deltas from manned-to-autonomous conversions shapes the analytical framework across the projection horizon. Segmentation modeling spans product type, technology, end user, and application dimensions with additional layering by regulatory jurisdiction cluster. CAGRs derive from installed base expansion trajectories and replacement cycle compression observed in Western Australian iron ore operations. Forecast inputs incorporate collision-avoidance protocol adoption timelines and interoperability mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play autonomy software houses or Chinese equipment manufacturers with subsidized sensor development programs would shift outcomes. Cross-checking against documented fleet productivity benchmarks from Rio Tinto and BHP autonomous haulage deployments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Digger Machinery Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Mining Tester Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Logging Cable Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Underground Mining Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Mining Drill Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Global Dozers Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Drilling Rigs Market