
 Global Asphalt Crushers Market | 2026-2036
Global Asphalt Crushers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asphalt Crushers Market Analysis
Germany is reconfiguring asphalt crusher supply chains through expanded domestic manufacturing capacity for road recycling equipment. Metso Outotec Corporation leverages its minerals processing heritage to anchor mobile crushing technology leadership in European infrastructure markets. Sandvik AB competes through integrated digital services bundled with its crusher hardware. Wirtgen Group (Kleemann) dominates precision-engineered mobile jaw and impact crusher lines purpose-built for asphalt recycling contractors.
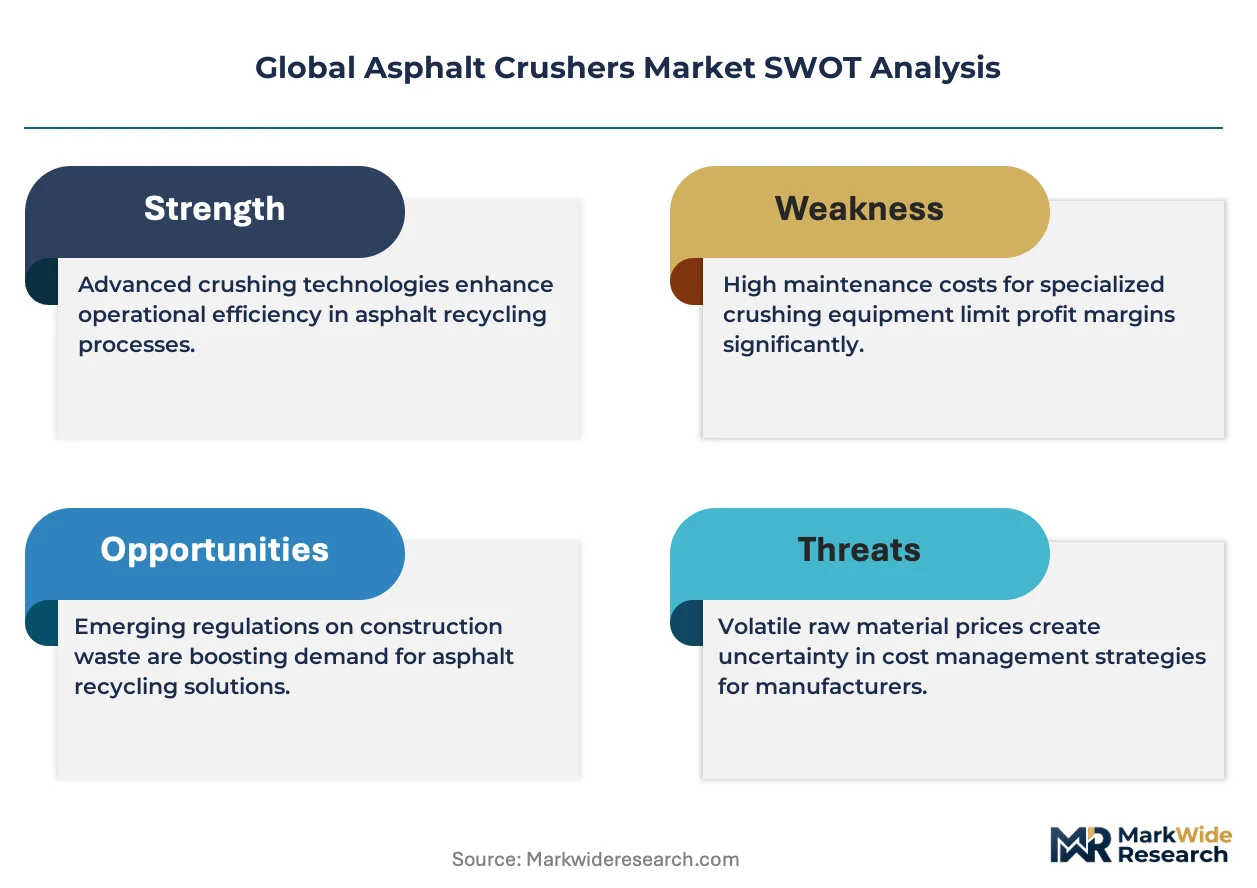
An asphalt crusher is a mechanical reduction machine engineered to break reclaimed asphalt pavement into specified aggregate gradations, typically processing material through compressive, impact, or shear forces with throughput capacities ranging from 100 to 1,000 tonnes per hour for road base reconstruction. Mobile technology leads equipment deployment because contractors prioritize on-site processing flexibility over centralized plant economics, while electric drivetrains represent the fastest-expanding sub-category as diesel emission restrictions tighten in urban demolition zones. Jaw crushers occupy the mature volume segment for primary asphalt reduction, whereas impact crushers capture premium positioning through superior cubical particle shaping that meets Superpave specifications.
The U.S. Environmental Protection Agency enforces Construction and Demolition debris diversion targets that directly stimulate asphalt recycling equipment purchases, while the European Union's Waste Framework Directive and F-Gas Regulation collectively mandate emission reductions and material circularity that reshape crusher design standards. Germany's Federal Highway Research Institute (BASt) certifies recycled asphalt aggregate quality thresholds that equipment manufacturers must engineer toward. Stakeholders must monitor how battery-electric powertrain integration intersects with emerging carbon border adjustments to determine capital allocation between hybrid and fully electric crusher platforms.
Market Dynamics
Electric drivetrain adoption is compressing equipment replacement cycles as contractors face diesel emission restrictions in urban demolition zones across Germany, the United States, and Japan. Battery-electric powertrains demand entirely new maintenance protocols and charging infrastructure investments that reshape fleet economics for asphalt recycling contractors.
Growth Catalysts
- EU Waste Framework Directive:Landfill diversion mandates in Germany, France, and Italy accelerate recycling infrastructure deployment and sustain equipment procurement for road rehabilitation contractors.
- Mobile crushing technology:On-site processing flexibility displaces centralized plant economics for urban road reconstruction projects in Tokyo and Los Angeles metropolitan zones.
- Federal highway renewal:Germany's BASt certification standards for recycled asphalt aggregate quality create sustained equipment orders from precision-engineered crusher manufacturers.
Market Restraints
- Steel input volatility:Crusher chamber liners and wear plates depend on high-manganese steel alloys subject to commodity price swings that compress manufacturer margins.
- Supply concentration:Precision hydraulic systems and control electronics concentrate among German and Japanese component suppliers, creating vulnerability to regional disruption.
- Technical limitation:Current battery energy density restricts continuous operation duration for electric mobile crushers below diesel-equivalent throughput in high-volume applications.
Strategic Opportunities
- India's National Highway Development:Underpenetrated road recycling infrastructure in Maharashtra and Gujarat states creates whitespace for mobile crusher deployment as federal pavement renewal budgets expand.
- Carbon Border Adjustment Mechanism:EU CBAM creates regulatory tailwind for low-emission electric crusher platforms by penalizing embodied carbon in imported construction equipment.
- Telematics-converged maintenance:Integration of predictive diagnostics with OEM service networks enables outcome-based uptime guarantees that differentiate premium equipment offerings.
Industry Challenges
- Electrification skill gap:Maintenance technicians lack certification in high-voltage battery systems and power electronics, forcing contractors into costly OEM dependency for field repairs.
- Legacy fleet integration:Hybrid and electric crushers require incompatible material handling workflows that complicate mixed-fleet operations for mid-size contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asphalt Crushers Market |
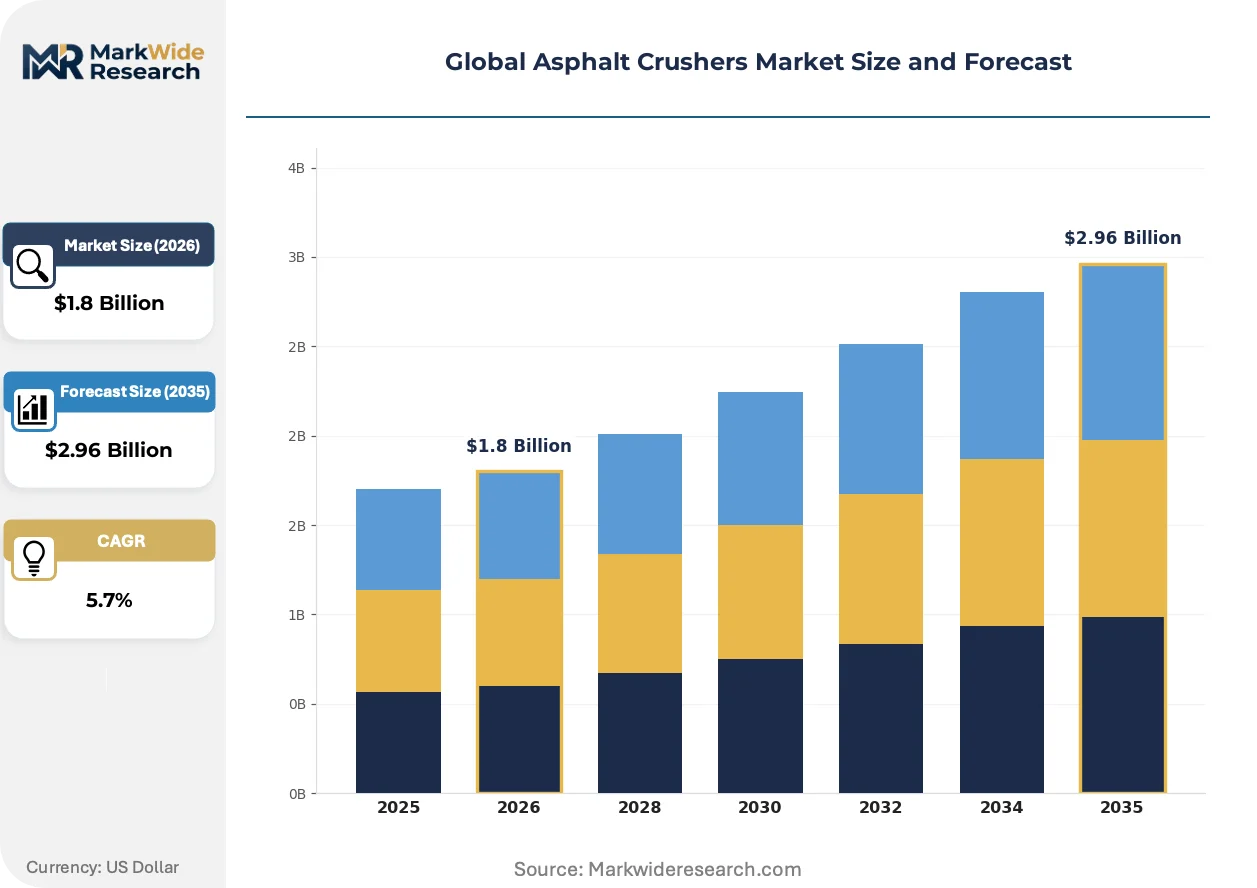
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jaw Crushers, Cone Crushers, Impact Crushers, Hammer Crushers Technology: Mobile, Stationary, Hybrid, Electric End User: Construction, Demolition, Recycling, Mining Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Metso Outotec Corporation, Sandvik AB, Wirtgen Group (Kleemann), Terex Corporation, McCloskey International, Thyssenkrupp AG, Astec Industries, Eagle Crusher Company, Rubble Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asphalt Crushers Market Emerging Trajectories
Digitalization of crushing operations is compressing the information gap between equipment performance and contractor decision-making. Real-time particle size distribution monitoring and automated gap adjustment systems are displacing manual sampling protocols that previously delayed production optimization.
Telematics-integrated crusher control systems are virtualizing the traditional relationship between operator skill and output quality. Municipal contractors in Germany and Japan deploy these platforms to standardize aggregate gradation across dispersed project sites. The technology is virtualizing equipment procurement criteria as buyers prioritize data accessibility over raw mechanical specifications.
EPA enforcement of Construction and Demolition debris diversion targets is mandating measurable recycling rates for federally-funded infrastructure projects. Contractors in California and Texas now face documentation requirements that favor crushers with integrated weighing and material tracking systems. Mobile equipment fleets are responding with certified measurement devices that streamline compliance reporting.
Rental and leasing channels are displacing outright purchase for mid-capacity asphalt crushers in North American markets. Independent contractors in Texas and Florida prioritize operational flexibility over balance-sheet ownership as project pipelines fluctuate. This pattern concentrates most visibly among secondary impact crusher categories where utilization rates vary seasonally with road construction windows.
Global Asphalt Crushers Market Segmentation
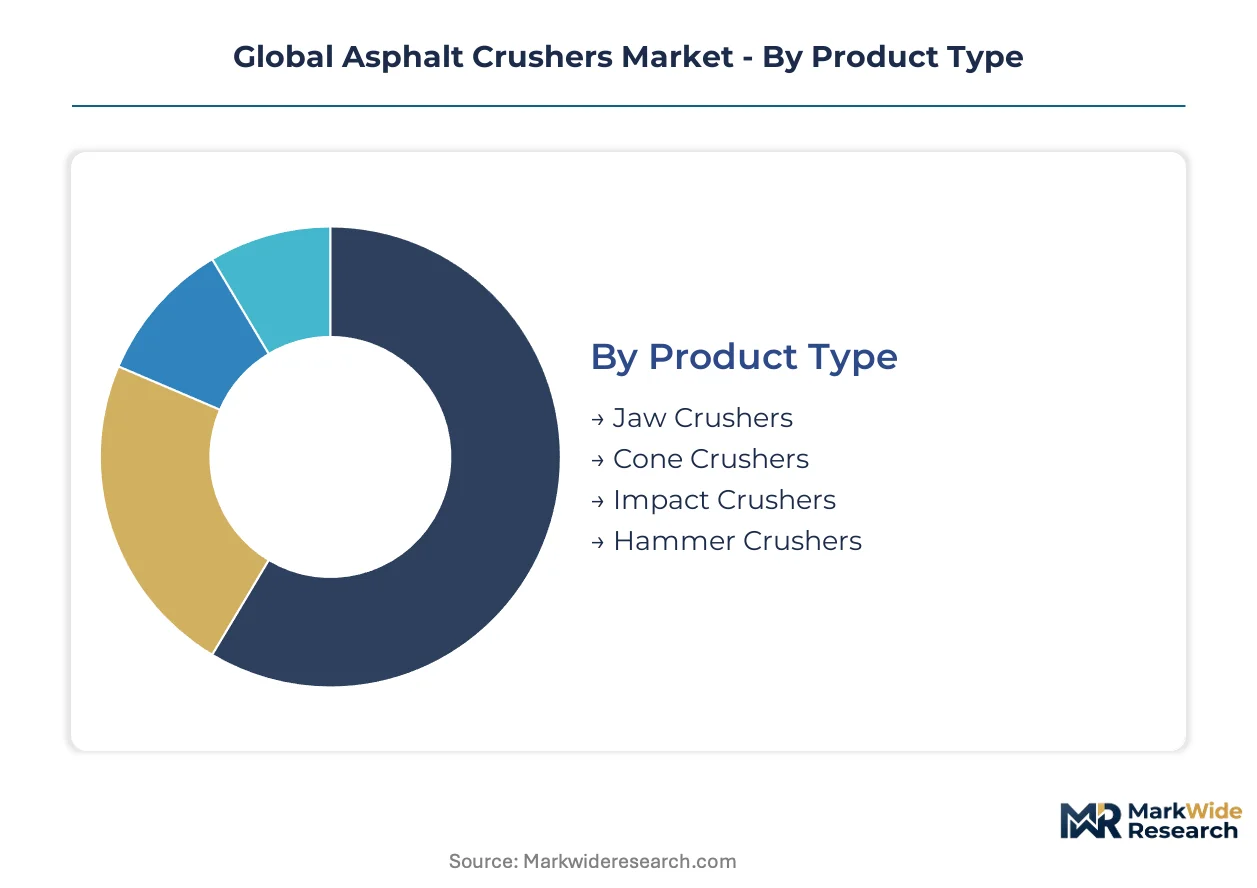
Equipment segmentation in asphalt crushing reveals how contractors balance mobility requirements against throughput economics. Product architecture and powertrain choices directly determine project eligibility for urban demolition zones versus highway reconstruction corridors.
Product Type:
Equipment architecture separates primary reduction duty from secondary shaping applications across road recycling workflows.
- Jaw Crushers:Compression-based reduction systems process oversized reclaimed asphalt pavement through toggle plate mechanisms with adjustable discharge gaps. German federal highway contractors deploy these units for initial size reduction on Autobahn rehabilitation corridors where input material exceeds 500mm. Diesel emission restrictions in Berlin and Munich municipal zones are compressing replacement cycles toward electric-hybrid configurations.
- Impact Crushers:Rotor-and-blowbar systems generate cubical aggregate through kinetic energy transfer, meeting Superpave specifications for surface course applications. Los Angeles County road agencies specify these units for precision gradation control on Interstate 5 reconstruction segments. California EPA documentation requirements favor crushers with integrated weighing systems for debris diversion compliance reporting.
- Cone Crushers:Eccentric rotating mantle designs deliver consistent reduction ratios for secondary processing stages in centralized recycling plants.
- Hammer Crushers:Rotating drum assemblies with replaceable manganese steel hammers target high-abrasion applications in mining-derived asphalt aggregate preparation.
Jaw crushers hold installed capacity. Impact crushers are rotating up the share rankings.
Technology:
Powertrain configuration determines operational eligibility across regulated urban demolition environments and remote highway corridors.
- Mobile:Tracked or wheeled chassis-mounted crushing units enable on-site processing without material transport to centralized plants. Tokyo metropolitan contractors deploy these systems for expressway maintenance windows with strict noise and emission curfews. Japan's METI efficiency standards are accelerating battery-electric retrofits for diesel-powered legacy fleets.
- Electric:Grid-tethered or battery-powered drivetrains eliminate exhaust emissions for enclosed demolition sites and tunnel reconstruction projects. Paris municipal authorities mandate these configurations for intra-muros roadworks under EU F-Gas Regulation compliance frameworks. Current battery energy density constraints restrict continuous operation duration below diesel-equivalent throughput in high-volume applications.
- Stationary:Fixed-base installations serve high-throughput permanent recycling facilities with dedicated material handling infrastructure.
- Hybrid:Dual-power systems switch between diesel and electric modes to balance mobility requirements with emission zone restrictions.
Mobile technology holds installed capacity. Electric configurations are climbing the fastest.
End User:
Customer category determines equipment specification priorities from aggregate quality certification to debris diversion documentation.
- Construction:General contractors procuring crushers for road base preparation prioritize throughput reliability over particle shape precision on federally-funded infrastructure projects.
- Recycling:Dedicated asphalt reclaimers require certified gradation compliance with state DOT specifications and integrated material tracking for EPA diversion rate verification.
- Demolition:Urban deconstruction specialists specify low-emission mobile units with noise suppression for work adjacent to occupied structures.
- Mining:Quarry operators integrate crushers into continuous production flows for aggregate supply to downstream hot-mix asphalt plants.
Construction holds installed capacity. Recycling is gaining share fastest.
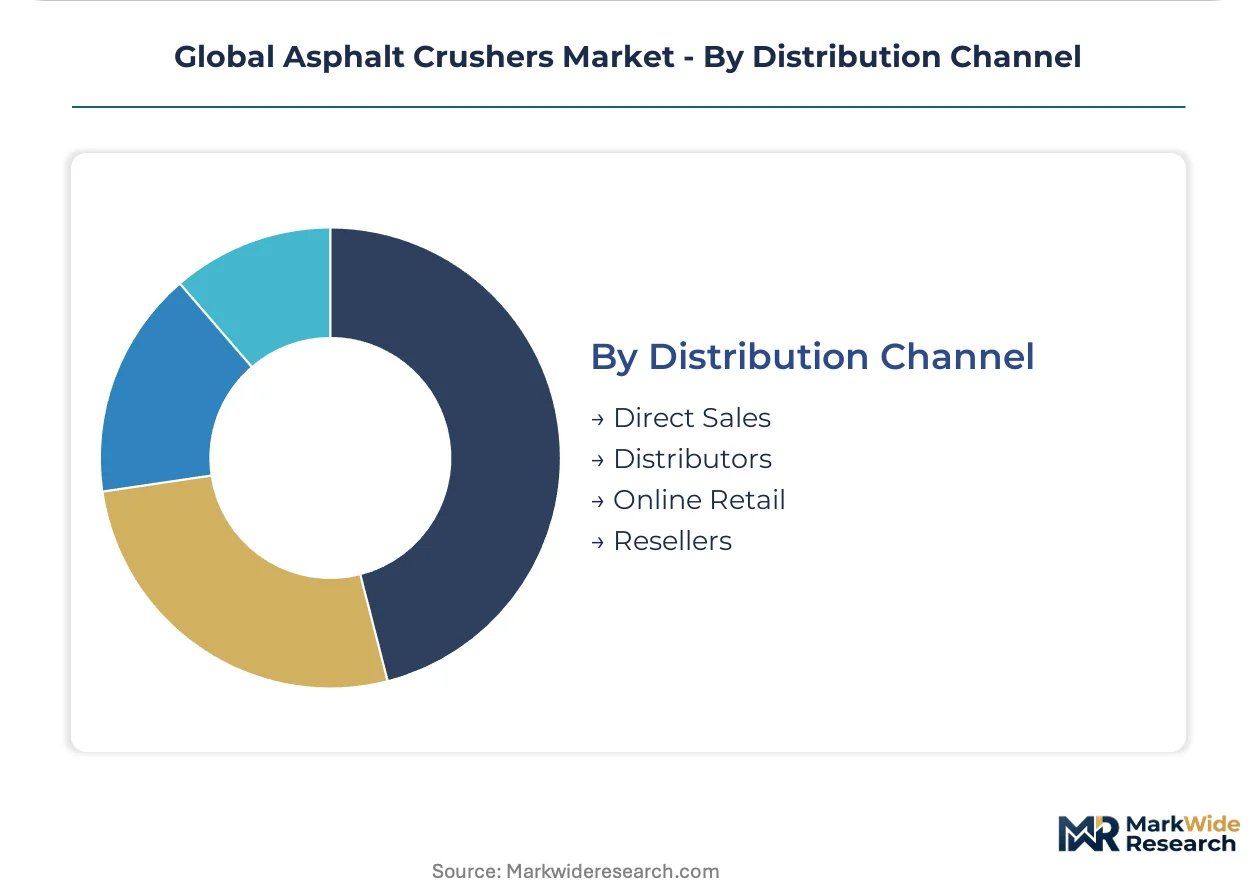
Distribution Channel:
Sales channel structure reflects capital intensity preferences and service dependency among contractor segments.
- Direct Sales:OEM field organizations serve large fleet operators with customized maintenance contracts and telematics integration.
- Distributors:Regional equipment dealers provide localized parts inventory and field service for mid-capacity contractors in Texas and Florida.
- Resellers:Independent brokers facilitate used equipment transactions for price-sensitive entry-level buyers.
- Online Retail:Digital platforms list standard configurations with transparent pricing for smaller contractors in underpenetrated Indian states.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA enforces Construction and Demolition debris diversion targets that directly stimulate asphalt recycling equipment purchases across the United States. Federal infrastructure spending and state-level pavement renewal programs create sustained procurement cycles for mobile crushing technology. Municipal emission restrictions in dense urban corridors accelerate electric drivetrain adoption.
United States
California and Texas dominate equipment deployment through state DOT pavement rehabilitation budgets and EPA compliance documentation requirements. Los Angeles County road agencies specify impact crushers with integrated weighing systems for Interstate 5 reconstruction segments. Federal highway funding formulas prioritize recycled content utilization, concentrating orders with telematics-enabled fleet operators in the Southwest and Southeast corridors.
Germany
The Federal Highway Research Institute certifies recycled asphalt aggregate quality thresholds that equipment manufacturers must engineer toward. BASt standards converge with circular economy targets to sustain precision-engineered crusher orders from Autobahn rehabilitation contractors. Munich and Berlin municipal zones enforce diesel emission curfews that compress replacement cycles toward electric-hybrid configurations.
China
National expressway maintenance programs and urban renewal mandates in the Yangtze River Delta generate demand for high-throughput mobile crushing systems. The Ministry of Ecology and Environment enforces construction waste recycling quotas that reshape procurement criteria for road base preparation equipment. Shanghai and Jiangsu province contractors prioritize on-site processing flexibility for metropolitan demolition zones.
Japan
Tokyo metropolitan contractors deploy tracked crushing units for expressway maintenance windows with strict noise and emission curfews. METI efficiency standards accelerate battery-electric retrofits for diesel-powered legacy fleets in Kanto and Kansai regions. Osaka prefecture road agencies specify low-emission configurations for tunnel reconstruction and intra-urban roadworks.
India
Maharashtra and Gujarat states present whitespace for mobile crusher deployment as National Highway Development budgets expand. The Ministry of Road Transport and Highways prioritizes recycled aggregate utilization in federal pavement renewal specifications. Mumbai-Ahmedabad industrial corridor contractors test on-site processing economics against centralized plant alternatives for greenfield expressway segments.
Global Asphalt Crushers Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: minerals processing heritage firms, integrated digital services providers, and precision-engineered mobile specialists. Dominant competitive moves include portfolio diversification toward electric powertrain platforms and geographic expansion through distributor network densification in underpenetrated Asian markets.
Among heritage-tier processors, Metso Outotec Corporation anchors mobile crushing technology leadership in European infrastructure markets. Sandvik AB exemplifies the integrated digital services archetype through outcome-based uptime guarantees bundled with hardware offerings. Wirtgen Group (Kleemann) occupies the precision-engineered specialist position for asphalt recycling contractors requiring BASt-certified aggregate quality. Terex Corporation and McCloskey International represent North American scale-driven competitors with rental and leasing channel concentration. Thyssenkrupp AG, Astec Industries, and Eagle Crusher Company sit within the mid-cap diversified machinery tier serving general construction and mining-derived aggregate preparation.
| Leading Market Players |
|---|
| Metso Outotec Corporation |
| Sandvik AB |
| Wirtgen Group (Kleemann) |
| Terex Corporation |
| McCloskey International |
| Thyssenkrupp AG |
| Astec Industries |
| Eagle Crusher Company |
| Rubble Master |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp corridor freight cost volatility compresses margins for high-manganese steel alloy shipments from German foundries to crusher assembly plants in Italy and Poland, forcing OEMs to pass transport surcharges through to asphalt recycling contractors while segmenting price tiers by emission certification grade.
Pricing Analysis
European price spreads between battery-electric and diesel-hybrid mobile crushers now exceed 15% at the factory gate, with German Autobahn contractors absorbing premiums for BASt-certified aggregate precision while Texas independent operators prioritize standard-tier units with distributor financing. Price differentiation hinges on telematics integration depth and EPA-compliant material tracking systems. Cost compression in the mid-capacity segment intensifies as rental channels displace outright purchase. Recycling specialists demonstrate lowest price sensitivity due to debris diversion documentation requirements, whereas general construction contractors negotiate aggressively on per-tonne throughput guarantees.
Supply Chain Analysis
Extended payment terms from German hydraulic systems suppliers now stretch to 90 days for Italian and Spanish crusher assemblers, reflecting working capital strain from steel alloy price volatility. Manufacturing concentrates in Germany, Japan, and the United States for precision components, with high-manganese wear plates drawing from Austrian and Swedish metallurgical specialists. Single-source vulnerability concentrates in precision control electronics sourced from Japanese component houses. Distribution runs through OEM direct sales for fleet operators and regional distributors for mid-capacity contractors in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as federal highway renewal programs across Germany and the United States reactivate equipment procurement deferred during budget consolidation periods.
For Market Incumbents: Pre-empt margin erosion in the mid-capacity segment by securing captive supply of high-manganese steel alloys through backward integration into European metallurgical partnerships. Accelerate battery-electric platform certification to meet tightening diesel emission curfews in Berlin, Munich, and Los Angeles municipal zones before 2027 regulatory deadlines compress replacement cycles. For New Entrants and Emerging Players: Pursue whitespace in Maharashtra and Gujarat states where National Highway Development budgets expand against underpenetrated road recycling infrastructure. Target mobile crusher rental partnerships with Mumbai-Ahmedabad corridor contractors testing on-site processing economics. Anchor go-to-market strategy through digital platforms listing standard electric configurations with transparent pricing for price-sensitive entry-level buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineered specialists with BASt certification relationships over scale-driven commodity assemblers. Long-term viability over the next decade hinges on electric powertrain integration depth and telematics-converged service revenue streams. Monitor battery energy density breakthrough thresholds as the inflection signal for fully electric platform economics surpassing diesel-equivalent throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Launch | Battery-electric crushers unlock municipal contracts under EU F-Gas Regulation compliance frameworks. |
| Telematics Integration Partnership | Predictive diagnostics bundled with OEM service networks differentiate premium offerings for German contractors. |
| Backward Integration into Steel Alloys | Captive supply of high-manganese wear plates insulates margins from commodity price swings. |
| Distributor Network Densification | Localized parts inventory in Texas and Florida captures rental channel growth in seasonal construction windows. |
| BASt Certification Investment | Federal Highway Research Institute quality thresholds sustain precision-engineered equipment orders from Autobahn contractors. |
Methodological Framework
A spread of perspectives from equipment procurement managers at German Autobahn contractors, aftermarket service directors at North American distributors, and plant engineers at Italian crusher assembly facilities converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed machinery manufacturers, BASt certification databases, and EPA Construction and Demolition debris diversion enforcement records. Bottom-up equipment shipment tallies triangulated against top-down federal highway budget appropriations.
Demand-supply balance modeling across the projection horizon segmented by powertrain configuration, mobility architecture, and end-user category with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle compression rates intersecting with emission restriction phase-in schedules. Industry-specific inputs incorporated battery energy density improvement curves and steel alloy price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure appropriations, construction commodity cycles, or battery supply chain constraints would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mini Cranes Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Induction Furnace Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Europe Crane Market
Construction Equipment
Global Crane Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Utility Locator Market
Construction Equipment
Global Construction Industry Core Drill Market