
 Critical Care Patient Monitoring Products Market | 2026-2036
Critical Care Patient Monitoring Products Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Patient Monitoring Products Market Analysis
Market Overview
Capital-intensity divergence between integrated platform vendors and point-solution specialists is reorganizing competitive dynamics in critical care monitoring. Medtronic plc leverages its deep vertical integration across sensors, software, and service networks to sustain premium positioning in North American health systems. Philips Healthcare anchors its presence through proprietary alarm management ecosystems that dominate European university hospital procurement.
Critical care patient monitoring products encompass multi-parameter bedside systems, telemetry transmitters, and centralized surveillance workstations engineered to capture electrocardiography, pulse oximetry, capnography, and invasive pressure waveforms with sampling frequencies exceeding 250 Hz. These systems serve the primary commercial purpose of enabling continuous hemodynamic and respiratory surveillance for mechanically ventilated and hemodynamically unstable patients. Bedside monitors command the largest installed base across intensive care units, while remote monitoring platforms represent the fastest-expanding margin pool as health systems pursue centralized command-center architectures. Software integration layers increasingly determine switching costs, with cloud-based systems capturing disproportionate R&D allocation from vendors seeking recurring revenue streams.
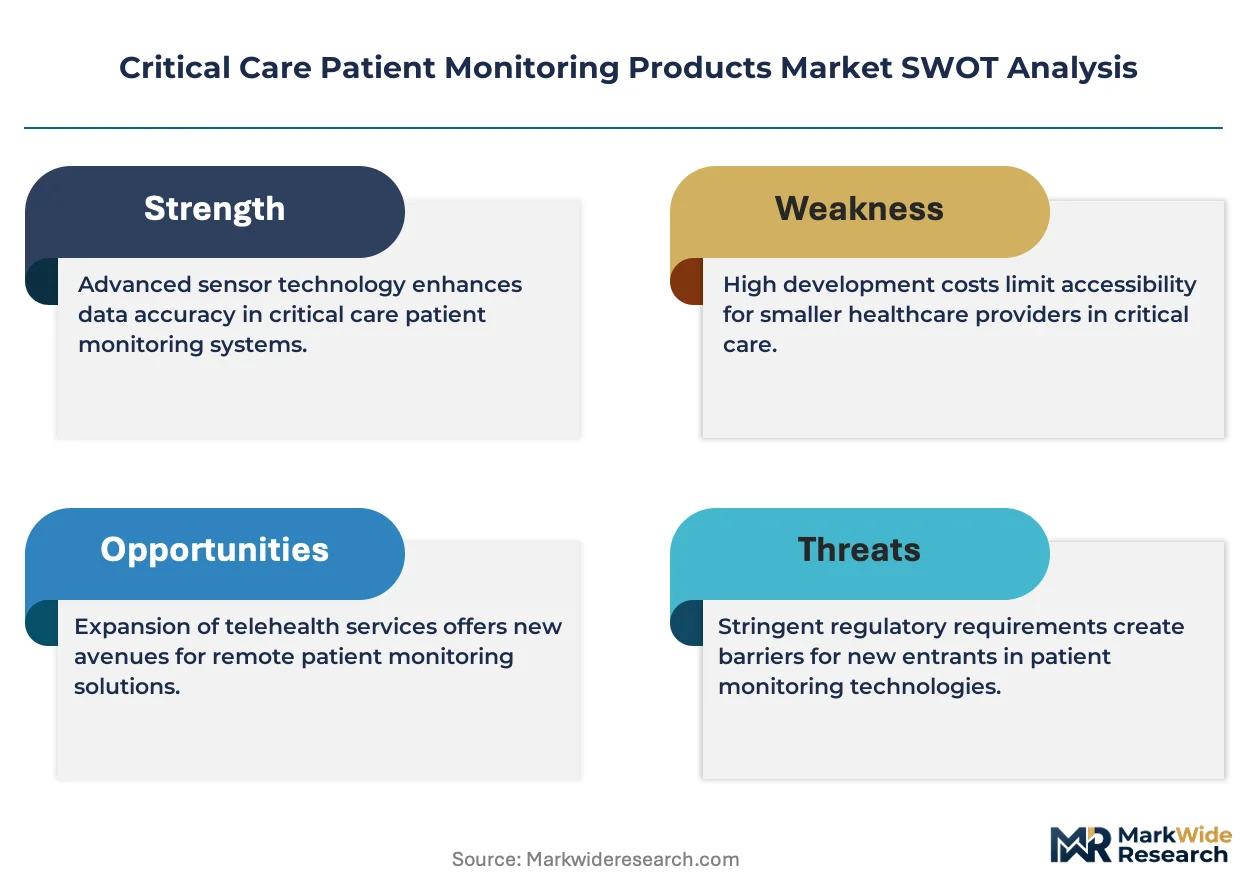
FDA Class II device clearance requirements, EU MDR technical documentation mandates, and IEC 60601-1-8 alarm safety standards collectively elevate engineering barriers and extend product development timelines for new entrants. Health Canada and TGA alignment with FDA-recognized consensus standards further narrows the regulatory pathways available to regional challengers. Stakeholders must monitor how FDA's evolving cybersecurity guidance for networked medical devices reshapes software update obligations and post-market surveillance burdens.
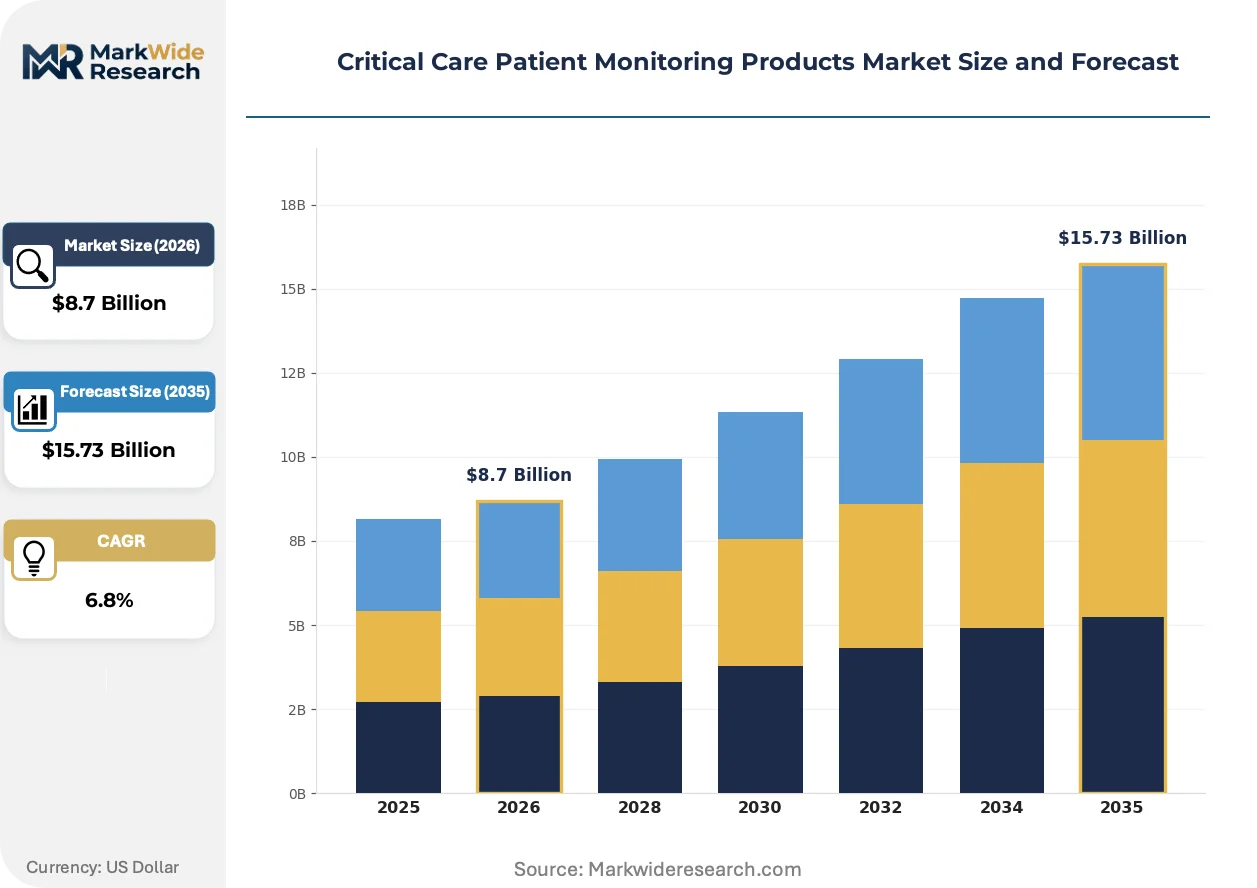
Market Dynamics
Alarm fatigue mitigation mandates from IEC 60601-1-8 are forcing manufacturers to redesign signal processing architectures, compressing development cycles and elevating R&D allocation toward software layers that differentiate switching costs.
Growth Catalysts
- FDA Class II premarket notification pathways:Streamlined 510(k) clearances for predicate-based submissions accelerate time-to-market for iterative sensor platforms, reducing regulatory friction for established vendors.
- Centralized command-center architectures:Health systems in Germany and the United States are consolidating ICU surveillance into single-vendor ecosystems, creating pull for integrated software-hardware bundles.
- Cloud-native telemetry infrastructure:Hospital IT departments prioritize subscription-based monitoring platforms that enable remote specialist access and reduce on-premise hardware footprints.
Market Restraints
- EU MDR technical documentation burdens:Extended conformity assessment timelines for Class IIa devices delay product launches by 12-18 months, compressing effective patent life for monitoring innovations.
- Semiconductor sensor supply concentration:Discrete analog front-end components for high-fidelity ECG acquisition depend on Taiwanese foundry capacity, exposing procurement to geopolitical disruption risk.
- Legacy bedside monitor installed base:Decade-long depreciation cycles in public hospital systems slow replacement demand despite superior connectivity in next-generation platforms.
Strategic Opportunities
- Home-based step-down monitoring:Post-acute care networks in the United States are deploying wearable telemetry for early discharge protocols, opening margin pools outside traditional ICU settings.
- AI-integrated alarm triage:Machine learning classifiers that suppress false-positive arrhythmia alerts command premium pricing from university hospitals seeking Joint Commission accreditation advantages.
- Health Canada alignment with FDA cybersecurity guidance:Harmonized post-market surveillance requirements for networked devices enable single regulatory dossiers across North American deployments.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for real-time physiological signal processing requires specialized expertise in digital filter design and medical-grade safety architectures.
- Interoperability certification complexity:IHE PCD profile compliance and HL7 FHIR integration consume substantial validation resources before health system procurement committees approve vendor selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Patient Monitoring Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemetry Monitors, Bedside Monitors, Portable Monitors, Central Stations Technology: Wireless Monitoring, Remote Monitoring, Software Integration, Cloud-Based Systems End User: Intensive Care Units, Emergency Departments, Operating Rooms, Post-Acute Care Facilities Application: Cardiac Monitoring, Respiratory Monitoring, Neurological Monitoring, Multisystem Monitoring |
| Companies Covered | Medtronic plc, GE Healthcare, Philips Healthcare, Abbott Laboratories, Becton, Dickinson and Company, Drägerwerk AG & Co. KGaA, Masimo Corporation, Baxter International Inc., Nihon Kohden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Patient Monitoring Products Market Emerging Trajectories
Continuous monitoring architectures are fragmenting into two distinct performance tiers, with premium platforms absorbing disproportionate innovation investment while value-tier systems compete on replacement-cycle capture.
Capnography-integrated multi-parameter modules are bifurcating the bedside monitor category. These systems combine mainstream CO2 waveform analysis with traditional vital signs capture. Academic medical centers in the United States and Germany are standardizing on these configurations for mechanically ventilated patient populations. The technology is bifurcating vendor competitive position into integrated platform specialists versus point-solution suppliers facing margin compression.
EU MDR Article 10 post-market clinical follow-up requirements impose sustained evidence-generation obligations on monitoring device manufacturers. These mandates force continuous real-world performance documentation rather than one-time premarket trials. Hemodynamic monitoring platforms with invasive pressure transducers face the heaviest surveillance burdens, prompting vendors to expand clinical affairs teams across European notified body jurisdictions.
Health system procurement committees are consolidating vendor relationships through multi-year enterprise agreements that bundle hardware, software, and technical service. This behavior concentrates purchasing authority within integrated delivery networks and away from individual ICU department managers. The shift is most visible in United States health systems pursuing standardized alarm management policies across distributed hospital campuses.
Critical Care Patient Monitoring Products Market Segmentation
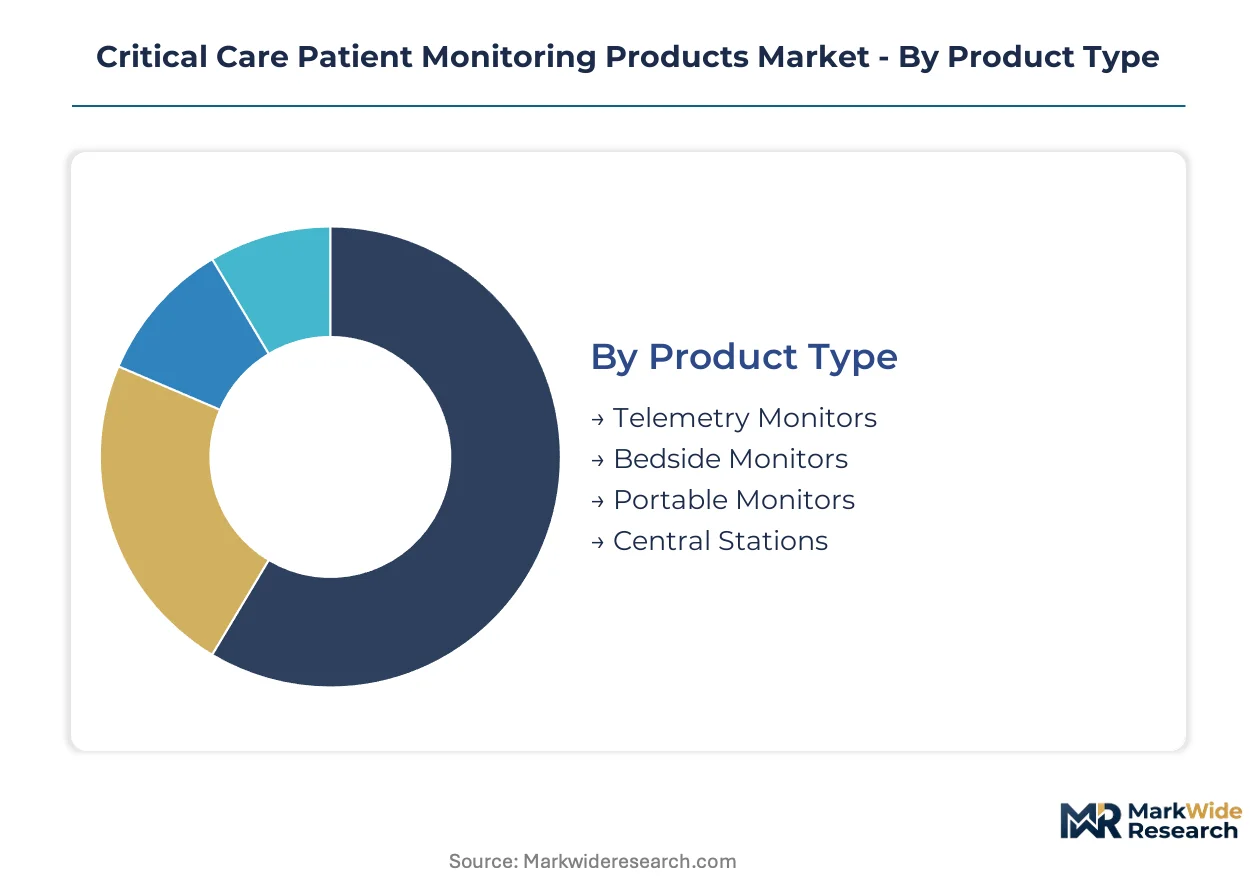
Critical care patient monitoring products fragment across four distinct category axes, each governing different procurement pathways and margin structures. Product type determines hardware replacement cycles and installed base economics. Technology segmentation increasingly dictates switching costs as health systems prioritize software-defined architectures over discrete device purchases.
Product Type:
Domestic production concentration varies sharply across this category, with bedside and central station systems manufactured primarily in Germany and the United States for regional health system deployment, while portable and telemetry platforms rely heavily on Taiwanese and Malaysian contract manufacturing for export markets.
- Bedside Monitors:Fixed multi-parameter systems integrate electrocardiography, pulse oximetry, invasive pressure monitoring, and capnography through modular parameter slots. Demand concentrates in German university hospital networks and United States academic medical centers where centralized command-center architectures require high-fidelity waveform capture exceeding 250 Hz sampling rates. IEC 60601-1-8 alarm safety compliance elevates engineering barriers for new entrants.
- Telemetry Monitors:Wearable transmitters enable ambulatory cardiac surveillance within hospital wards and step-down units. Export-led production from Taiwanese EMS providers supplies North American health systems pursuing early discharge protocols. Battery life and wireless range specifications determine competitive positioning in United States post-acute care networks.
- Portable Monitors:Compact battery-operated devices serve inter-hospital transport and emergency field deployment. Malaysian manufacturing clusters supply Southeast Asian and Middle Eastern procurement tenders.
- Central Stations:Surveillance workstations aggregate multi-bed data streams for remote specialist oversight. German and United States vendors dominate European and North American health system procurement respectively.
Bedside monitors command the established base. The steepest expansion runs through telemetry monitors.
Technology:
Cost tier differentiation separates premium subscription-based platforms from capital-intensive perpetual-license deployments, with cloud-native systems capturing disproportionate R&D allocation from vendors seeking recurring revenue streams.
- Cloud-Based Systems:Subscription telemetry infrastructure enables remote ICU specialist access and reduces on-premise hardware footprints. United States health systems in Texas and California prioritize these platforms for distributed hospital campus standardization. FDA cybersecurity guidance for networked devices shapes software update obligations.
- Remote Monitoring:Command-center architectures consolidate surveillance across geographically dispersed facilities. German hospital networks in Bavaria and North Rhine-Westphalia standardize on single-vendor ecosystems for alarm management policy uniformity.
- Wireless Monitoring:Bluetooth and proprietary RF protocols eliminate tethered connections for ambulatory patients. Taiwanese semiconductor supply concentration exposes procurement to geopolitical disruption risk.
- Software Integration:HL7 FHIR and IHE PCD profile compliance determines health system procurement committee approval timelines.
Software integration commands the established base. Cloud-based systems are gaining share fastest.
End User:
Application intensity varies by clinical setting, with intensive care units demanding highest parameter density while post-acute facilities prioritize cost-optimized telemetry for surveillance breadth over waveform fidelity.
- Intensive Care Units:Mechanically ventilated and hemodynamically unstable patients require continuous multi-parameter surveillance with invasive pressure monitoring. United States academic medical centers and German university hospitals drive specification standards for the category.
- Emergency Departments:Rapid triage protocols favor portable monitors with streamlined parameter sets for throughput optimization.
- Operating Rooms:Anesthesia workstations integrate capnography and hemodynamic monitoring for procedural sedation management.
- Post-Acute Care Facilities:Skilled nursing facilities in Florida and Arizona deploy wearable telemetry for early discharge and readmission reduction.
Intensive care units command the established base. Post-acute care facilities show the steepest expansion trajectory.
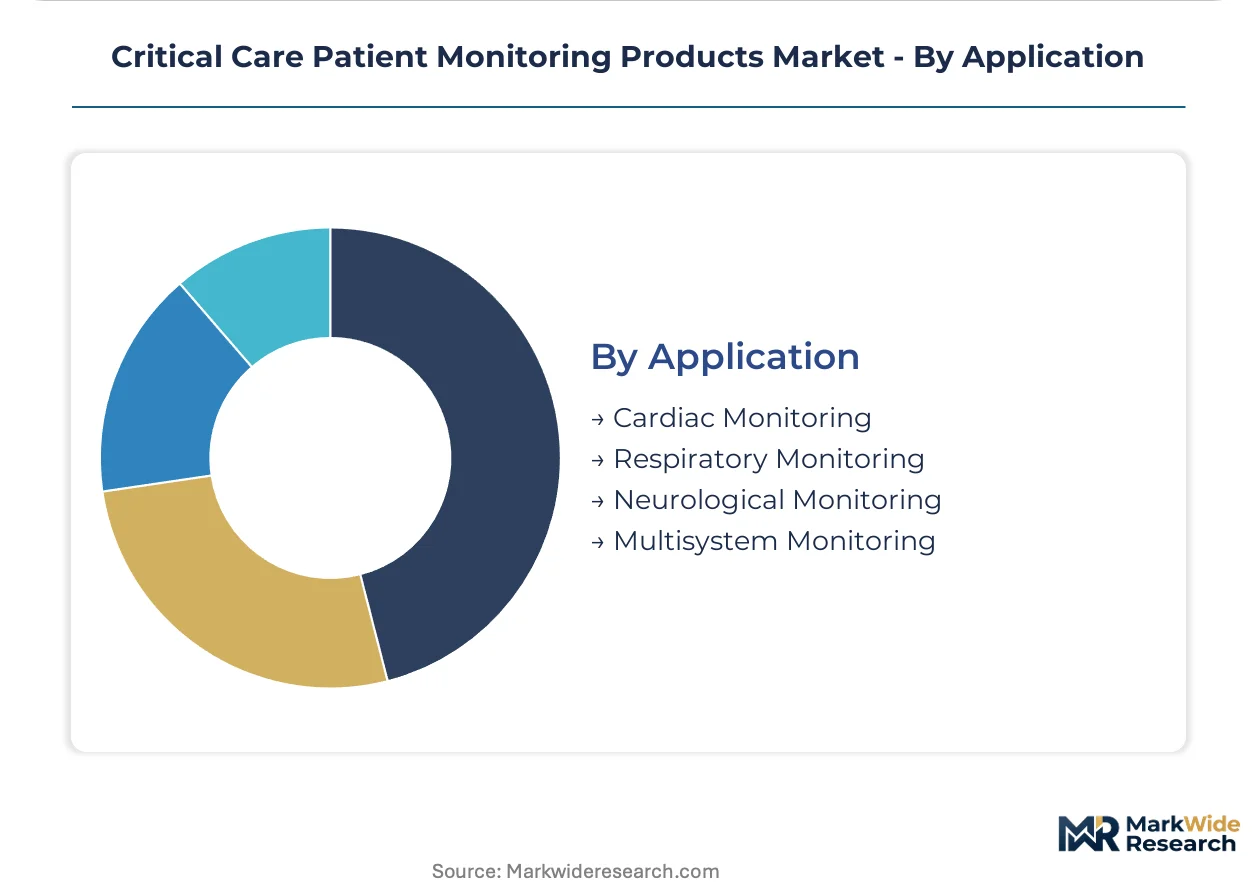
Application:
Customer type segmentation separates high-acuity hospital purchasers from emerging home-based and ambulatory surgical center demand, with cardiac and neurological applications commanding premium pricing through specialized sensor requirements.
- Cardiac Monitoring:Arrhythmia detection algorithms with machine learning classifiers suppress false-positive alerts and command premium pricing. United States university hospitals seeking Joint Commission accreditation advantages drive adoption of AI-integrated platforms.
- Respiratory Monitoring:Capnography-integrated modules serve mechanically ventilated populations in German and United States academic centers. Mainstream CO2 waveform analysis differentiates integrated platform specialists from point-solution suppliers.
- Neurological Monitoring:Intracranial pressure and cerebral oximetry parameters require specialized transducer interfaces with limited vendor supply.
- Multisystem Monitoring:Comprehensive parameter coverage consolidates vendor relationships through enterprise agreements spanning hardware, software, and technical service.
Cardiac monitoring commands the established base. Multisystem monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospital networks while procurement budgets tighten across United States public health systems, creating a transatlantic asymmetry in vendor margin capture.
United States
Academic medical centers in Texas and California drive demand for cloud-native telemetry platforms that enable remote ICU specialist access. FDA cybersecurity guidance for networked medical devices shapes software update obligations and post-market surveillance requirements. The Boston-Cambridge corridor anchors AI-integrated alarm triage development for Joint Commission accreditation advantages.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia prioritize centralized monitoring infrastructure with single-vendor ecosystem standardization. EU MDR Article 10 post-market clinical follow-up requirements impose sustained evidence-generation obligations on hemodynamic monitoring platforms. The Baden-Württemberg manufacturing cluster supplies high-fidelity bedside monitors with modular parameter slots exceeding 250 Hz sampling rates.
China
Provincial hospital systems in the Yangtze River Delta expand ICU capacity with cost-optimized multi-parameter systems for mechanically ventilated populations. NMPA Class II device registration pathways accelerate predicate-based submissions for iterative sensor platforms. The Shenzhen electronics manufacturing base produces discrete analog front-end components for ECG acquisition modules.
Japan
Metropolitan hospital networks in Tokyo and Osaka demand compact portable monitors for inter-hospital transport and emergency field deployment. PMDA alignment with IEC 60601-1-8 alarm safety standards elevates engineering barriers for new telemetry entrants. The Nagoya medical device cluster specializes in wireless monitoring protocols for ambulatory cardiac surveillance.
India
Corporate hospital chains in Maharashtra and Karnataka deploy wearable telemetry for post-acute step-down monitoring and early discharge protocols. CDSCO medical device rules for Class B and C devices create extended conformity assessment timelines for imported monitoring platforms. The Bengaluru health technology hub develops software integration layers for HL7 FHIR compliance in enterprise procurement.
Critical Care Patient Monitoring Products Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform specialists commanding premium positioning through proprietary alarm management ecosystems while point-solution suppliers face margin compression. The vendor base organizes into three strategic archetypes: diversified medical technology conglomerates with deep backward integration into sensors and software, mid-scale specialists focused on parameter-specific innovation, and regional contract manufacturers serving export markets through Taiwanese and Malaysian production clusters. Competitive dynamics center on multi-year enterprise agreements that bundle hardware, software, and technical service, alongside regulatory dossier harmonization across FDA, Health Canada, and TGA jurisdictions.
Among diversified medical technology conglomerates, Medtronic plc and GE Healthcare occupy positions as integrated platform anchors, while Philips Healthcare exemplifies the alarm management ecosystem specialist archetype. These entities represent the premium-tier vector where software-defined architectures determine switching costs and recurring revenue capture.
| Leading Market Players |
|---|
| Medtronic plc |
| GE Healthcare |
| Philips Healthcare |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Baxter International Inc. |
| Nihon Kohden |
| Others |
Supply Flow & Price Mechanics
Ninety-day semiconductor inventory cycles at Taiwanese foundries directly shape pricing power for high-fidelity ECG acquisition modules, compressing margins for vendors without captive analog front-end supply while amplifying premium capture for integrated platform specialists with backward integration into sensor production.
Pricing Analysis
Configured-to-order bedside monitors with modular parameter slots command 40-60% premiums over standard telemetry configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from point-solution specialists and regional contract manufacturers. Cost compression in the standard tier intensifies because Malaysian and Taiwanese EMS providers compete on replacement-cycle capture for public hospital systems. Post-acute care facilities in the United States exhibit highest price sensitivity, while German university hospital networks prioritize alarm management ecosystem uniformity over unit economics.
Supply Chain Analysis
Strategic stockpiling of discrete analog front-end components dominates inventory strategy among United States and German vendors exposed to Taiwanese foundry concentration. Semiconductor sensor supply draws from Taiwan, Malaysia, and China, with ECG acquisition modules and pulse oximetry LEDs resting on concentrated Asian manufacturing. Single-source vulnerability in Bluetooth and proprietary RF protocol chipsets elevates procurement risk for wireless telemetry platforms. Distribution runs through health system GPO contracts and direct enterprise agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution pressure from cloud-native telemetry platforms that displace capital-intensive bedside hardware with subscription-based remote monitoring, requiring defensive repositioning around software-defined switching costs.
For Market Incumbents: Fortify proprietary alarm management ecosystems through HL7 FHIR integration investments that deepen health system switching costs. Expand clinical affairs teams across European notified body jurisdictions to manage EU MDR Article 10 post-market surveillance burdens. Cloud-native entrants threaten hardware-centric revenue streams; backward integration into sensor production secures margin control against Taiwanese foundry volatility. For New Entrants and Emerging Players: AI-integrated alarm triage services represent the most penetrable white-space where incumbents under-serve United States academic medical centers seeking Joint Commission accreditation advantages. Target post-acute care networks in Florida and Arizona with wearable telemetry for early discharge protocols, where procurement authority has decentralized from ICU managers to skilled nursing facility operators. Pursue FDA 510(k) predicate-based clearances for iterative sensor platforms to accelerate time-to-market against entrenched alarm management ecosystems. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue transition play because cloud-native telemetry infrastructure captures disproportionate R&D allocation from vendors seeking subscription-based models over capital-intensive hardware sales. Acquisition targets should display software integration layer expertise with IHE PCD profile compliance and established hospital system pilot programs. Watch FDA cybersecurity guidance enforcement intensity as the inflection signal that reshapes post-market surveillance burdens and software update obligations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined predicate-based clearances accelerate iterative sensor platform launches for established vendors. |
| CE Marking Pathway | EU MDR technical documentation compliance extends effective patent life for hemodynamic monitoring innovations. |
| Hospital System Partnership | Multi-year enterprise agreements bundle hardware, software, and technical service across distributed campuses. |
| Software Companion Development | Cloud-native telemetry platforms enable remote ICU specialist access and reduce on-premise hardware footprints. |
| Reimbursement Strategy | Early discharge protocol alignment with United States post-acute care networks opens margin pools outside traditional ICU settings. |
Methodological Framework
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and ICU clinical directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and GPO contract repositories. Bottom-up installed base modeling and top-down health system expenditure analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness across semiconductor supply disruption scenarios and regulatory timeline compression assumptions. Segmentation dimensions modeled include product type, technology architecture, end-user clinical setting, and application intensity across the projection horizon. CAGRs derived from replacement cycle dynamics, ICU capacity expansion rates, and cloud-native platform adoption curves. Forecast inputs incorporated IEC 60601-1-8 alarm safety compliance costs and EU MDR post-market clinical follow-up expenditure burdens.
Forecasts assume regulatory continuity in FDA Class II device pathways and EU MDR conformity assessment timelines; material policy shifts would require re-modeling. Semiconductor supply concentration in Taiwanese foundries and cybersecurity guidance enforcement intensity represent specific risk factors. Revision becomes warranted when cloud-native platform penetration crosses thresholds that displace traditional bedside monitor replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market