
 Holter Monitoring Systems Market | 2026-2036
Holter Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Holter Monitoring Systems Market Outlook
Multi-source procurement of Holter components is rebalancing toward vertically integrated domestic suppliers as OEMs mitigate semiconductor supply volatility. Koninklijke Philips N.V. anchors its position through captive manufacturing of digital signal processing chipsets. GE Healthcare differentiates via cloud-based analytics platforms that integrate with hospital enterprise systems. Hill-Rom Services leverages its Baxter distribution network to control channel access across North American cardiology clinics.
Holter monitoring systems comprise portable electrocardiographic recorders that continuously capture cardiac electrical activity through two to twelve surface electrodes over 24 to 48 hours, with modern devices sampling at 128 to 1024 Hz for diagnostic-grade resolution. These systems serve primarily to detect transient arrhythmias, ischemic episodes, and conduction abnormalities in ambulatory patients outside clinical settings. Wireless monitors represent the fastest-expanding product category, as Bluetooth-enabled patch electrodes eliminate lead-wire artifacts and improve patient compliance during extended monitoring periods. Cloud-based solutions command disproportionate margin pools relative to hardware, since recurring software subscriptions and AI-enhanced diagnostic reporting create sticky revenue streams distinct from capital equipment sales.
The FDA enforces 21 CFR Part 820 quality system regulations for Holter device manufacturing, while the EU Medical Device Regulation requires notified body certification and post-market surveillance for European market access. HIPAA governs data transmission security for cloud-connected monitors deployed in US healthcare networks. Stakeholders must monitor evolving FDA cybersecurity premarket guidance and EU AI Act risk classifications for algorithmic arrhythmia detection features.
Market Dynamics
Wireless patch electrodes and cloud-native analytics platforms are compressing the traditional hardware-software boundary, forcing incumbents to rebuild revenue models around recurring diagnostics subscriptions rather than capital equipment sales.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare & Medicaid Services extended ambulatory cardiac monitoring coverage under value-based care contracts, accelerating clinic procurement of extended-wear Holter devices.
- AI-enhanced arrhythmia detection:Machine learning algorithms embedded in cloud platforms reduce false-positive rates and cut cardiologist interpretation time by half.
- Home-based cardiac surveillance:Post-acute care protocols now mandate 30-day monitoring for cryptogenic stroke patients, creating durable demand for patient-friendly wireless patches.
Market Restraints
- Semiconductor supply volatility:Discrete analog-to-digital converters and low-power Bluetooth SoCs face 26-week lead times, constraining OEM production schedules.
- Cybersecurity compliance burden:FDA premarket guidance for connected devices mandates third-party penetration testing, adding 8-14 months to product launch timelines.
- Reimbursement rate compression:Commercial payers in the United States have cut technical component fees for external electrocardiographic monitoring by double-digit percentages since 2022.
Strategic Opportunities
- EU AI Act algorithmic classification:Early compliance with high-risk system requirements positions vendors for preferential procurement by European hospital networks.
- Pediatric congenital heart programs:Extended monitoring for post-surgical arrhythmia surveillance remains underpenetrated, with patch-based systems replacing legacy telemetry.
- Direct-to-employer contracting:Self-insured corporations are purchasing population cardiac screening services, bypassing traditional hospital channel intermediaries.
Industry Challenges
- Electrophysiologist interpretation bottleneck:Cloud platforms generate terabytes of rhythm data that exceed specialist reading capacity, requiring investment in automated triage workflows.
- Legacy EMR integration friction:Hospital IT departments face 6-9 month projects to embed Holter data streams into existing electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holter Monitoring Systems Market |
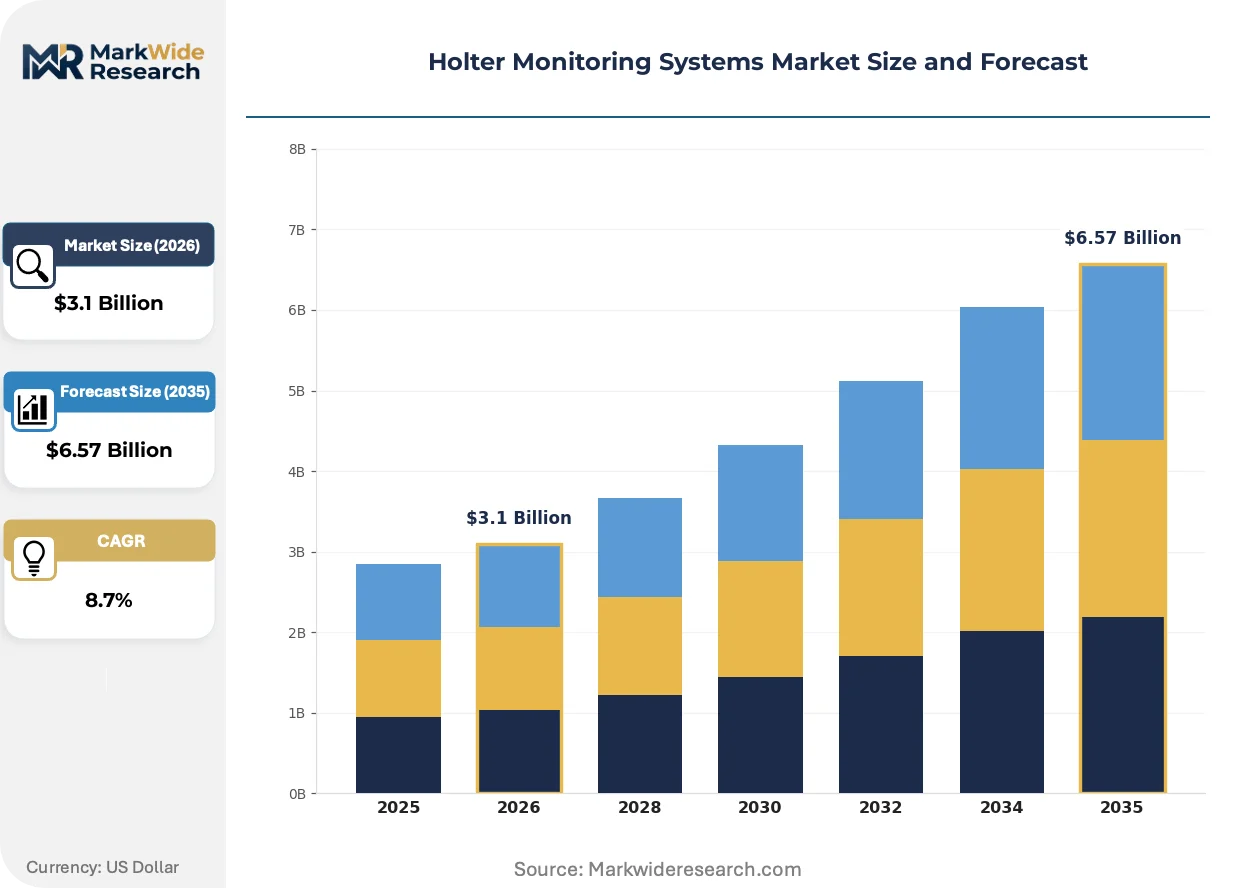
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lead Monitor, Multi-Lead Monitor, Wireless Monitor, Ambulatory Monitor Technology: Analog Technology, Digital Technology, Cloud-based Solutions, Software Solutions End User: Hospitals, Cardiology Clinics, Home Care, Research Institutions Application: Arrhythmia Detection, Heart Rate Monitoring, Post-Operative Monitoring, Preventive Cardiology |
| Companies Covered | Koninklijke Philips N.V., GE Healthcare, Hill-Rom Services, Inc. (Baxter), SCHILLER AG, Fukuda Denshi, OSI Systems, Inc., Nihon Kohden, Medtronic, Spacelabs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holter Monitoring Systems Market Strategic Shifts
Convergence between consumer-grade wearables and clinical-grade diagnostics is eroding the traditional boundary between wellness tracking and medical monitoring, forcing regulatory recalibration and new partnership models.
Multi-lead adhesive patch arrays with integrated accelerometers and temperature sensors are unifying motion artifact correction with physiological signal capture. Cardiology clinics in the United States are replacing conventional 5-lead Holter recorders with these systems for 14-day monitoring protocols. This unification of sensing modalities is compressing the distinction between diagnostic and monitoring-grade devices, enabling single-platform deployment across ambulatory and acute care settings.
The EU Medical Device Regulation's post-market surveillance requirements now mandate periodic safety update reports and proactive vigilance data submission for all Class IIa cardiac monitoring devices. Manufacturers must maintain notified body relationships across multiple European jurisdictions, increasing fixed compliance costs by 15-20 percent. Wireless Holter systems with algorithmic arrhythmia classification face heightened scrutiny under the EU AI Act's high-risk system framework, accelerating investment in clinical validation studies.
Cardiology group purchasing organizations are consolidating vendor selection around integrated hardware-software-service bundles, displacing standalone equipment procurement. Independent physician practices and mid-sized hospital networks now favor multi-year contracts that include device upgrades, cloud storage, and AI-assisted overread services. This bundling behavior is most pronounced in the United States, where IDN consolidation has concentrated buying power among 200-300 large health systems controlling regional referral patterns.
Holter Monitoring Systems Market Segmentation
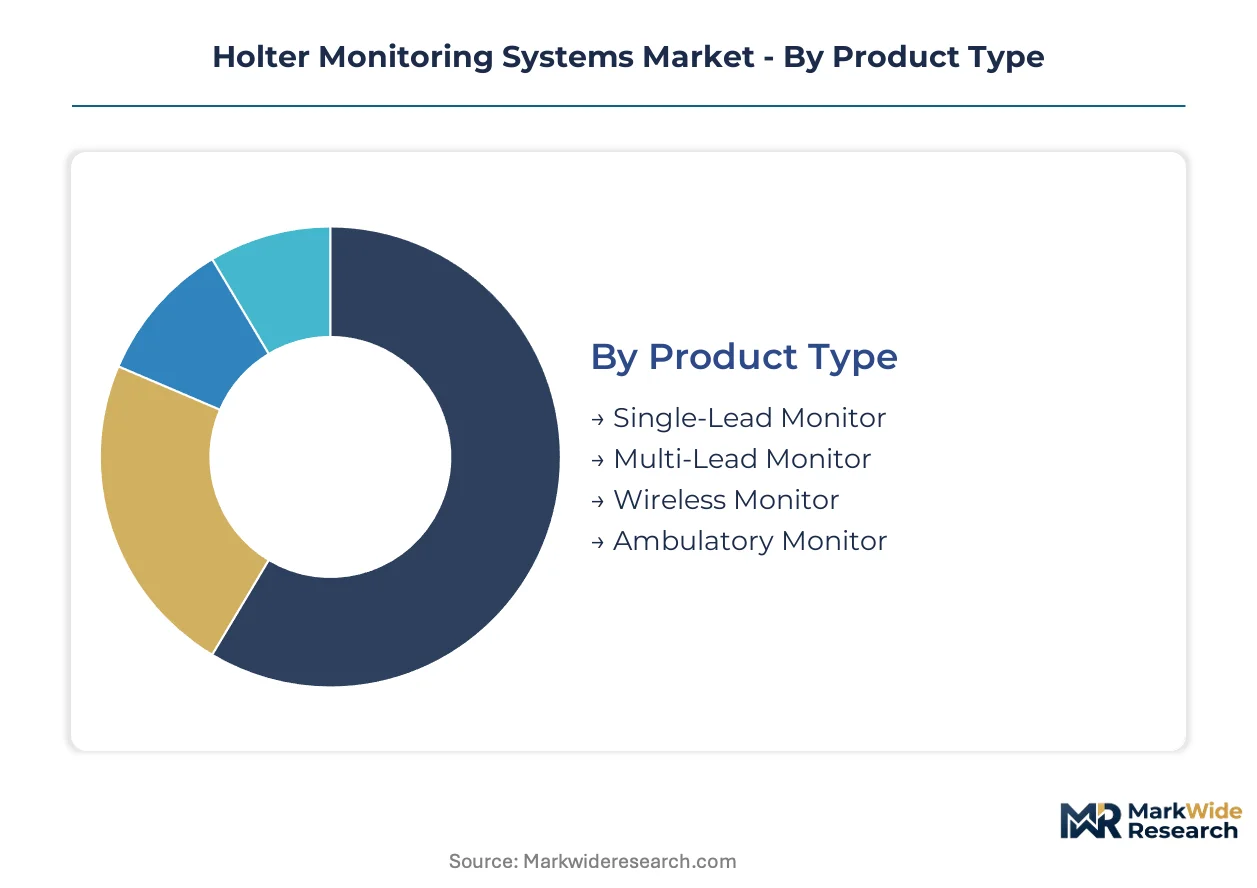
Holter monitoring systems fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and technology investment priorities. Each segmentation layer reveals distinct buyer priorities—from hardware specifications to software integration requirements—that shape vendor competitive strategy.
Product Type:
Buyers in this category differentiate by monitoring duration needs and patient mobility constraints rather than upfront hardware cost alone.
- Single-Lead Monitor:Compact adhesive patch electrodes capture single-channel ECG through integrated dry sensors, eliminating gel-based skin preparation. Home care agencies in the United States deploy these for 7-14 day ambulatory protocols where patient compliance limits traditional lead-wire systems. CMS reimbursement codes for extended external monitoring favor this form factor for outpatient cryptogenic stroke workups.
- Wireless Monitor:Bluetooth-enabled patch arrays transmit encrypted rhythm data to cloud platforms in real time, enabling automated arrhythmia alerts without patient-initiated transmission. Cardiology clinics across Germany and France are replacing Holter recorders with these systems to reduce in-clinic device returns and data download bottlenecks. Patient dropout rates fall substantially when lead-wire artifacts disappear.
- Multi-Lead Monitor:Five to twelve electrode configurations deliver diagnostic-grade spatial resolution for ischemia localization and complex arrhythmia mapping.
- Ambulatory Monitor:Belt-worn recorders with patient-activated event markers serve intermittent symptom correlation for infrequent palpitations.
Multi-lead monitors lead volumes today; wireless monitors are gaining share fastest.
Technology:
Technology selection hinges on data sovereignty requirements and existing hospital IT infrastructure rather than algorithmic performance metrics.
- Digital Technology:Solid-state flash storage and low-power microcontrollers enable 48-72 hour continuous recording at 256-1024 Hz sampling rates with minimal motion artifact. Japanese university hospitals and South Korean cardiac centers specify these systems for research-grade signal fidelity in electrophysiology studies. Signal-to-noise ratios exceed analog predecessors by orders of magnitude.
- Cloud-based Solutions:HIPAA-compliant data lakes and API-first architectures allow rhythm data streaming directly into Epic and Cerner electronic medical records without on-premise middleware. United States health systems with IDN consolidation mandates favor these platforms to standardize cardiac monitoring across 15-50 facility networks. Recurring subscription revenue now exceeds hardware margins for vendors with mature deployments.
- Analog Technology:Cassette-based tape recorders persist in resource-constrained settings with limited technical support infrastructure.
- Software Solutions:AI-enhanced overread platforms and automated preliminary reports reduce cardiologist interpretation burden.
Digital technology leads volumes today; cloud-based solutions are climbing the fastest.
End User:
End-user procurement authority concentrates in cardiology service line directors who control capital budgets and value-based care contract performance.
- Hospitals:Integrated delivery networks purchase enterprise-wide monitoring contracts spanning emergency department chest pain protocols, inpatient telemetry step-down, and post-discharge surveillance. Texas Medical Center and Cleveland Clinic anchor procurement volumes through standardized device fleets across 20+ affiliated facilities. Joint Commission accreditation requirements for continuous monitoring coverage drive replacement cycles.
- Cardiology Clinics:Independent electrophysiology practices and multi-specialty cardiology groups favor wireless patch systems with per-test pricing rather than capital ownership. The American College of Cardiology's quality metrics for atrial fibrillation detection incentivize extended monitoring adoption. Reimbursement rate compression since 2022 has shifted preferences toward operational expenditure models.
- Home Care:Post-acute nursing services and remote patient monitoring vendors deploy patient-friendly systems for 30-day protocols.
- Research Institutions:Academic medical centers specify open-data formats and raw signal export capabilities for algorithm development.
Hospitals lead volumes today; cardiology clinics are expanding most quickly.
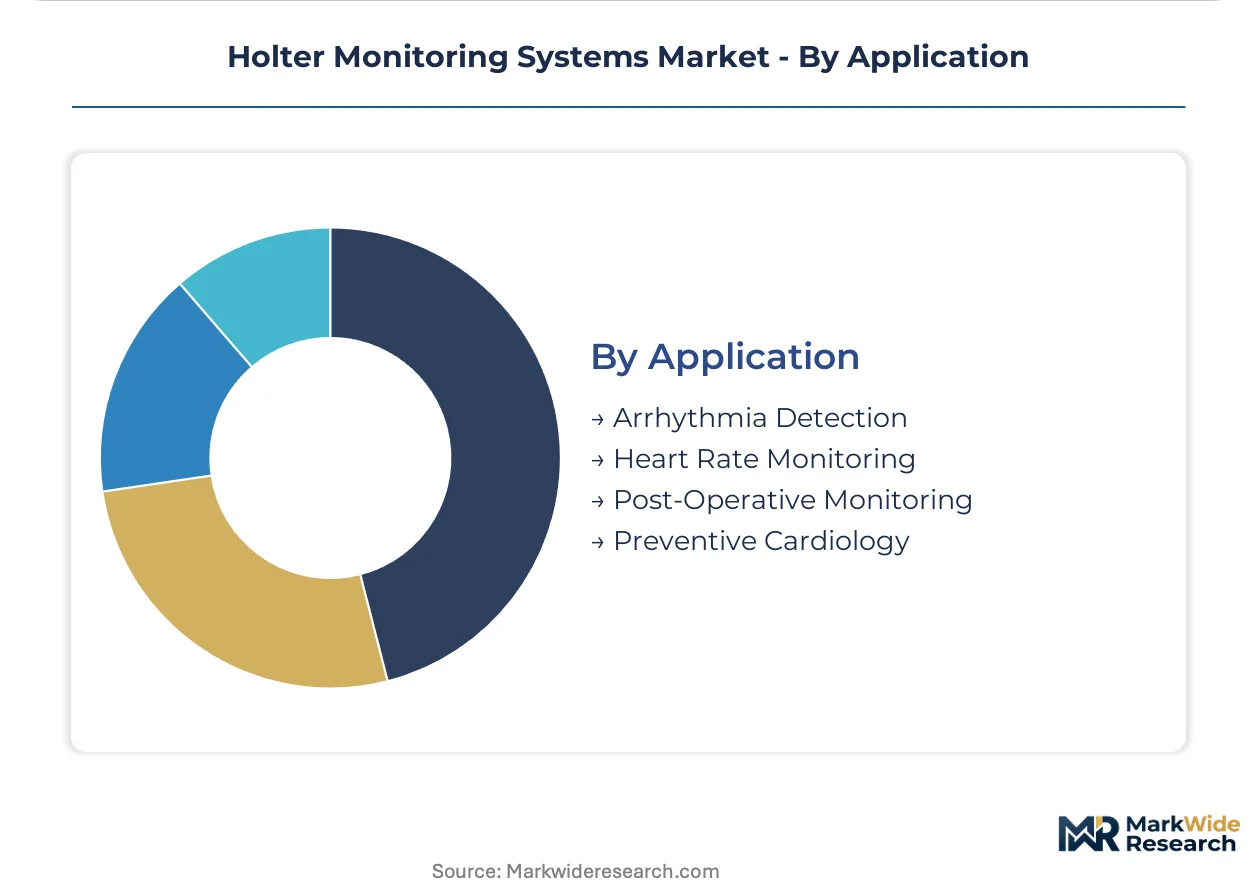
Application:
Application prioritization follows stroke prevention protocols and surgical quality improvement initiatives rather than general cardiovascular screening.
- Arrhythmia Detection:Atrial fibrillation screening and cryptogenic stroke monitoring dominate utilization, with patch-based systems replacing implantable loop recorders for initial diagnostic workups. Kaiser Permanente and UnitedHealthcare have established 30-day monitoring as standard of care for embolic stroke of undetermined source. Algorithmic detection of subclinical atrial fibrillation drives cloud platform subscriptions.
- Post-Operative Monitoring:Cardiac surgery programs and structural heart intervention suites mandate 7-14 day surveillance for atrial flutter and complete heart block following valve replacement or ablation procedures. Cleveland Clinic's post-surgical arrhythmia protocols have been adopted by 40+ US hospital systems. Wireless patches eliminate telemetry bed days and accelerate discharge.
- Heart Rate Monitoring:Exercise stress recovery and autonomic function assessment serve niche sports cardiology and tilt-table testing applications.
- Preventive Cardiology:Population screening for subclinical atrial fibrillation in patients over 65 remains experimental outside direct-to-employer contracts.
Arrhythmia detection leads volumes today; post-operative monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Medical Center anchors procurement volumes for Holter monitoring systems through standardized device fleets spanning 20-plus affiliated facilities across the southern United States.
United States
Kaiser Permanente and UnitedHealthcare established 30-day monitoring as standard care for embolic stroke of undetermined source. The FDA enforces 21 CFR Part 820 quality system regulations for device manufacturing. Cleveland Clinic's post-surgical arrhythmia protocols have been adopted by 40-plus hospital systems nationwide.
Germany
Cardiology clinics across Germany replace Holter recorders with wireless patch systems to reduce in-clinic device returns. The EU Medical Device Regulation requires notified body certification and post-market surveillance for market access. Berlin's Charité hospital network drives adoption of cloud-native analytics platforms across its 17 research institutes.
Japan
University hospitals and cardiac centers specify digital systems for research-grade signal fidelity in electrophysiology studies. METI promotes domestic production of medical device components through supply chain resilience programs. Tokyo's Keio University Hospital anchors demand for high-sampling-rate monitors in Asia-Pacific clinical trials.
France
Cardiology clinics deploy wireless monitors to eliminate lead-wire artifacts and improve patient compliance during extended protocols. ANSM oversees post-market vigilance for Class IIa cardiac monitoring devices. Paris's Assistance Publique-Hôpitaux de Paris network consolidates procurement around integrated hardware-software bundles.
United Kingdom
The National Health Service's long-term plan mandates expanded ambulatory cardiac monitoring for atrial fibrillation detection. MHRA implements the EU MDR framework through domestic legislation for Northern Ireland market access. London's Guy's and St Thomas' NHS Foundation Trust pilots AI-enhanced overread services for population screening programs.
Holter Monitoring Systems Market Competitive Environment
Global majors compete with regional champions across cloud analytics and wireless hardware dimensions. The vendor base clusters around three tiers: integrated healthcare conglomerates with captive semiconductor supply, specialized cardiac monitoring firms with algorithmic differentiation, and regional distributors controlling clinic channel access. Two strategic archetypes dominate: full-stack hardware-software-service bundlers and component specialists supplying white-label patch electrodes. M&A activity concentrates on cloud analytics platform acquisitions, while capacity expansion targets domestic semiconductor fabrication for Bluetooth SoCs.
Within the integrated healthcare conglomerate tier, Koninklijke Philips N.V. and GE Healthcare exemplify full-stack positioning through captive manufacturing and enterprise system integration. Hill-Rom Services, Inc. (Baxter) occupies a distinct channel-control archetype leveraging distribution networks across North American cardiology clinics. These three entities represent contrasting competitive vectors: semiconductor autonomy, cloud platform stickiness, and physical channel dominance.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE Healthcare |
| Hill-Rom Services, Inc. (Baxter) |
| SCHILLER AG |
| Fukuda Denshi |
| OSI Systems, Inc. |
| Nihon Kohden |
| Medtronic |
| Spacelabs Healthcare |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of digital signal processing chipsets anchors both supply security and pricing power for integrated healthcare conglomerates. Koninklijke Philips N.V. controls cost structures through in-house semiconductor production, while competitors absorbing spot-market Bluetooth SoC pricing face margin compression. This integration choice separates vendors who can absorb CMS reimbursement cuts from those forced into hardware commoditization.
Pricing Analysis
Component cost pass-through from 26-week lead times on discrete analog-to-digital converters is intensifying pricing pressure across mid-tier vendors. Three-tier pricing structure across premium, standard, and economy levels reflects FDA cybersecurity certification tiers and cloud analytics bundling depth. Cardiology clinics exhibit highest price sensitivity due to reimbursement rate compression, while integrated delivery networks prioritize total cost of ownership over per-unit hardware costs.
Supply Chain Analysis
Reverse-logistics flows for wireless patch electrodes create secondary refurbishment channels that extend device lifecycle economics. Taiwan and South Korea anchor Bluetooth SoC fabrication, while Japan and Germany supply precision analog components. Single-source vulnerability in low-power microcontroller supply chains threatens production schedules. Distribution runs through cardiology group purchasing organizations that consolidate vendor selection around bundled hardware-software-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where cloud-native analytics platforms and AI-enhanced diagnostic reporting command premium positioning. Demand is shifting toward integrated hardware-software bundles that reduce cardiologist interpretation burden and capture recurring revenue streams.
For Market Incumbents: Deepen backward integration into semiconductor supply chains to mitigate analog-to-digital converter lead time volatility. Prioritize FDA cybersecurity premarket guidance compliance as a competitive moat against emerging entrants lacking penetration testing infrastructure. Expand cloud storage and AI-assisted overread services to lock in multi-year contracts with integrated delivery networks. For New Entrants and Emerging Players: Begin with pediatric congenital heart programs where patch-based systems replace legacy telemetry in underpenetrated post-surgical arrhythmia surveillance. Target direct-to-employer contracting channels that bypass hospital procurement intermediaries for population cardiac screening services. Lead with per-test pricing models that convert capital-averse independent electrophysiology practices. For Investors and Strategic Acquirers: Roll-up economics work for cloud analytics platform specialists because electrophysiologist interpretation bottlenecks create automated triage workflow demand that scales across hospital networks. Five-to-ten year viability hinges on EU AI Act high-risk system compliance positioning. Watch for AI-enhanced arrhythmia detection false-positive rate improvements as inflection indicator for platform stickiness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket guidance compliance accelerates product launch timelines for connected Holter devices. |
| Hospital System Partnership | Epic and Cerner EMR integration contracts secure enterprise-wide monitoring standardization. |
| Software Companion Development | AI-enhanced overread platforms reduce cardiologist interpretation burden by half. |
| Reimbursement Strategy | CMS coverage expansion for extended external monitoring codes drives clinic procurement. |
| CE Marking Pathway | EU MDR notified body certification and post-market surveillance enable European market access. |
Study Parameters
Multiple input streams — cardiologist interviews, biomedical engineer surveys, hospital purchasing committee discussions, and group purchasing organization contract analysis — were reconciled against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records. Secondary validation drew from EU MDR notified body certification registries and GPO contract repositories. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored volume estimates.
Historical adoption curves for wireless patch electrodes were cross-referenced against panel input from cardiology service line directors across integrated delivery networks. Segmentation modeling spanned product type, technology architecture, end-user procurement authority, and application protocol. CAGRs were derived from trend extrapolation of ambulatory monitoring expansion under value-based care contracts and cryptogenic stroke protocol adoption. Forecast inputs incorporated semiconductor supply lead time assumptions and AI algorithm regulatory classification timelines.
Several conditions sit outside the modeled scope, including unforeseen FDA cybersecurity guidance revisions, EU AI Act enforcement intensity variations, and discrete analog-to-digital converter supply disruptions beyond current lead time projections. Forecasts reflect assumptions about CMS reimbursement stability and cardiology clinic consolidation rates. Periodic stress-testing of base assumptions is recommended given reimbursement rate compression trends and electrophysiologist workforce constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
South America Hemodynamic Monitoring Market